
 Neonatal Monitoring Equipment Market | 2026-2036
Neonatal Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Monitoring Equipment Market Outlook
Home care settings for post-discharge preterm infants is repositioning the channel mix away from pure hospital-centric sales. GE HealthCare leverages its Edison platform to integrate AI-assisted alarm management across NICU monitoring suites. Koninklijke Philips N.V. anchors its portfolio in wireless pulse oximetry and wearable temperature sensors designed for kangaroo mother care environments. Masimo competes through its rainbow SET platform, extending beyond SpO2 to total hemoglobin and respiration rate monitoring in neonatal populations.
Neonatal monitoring equipment encompasses physiologic surveillance systems engineered for infants under 28 days of age, typically operating with skin-friendly adhesive sensors, microsample blood analysis modules, and alarm thresholds calibrated to neonatal vital sign ranges below adult norms. Pulse oximeters occupy the largest revenue share due to universal screening mandates for critical congenital heart defects in birthing centers across multiple countries. Wireless monitoring and wearable devices represent the fastest-expanding technology cluster as NICUs prioritize family-centered care models that reduce cable tethering and support parent-infant bonding during extended hospitalization.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) establish divergent conformity pathways that manufacturers must navigate simultaneously to access the United States and European markets. India's CDSCO and BIS certification requirements for imported medical electronics create additional gatekeeping layers that favor localized assembly partnerships. Stakeholders must monitor how reimbursement coding for remote patient monitoring in home care settings reshapes capital allocation between bedside and ambulatory neonatal device platforms.
Market Dynamics
Wireless sensor miniaturization is collapsing the physical footprint of NICU monitoring suites while expanding the addressable market into transitional care and home settings.
Growth Catalysts
- Critical congenital heart defect screening mandates:Universal pulse oximetry protocols in birthing centers across the United States, United Kingdom, and Australia create baseline demand for multi-parameter monitors.
- Preterm birth rate elevation:Tertiary hospital NICU expansion in India, Brazil, and Nigeria drives procurement of cardiorespiratory monitoring systems with integrated apnea detection.
- AI-assisted alarm management:Machine learning algorithms reduce clinical alarm fatigue by filtering false-positive arrhythmia alerts, accelerating adoption in academic medical centers.
Market Restraints
- Biocompatible sensor material costs:Medical-grade hydrogel adhesives and skin-friendly conductive polymers face price volatility tied to petrochemical feedstock fluctuations.
- Single-source semiconductor dependency:Neonatal monitor ASICs and microcontrollers concentrate in Taiwan and South Korean foundry capacity, exposing supply chains to geopolitical disruption.
- EU MDR technical documentation burden:The 2017/745 regulation's expanded clinical evidence requirements for Class IIa devices extend clearance timelines and elevate regulatory consulting expenditures.
Strategic Opportunities
- Rural India special newborn care units:Government-funded SNCU networks in Uttar Pradesh, Bihar, and Madhya Pradesh remain underpenetrated for wireless temperature monitoring and portable pulse oximetry.
- Kangaroo mother care wearables:Continuous cardiorespiratory sensors designed for skin-to-skin contact address the WHO-recommended intervention gap in low-resource birthing facilities.
- Remote patient monitoring reimbursement:United States CMS billing codes for post-discharge neonatal surveillance create financial viability for home-based monitoring subscriptions.
Industry Challenges
- Pediatric biomedical engineering specialization:NICU device calibration requires expertise in neonatal physiology ranges that diverge substantially from adult norms, constraining field service team scalability.
- Legacy hospital IT integration:HL7 FHIR interoperability with entreained electronic health record systems from Epic and Cerner demands customized middleware development.
- ISO 80601-2-56 testing bottlenecks:Pulse oximeter accuracy validation against CO-oximetry reference methods creates extended premarket verification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Monitoring Equipment Market |
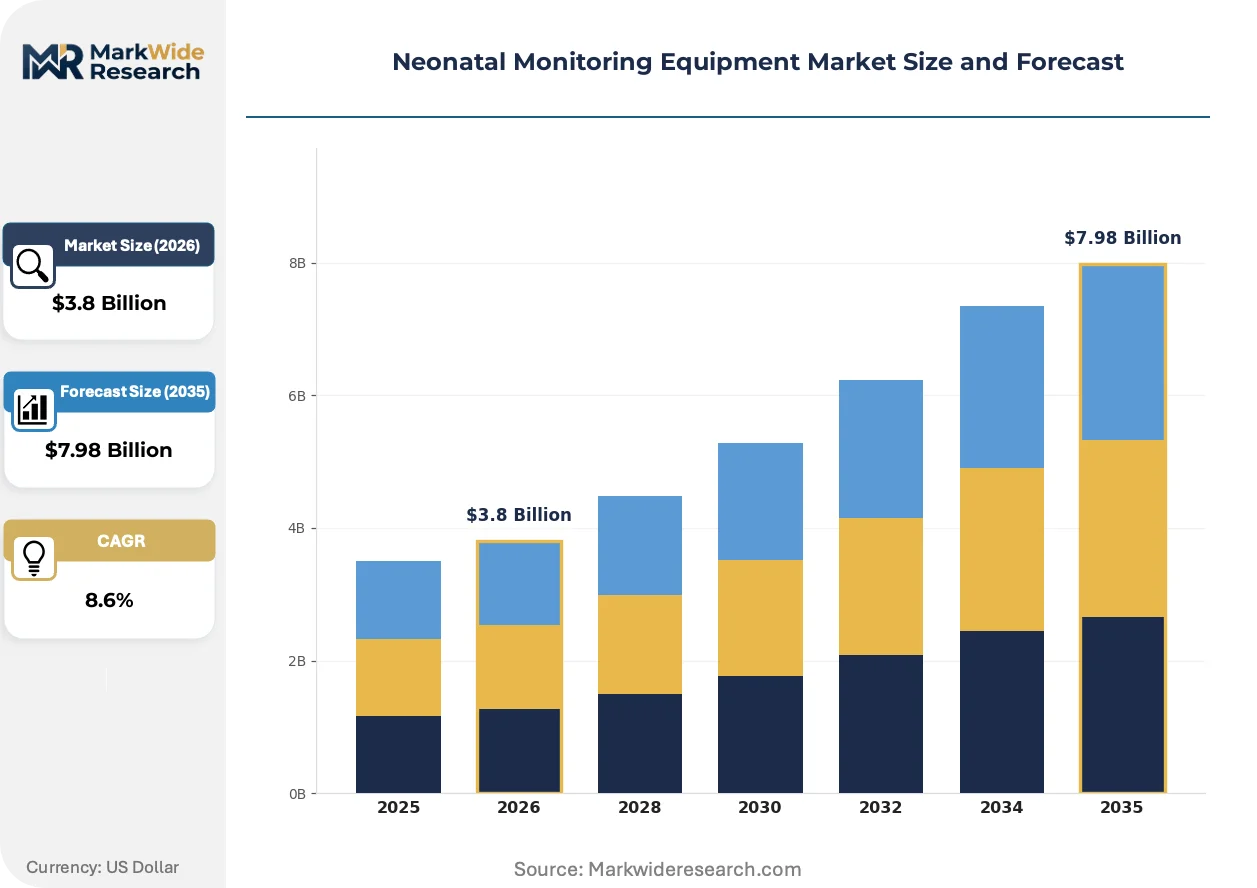
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Oximeters, ECG Monitors, Temperature Monitors, Neurological Monitors Technology: Wireless Monitoring, Wearable Devices, Telemedicine Solutions, Portable Equipment End User: Hospitals, Clinics, Home Care Settings, Research Institutions Application: Critical Care, Routine Monitoring, Postpartum Care, Data Analysis |
| Companies Covered | GE HealthCare, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Medtronic, Masimo, Siemens Healthineers, Nihon Kohden Corporation, Natus Medical Incorporated, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Monitoring Equipment Market Strategic Shifts
Neonatal monitoring is pivoting from bedside tethering toward continuous ambulatory surveillance, enabled by advances in low-power wireless transmission and flexible electronics.
Multi-wavelength pulse oximetry is integrating total hemoglobin and respiration rate measurement into single adhesive sensors, eliminating the need for blood draws in fragile neonates. Level IV NICUs in the United States and tertiary centers in Germany are adopting these expanded-parameter devices to reduce iatrogenic anemia from frequent laboratory sampling. The technology is integrating previously discrete diagnostic functions into unified surveillance platforms, compressing capital equipment requirements per patient bed.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic collection of real-world performance data across distributed device fleets. Manufacturers must now maintain electronic systems for capturing vigilance reports and periodic safety update reports, elevating data infrastructure investments. Pediatric device specialists targeting European markets are responding by embedding cellular connectivity as standard to enable remote performance monitoring and automated adverse event flagging.
Family-centered care protocols are displacing traditional cable-dependent monitoring configurations in favor of wearable, parent-portable devices. NICU departments in Scandinavia and the Netherlands are piloting continuous monitoring during kangaroo care and rooming-in transitions, with sensor data streaming to centralized nursing stations. This behavioral shift is most visible in academic medical centers pursuing Baby-Friendly Hospital Initiative certification, where parental bonding metrics now influence technology procurement decisions alongside clinical accuracy specifications.
Neonatal Monitoring Equipment Market Segmentation
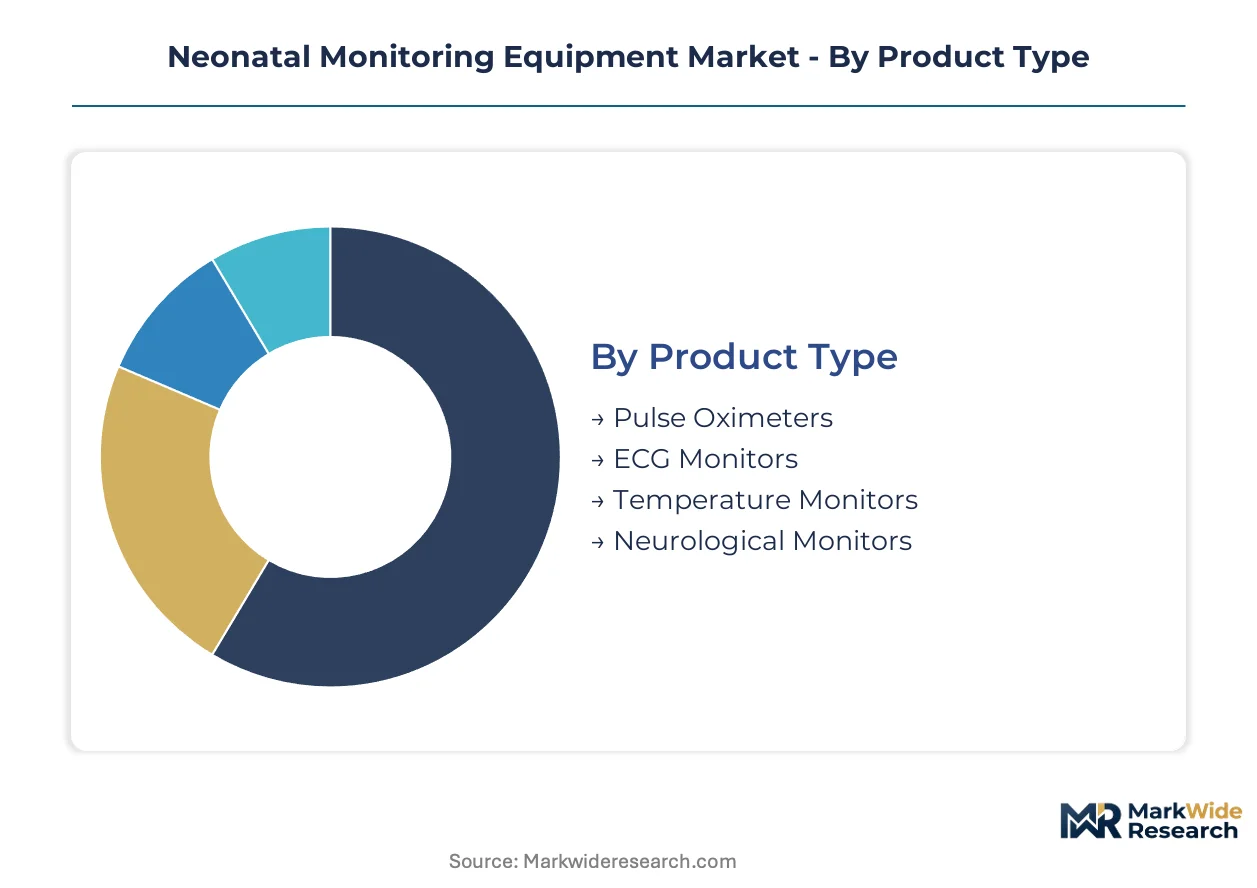
Neonatal monitoring equipment segments diverge sharply in regulatory burden, with wireless and wearable technologies triggering novel FDA 510(k) pathways while conventional bedside systems follow established Class II frameworks. Understanding these certification boundaries shapes portfolio investment and geographic prioritization for manufacturers.
Product Type:
FDA 510(k) clearance timelines stretch longest for neurological monitors requiring specialized pediatric indications, while pulse oximeters benefit from predicate device abundance. ECG monitors and temperature monitors occupy intermediate regulatory complexity tiers.
- Pulse Oximeters:Multi-wavelength adhesive sensors measuring SpO2, perfusion index, and pleth variability through photoplethysmography. Demand concentrates in United States birthing centers subject to universal critical congenital heart defect screening mandates, with procurement accelerating as state Medicaid programs expand coverage for pulse oximetry-based protocols.
- ECG Monitors:Three-lead and five-lead configurations with neonatal-specific electrode placements and R-wave detection algorithms calibrated for heart rates between 60-220 bpm. Tertiary hospital NICUs in Germany and the United Kingdom drive replacement cycles as integrated apnea-bradycardia detection becomes standard-of-care.
- Temperature Monitors:Continuous skin-surface thermometry using skin-friendly adhesive patches.
- Neurological Monitors:Amplitude-integrated EEG systems for seizure detection in hypoxic-ischemic encephalopathy cases.
Leading the category by volume: Pulse Oximeters. Growing fastest: Neurological Monitors.
Technology:
Cost tier stratification separates premium wireless ecosystems from economy portable units, with telemedicine solutions commanding subscription-based pricing distinct from capital equipment models.
- Wireless Monitoring:Low-power Bluetooth and proprietary radio protocols enabling cable-free NICU environments with centralized nursing station dashboards. Scandinavian academic medical centers pilot continuous data streaming during kangaroo mother care, with Sweden's Karolinska Institute and Denmark's Rigshospitalet establishing clinical evidence for family-centered wireless protocols.
- Wearable Devices:Flexible electronics and skin-conformal sensor arrays designed for parent-portable monitoring during skin-to-skin contact. India's government-funded special newborn care units in Gujarat and Tamil Nadu represent emerging procurement channels as medical device parks enable localized assembly cost reduction.
- Telemedicine Solutions:Cloud-based surveillance platforms with remote clinician access.
- Portable Equipment:Battery-powered multi-parameter monitors for transport and rural deployment.
Wireless Monitoring captures the largest revenue share. Wearable Devices are climbing the fastest as family-centered care protocols expand.
End User:
Application maturity varies across customer types, with hospitals demanding full-parameter integration while home care settings prioritize simplified, parent-operable interfaces.
- Hospitals:Level III and Level IV NICUs requiring FDA-cleared devices with enterprise EHR integration through HL7 FHIR protocols. United States academic medical centers in Boston, Philadelphia, and San Francisco anchor demand for AI-assisted alarm management systems.
- Home Care Settings:Post-discharge monitoring for apnea of prematurity and bradycardia surveillance. United States CMS reimbursement codes for remote patient monitoring create financial viability for subscription-based service models targeting preterm infant cohorts.
- Clinics:Intermediate care nurseries and special care baby units.
- Research Institutions:Clinical trial infrastructure for neonatal device development.
Hospitals dominate procurement volume. Home Care Settings show steepest expansion trajectory as reimbursement frameworks mature.
Application:
Geographic deployment patterns concentrate critical care installations in tertiary urban centers while routine monitoring penetrates secondary hospitals and birthing facilities.
- Critical Care:Multi-parameter surveillance for ventilated preterm infants with integrated capnography and invasive blood pressure monitoring. Brazil's expanding NICU infrastructure in São Paulo and Rio de Janeiro drives demand for high-acuity monitoring suites.
- Data Analysis:Machine learning platforms processing longitudinal vital sign trends for predictive deterioration alerts. Academic medical centers in the Netherlands and Belgium pilot algorithmic early warning systems for neonatal sepsis detection.
- Routine Monitoring:Standard physiologic surveillance for stable neonates.
- Postpartum Care:Transitional monitoring during mother-infant rooming-in.
Critical Care leads by installed base. Data Analysis is gaining share fastest as AI validation studies complete.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of neonatal monitoring equipment concentrates in Germany, the United States, and Japan, while demand expansion accelerates fastest across India's government-funded healthcare networks and Brazil's tertiary hospital infrastructure.
United States
FDA's 510(k) premarket notification pathway for Class II medical devices shapes product clearance timelines and design priorities for manufacturers targeting domestic birthing centers. Critical congenital heart defect screening mandates in all 50 states create baseline demand for multi-parameter pulse oximeters. Boston, Philadelphia, and San Francisco anchor demand for AI-assisted alarm management systems in Level IV NICUs.
Germany
Tertiary hospital NICU expansion drives procurement of cardiorespiratory monitoring systems with integrated apnea detection algorithms calibrated for neonatal physiology. EU Medical Device Regulation technical documentation requirements extend clearance timelines for wireless monitoring platforms. Academic medical centers in Berlin and Munich pilot continuous data streaming during kangaroo mother care protocols.
India
Government-funded special newborn care units in Uttar Pradesh, Bihar, and Madhya Pradesh accelerate procurement of pulse oximetry and portable temperature monitors. CDSCO and BIS certification requirements for imported medical electronics favor localized assembly partnerships in Gujarat and Tamil Nadu medical device parks. Procurement concentrates in SNCU networks where wireless temperature monitoring remains underpenetrated.
Brazil
Expanding NICU infrastructure in São Paulo and Rio de Janeiro drives demand for high-acuity monitoring suites with invasive blood pressure and capnography integration. ANVISA regulatory pathways for imported medical devices create gatekeeping layers that favor established multinational suppliers. Tertiary centers prioritize multi-parameter devices capable of supporting ventilated preterm infant populations.
Japan
PMDA's structured review process for pediatric medical devices emphasizes clinical evidence generation for neonatal-specific indications. METI industrial policy supports domestic manufacturing of precision sensor components for pulse oximetry modules. Tokyo and Osaka metropolitan hospital networks anchor replacement cycles for integrated neurological monitoring systems.
Neonatal Monitoring Equipment Market Competitive Environment
Top-tier vendors anchor the premium wireless monitoring segment, while mid-tier specialists compete on portable equipment and regional service density. The vendor base separates into three distinct tiers: diversified health technology conglomerates with full NICU suite portfolios, specialized neonatal device manufacturers with focused regulatory expertise, and emerging wearable sensor developers targeting home care transitions. Competitive positioning sharpens through strategic partnerships for AI algorithm licensing and backward integration into biocompatible adhesive materials.
Among diversified health technology conglomerates, GE HealthCare, Koninklijke Philips N.V., and Masimo occupy positions representing distinct strategic archetypes. GE HealthCare exemplifies the platform-integrated tier leveraging enterprise IT infrastructure for NICU deployment. Koninklijke Philips N.V. anchors the wireless-first vector with sensor portfolios designed for family-centered care environments. Masimo represents the parameter-expansion specialist tier, extending beyond core pulse oximetry into multi-wavelength physiological surveillance. Drägerwerk AG & Co. KGaA and Siemens Healthineers sit within the European-centered fabrication cluster with established regulatory pathways across EMA member states.
| Leading Market Players |
|---|
| GE HealthCare |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Medtronic |
| Masimo |
| Siemens Healthineers |
| Nihon Kohden Corporation |
| Natus Medical Incorporated |
| BD |
| Others |
Value Chain & Pricing Dynamics
Level IV NICU procurement committees in United States academic medical centers anchor demand for premium wireless monitoring suites, locking in subscription-based pricing models that bundle hardware, software, and predictive analytics services. This buyer concentration shifts pricing power toward vendors with validated AI-assisted alarm management and seamless HL7 FHIR integration.
Pricing Analysis
Margin tightening in portable equipment tiers reflects aggressive government tender competition across India's special newborn care unit networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wireless ecosystems with AI integration from CE-marked portable monitors and unbranded economy pulse oximeters for rural clinics. Price differentiation hinges on ISO 80601-2-56 certification status and after-sales field service density. Cost-down pressure on economy segments accelerates because medical device parks in Gujarat and Tamil Nadu enable localized assembly cost reduction. Government procurement bodies in Uttar Pradesh and Bihar exhibit highest price sensitivity; United States Level IV NICUs show lowest sensitivity due to outcome-based reimbursement alignment.
Supply Chain Analysis
ISO 13485 certification and FDA establishment registration requirements gate supplier qualification for neonatal monitor ASICs and medical-grade sensor substrates. Manufacturing concentrates in Taiwan, South Korea, and Germany for semiconductor foundry capacity and precision sensor fabrication. Raw material dependencies include medical-grade hydrogel adhesives, photoplethysmography LED arrays, and biocompatible conductive polymers. Single-source vulnerability in Taiwan-based microcontroller supply exposes procurement timelines to geopolitical disruption. Distribution runs through authorized medical device distributors with GPO contracts for hospital system penetration and direct government tender channels for India's SNCU networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into biocompatible adhesive materials and captive sensor fabrication, as supply security and cost control separate viable competitors from margin-squeezed assemblers.
For Market Incumbents: Hedge against wearable sensor commoditization by locking exclusive supply agreements for medical-grade hydrogel substrates and expanding captive foundry partnerships in Germany and Japan. Defend installed base through embedded AI algorithm licensing that raises switching costs for Level IV NICU customers. Accelerate certification investment for EU MDR Class IIa technical documentation to extend clearance moats against emerging Asian competitors.
For New Entrants and Emerging Players: Flexible electronics for kangaroo mother care wearables offers the most penetrable white-space entry, with India's government-funded SNCU networks and Brazil's expanding tertiary infrastructure showing lowest incumbent saturation. Target rural India special newborn care units in Madhya Pradesh and Bihar with portable temperature monitoring bundles priced for government tender ceilings. Pursue CDSCO manufacturing license partnerships with Tamil Nadu medical device parks to bypass import duty disadvantages.
For Investors and Strategic Acquirers: The window for entry favors specialized neonatal wearable developers with validated clinical evidence in family-centered care protocols. Long-term viability centers on algorithmic differentiation and reimbursement code capture rather than hardware margin extraction. Watch for CMS remote patient monitoring billing code expansion as the inflection signal validating home-based monitoring subscription economics.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investment opens 27-country market access for wireless monitoring platforms. |
| Hospital System Partnership | GPO contracts with United States academic medical centers lock in multi-year AI-assisted alarm management deployments. |
| Software Companion Development | FDA-cleared predictive analytics modules differentiate premium wireless ecosystems from commodity pulse oximetry. |
| Reimbursement Strategy | CMS remote patient monitoring code capture enables subscription pricing for post-discharge neonatal surveillance services. |
| Backward Integration | In-house production of biocompatible hydrogel adhesives insulates margins from petrochemical feedstock volatility. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this neonatal monitoring equipment analysis. Primary interviews with biomedical engineers, NICU clinical directors, hospital purchasing committee members, and GPO contracts managers combined with secondary validation from FDA 510(k) databases, CDSCO import records, and EU MDR notified body documentation. Bottom-up modeling of device shipments by product type and technology tier triangulated against top-down healthcare expenditure allocation across the analysis window.
Segment-level granularity modeled pulse oximeters, ECG monitors, temperature monitors, and neurological monitors with technology splits across wireless monitoring, wearable devices, telemedicine solutions, and portable equipment. End-use dimensions captured hospitals, home care settings, clinics, and research institutions with geographic clustering by regulatory framework. CAGRs derived from fitted growth curves calibrated to preterm birth rate trajectories, government healthcare infrastructure investment announcements, and reimbursement code expansion timelines. Forecast inputs incorporated AI algorithm validation study completion rates and medical device park capacity buildouts in India.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or Taiwan semiconductor supply disruptions. Forecasts reflect assumptions regarding sustained government SNCU funding in India, stable FDA 510(k) review timelines, and continued CMS reimbursement support for remote patient monitoring. A model refresh is warranted upon material change in FDA premarket notification pathway requirements or India PLI scheme medical device eligibility expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Umbilical Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Perinatal Software Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market