
 Aluminum Parts Gravity Die Casting Market | 2026-2036
Aluminum Parts Gravity Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Parts Gravity Die Casting Market Outlook
Digital twin integration across gravity die casting workflows is reconfiguring how manufacturers optimize thermal management and defect prediction before physical tooling begins. Endurance Technologies leverages captive foundry networks across India's western industrial corridor to sustain cost-competitive output for two-wheeler powertrain castings. Nemak dominates North American supply of structural aluminum nodes through integrated high-pressure and gravity die casting capacity. Georg Fischer Ltd differentiates via precision sand-casting-to-gravity-die process migration for hydraulic valve bodies.
Aluminum parts gravity die casting produces complex, dimensionally stable components by pouring molten aluminum alloy into permanent steel molds under gravity-fed conditions, typically achieving wall thicknesses of 3–12 mm and tolerances of ±0.5 mm for automotive-grade applications. Engine blocks and transmission housings command the largest share of current output value, with brackets gaining fastest traction as vehicle architectures shift to multi-material body-in-white construction. Mass production stage gravity die casting anchors margin pools through multi-cavity tooling amortization across million-unit automotive programs, while prototyping remains fragmented among job shops lacking scale economies.
EPA fuel economy standards and NHTSA safety regulations in the United States mandate aluminum-intensive vehicle architectures that directly expand gravity die casting procurement for crash-management components. REACH substance restrictions and the EU Green Deal's carbon border adjustments are forcing European foundries to document alloy sourcing and energy intensity across production chains. Stakeholders must monitor how evolving lifecycle assessment requirements reshape supplier qualification criteria and capital allocation toward low-carbon smelter partnerships.
Market Dynamics
Automotive OEM lightweighting mandates are compressing design-to-production cycles for aluminum chassis components, forcing foundries to compress tooling validation timelines while maintaining dimensional tolerances. This structural pressure is reconfiguring capital allocation toward thermal simulation capabilities and multi-cavity die investments.
Growth Catalysts
- EPA fuel economy standards:NHTSA safety regulations in the United States mandate aluminum-intensive vehicle architectures that expand gravity die casting procurement for crash-management components and structural nodes.
- Two-wheeler powertrain demand:India's western industrial corridor sustains high-volume production of cost-competitive engine castings through captive foundry networks serving domestic OEM assembly plants.
- Digital twin integration:Thermal management virtualization is compressing defect prediction cycles before physical tooling begins, reducing scrap rates in high-pressure automotive programs.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelter operations expose foundries to input cost swings that erode margin pools on fixed-price automotive contracts.
- Permanent mold supply concentration:Specialized steel die fabrication capacity clusters in Germany's Baden-Württemberg region, creating bottleneck risks for tooling procurement.
- High-pressure die casting substitution:Structural aluminum nodes increasingly migrate toward HPDC processes that achieve thinner wall sections for battery enclosure applications.
Strategic Opportunities
- EU Green Deal carbon border adjustments:European foundries documenting low-carbon alloy sourcing and energy intensity gain preferential qualification status with premium OEM sourcing teams.
- Hydraulic valve body precision migration:Sand-casting-to-gravity-die process conversion creates margin expansion for fluid power component manufacturers serving construction equipment OEMs.
- China material traceability enforcement:NMPA and MIIT tightening rules for cast aluminum structural parts creates compliance service opportunities for third-party certification providers.
Industry Challenges
- Thermal simulation expertise scarcity:Foundries struggle to recruit engineers capable of operating coupled fluid-thermal-solidification modeling software for multi-cavity die optimization.
- REACH substance documentation timelines:European suppliers face extended certification cycles for alloy chemistry declarations under evolving lifecycle assessment frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Parts Gravity Die Casting Market |
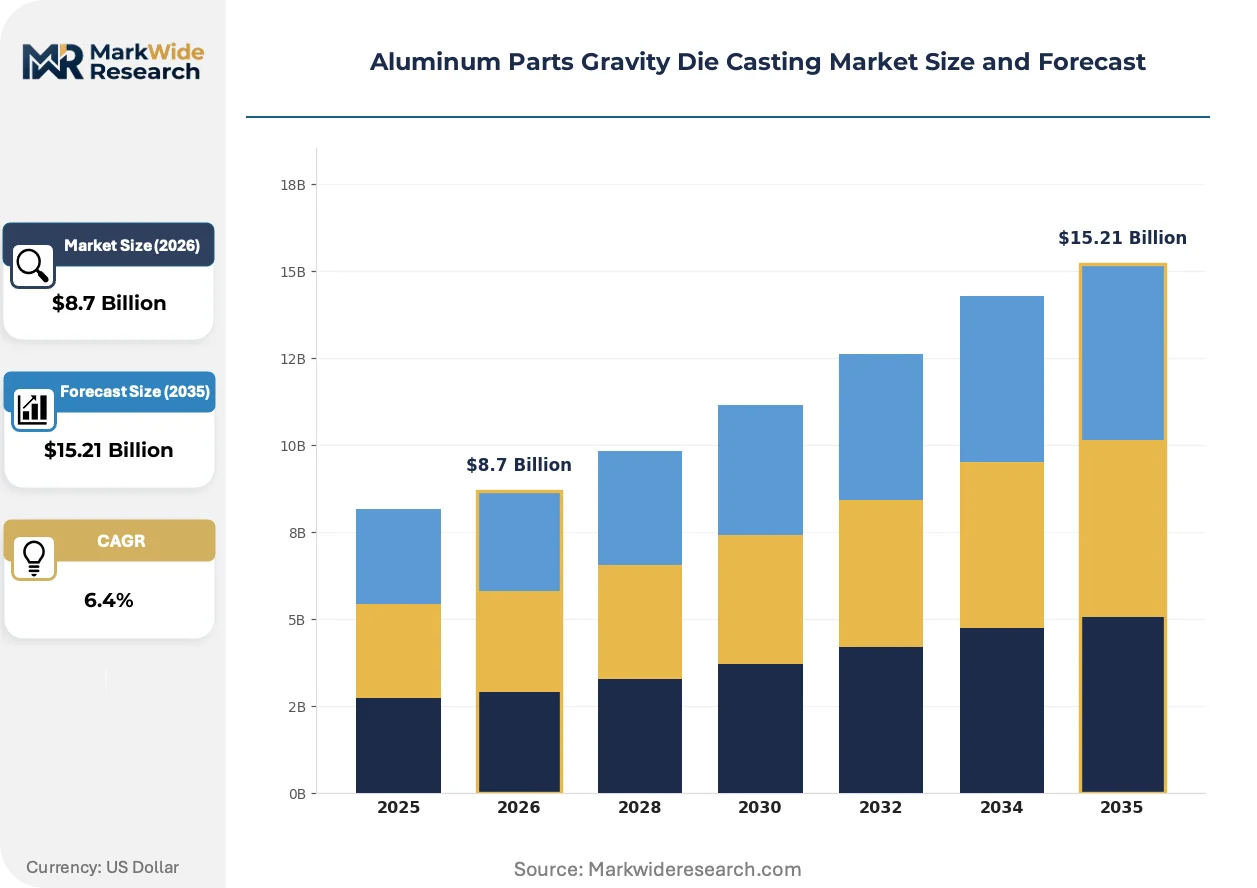
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Blocks, Transmission Housings, Brackets, Wheels End User: Automotive, Aerospace, Electronics, Industrial Machinery Manufacturing Stage: Design, Prototyping, Mass Production, Finishing Application: Automotive Parts, Decorative Items, Mechanical Components, Others |
| Companies Covered | Endurance Technologies, Minda Corporation Limited, Sundaram Clayton Limited, Rockman Industries, CIE Automotive, Nemak, Gibbs Die Casting Corp., Georg Fischer Ltd, Dynacast International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Parts Gravity Die Casting Market Strategic Shifts
Process virtualization and regulatory carbon accounting are simultaneously compressing physical prototyping cycles and expanding documentation burdens across aluminum gravity die casting supply chains. These forces are reshaping competitive differentiation toward digital capability depth rather than scale alone.
Digital twin platforms for gravity die casting are virtualizing thermal management optimization and solidification defect prediction before steel dies are machined. Tier-one automotive suppliers are deploying these tools across million-unit programs to compress tooling validation from months to weeks. This virtualization is displacing traditional trial-and-error methods that required multiple physical die iterations.
REACH substance restrictions and the EU Green Deal's carbon border adjustment mechanism are forcing European foundries to document alloy sourcing and energy intensity across production chains. Compliance teams must now trace primary aluminum from smelter to finished component with verified carbon footprints. German automotive clusters are responding fastest, with tier-one suppliers mandating supplier-specific lifecycle assessments for qualification.
Buyer concentration among automotive OEMs is compressing sourcing decision cycles and unbundling after-sales service from component supply contracts. Tier-one suppliers now compete on standalone tooling amortization terms rather than integrated lifecycle service packages. This pattern is most visible in Germany and the United States, where procurement teams are consolidating foundry panels to three preferred suppliers per component category.
Aluminum Parts Gravity Die Casting Market Segmentation
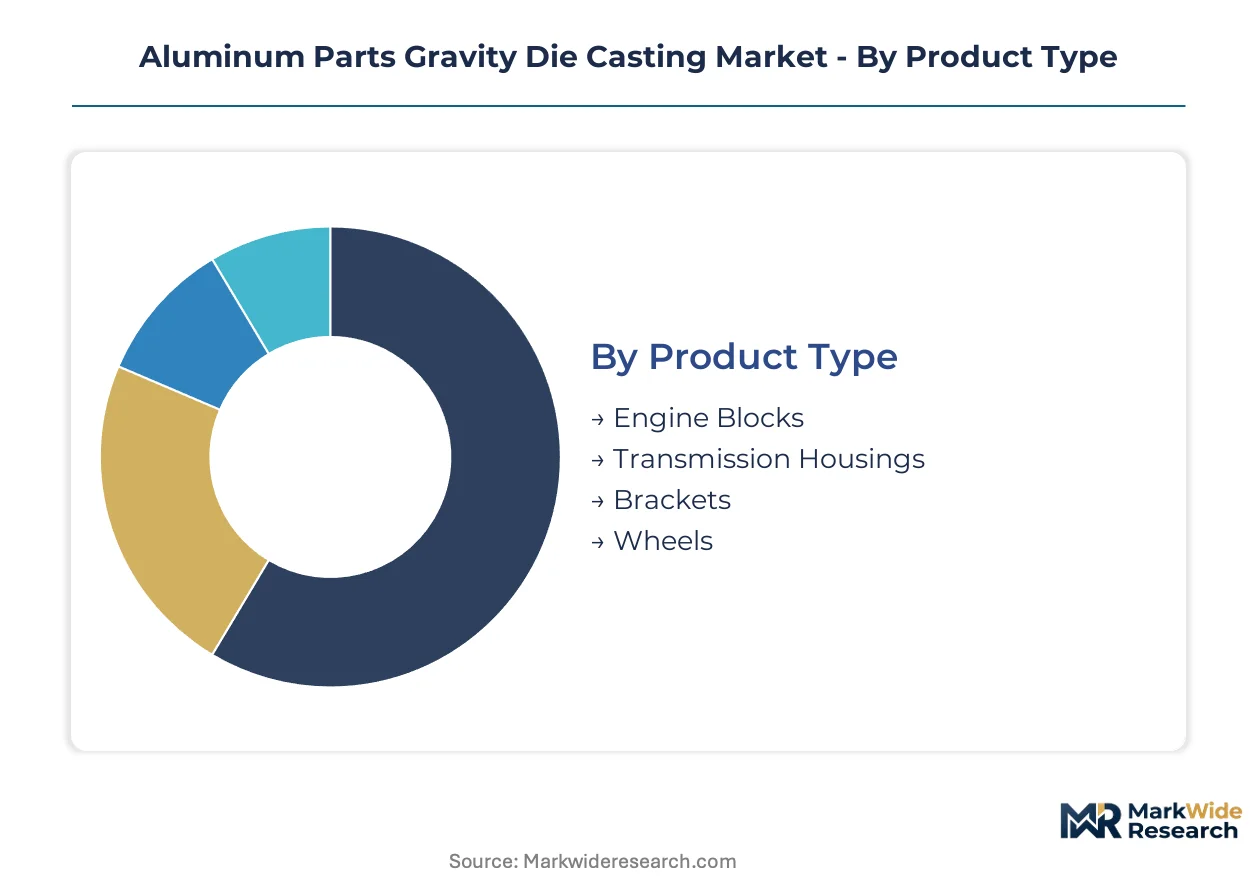
Gravity die casting serves heterogeneous demand profiles across automotive powertrains, precision aerospace structures, and industrial fluid power systems. Segment boundaries blur where multi-material vehicle architectures require cast aluminum nodes with divergent mechanical specifications and certification burdens.
Product Type:
Mature segments anchor revenue pools through million-unit automotive programs, while emerging categories capture value from electrification-driven chassis redesigns.
- Engine Blocks:High-pressure-tolerant aluminum-silicon alloys with integrated cooling galleries dominate internal combustion powertrain procurement. German automotive OEMs in Baden-Württemberg sustain dense supplier networks for these castings under tightening EU carbon border documentation requirements.
- Transmission Housings:Complex internal geometries with bearing pockets and seal surfaces demand multi-cavity die investments amortized across high-volume programs. India's western industrial corridor hosts captive foundry networks serving two-wheeler OEM assembly plants with cost-competitive output.
- Brackets:Multi-material body-in-white construction is accelerating procurement of these structural nodes.
- Wheels:Aesthetic and load-bearing specifications converge in premium automotive applications.
Engine blocks retain volume leadership; brackets hold the steepest expansion curve.
End User:
Customer concentration varies sharply, with automotive procurement consolidating around tier-one supplier panels while aerospace maintains fragmented qualification pathways.
- Automotive:EPA fuel economy standards and NHTSA safety regulations mandate aluminum-intensive architectures that expand gravity die casting procurement for crash-management components. OEM lightweighting targets compress design-to-production cycles, forcing foundries toward thermal simulation capabilities.
- Aerospace:AS9100 certification and material traceability requirements extend qualification timelines for structural castings. European foundries documenting low-carbon alloy sourcing gain preferential status with airframe OEM sourcing teams under evolving lifecycle assessment frameworks.
- Electronics:Thermal management housings for power electronics drive precision tolerances.
- Industrial Machinery:Hydraulic valve bodies and fluid power components sustain mid-volume demand.
Automotive commands absolute revenue share; aerospace climbs fastest on qualification backlogs.
Manufacturing Stage:
Capital intensity and margin structure diverge across the value chain, with mass production anchoring returns and prototyping capturing premium pricing for speed.
- Design:Digital twin platforms now virtualize thermal management optimization before steel dies are machined. Tier-one suppliers deploy these tools to compress tooling validation from months to weeks, displacing traditional trial-and-error methods.
- Prototyping:Job shops lacking scale economies dominate this fragmented segment, serving program development cycles with limited multi-cavity tooling investment.
- Mass Production:Multi-cavity die amortization across million-unit programs anchors margin pools for automotive-grade castings.
- Finishing:CNC machining and surface treatment operations capture value-add downstream of casting solidification.
Mass production dominates value capture; design services expand most quickly on virtualization demand.
Application:
Functional performance requirements separate regulated automotive safety components from decorative and general mechanical applications with lower certification burdens.
- Automotive Parts:Structural nodes and crash-management components must satisfy NHTSA safety regulations and EPA fuel economy standards in the United States, plus REACH substance restrictions in Europe. China's NMPA and MIIT are tightening material traceability rules for these castings.
- Mechanical Components:Precision hydraulic valve bodies serve construction equipment OEMs through sand-casting-to-gravity-die process migration.
- Decorative Items:Architectural and consumer product applications emphasize surface finish over mechanical loading specifications.
- Others:Niche industrial applications span medical equipment bases to semiconductor processing hardware.
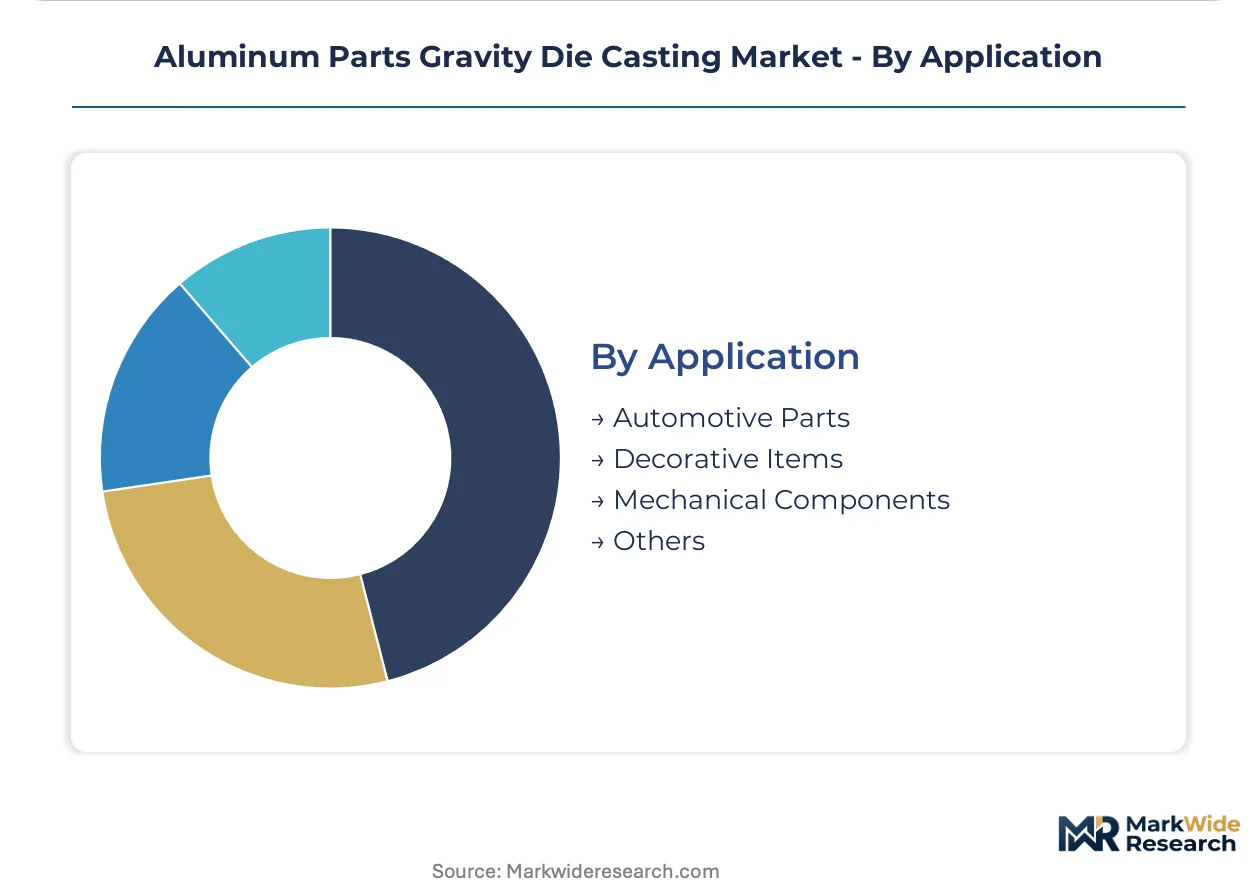
Automotive parts retain procurement volume leadership; mechanical components gain share fastest on fluid power demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in aluminum castings are reshaping regional production footprints, with deficit markets accelerating local capacity investments while surplus regions consolidate around captive automotive supply chains.
China
Domestic EV manufacturers are scaling aluminum-intensive chassis platforms at unprecedented rates. NMPA and MIIT traceability mandates now require documented alloy provenance for structural castings entering vehicle certification pathways. Yangtze River Delta foundries are absorbing German tooling expertise through joint ventures to meet precision tolerances for export-bound components.
Germany
Baden-Württemberg's automotive cluster sustains dense supplier networks for engine block and transmission housing production. EU Green Deal carbon border adjustments force foundries to verify smelter energy intensity across upstream supply chains. Stuttgart-area tier-one suppliers are consolidating foundry panels to three preferred vendors per component category.
United States
EPA fuel economy standards and NHTSA crash safety regulations mandate aluminum-intensive architectures for light trucks and SUVs. Southeast automotive corridors attract gravity die casting investments to serve transplant OEM assembly plants. Mexican border states provide tariff-advantaged finishing capacity for US-bound castings.
India
Two-wheeler OEMs sustain high-volume demand for cost-competitive powertrain castings through captive foundry networks. BIS quality certification requirements are tightening for aluminum alloy specifications in automotive applications. Maharashtra and Gujarat industrial corridors host dense concentrations of job shops serving domestic assembly plants.
Aluminum Parts Gravity Die Casting Market Competitive Environment
On the supply side, the industry is bifurcated between scale-driven automotive tier-ones and fragmented regional job shops lacking multi-cavity tooling capabilities. Consolidation pressure concentrates among mid-cap specialists serving single OEM programs. Three archetypes dominate: integrated automotive suppliers with captive foundry networks, precision-focused hydraulic component specialists, and cost-optimized two-wheeler powertrain fabricators. Competitive moves center on thermal simulation technology licensing and strategic die fabrication partnerships.
Within the integrated automotive supplier tier, Endurance Technologies and Nemak exemplify divergent geographic strategies—Endurance anchoring cost-competitive production across India's western industrial corridor, Nemak occupying structural node supply positions in North American OEM programs. Georg Fischer Ltd represents the precision migration archetype, with Swiss-incorporated heritage signaling sand-casting-to-gravity-die process conversion capabilities for fluid power applications.
| Leading Market Players |
|---|
| Endurance Technologies |
| Minda Corporation Limited |
| Sundaram Clayton Limited |
| Rockman Industries |
| CIE Automotive |
| Nemak |
| Gibbs Die Casting Corp. |
| Georg Fischer Ltd |
| Dynacast International Inc. |
| Others |
Value Chain & Pricing Dynamics
Germany's Baden-Württemberg tooling fabrication cluster anchors upstream supply concentration, directing margin pools toward foundries with captive die design capabilities and long-term automotive program amortization structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing with three-tier differentiation across premium AS9100-certified aerospace castings, standard automotive-grade production, and economy-tier two-wheeler components. Price differentiation rests on certification burden and volume scale, with EPA fuel economy mandates compressing margins on fixed-price chassis contracts. Pricing pressure stems from primary aluminum energy cost volatility eroding foundry margin pools. Two-wheeler OEM procurement teams in India exhibit highest price sensitivity; aerospace airframe buyers accept premium positioning for traceability documentation.
Supply Chain Analysis
Tariff exposure between China and North American automotive corridors dominates supply chain risk planning for gravity die casting procurement. Production gravity centers on Germany, China, and India's western industrial corridor, with specialized steel die fabrication drawing from Baden-Württemberg supplier networks. Raw material dependencies rest on primary aluminum smelter output, high-grade tool steel, and precision CNC finishing capacity. Single-source vulnerability concentrates in permanent mold fabrication. Distribution runs through tier-one supplier consolidation panels serving OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gravity die casting operates as a defensive-moat market where regulatory entrenchment through NMPA traceability mandates and AS9100 certification pathways creates substantial switching costs for qualified supplier relationships.
For Market Incumbents: Insulate core automotive programs through backward integration into thermal simulation software licensing and captive die fabrication partnerships in Baden-Württemberg. High-pressure die casting substitution threatens structural node applications; counter by deepening multi-cavity tooling expertise for transmission housings where wall thickness requirements favor gravity processes. For New Entrants and Emerging Players: Build out compliance service capabilities targeting China's NMPA and MIIT material traceability enforcement, where third-party certification providers face demand surges. Hydraulic valve body precision migration offers the most penetrable white-space for sand-casting-to-gravity-die process conversion. Go-to-market positioning should emphasize documented low-carbon alloy sourcing for EU Green Deal qualification pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision foundry specialists holding AS9100 aerospace certifications and automotive thermal simulation capabilities. Long-term viability across the analysis window favors targets with multi-program tooling amortization and documented smelter partnerships for carbon border compliance. Watch for inflection in battery enclosure architecture shifts that accelerate or retard HPDC substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Tier-one suppliers compress tooling validation cycles from months to weeks across million-unit automotive programs. |
| Low-Carbon Smelter Partnership | European foundries gain preferential OEM qualification status under EU Green Deal carbon border adjustment mechanisms. |
| Multi-Cavity Die Investment | Mass production stage margin pools anchor on tooling amortization across high-volume transmission housing contracts. |
| Traceability Compliance Service | Third-party certification providers capture value from China's NMPA tightening rules for structural aluminum castings. |
| Thermal Simulation Capability Acquisition | Foundries address engineer scarcity in coupled fluid-thermal-solidification modeling for defect prediction. |
Study Parameters
The analysis maps engine block, transmission housing, bracket, and wheel sub-sectors, each validated through foundry operations directors, OEM procurement managers, tier-one supplier platform engineers, and thermal simulation software specialists. Primary interview intelligence combined with customs trade data, automotive production databases, SEC filings from listed component suppliers, and IHS Markit vehicle registration records. Bottom-up program-level volume estimates triangulate against top-down OEM lightweighting spend projections.
Fixed assumptions across the projection horizon include sustained EPA fuel economy standard stringency, continued EU Green Deal carbon border enforcement, and stable two-wheeler demand in India's western industrial corridor. Segmentation dimensions modeled encompass product type, end user industry, manufacturing stage, and regional production cluster. CAGRs derive from weighted average of program-level volume trajectories and value-per-vehicle content shifts. Industry-specific inputs include aluminum alloy price indices and multi-cavity tooling investment cycles.
Stress conditions across primary aluminum energy cost volatility, NMPA traceability timeline acceleration, and HPDC technological substitution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory enforcement shifts or battery enclosure architecture pivots. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Air Springs Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Brake Pad Market
Automotive Parts
Philippines Automotive Engine Oils Market