
 Aircraft Carrier Ship Market | 2026-2036
Aircraft Carrier Ship Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Carrier Ship Market Analysis
Naval procurement among sovereign buyers is consolidating around a handful of major fleet operators with long-term capital commitments. Newport News Shipbuilding leverages its monopoly on U.S. nuclear carrier construction to sustain decades-long production cycles. Huntington Ingalls Industries anchors the entire enterprise through integrated yard operations that span design, fabrication, and lifecycle support. BAE Systems competes across the Atlantic with specialized expertise in carrier conversion and complex systems integration for allied navies.
An aircraft carrier is a flat-deck warship designed to deploy, recover, and sustain fixed-wing aircraft operations at sea, typically displacing over 40,000 tons with a flight deck length exceeding 240 meters and propulsion systems enabling sustained speeds above 25 knots. Its primary purpose is to project air power beyond territorial limits without dependence on land-based airfields. Nuclear-powered carriers dominate capital allocation within the ship type segment due to their unlimited endurance and strategic mobility, while integrated command and automation systems represent the fastest-growing technology category as navies reduce crew complements and accelerate decision cycles. Conventional propulsion retains relevance for mid-size operators with constrained budgets or non-nuclear policies.
The U.S. Navy's shipbuilding standards, the UK's Defence Nuclear Safety Regulator requirements, and China's MEE environmental compliance frameworks for naval yards collectively shape design specifications, construction timelines, and international market access for foreign suppliers. EMALS certification demands and reactor safety protocols create barriers that only established nuclear-certified shipbuilders can surmount. Stakeholders must monitor shifting alliance structures and domestic content rules that determine which yards qualify for carrier construction contracts.
Market Dynamics
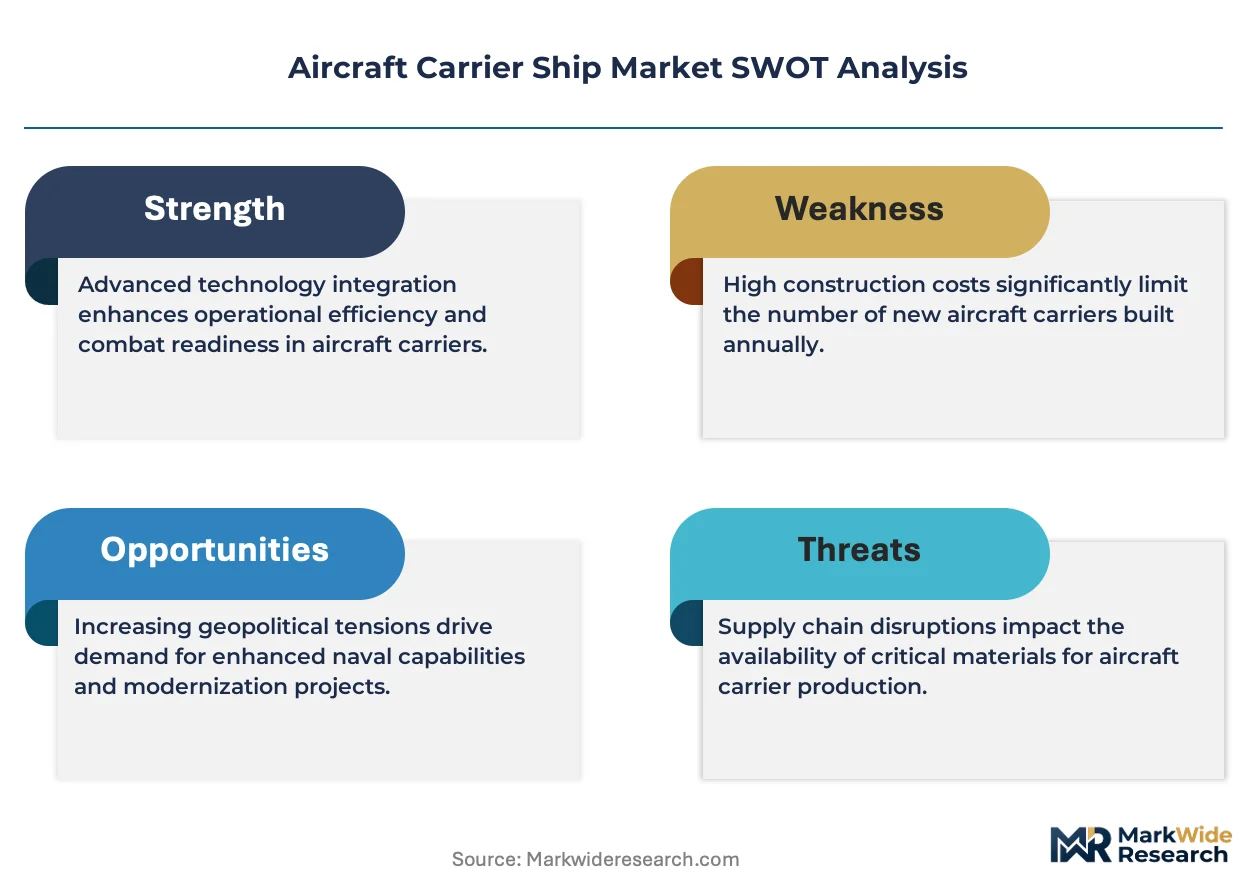
Electromagnetic launch technology is compressing carrier construction timelines while expanding the pool of aircraft types deployable from flat-deck hulls. This shift is redistributing competitive advantage toward yards with advanced electrical systems integration capabilities.
Growth Catalysts
- EMALS Mandates:U.S. Navy specifications requiring electromagnetic catapults on new hulls are pulling advanced motor and power electronics demand into certified supplier networks.
- Indo-Pacific Alliances:Australia's AUKUS commitments and Japan's defense posture reviews are generating joint carrier-compatible logistics requirements.
- Reactor Modernization Cycles:Life-extension programs for existing nuclear propulsion plants are sustaining specialized engineering workforce pools at Newport News and BAE Systems facilities.
Market Restraints
- Specialized Steel Input Costs:HY-80 and HY-100 alloy plate availability constrains hull fabrication schedules at any price point.
- Geographic Supply Concentration:Electromagnetic launch system manufacturing concentrates in a single U.S. defense contractor, creating single-source vulnerability for allied navies.
- Nuclear Certification Barriers:U.S. Navy reactor safety protocols and UK Defence Nuclear Safety Regulator requirements exclude non-certified shipyards from prime contractor status.
Strategic Opportunities
- Conventional Carrier White Space:Turkey and South Korea are evaluating ski-jump configured hulls that bypass electromagnetic launch requirements entirely.
- Dual-Use Port Infrastructure:Civilian heavy-lift vessel standards from classification societies are converging with naval auxiliary requirements, opening commercial yard participation.
- Automation Retrofit Demand:Legacy hulls in France and India require integrated command system upgrades to reduce crew complements without dry-dock reconstruction.
Industry Challenges
- Welding Specialist Scarcity:Thick-section alloy hull welding certification programs produce fewer qualified technicians than retirement rates across U.S. and UK yards.
- Electromagnetic-Arresting Integration Complexity:Advanced Arresting Gear systems require simultaneous power management and mechanical braking coordination that extends sea trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Carrier Ship Market |
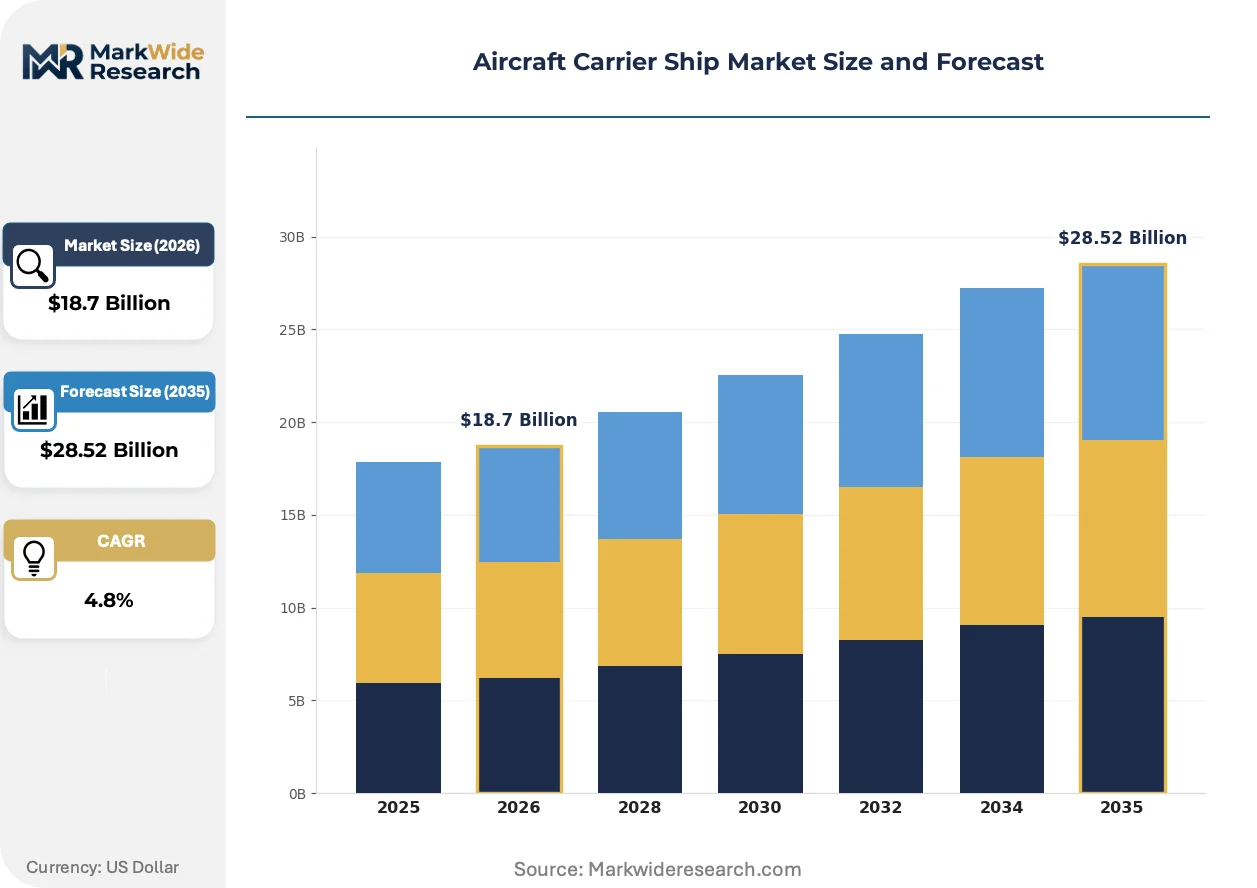
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ship Type: Nuclear-Powered, Conventional, Amphibious, Helicopter Carrier End User: Naval Forces, Coast Guards, Research Organizations, Private Contractors Deployment Type: Active Fleet, Reserve Fleet, Decommissioned, Under Construction Technology: Integrated Command, Stealth Features, Advanced Radar, Automation Systems |
| Companies Covered | Naval Group, Newport News Shipbuilding, Huntington Ingalls Industries, Thales Group, Dalian Shipbuilding Industry Company, General Dynamics, BAE Systems, Babcock International, China State Shipbuilding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Carrier Ship Market Emerging Trajectories
Carrier design is converging around unmanned aircraft integration requirements that demand redesigned flight decks and hangar configurations. This shift is compressing the relevance of legacy human-pilot-optimized infrastructure.
Distributed energy storage architectures are unifying propulsion, weapons, and launch power demands into single integrated power systems. The U.S. Navy's Ford-class hulls are adopting these configurations fastest. This unifying approach is eliminating redundant turbine-generator sets and freeing hull volume for aviation fuel or ordnance magazines.
China's MEE environmental compliance frameworks are tightening heavy-metal discharge standards at Dalian and Jiangnan shipyards. These rules are extending construction timelines for hulls in early fabrication stages. Conventional propulsion variants for export markets are most affected, as nuclear hulls operate under separate environmental review tracks.
Allied navies are consolidating through-life support contracts into single prime-vendor arrangements that bundle construction, maintenance, and mid-life refit obligations. Australia's future carrier planning and the UK's Carrier Strike Group sustainment model illustrate this compression. France's Naval Group is responding with extended performance guarantees on Charles de Gaulle replacement studies.
Aircraft Carrier Ship Market Segmentation
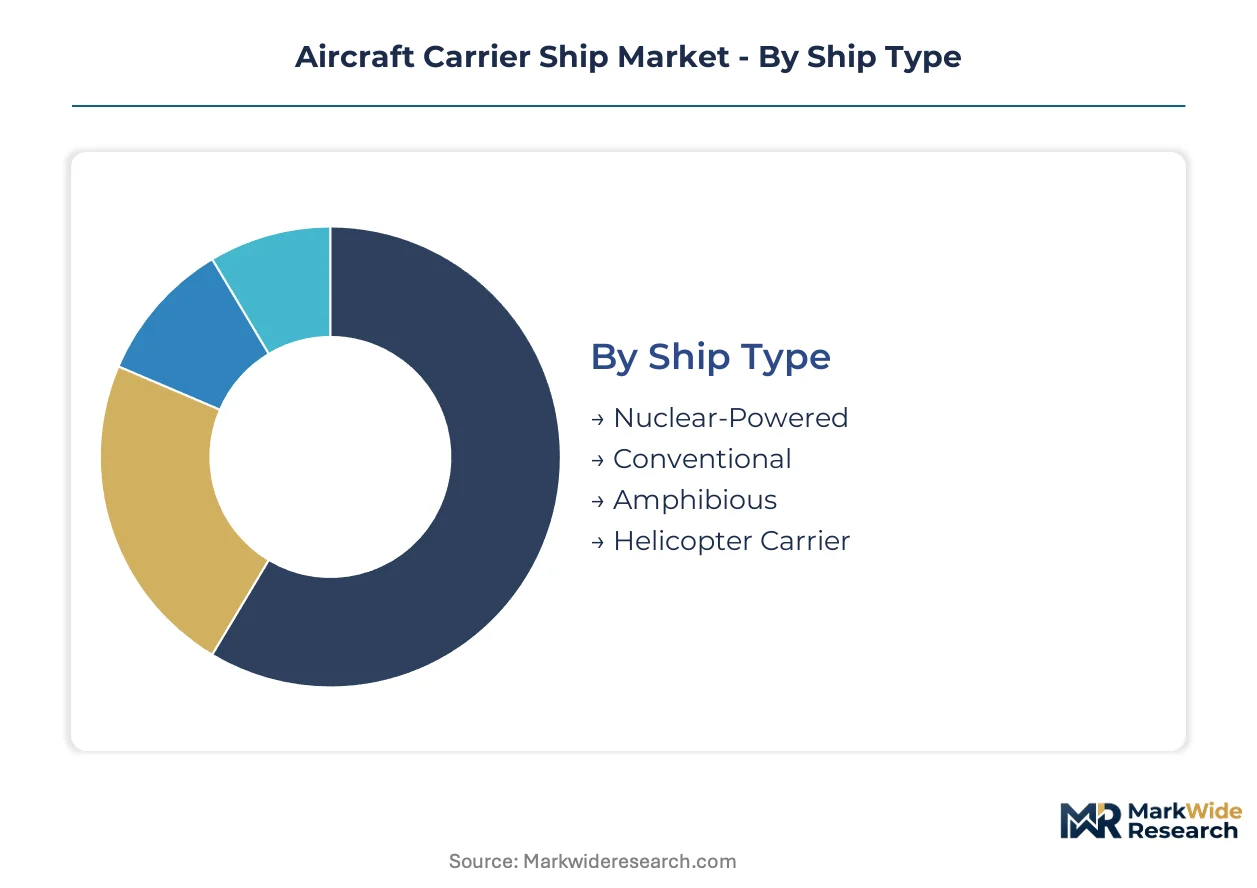
Carrier procurement decisions cascade through multiple classification systems that determine construction standards, operational roles, and lifecycle economics. Each segmentation dimension shapes vendor qualification requirements and alliance compatibility for fleet operators.
Ship Type:
Nuclear hulls operate as sovereign strategic assets with decades-long deployment horizons, while conventional variants serve alliance partners with constrained capital cycles or non-nuclear policies.
- Nuclear-Powered:These hulls integrate pressurized water reactors delivering unlimited endurance at speeds exceeding 30 knots. The U.S. Navy's Ford-class program and the UK's Dreadnought replacement studies concentrate demand for Newport News and BAE Systems yards, with reactor certification barriers excluding non-nuclear shipbuilders from prime contractor status.
- Conventional:Oil-fired or gas-turbine propulsion limits range but reduces construction complexity and crew radiation safety requirements. China's Type 003 program and Turkey's prospective ski-jump hulls demonstrate where mid-size operators bypass nuclear infrastructure investments entirely.
- Amphibious:Flat-deck hulls optimized for vertical assault with well decks and landing craft capacity alongside aviation facilities. U.S. Navy America-class and Chinese Type 075 programs dominate this segment's procurement volume.
- Helicopter Carrier:Smaller displacement hulls optimized for rotary-wing and tiltrotor operations without fixed-wing catapult requirements. Japan's Izumo-class conversions and South Korean CVX studies illustrate regional demand for lower-cost aviation platforms.
Volume placements concentrate in nuclear-powered hulls; the faster expansion belongs to helicopter carriers as Indo-Pacific operators seek affordable aviation presence.
End User:
Procurement authority distribution shapes contract structures, with sovereign naval commands retaining direct construction oversight while research organizations influence technology demonstration programs.
- Naval Forces:National fleet commands in the United States, China, and the United Kingdom drive capital allocation through decade-long shipbuilding programs. These operators specify EMALS mandates and nuclear safety protocols that filter vendor pools.
- Coast Guards:Maritime security agencies with limited aviation requirements occasionally acquire surplus hulls or modified auxiliaries. No major carrier construction programs originate from coast guard procurement.
- Research Organizations:Defense laboratories and naval test establishments charter hulls for electromagnetic launch validation and unmanned aircraft integration trials. ONR and China's 701 Institute influence pre-production technology maturation.
- Private Contractors:Commercial operators provide through-life maintenance and mid-life refit services under long-term performance contracts. Huntington Ingalls Industries and Naval Group bundle construction with sustainment obligations.
Capital deployment clusters with naval forces; research organizations are gaining share fastest as unmanned aircraft integration demands expand sea trial complexity.
Deployment Type:
Status classification determines maintenance liability distribution and crew training pipeline allocation across fleet management cycles.
- Active Fleet:Operationally deployable hulls with full air wings and escort groups maintained at readiness. The U.S. Navy maintains eleven active carriers under continuous deployment rotation.
- Reserve Fleet:Mothballed hulls preserved for rapid reactivation during surge requirements. No nuclear carriers currently reside in reserve status due to reactor maintenance complexity.
- Decommissioned:Permanently retired hulls awaiting disposal or conversion to museums. U.S. Navy Enterprise and France's Clemenceau-class illustrate end-of-life management challenges.
- Under Construction:Hull modules in fabrication or outfitting phases at certified shipyards. Newport News and Jiangnan shipyards hold the majority of global carrier construction backlog.
Operational emphasis rests with active fleet hulls; under construction categories are climbing the fastest as Indo-Pacific operators accelerate build schedules.
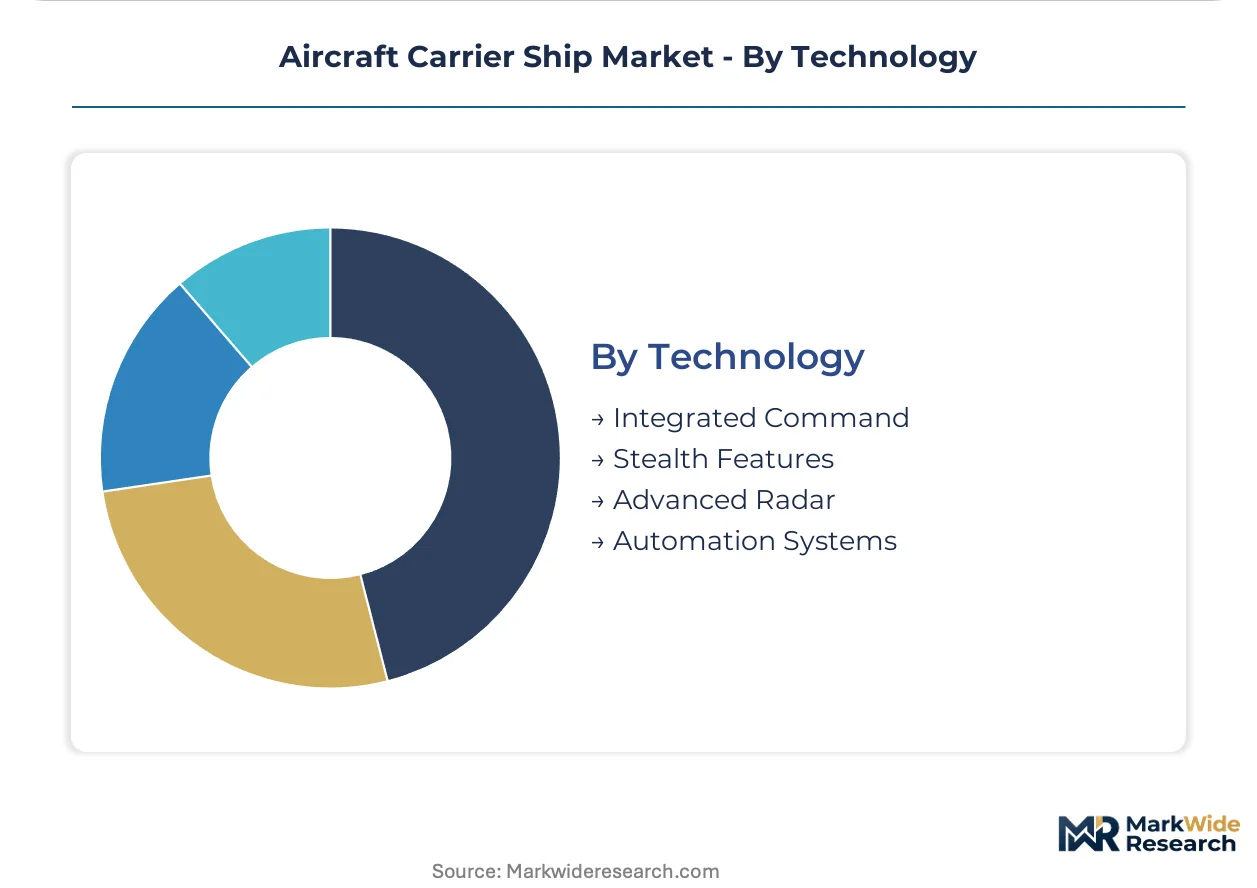
Technology:
Systems integration depth separates legacy hulls requiring dry-dock reconstruction from new-build platforms with native digital architectures.
- Integrated Command:Unified combat management systems consolidating sensor fusion, weapons direction, and aviation control into single operator workstations. France's PA2 studies and India's Vikrant-class retrofits demonstrate demand concentration.
- Stealth Features:Radar cross-section reduction through angled island structures, signature-managed flight deck coatings, and infrared suppression systems. China's Type 003 incorporates integrated stealth design from keel laying.
- Advanced Radar:Dual-band active electronically scanned arrays for air surveillance and fire control. SPY-6 procurement for Ford-class follow-on hulls anchors U.S. Navy demand.
- Automation Systems:Reduced crew complements through robotics for munitions handling, damage control, and aviation fueling. Royal Navy Queen Elizabeth-class automation targets 40% crew reduction versus previous generation.
Procurement volume concentrates in integrated command installations; automation systems show the steepest expansion trajectory as personnel costs escalate across NATO and Indo-Pacific fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier construction concentrates where naval budgets sustain decade-long capital cycles and certified shipyards maintain nuclear-qualified workforces. Sovereign procurement in the United States, China, and the United Kingdom absorbs the majority of global hull fabrication capacity.
United States
The U.S. Navy's Ford-class program drives EMALS and reactor integration demand through Newport News Shipbuilding. Department of Defense shipbuilding standards mandate nuclear certification that excludes non-qualified contractors. Virginia's Hampton Roads cluster anchors the entire enterprise through integrated design-fabrication-lifecycle operations.
China
Type 003 and follow-on hulls at Dalian and Jiangnan shipyards expand the People's Liberation Army Navy's blue-water aviation capabilities. MEE environmental compliance frameworks tighten heavy-metal discharge standards at naval construction facilities. Dalian Shipbuilding Industry Company concentrates activity in Liaoning province where steel plate logistics and military oversight converge.
United Kingdom
Queen Elizabeth-class operations and Dreadnought replacement studies sustain BAE Systems' carrier-relevant engineering workforce. The Defence Nuclear Safety Regulator imposes reactor safety protocols that filter vendor participation. Scotland's Rosyth facilities handle integration and through-life support for Royal Navy flat-deck programs.
France
Charles de Gaulle replacement studies and PA2 concept development keep Naval Group engaged in next-generation carrier architecture. ANSM and defense procurement directives shape nuclear propulsion safety requirements for future hulls. Brittany's Lorient and Saint-Nazaire yards maintain specialized capability for complex naval systems integration.
Japan
Izumo-class conversions and CVX studies reflect Maritime Self-Defense Force interest in fixed-wing aviation from flat-deck hulls. METI industrial policy supports domestic shipyard participation in naval construction. Nagasaki and Yokohama clusters advance heavy-industry fabrication standards applicable to prospective carrier programs.
Aircraft Carrier Ship Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue conventional propulsion and regional aviation platform niches. The market structure consolidates around sovereign-certified shipyards with nuclear construction heritage, while mid-size operators compete on conversion and subsystem integration. Three archetypes dominate: integrated prime contractors with design-to-disposal capabilities, specialized combat systems integrators, and state-owned enterprises with captive domestic demand. Competitive dynamics center on long-term performance contracting and cross-border alliance structures for through-life support.
Among integrated prime contractors, Huntington Ingalls Industries and BAE Systems exemplify the sovereign-certified archetype with decades-long production cycles. Naval Group occupies a comparable position in the European tier. State-owned enterprises including China State Shipbuilding Corporation represent the alternative model where domestic procurement absorbs hull fabrication capacity without external competition. Newport News Shipbuilding anchors the U.S. nuclear carrier construction segment through exclusive Ford-class production rights.
| Leading Market Players |
|---|
| Naval Group |
| Newport News Shipbuilding |
| Huntington Ingalls Industries |
| Thales Group |
| Dalian Shipbuilding Industry Company |
| General Dynamics |
| BAE Systems |
| Babcock International |
| China State Shipbuilding Corporation |
| Others |
Supply Flow & Price Mechanics
HY-80 and HY-100 alloy plate costs cascade from U.S. and Japanese specialty steel mills through Newport News and Dalian shipyards into nuclear carrier hull fabrication premiums, while electromagnetic launch system single-source dependency concentrates pricing power with General Dynamics Electric Boat's supplier network.
Pricing Analysis
Volume placements cluster with sovereign naval commands bearing decade-long capital cycles, while margins concentrate in reactor-certified yards protected by U.S. Navy and UK Defence Nuclear Safety Regulator barriers. Price differentiation rests on nuclear certification tier and EMALS integration depth. Cost compression in conventional propulsion segments intensifies as Turkey and South Korea evaluate ski-jump alternatives. Coast guard and research organization buyers exhibit highest price sensitivity; national fleet commands show lowest.
Supply Chain Analysis
Freight costs for reactor pressure vessel forgings and electromagnetic launch system components concentrate supply chain leverage on U.S.-based heavy-lift logistics networks. Manufacturing draws from the United States, China, and the United Kingdom for certified hull fabrication. Critical inputs include HY-80 steel plate, pressurized water reactor components, and advanced radar arrays. Single-source vulnerability in electromagnetic catapult production creates structural risk. Distribution runs through sovereign defense procurement channels with classified contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where U.S. Navy reactor safety protocols and UK Defence Nuclear Safety Regulator requirements erect decade-long certification barriers that protect incumbent margins from unqualified competitors.
For Market Incumbents: Anticipate workforce attrition in thick-section alloy welding certification programs by expanding apprenticeship pipelines at Newport News and Rosyth facilities. Lock in through-life support contracts that bundle construction with mid-life refit obligations, neutralizing emerging Turkish and South Korean yards competing on conventional hull price points.
For New Entrants and Emerging Players: Enter via automation systems retrofit demand for legacy French and Indian hulls requiring integrated command upgrades without dry-dock reconstruction. Target helicopter carrier segments where Japan's Izumo-class conversions and South Korean CVX studies demonstrate lower certification barriers. Pursue dual-use port infrastructure convergence between civilian heavy-lift standards and naval auxiliary requirements.
For Investors and Strategic Acquirers: AUKUS joint logistics commitment announcements are the leading indicator that through-life support contract bundling is accelerating across Indo-Pacific allied navies. Five-to-ten year viability favors yards with captive nuclear-certified workforces and EMALS integration capabilities. Monitor Australia's future carrier planning disclosures as inflection signals for regional procurement concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Certification Investment | U.S. Navy protocols exclude non-qualified shipbuilders from Ford-class prime contractor status entirely. |
| EMALS Supplier Network Expansion | General Dynamics Electric Boat's electromagnetic launch manufacturing creates single-source leverage for allied navies. |
| Through-Life Support Bundling | Australia's carrier planning and UK Carrier Strike Group sustainment compress vendor relationships into single-prime arrangements. |
| Automation Systems Retrofit | France's Charles de Gaulle and India's Vikrant-class generate demand for crew reduction without hull reconstruction. |
| Conventional Propulsion White Space | Turkey's ski-jump evaluations and South Korean CVX studies bypass nuclear infrastructure investments entirely. |
Methodological Framework
Defense procurement databases, naval shipbuilding trade filings, and sovereign budget appropriations records formed the secondary backbone, supplemented by primary interviews with carrier program executives, naval reactor safety regulators, shipyard welding certification directors, and electromagnetic systems integration engineers. Bottom-up hull fabrication capacity estimates triangulated against top-down naval budget allocation analysis across the analysis window.
Historical carrier delivery timelines and reactor plant modernization cycles anchored projection modeling across ship type, propulsion architecture, and technology segmentation dimensions. CAGRs derived from defense procurement trajectory correlation with fleet replacement schedules. Forecast inputs incorporated EMALS certification pipeline constraints and Indo-Pacific alliance structure evolution.
Revisions become necessary when AUKUS commitment modifications, MEE environmental compliance tightening, or nuclear certification protocol changes materialize. Forecasts reflect documented assumptions regarding sovereign budget continuity and shipyard workforce retention. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Naval Smart Weapons Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Bow and Stern Thrusters Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Military Frigate Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Combat Management System Market
Naval Warfare
Naval Vessels and Surface Combatants Market