
 North America Industrial Catalyst Market | 2026-2036
North America Industrial Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Catalyst Market Intelligence
Ultra-low sulfur diesel (ULSD) grade specifications is bifurcating the North America industrial catalyst landscape into premium-performance and commodity supply tiers. Albemarle Corporation leverages its bromine and lithium-linked catalyst precursor chain to sustain cost-advantaged hydroprocessing catalyst output. BASF SE anchors its position through integrated rare earth sourcing for automotive emission control catalysts. Johnson Matthey competes via deep specialization in platinum group metal (PGM) reforming systems for the U.S. refining base.
An industrial catalyst is a substance that accelerates chemical reactions without permanent consumption, typically engineered from zeolite frameworks, transition metal oxides, or supported PGM compositions manufactured through impregnation, precipitation, or sol-gel methods, and deployed to raise yield, selectivity, or energy efficiency in continuous-flow chemical processes. Heterogeneous catalysts dominate installed value due to their separability and regeneration economics in fixed-bed refinery reactors. Environmental applications represent the fastest-expanding application segment as EPA Tier 3 and Environment Canada Clean Fuel Regulations tighten tailpipe and stack emission limits. Zeolite catalysts occupy a structurally defended margin pool because their microporous topology demands proprietary synthesis know-how and lengthy customer qualification cycles.
EPA emission standards, Environment Canada Clean Fuel Regulations, and OSHA process safety mandates collectively shape catalyst formulation requirements, testing protocols, and refinery retrofit timelines across the United States and Canada. The U.S. Environmental Protection Agency enforces Mobile Source Air Toxics rules that directly dictate PGM loading specifications in automotive catalytic converters. Stakeholders must monitor evolving cross-border carbon intensity accounting rules, as these will determine whether U.S. Gulf Coast or Alberta-based producers face diverging catalyst performance thresholds for hydrogen production and fuel upgrading.
Market Dynamics
Ultra-low sulfur diesel mandates from EPA and Environment Canada are compressing catalyst replacement cycles across the U.S. Gulf Coast refining corridor, forcing operators to absorb premium-grade reforming systems at higher frequency than historical baselines.
Growth Catalysts
- EPA Tier 3 tailpipe standards:These rules mandate stricter sulfur and particulate limits, compelling refiners to deploy advanced hydroprocessing catalysts in gasoline and diesel upgrading units.
- Polymerization demand:Integrated petrochemical complexes along the Texas-Louisiana corridor consume zeolite catalysts continuously for polyethylene and polypropylene production.
- Alberta oil sands upgrading:Heavy bitumen processing requires specialized hydrotreating catalysts to meet pipeline specifications and export-grade product standards.
Market Restraints
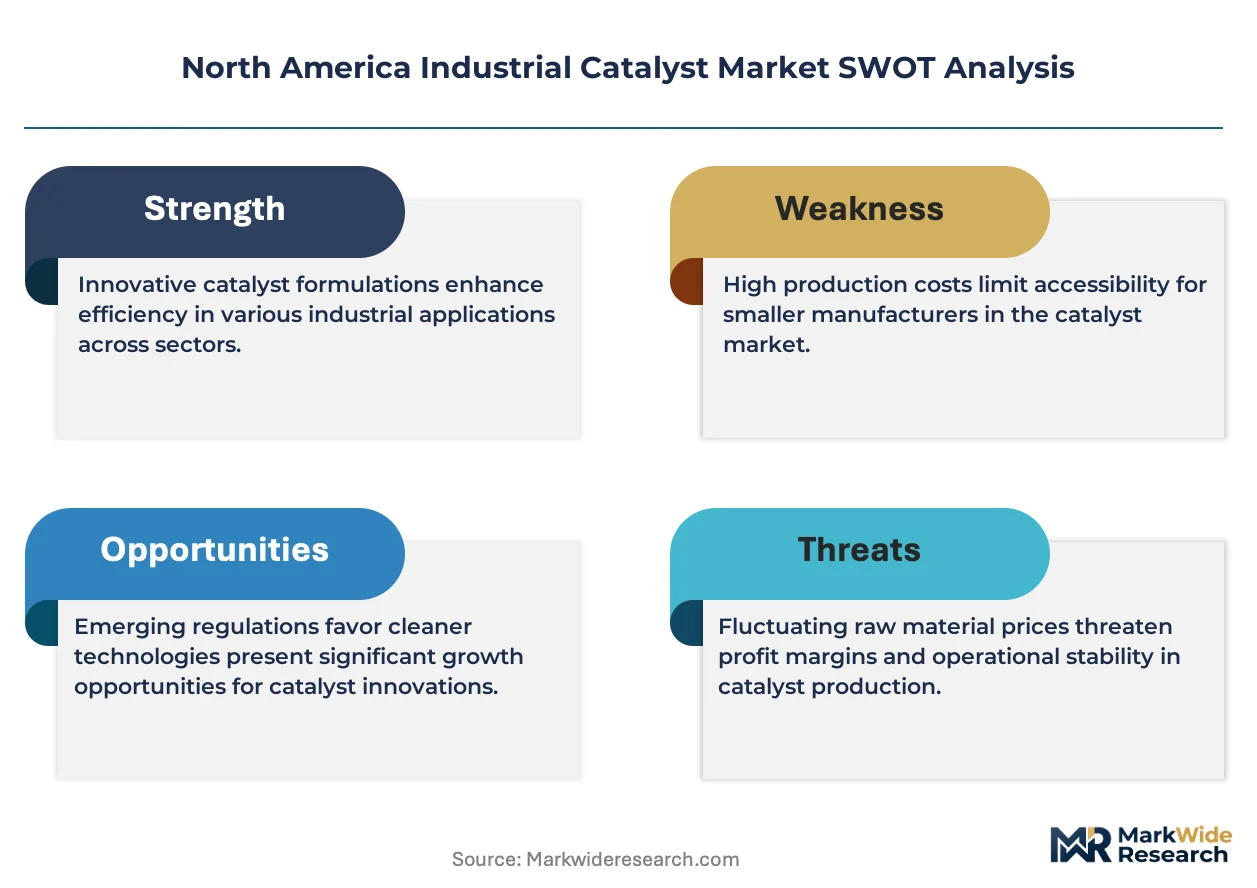
- PGM price volatility:Platinum and palladium cost swings directly compress margins for automotive emission control catalyst formulations.
- Rare earth concentrate dependence:Zeolite catalyst production relies on Chinese-processed lanthanide supply chains vulnerable to export quota disruptions.
- Extended qualification timelines:Refinery catalyst approvals from U.S. operators stretch 18-24 months, locking out novel formulations regardless of performance gains.
Strategic Opportunities
- Carbon capture integration:Catalyst-assisted hydrogen production for ammonia and blue hydrogen projects in Louisiana and Alberta opens adjacent demand pools.
- Mexico refinery modernization:Pemex facility upgrades present greenfield catalyst specification opportunities outside saturated U.S. markets.
- Renewable diesel feedstock processing:Pretreatment catalysts for waste oils and fats address emerging renewable fuel mandates in California and British Columbia.
Industry Challenges
- Specialized synthesis technician shortage:Zeolite manufacturing requires proprietary hydrothermal reactor operation expertise concentrated among retiring cohorts at legacy production sites.
- Cross-border carbon accounting alignment:Divergent methodologies between U.S. EPA and Environment Canada complicate catalyst performance benchmarking for integrated North American operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Catalyst Market |
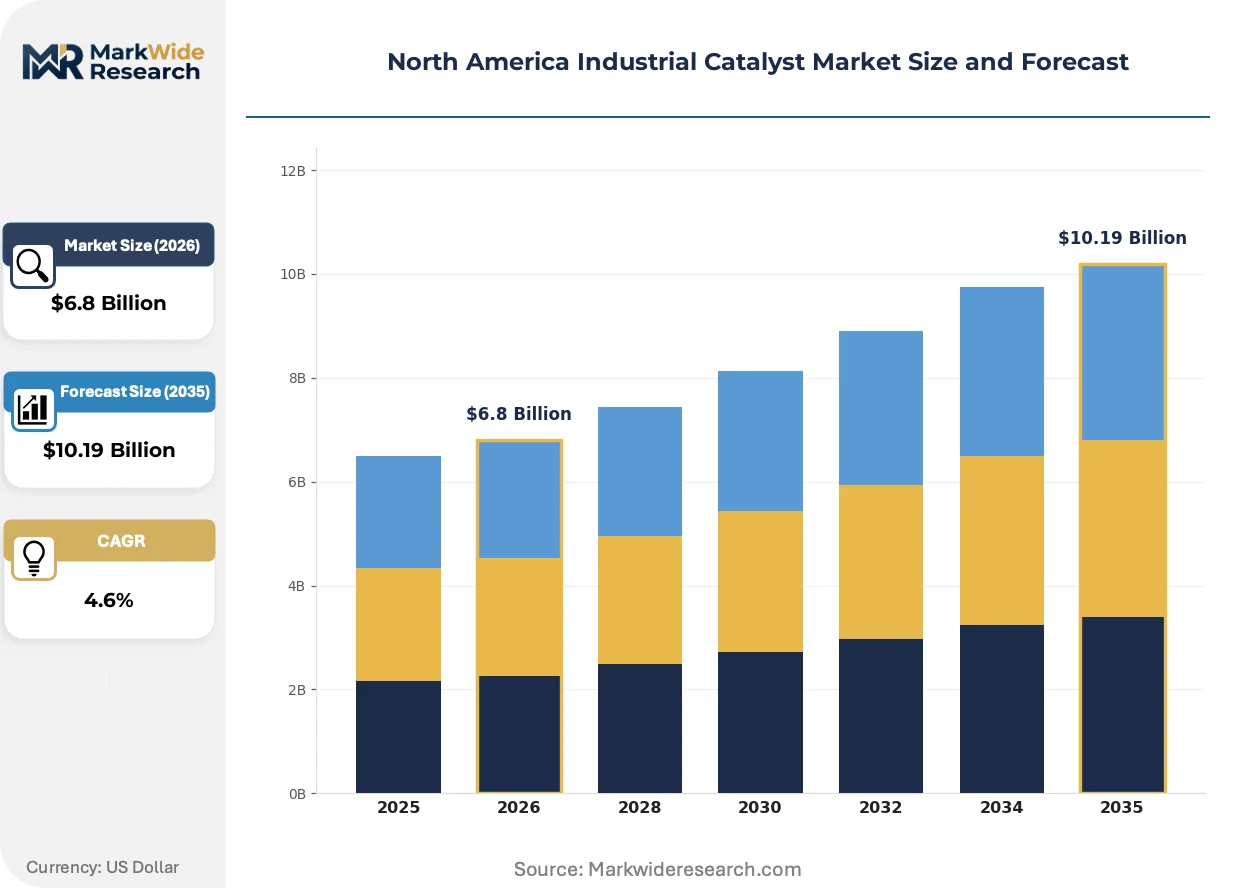
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heterogeneous Catalysts, Homogeneous Catalysts, Enzymatic Catalysts, Supported Catalysts Application: Chemical Production, Refining Processes, Environmental Applications, Petrochemicals End User: Chemicals Industry, Oil & Gas, Pharmaceuticals, Automotive Technology: Zeolite Catalysts, Metal Catalysts, Biocatalysts, Supported Metal Catalysts |
| Companies Covered | Albemarle Corporation, BASF SE, Clariant AG, Johnson Matthey, Honeywell UOP, W. R. Grace & Co., Evonik Industries, Haldor Topsoe, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Catalyst Market Strategic Shifts & Innovations
Zeolite topology engineering and PGM loading optimization are converging to redefine performance benchmarks across refinery and environmental catalyst categories. These advances compress the viable lifecycle of incumbent formulations while opening specification windows for differentiated suppliers.
Single-atom platinum dispersions on tailored alumina supports are supplanting conventional nanoparticle loadings in diesel oxidation catalysts. U.S. heavy-duty truck engine manufacturers are qualifying these systems for 2027 model year compliance. The shift enables 40% PGM reduction while maintaining conversion efficiency, compressing raw material cost exposure for catalyst formulators.
Environment Canada's Clean Fuel Regulations impose escalating carbon intensity reduction requirements on gasoline and diesel pools through 2030. Refiners must deploy advanced hydrotreating catalysts to process renewable feedstocks and achieve compliance credits. The regulation most directly affects integrated operators in Ontario and Quebec with limited coking capacity for residue upgrading.
Refinery procurement departments are consolidating catalyst supply relationships from fragmented regional distributors toward direct manufacturer partnerships. This consolidation eliminates specification interpretation errors and accelerates technical service response. The pattern is most pronounced among merchant refiners in the U.S. Mid-Atlantic lacking in-house catalyst research capabilities.
North America Industrial Catalyst Market Segmentation
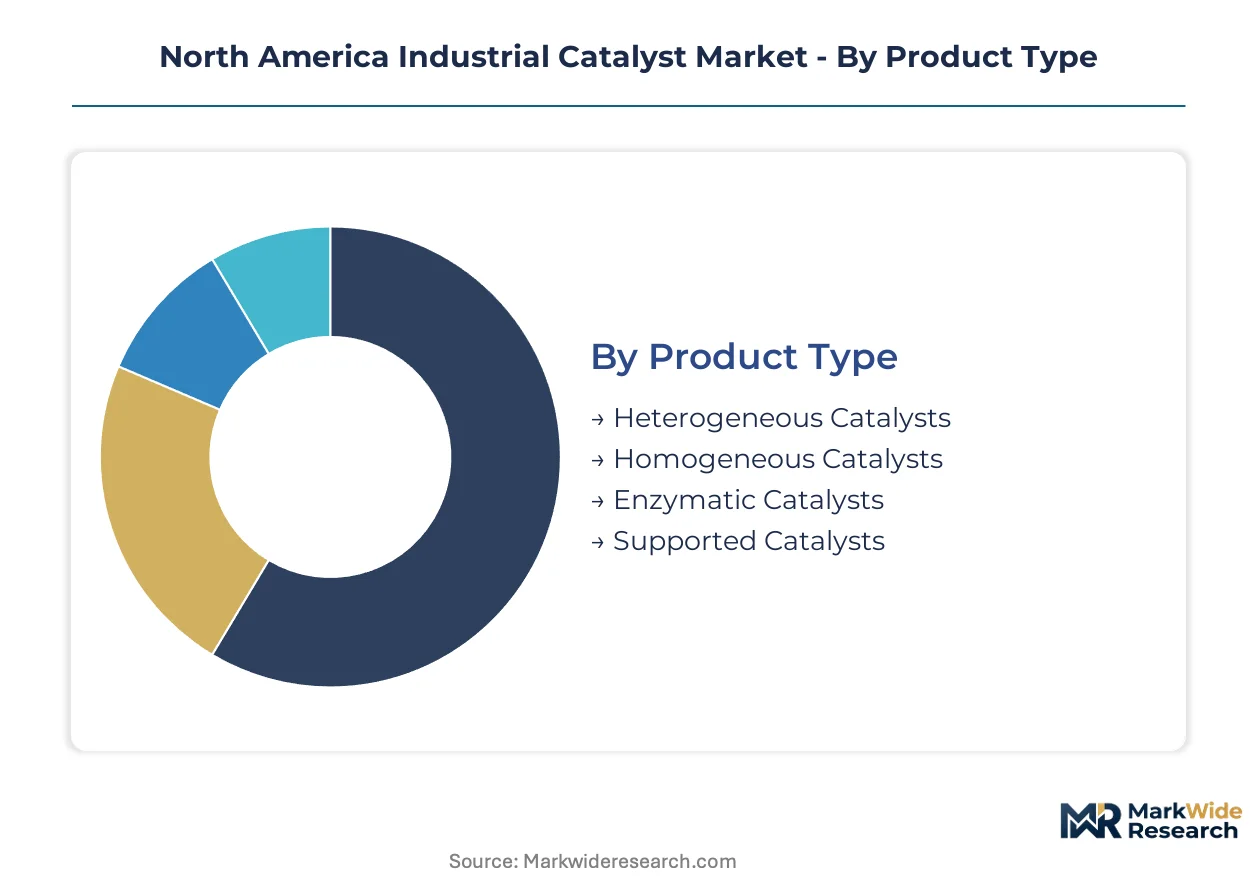
Industrial catalyst procurement in North America follows distinct technical and commercial logics across product, application, and end-user dimensions. EPA Tier 3 and Environment Canada Clean Fuel Regulations create divergent specification requirements that reshape how segments compete on performance versus cost.
Product Type:
EPA and Environment Canada mandates on sulfur content and emission intensity split catalyst procurement between regenerable fixed-bed systems and single-use homogeneous formulations.
- Heterogeneous Catalysts:Solid-phase systems deploy in fixed-bed refinery reactors where separability enables regeneration economics. U.S. Gulf Coast hydroprocessing units consume these continuously under tightening ULSD specifications.
- Supported Catalysts:Active metals dispersed on alumina, silica, or zeolite carriers dominate automotive emission control under EPA Mobile Source Air Toxics rules. Platinum group metal loading optimization compresses raw material exposure while maintaining conversion efficiency.
- Homogeneous Catalysts:Single-phase liquid systems serve specialty chemical production with precise molecular control.
- Enzymatic Catalysts:Protein-based biocatalysts address pharmaceutical and renewable fuel applications with mild operating conditions.
Heterogeneous catalysts handle the majority of throughput; supported catalysts are the fastest mover on share.
Application:
Cost tier differentiation separates continuous-process refinery units from batch chemical operations with disparate catalyst replacement economics.
- Refining Processes:Hydrocracking and hydrotreating units along the Texas-Louisiana corridor operate under compressed replacement cycles mandated by sulfur regulations. Alberta oil sands upgrading demands specialized heavy feedstock tolerance.
- Environmental Applications:Automotive catalytic converters and stationary emission control systems face escalating PGM loading specifications under EPA Tier 3. This segment climbs the fastest on regulatory pressure.
- Petrochemicals:Polyethylene and polypropylene polymerization consumes zeolite catalysts in integrated Gulf Coast complexes.
- Chemical Production:Batch and continuous specialty chemical processes deploy homogeneous and enzymatic systems.
Refining processes anchor installed value; environmental applications are expanding most quickly on compliance-driven retrofit demand.
End User:
Customer type determines procurement consolidation patterns, with integrated operators favoring direct manufacturer partnerships over distributor intermediaries.
- Oil & Gas:Merchant refiners and integrated majors in the U.S. Mid-Atlantic and Gulf Coast consolidate supply relationships to eliminate specification errors. Extended qualification timelines lock in incumbent suppliers.
- Chemicals Industry:Petrochemical complexes drive continuous zeolite consumption for polymerization units.
- Automotive:Heavy-duty truck engine manufacturers qualify single-atom platinum dispersions for emission compliance.
- Pharmaceuticals:Batch pharmaceutical synthesis employs enzymatic catalysts for stereoselective transformations.
Oil & gas commands the dominant procurement volume; automotive is gaining share fastest on emission standard tightening.
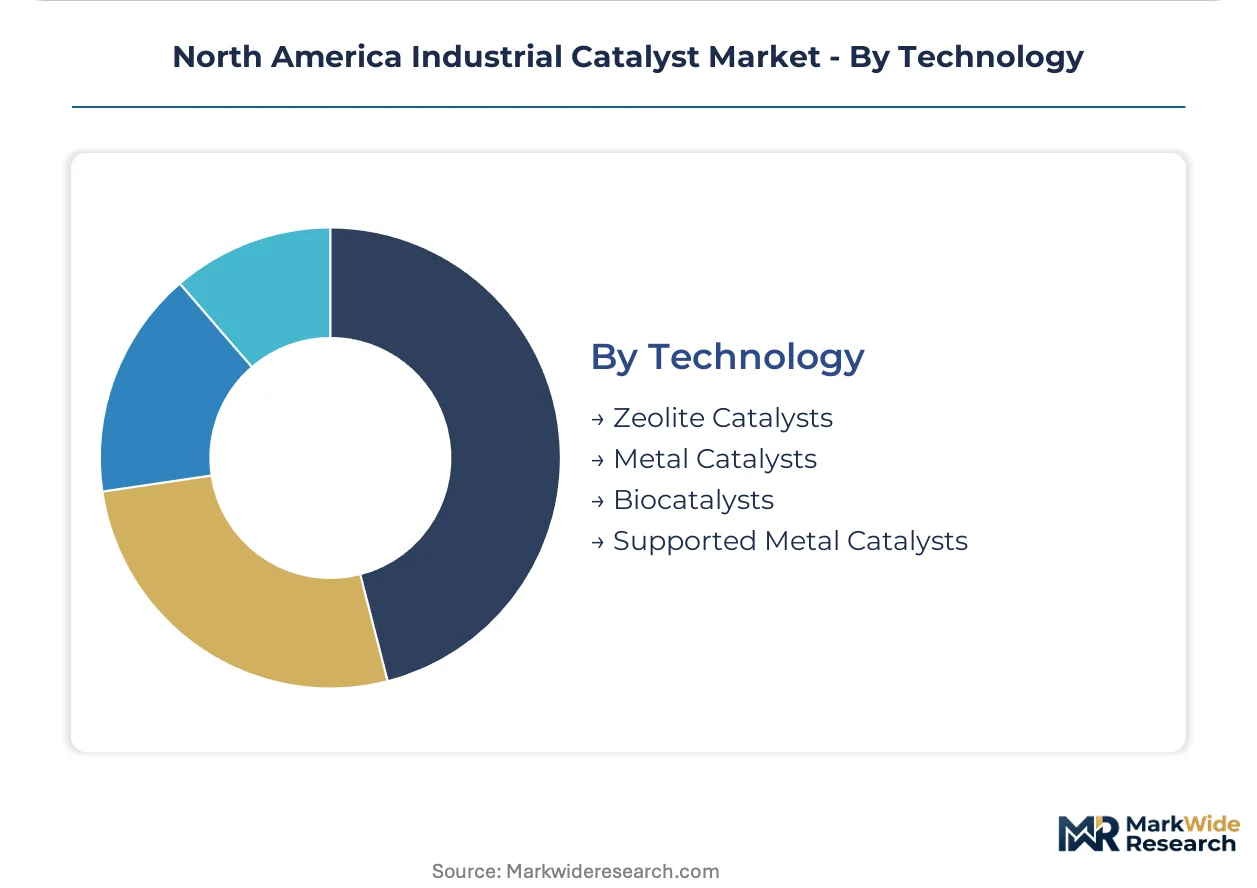
Technology:
Margin structure varies with synthesis complexity, where proprietary zeolite topology commands defended returns against commodity metal catalyst competition.
- Zeolite Catalysts:Microporous aluminosilicate frameworks require hydrothermal synthesis expertise concentrated among legacy production sites. Proprietary topology and lengthy customer qualification cycles protect margin pools.
- Metal Catalysts:Platinum, palladium, and base metal systems face raw material price volatility that compresses formulation margins.
- Supported Metal Catalysts:Dispersed active phases on tailored carriers optimize PGM utilization for automotive applications.
- Biocatalysts:Enzyme immobilization technologies serve pharmaceutical and renewable chemical niches.
Zeolite catalysts dominate value capture; supported metal catalysts are climbing fastest on PGM efficiency optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalyst manufacturing concentrates in the U.S. Gulf Coast petrochemical corridor, where integrated refinery complexes sustain continuous demand for hydroprocessing and polymerization systems. Canadian oil sands upgrading and Mexican refinery modernization create secondary demand nodes with distinct specification requirements.
United States
EPA Tier 3 tailpipe standards and ULSD mandates drive catalyst replacement cycles across Texas-Louisiana refining complexes. The U.S. Environmental Protection Agency enforces Mobile Source Air Toxics rules that dictate PGM loading specifications. Houston-area petrochemical clusters consume zeolite catalysts continuously for polyethylene and polypropylene production.
Canada
Alberta oil sands upgrading demands specialized hydrotreating catalysts for heavy bitumen processing to meet pipeline specifications. Environment Canada Clean Fuel Regulations impose escalating carbon intensity reduction requirements through 2030. Ontario and Quebec refiners deploy advanced catalyst systems to process renewable feedstocks for compliance credits.
Mexico
Pemex facility upgrades present greenfield catalyst specification opportunities outside saturated U.S. markets. Mexican energy sector reforms accelerate refinery modernization timelines. Nuevo León and Tamaulipas industrial corridors attract catalyst suppliers targeting petrochemical expansion projects.
North America Industrial Catalyst Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated chemical conglomerates with captive raw material positions compete against specialized catalyst formulators with deep process expertise. Two strategic archetypes dominate: diversified materials suppliers leveraging upstream integration, and focused technology licensors commanding premium pricing through proprietary formulations. Competitive moves center on direct manufacturer partnerships with refiners and zeolite topology engineering investments.
Among U.S.-based diversified materials suppliers, Albemarle Corporation exemplifies the upstream-integrated archetype through its bromine and lithium-linked precursor chain. German chemical conglomerate BASF SE anchors the European multinational position with integrated rare earth sourcing capabilities. British specialist Johnson Matthey occupies the focused technology tier through deep platinum group metal reforming expertise. These three companies represent distinct competitive positions without overlapping strategic profiles.
| Leading Market Players |
|---|
| Albemarle Corporation |
| BASF SE |
| Clariant AG |
| Johnson Matthey |
| Honeywell UOP |
| W. R. Grace & Co. |
| Evonik Industries |
| Haldor Topsoe |
| ExxonMobil Chemical |
| Others |
Cost & Logistics Intelligence
Eighteen-month qualification timelines for refinery catalyst formulations compress inventory flexibility and amplify supplier pricing power for incumbent manufacturers serving EPA-regulated hydroprocessing units. This elongated validation cycle concentrates procurement decisions among vertically integrated producers with captive precursor supply, while tiered pricing structures stratify across performance-certified premium grades and commodity metal formulations.
Pricing Analysis
EPA Tier 3 tailpipe standards dictate the pricing tier structure across automotive emission control catalysts, separating platinum-optimized premium formulations from base-metal economy alternatives. Price differentiation rests on PGM loading efficiency and Environment Canada carbon intensity certification tiers. Cost compression in standard-grade zeolite catalysts is intensifying because Chinese-processed rare earth concentrate volatility feeds raw material uncertainty. Merchant refiners in the U.S. Mid-Atlantic exhibit highest price sensitivity due to fragmented procurement scale, while integrated Gulf Coast operators absorb premium pricing for guaranteed supply continuity.
Supply Chain Analysis
Strategic stockpiling of platinum group metals dominates inventory strategy among automotive catalyst formulators facing spot price volatility, while just-in-time zeolite precursor delivery prevails in Gulf Coast petrochemical corridors. Supply concentrates in the United States, Germany, and China for finished catalyst manufacturing, with raw material dependencies spanning South African PGM mining, Chinese rare earth processing, and Canadian bromine extraction. Single-source vulnerability in lanthanide supply chains poses structural risk for zeolite topology production. Distribution runs through direct manufacturer partnerships with integrated refinery operators, bypassing regional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America industrial catalyst market sits in early-cycle expansion as renewable diesel mandates in California and British Columbia accelerate pretreatment catalyst adoption ahead of saturation in conventional refining applications.
For Market Incumbents: Fortify qualification-cycle advantages by embedding technical service teams within U.S. Gulf Coast refinery operations, locking out novel entrants regardless of performance gains. Deepen backward integration into bromine and lithium precursor chains to sustain cost-advantaged hydroprocessing output against BASF's rare earth-anchored position. Prioritize zeolite topology engineering investments to defend proprietary synthesis margins from commodity metal catalyst competition. For New Entrants and Emerging Players: Lead with carbon capture integration opportunities in Louisiana and Alberta blue hydrogen projects, where incumbent qualification histories carry less weight. Target Mexico refinery modernization as the most penetrable geography, where Pemex facility upgrades lack entrenched supplier relationships. Pursue direct partnership models with merchant refiners seeking specification clarity absent in-house catalyst research capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because escalating EPA and Environment Canada sulfur mandates guarantee replacement cycle demand regardless of underlying fuel consumption trends. Acquisition targets should emphasize zeolite manufacturing sites with hydrothermal reactor expertise concentrated among retiring technician cohorts. Watch for divergence in U.S.-Canada carbon intensity accounting methodologies as the inflection signal determining regional catalyst performance threshold misalignment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive bromine and lithium chains enable Albemarle's cost-advantaged hydroprocessing catalyst positioning. |
| Zeolite Topology Engineering Investment | Proprietary microporous frameworks defend margin pools against commodity metal catalyst price volatility. |
| Direct Manufacturer Partnership Consolidation | Eliminates specification interpretation errors for U.S. Mid-Atlantic merchant refiners lacking in-house research. |
| Carbon Capture Catalyst Development | Opens adjacent demand pools in Louisiana and Alberta ammonia and blue hydrogen production projects. |
| Mexico Refinery Modernization Targeting | Pemex facility upgrades present greenfield specification opportunities outside saturated U.S. Gulf Coast markets. |
Research Approach
A standing panel of refinery procurement directors, catalyst plant managers, and hydroprocessing unit engineers provided ongoing calibration across primary interview cycles, supplemented by secondary validation from EPA Mobile Source Air Toxics filings, Environment Canada Clean Fuel Regulation impact assessments, SEC 10-K disclosures from listed chemical conglomerates, and American Chemistry Council sector reports. Bottom-up unit-level demand modeling triangulated against top-down market sizing from trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning product type, application tier, end-user industry, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of historical replacement cycle data and regulatory mandate implementation schedules, incorporating PGM price trajectory assumptions and refinery capacity utilization trends as industry-specific inputs.
Underlying assumptions cover sustained EPA Tier 3 enforcement and Environment Canada carbon intensity reduction trajectories, with deviation risk concentrated in rare earth export quota disruptions and cross-border carbon accounting methodology divergence. Revision becomes warranted when PEMEX modernization timelines accelerate or single-atom platinum dispersion adoption crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Light Powered Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Natural Zeolites Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Rhodium Carbon Catalyst Market