
 Drinking Water Adsorbents Market | 2026-2036
Drinking Water Adsorbents Market Size, Share, and Industry Trends Forecast 2026-2036
Drinking Water Adsorbents Market Analytics
The EPA's finalized maximum contaminant levels for PFAS is realigning procurement criteria across municipal water systems. BASF SE leverages its integrated activated carbon production network to sustain supply security for North American utilities. Calgon Carbon Corporation anchors its position through specialized reactivation services that extend product lifecycle value.
Drinking water adsorbents are porous solid materials engineered with high surface area—typically 500–1,500 square meters per gram for activated carbon—to capture dissolved contaminants through physical adsorption or ion exchange mechanisms, primarily serving municipal and industrial water purification operations. Activated carbon dominates product type revenue due to decades of operational validation and established regeneration infrastructure, while biobased adsorbents represent the fastest-expanding category as agricultural waste feedstocks gain regulatory preference under circular economy frameworks. Municipal water treatment commands the largest application share because centralized infrastructure mandates drive volume procurement, though point of use systems are gaining traction among residential end users seeking decentralized compliance with emerging contaminant standards.
The EPA enforces drinking water standards under the Safe Drinking Water Act, while the EU Drinking Water Directive sets parametric values across member states and ISO 17025 accreditation governs testing laboratory competence for adsorbent performance validation. These frameworks collectively elevate product certification requirements and filter replacement frequencies, directly expanding consumable demand. Stakeholders must monitor regulatory expansion toward emerging contaminants including microplastics and pharmaceutical residues to anticipate next-generation adsorbent specifications.
Market Dynamics
EPA enforcement of maximum contaminant levels for PFAS is restructuring municipal procurement protocols across United States water systems, forcing accelerated capital deployment into advanced adsorbent infrastructure ahead of compliance deadlines.
Growth Catalysts
- EU Drinking Water Directive revisions:Germany's municipal treatment facilities are expanding activated carbon capacity to meet stricter parametric values for emerging contaminants, creating immediate equipment demand.
- Cyclodextrin polymer technology:These engineered materials are capturing PFAS molecules with higher selectivity than conventional granular carbon, driving replacement cycles in remediation applications.
- Point-of-use residential systems:Decentralized compliance demand from homeowners seeking independent certification against emerging standards is expanding the addressable market beyond centralized infrastructure.
Market Restraints
- Coconut shell feedstock volatility:Activated carbon production depends on agricultural waste supply concentrated in Southeast Asian sourcing regions, exposing margins to climate-induced harvest fluctuations.
- Reactivation infrastructure concentration:Specialized thermal regeneration facilities cluster near industrial hubs, limiting service accessibility for remote municipal systems and extending logistics costs.
- Competing membrane filtration:Reverse osmosis systems are displacing adsorbents in certain high-salinity applications where ionic rejection outperforms surface binding.
Strategic Opportunities
- India municipal infrastructure:Central government Jal Jeevan Mission targets universal tap water coverage, creating greenfield demand for adsorbent-integrated treatment plants in underserved districts.
- Pharmaceutical residue remediation:Advanced oxidation-adsorbent hybrid systems address emerging contaminants lacking established maximum contaminant levels, opening premium specification tiers.
- ISO 17025 laboratory accreditation:Testing protocol standardization across certification bodies is elevating performance documentation requirements, favoring suppliers with validated quality systems.
Industry Challenges
- PFAS analytical capability gaps:Municipal utilities lack in-house mass spectrometry expertise to verify adsorbent exhaustion points, complicating replacement scheduling and compliance documentation.
- Legacy system integration:Retrofitting granular activated carbon contactors with advanced polymer media requires hydraulic reconfiguration that many aging treatment plants cannot accommodate without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drinking Water Adsorbents Market |
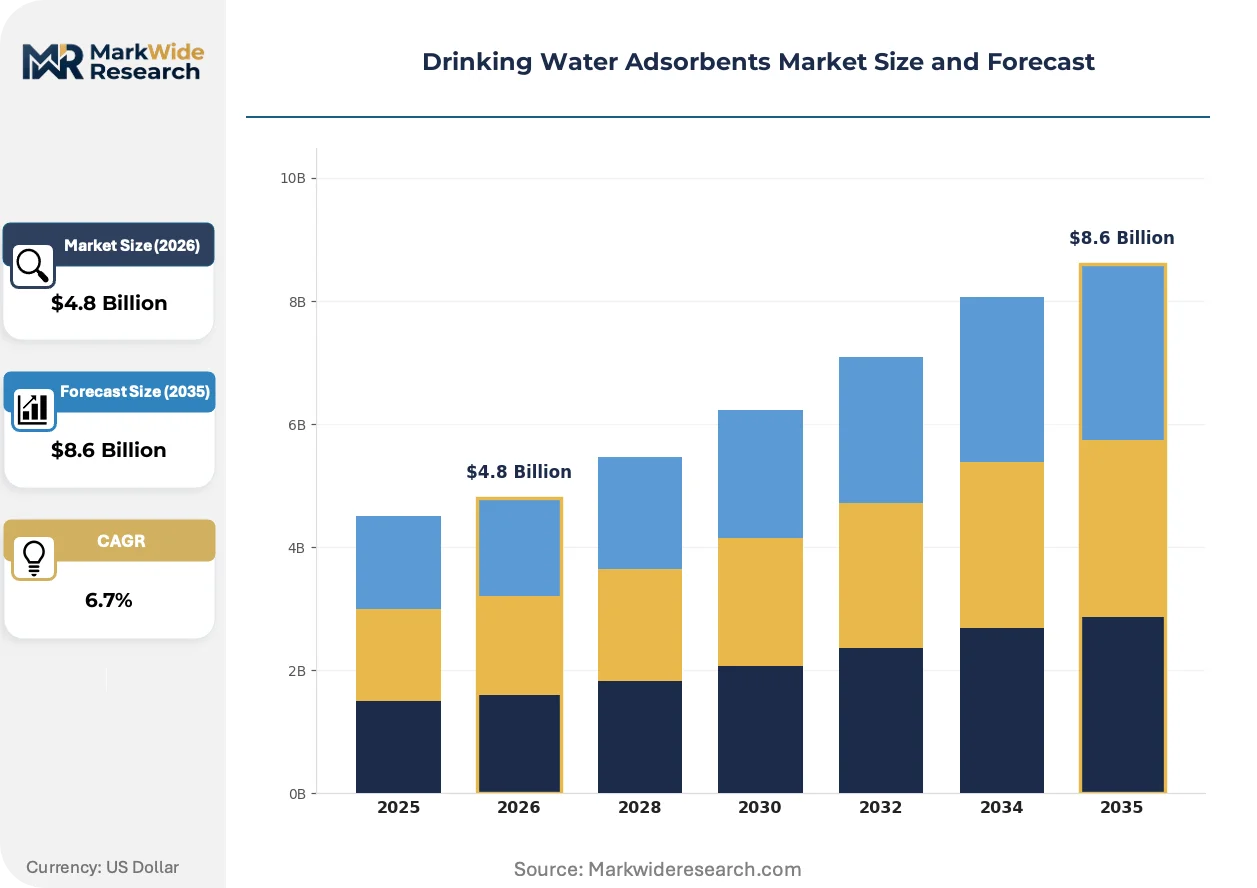
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Ion Exchange Resins, Clay Adsorbents, Biobased Adsorbents Application: Municipal Water Treatment, Industrial Wastewater Treatment, Point of Use Systems, Well Water Filtration End User: Residential Users, Commercial Establishments, Water Treatment Plants, Industrial Facilities Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesale Suppliers |
| Companies Covered | BASF SE, Calgon Carbon Corporation, Cabot Corporation, Purolite Corporation, DuPont de Nemours, Inc., Evoqua Water Technologies LLC, CycloPure Inc., Kuraray Co., Ltd., TIGG LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drinking Water Adsorbents Market Evolving Landscape
Material science advances are compressing the performance gap between established activated carbon and next-generation engineered adsorbents, while regulatory expansion into emerging contaminants is fragmenting certification requirements across jurisdictions.
Metal-organic frameworks are consolidating research attention for their tunable pore geometries that target specific contaminant molecular structures. Defense and aerospace end-users are piloting these materials for trace contaminant removal where selectivity outweighs cost sensitivity. This technology is consolidating the high-performance segment previously served only by specialized ion exchange resins.
REACH authorization procedures for persistent organic pollutants are expanding substance restriction lists faster than adsorbent suppliers can validate replacement chemistries. Industrial wastewater pretreatment facilities in Belgium and the Netherlands are retrofitting multi-stage adsorption trains to intercept restricted compounds before discharge. Activated carbon block filters with impregnated catalytic surfaces are capturing volatile organics that earlier specifications missed.
Specification-driven purchasing is compressing supplier qualification timelines as municipal engineers prioritize pre-certified products over custom development. Engineering-procurement-construction firms are consolidating vendor lists to reduce liability exposure, marginalizing smaller regional carbon reactivators. California and New York procurement offices are mandating third-party validation data before bid consideration, shifting competitive advantage toward laboratories with established ISO 17025 accreditation.
Drinking Water Adsorbents Market Segmentation
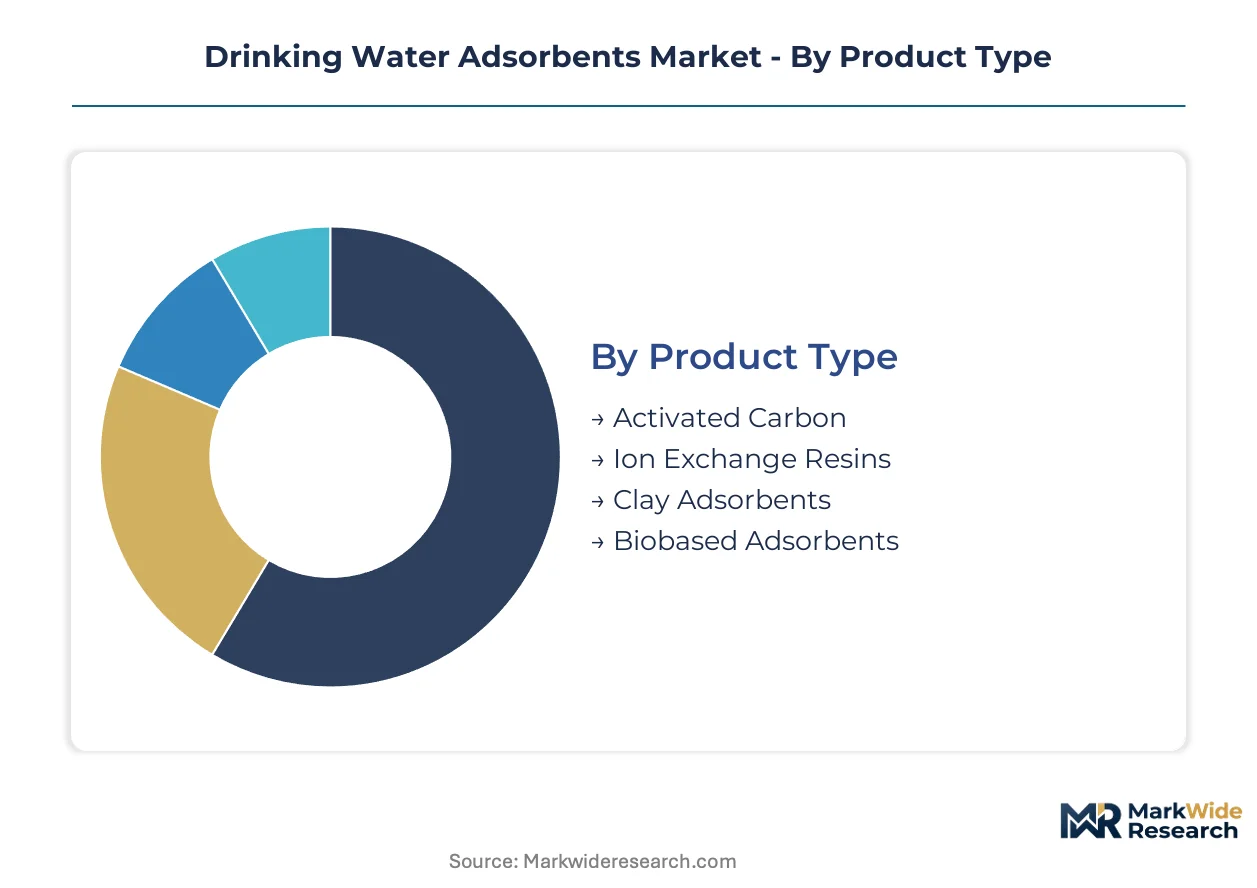
Segmentation in drinking water adsorbents reveals how procurement authority, technical specifications, and regulatory exposure fragment demand across customer types. Buyers prioritize surface area metrics, regeneration economics, or certification speed depending on their operational scale and compliance timelines.
Product Type:
Cost tier separates municipal engineers seeking validated regeneration infrastructure from industrial buyers prioritizing selectivity for emerging contaminants.
- Activated Carbon:Porous carbonaceous material with 500–1,500 square meters per gram surface area dominates procurement volumes due to decades of operational validation and established thermal reactivation services. Demand concentrates in United States municipal systems where EPA enforcement of maximum contaminant levels for PFAS is forcing accelerated infrastructure deployment ahead of compliance deadlines.
- Ion Exchange Resins:Synthetic polymer beads with functionalized active sites enable targeted ionic contaminant removal through reversible exchange mechanisms. Demand concentrates in industrial facilities managing high-salinity process streams where selective ionic rejection outperforms physical adsorption.
- Clay Adsorbents:Naturally occurring aluminosilicate minerals with layered crystalline structures provide low-cost alternatives for regions with limited regeneration infrastructure.
- Biobased Adsorbents:Agricultural waste-derived materials including coconut shell, wood, and fruit pit carbons gain regulatory preference under circular economy frameworks.
Volume sits with Activated Carbon; growth tilts toward Biobased Adsorbents.
Application:
Application scope determines whether buyers need continuous-flow infrastructure or intermittent-use certification.
- Municipal Water Treatment:Centralized filtration infrastructure serving population-scale distribution networks requires high-volume adsorbent procurement with documented regeneration protocols. Germany's municipal facilities are expanding activated carbon capacity to meet stricter EU Drinking Water Directive parametric values for emerging contaminants.
- Point of Use Systems:Residential and small commercial units deliver decentralized compliance through cartridge-based filtration without centralized infrastructure. Demand concentrates in United States homeowner segments seeking independent certification against EPA maximum contaminant level standards.
- Industrial Wastewater Treatment:Process-integrated pretreatment systems intercept regulated compounds before discharge to municipal sewers or surface waters.
- Well Water Filtration:Private groundwater systems serving rural and exurban properties require contaminant-specific remediation without utility connection.
Procurement scale peaks with Municipal Water Treatment; addressable market expansion favors Point of Use Systems.
End User:
End user category maps directly to technical specification authority and replacement frequency economics.
- Water Treatment Plants:Centralized utilities with engineering staff manage multi-year adsorbent contracts tied to regeneration service agreements. India's Jal Jeevan Mission is creating greenfield demand for adsorbent-integrated treatment plants in underserved districts.
- Residential Users:Individual households purchase replacement cartridges through retail channels based on third-party certification labels. California and New York procurement offices are mandating third-party validation data before bid consideration.
- Commercial Establishments:Food service, hospitality, and healthcare facilities balance brand protection with compliance documentation requirements.
- Industrial Facilities:Manufacturing and process industries integrate adsorbent stages into wastewater pretreatment trains.
Contract value concentrates with Water Treatment Plants; replacement frequency runs highest among Residential Users.
Distribution Channel:
Channel selection reflects buyer technical sophistication and volume consolidation.
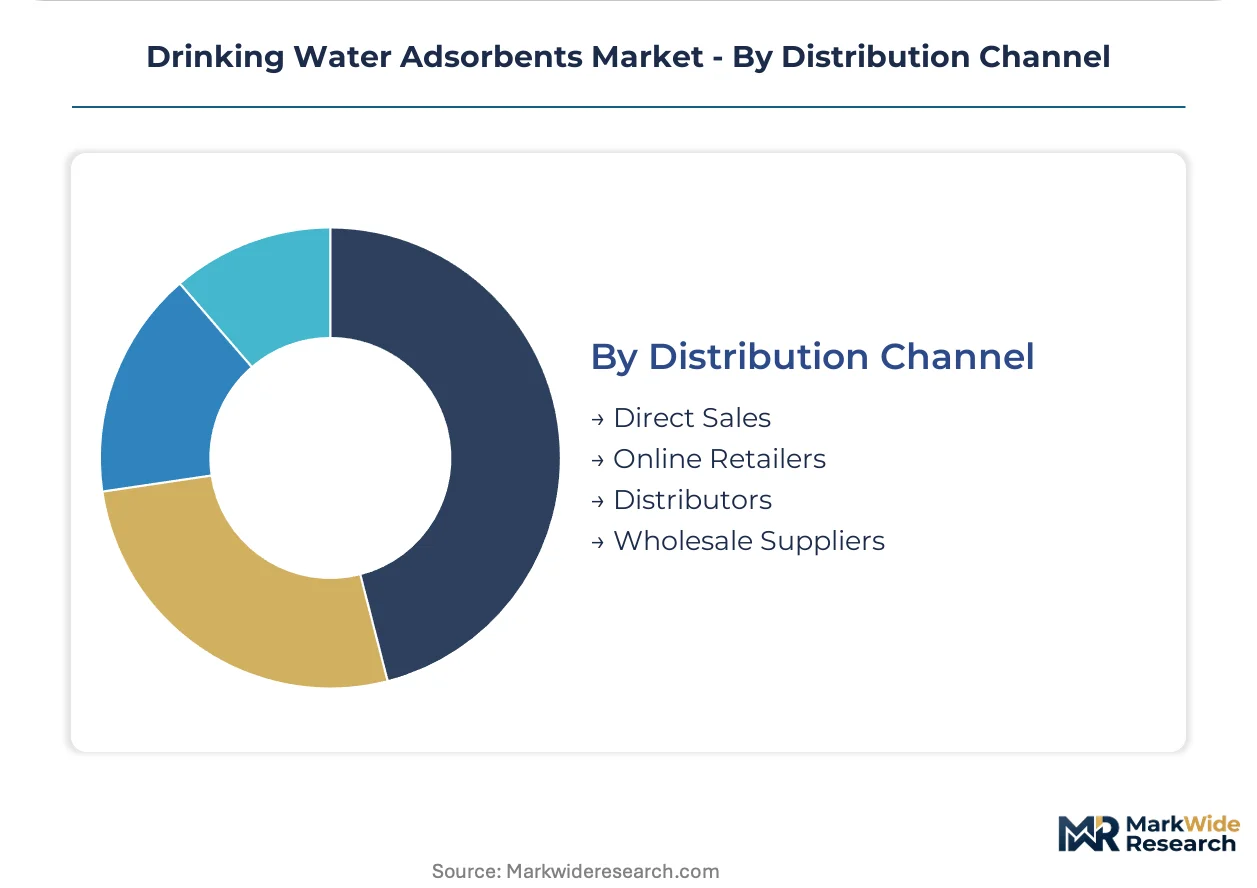
- Distributors:Regional inventory holders with technical sales support serve mid-size municipal and industrial accounts requiring specification guidance.
- Direct Sales:Manufacturer-to-utility relationships dominate large municipal contracts with multi-year service agreements.
- Online Retailers:E-commerce platforms capture residential point-of-use replacement cartridge demand.
- Wholesale Suppliers:Volume aggregators serve contractor and installer networks with limited technical specification involvement.
Relationship intensity peaks with Direct Sales; transaction velocity runs highest through Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Southeast Asia concentrate activated carbon feedstock processing, while European chemical parks integrate adsorbent manufacturing with downstream water treatment engineering services.
United States
EPA enforcement of maximum contaminant levels for PFAS is forcing municipal utilities into accelerated procurement cycles. The Safe Drinking Water Act amendments mandate filtration infrastructure upgrades with documented compliance timelines. Treatment facilities across the Ohio River Valley and Great Lakes states are expanding granular activated carbon contactor capacity ahead of enforcement deadlines.
Germany
Municipal water authorities in North Rhine-Westphalia and Bavaria are retrofitting treatment trains with expanded activated carbon stages. The revised EU Drinking Water Directive sets stricter parametric values for emerging contaminants including pharmaceutical residues. Chemical park clusters along the Rhine corridor integrate adsorbent production with specialized thermal reactivation services.
India
The Jal Jeevan Mission targets universal tap water coverage, creating greenfield demand for adsorbent-integrated treatment plants. Central government funding flows to underserved districts in Maharashtra, Gujarat, and Tamil Nadu. State-level water boards in Karnataka and Telangana are issuing bulk procurement tenders for municipal filtration infrastructure.
China
MEE standards for drinking water quality are tightening enforcement of contaminant limits in municipal distribution systems. Yangtze River Delta municipalities are upgrading centralized treatment capacity with advanced adsorption stages. Pearl River Delta manufacturing clusters are piloting metal-organic framework materials for trace contaminant removal in high-specification applications.
Japan
METI guidance on water infrastructure resilience is driving replacement of aging granular carbon systems in metropolitan treatment plants. JIS standards govern adsorbent performance certification for municipal procurement. Kansai region utilities are integrating point-of-use filtration certification requirements into building code compliance for commercial developments.
Drinking Water Adsorbents Market Competitive Landscape
North American producers anchor one tier; German and Japanese specialists hold differentiated positions in high-selectivity resin segments. The market structure tilts toward consolidation among integrated chemical conglomerates with captive carbon activation capacity, while mid-scale reactivation service providers compete on geographic proximity to municipal accounts. Three archetypes dominate: integrated petrochemical-carbon producers, specialized ion exchange resin manufacturers, and regional reactivation service operators. Capacity expansion and thermal reactivation infrastructure partnerships constitute the dominant competitive moves as utilities prioritize lifecycle cost over upfront capital.
Within the integrated chemical producer tier, BASF SE and Cabot Corporation occupy positions defined by backward integration into feedstock supply and captive regeneration networks. Among specialized technology developers, CycloPure Inc. exemplifies the engineered polymer segment targeting PFAS selectivity premiums. Calgon Carbon Corporation anchors the reactivation-services archetype through established municipal relationships and thermal processing infrastructure.
| Leading Market Players |
|---|
| BASF SE |
| Calgon Carbon Corporation |
| Cabot Corporation |
| Purolite Corporation |
| DuPont de Nemours, Inc. |
| Evoqua Water Technologies LLC |
| CycloPure Inc. |
| Kuraray Co., Ltd. |
| TIGG LLC |
| Others |
Value Network & Pricing Analysis
EU circular economy mandates gate qualified supply and premium-tier pricing access, restricting biobased adsorbent certification to processors with documented agricultural waste traceability while elevating contract values for municipal buyers seeking compliant material streams.
Pricing Analysis
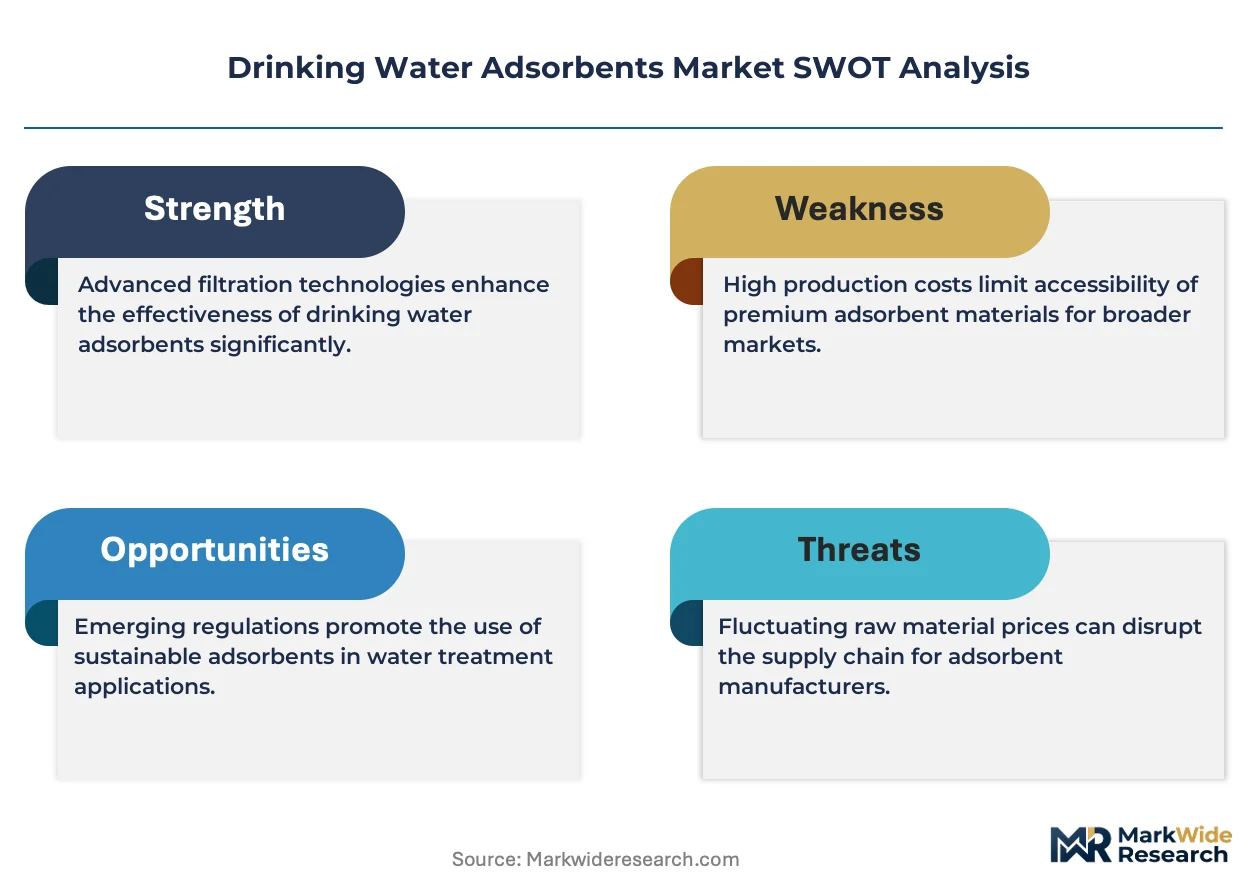
Short lead-time premiums command contract escalation clauses from municipal utilities facing EPA compliance deadlines, while spot inventory of standard-grade activated carbon trades at discounted rates. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified regeneration services from basic thermal reactivation and unvalidated virgin carbon. Pricing pressure stems from coconut shell feedstock volatility in Southeast Asian sourcing regions. Industrial facilities demonstrate highest price sensitivity due to competing membrane filtration alternatives, whereas municipal utilities under regulatory enforcement absorb premium tiers.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan maintain hub-and-spoke patterns to service municipal reactivation contracts with thermal processing infrastructure. Raw material streams draw from Indonesian and Sri Lankan coconut shell harvesting, Appalachian coal activation in North America, and engineered polymer resin production in German chemical parks. Single-source vulnerability concentrates in Southeast Asian agricultural waste supply exposed to climate-induced harvest disruption. Distribution runs through direct manufacturer-to-utility relationships for large contracts, with regional distributors serving mid-tier industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal reactivation infrastructure scarcity props pricing across municipal contracts, constraining supply elasticity as utilities prioritize lifecycle cost over virgin carbon procurement.
For Market Incumbents: Extend reactivation service footprints into underserved Midwestern and Mountain West municipal markets before regional competitors establish thermal processing nodes. Consolidate backward integration into coconut shell feedstock sourcing through long-term offtake agreements with Indonesian processors to defend margin position against agricultural commodity volatility. Cyclodextrin polymer substitution in PFAS remediation represents the most pressing technology threat requiring R&D response. For New Entrants and Emerging Players: Capture India's Jal Jeevan Mission procurement windows in Maharashtra and Gujarat where incumbent thermal reactivation networks remain undeveloped and price competition is muted. Penetrate point-of-use residential segments through e-commerce certification partnerships with California and New York procurement offices mandating third-party validation data. Pursue ISO 17025 laboratory accreditation as the primary go-to-market credential to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: EPA maximum contaminant level enforcement acceleration is the leading indicator that municipal capital deployment into adsorbent infrastructure will sustain above-trend replacement cycles. Position acquisition screening toward regional reactivation service operators with established municipal relationships and underutilized thermal processing capacity. Monitor cyclodextrin polymer cost curves as the inflection signal for engineered adsorbent displacement economics.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Reactivation Capacity Expansion | Secures municipal service contracts in Ohio River Valley compliance zones. |
| Backward Integration into Feedstock Supply | Captures Indonesian coconut shell harvesting networks ahead of climate volatility. |
| ISO 17025 Laboratory Accreditation | Unlocks California and New York municipal bid eligibility requirements. |
| Engineered Polymer R&D Partnership | Addresses PFAS selectivity gaps threatening granular activated carbon displacement. |
| India Distribution Joint Venture | Positions for Jal Jeevan Mission greenfield treatment plant procurement. |
Research Methodology
Trade association filings, customs import records, and municipal procurement databases formed the secondary backbone, supplemented by primary interviews with water treatment plant engineers, activated carbon procurement managers, thermal reactivation facility operators, and regulatory compliance officers. Bottom-up triangulation across product type volumes and top-down validation against end-use expenditure patterns anchored market sizing. The analysis combined documented regeneration service contract values with virgin carbon spot pricing to construct segment-level revenue estimates.
Historical trendline analysis of municipal capital expenditure cycles and regulatory enforcement timelines informed projection modeling across the analysis window. Segmentation dimensions included product type, application scope, end-user category, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for compliance deadline acceleration and infrastructure replacement cycle compression. Forecast inputs incorporated EPA enforcement schedule assumptions and EU Drinking Water Directive revision implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to coconut shell harvest variability, cyclodextrin polymer cost reduction trajectories, and membrane filtration technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Global Wood Activated Carbon Market