
 Global VOC Catalysts Market | 2026-2036
Global VOC Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Global VOC Catalysts Market Foresight
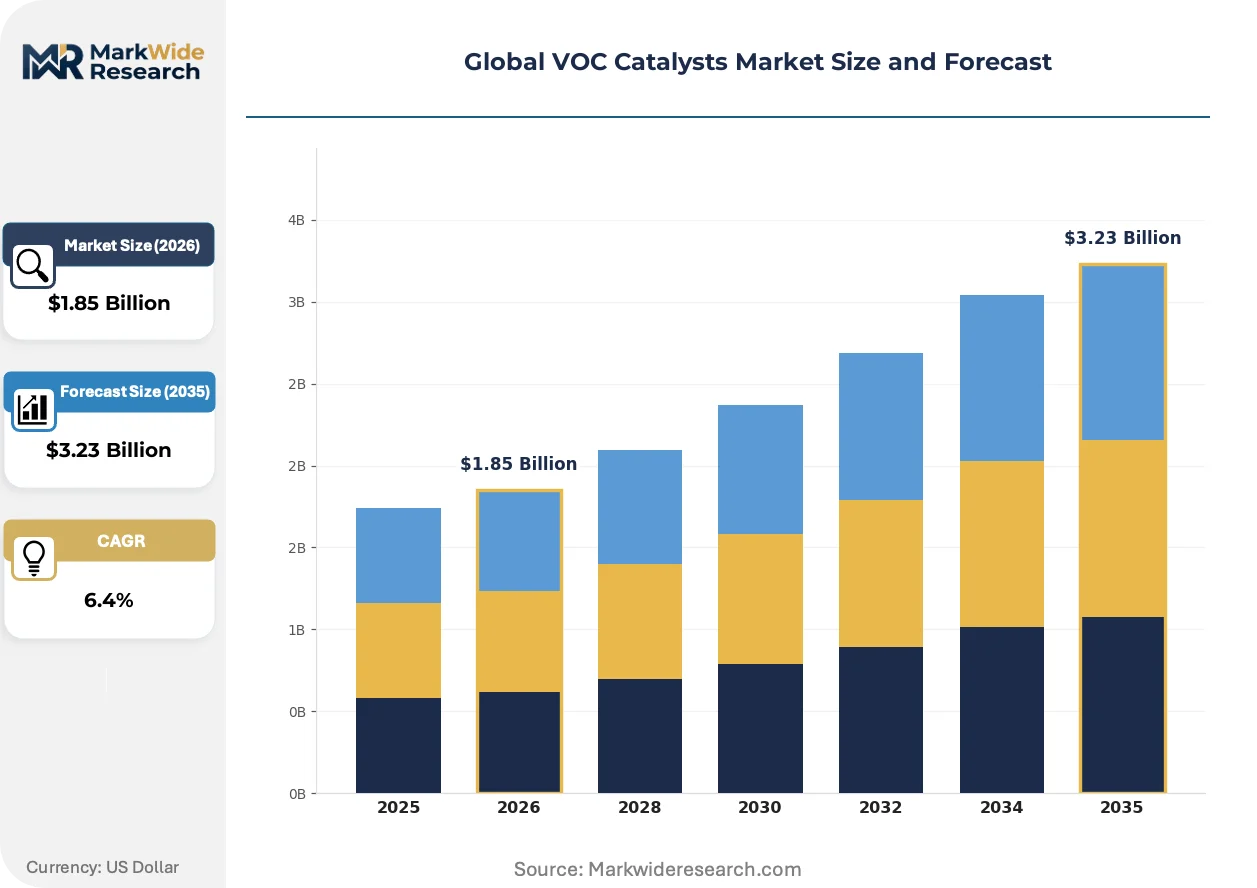
Capital intensity divergence between integrated precious metal refiners and specialty catalyst formulators is bifurcating competitive returns in the Global VOC Catalysts Market. Johnson Matthey leverages captive rhodium and palladium sourcing to sustain margin stability across volatile metal cycles. BASF Catalysts anchors European supply through its Ludwigshafen manufacturing complex, while Clariant Catalysts differentiates via zeolite-based formulations for lower-temperature oxidation.
VOC catalysts are heterogeneous or homogeneous substances that accelerate oxidation reactions to convert volatile organic compounds into carbon dioxide and water, typically operating at temperatures between 150°C and 600°C depending on the active material and contaminant load. Precious metal catalysts command premium positioning in automotive exhaust control where thermal durability and conversion efficiency requirements are most stringent. Zeolite and metal oxide formulations compete aggressively on unit economics in industrial emissions treatment, while fixed bed systems remain the dominant deployment architecture for continuous-process manufacturing plants.
The US EPA enforces Maximum Achievable Control Technology standards that mandate catalytic destruction for specific VOC-emitting source categories, while China's MEE implements dual carbon goals that tighten emission limits across chemical processing clusters. REACH registration requirements in Europe shape product composition and supply chain documentation obligations for catalyst importers. Stakeholders must monitor regulatory calibration in multiple jurisdictions to anticipate reformulation requirements and certification timelines.
Market Dynamics
EU F-Gas Regulation enforcement is compressing deployment timelines for catalytic oxidation systems across chemical processing clusters, forcing facility operators to accelerate capital planning cycles and consolidate vendor relationships ahead of compliance deadlines.
Growth Catalysts
- Dual carbon goals:China's MEE mandates tighten emission limits across petrochemical corridors in Shanghai and Guangdong, pulling forward replacement demand for legacy thermal oxidizers.
- Automotive exhaust standards:NHTSA-aligned state regulations in California and New York sustain premium catalyst consumption for heavy-duty vehicle retrofits.
- Precious metal recovery loops:Closed-loop rhodium and palladium refining from spent automotive catalysts is reducing net new metal demand volatility for formulators.
Market Restraints
- Platinum group metal price volatility:Rhodium spot market swings above fifteen thousand dollars per ounce compress formulator margins on fixed-price supply contracts.
- Zeolite supply concentration:Synthetic zeolite production clusters in Germany and Japan create single-source risk for lower-temperature oxidation formulations.
- REACH registration friction:ECHA substance evaluation timelines extend eighteen to thirty-six months, delaying new catalyst composition launches in European chemical processing.
Strategic Opportunities
- India petrochemical expansion:Reliance Industries and Indian Oil Corporation greenfield projects in Gujarat and Maharashtra lack established catalyst supply relationships, opening vendor entry points.
- Biogas upgrading applications:Siloxane-contaminated landfill gas treatment is emerging as a high-margin niche for precious metal catalysts in waste-to-energy facilities.
- Performance-based service contracts:Guaranteeing conversion efficiency rather than selling catalyst volume aligns vendor incentives with operator opex preferences.
Industry Challenges
- Catalyst characterization expertise:Shortage of specialists capable of correlating surface area degradation with operational parameters slows troubleshooting for process licensors.
- Legacy thermal oxidizer retrofit integration:Existing ductwork configurations and burner placements constrain catalyst bed geometry, forcing custom engineering on sixty percent of replacement projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global VOC Catalysts Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Zeolite, Metal Oxide, Precious Metals, Enzymatic Catalysts Application: Industrial Emissions Treatment, Automotive Exhaust Control, Chemical Processing, Paints & Coatings, Waste Gas Purification End User: Manufacturing Plants, Vehicle OEMs, Chemical Refineries, Commercial Facilities, Research Laboratories Deployment: Fixed Bed Systems, Fluidized Bed Reactors, Monolith Catalysts, Mobile Emission Units, Portable Scrubbers |
| Companies Covered | Clariant Catalysts, TANAKA Precious Metals, BASF Catalysts, Nikki-Universal Co., Ltd., Haldor Topsoe, Johnson Matthey, Cataler Corporation, Dinos Environmental Technology Holdings Ltd., Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global VOC Catalysts Market Shifts & Advancements
Formulation chemistry is pivoting toward lower-temperature activity windows as energy costs reshape operator total cost of ownership calculations, while digital monitoring tools embed into catalyst lifecycle management.
Perovskite-structured mixed metal oxides are displacing conventional platinum-rhodium formulations in select industrial applications where thermal cycling tolerance matters less than material cost stability. Chemical processors in the US Gulf Coast and Rotterdam-Antwerp corridor are piloting these alternatives for steady-state operations. The displacement is compressing premium pricing power for traditional precious metal suppliers in mid-temperature oxidation segments.
REACH authorization requirements for cobalt compounds are forcing reformulation of certain metal oxide catalysts used in paint and coating emissions control. ECHA sunset date pressures are accelerating R&D spending among European formulators ahead of 2026 deadlines. The regulatory compression is favoring integrated chemical companies with in-house toxicology and registration capabilities over import-dependent distributors.
Long-term catalyst leasing arrangements are replacing outright purchase in automotive exhaust aftermarket channels, transferring performance risk from fleet operators to suppliers. BASF and Umicore are structuring contracts covering Detroit and Stuttgart commercial vehicle markets with guaranteed conversion efficiency clauses. The service model shift is most visible in North American Class 8 truck segments where EPA enforcement has tightened idle emission testing protocols.
Global VOC Catalysts Market Segmentation
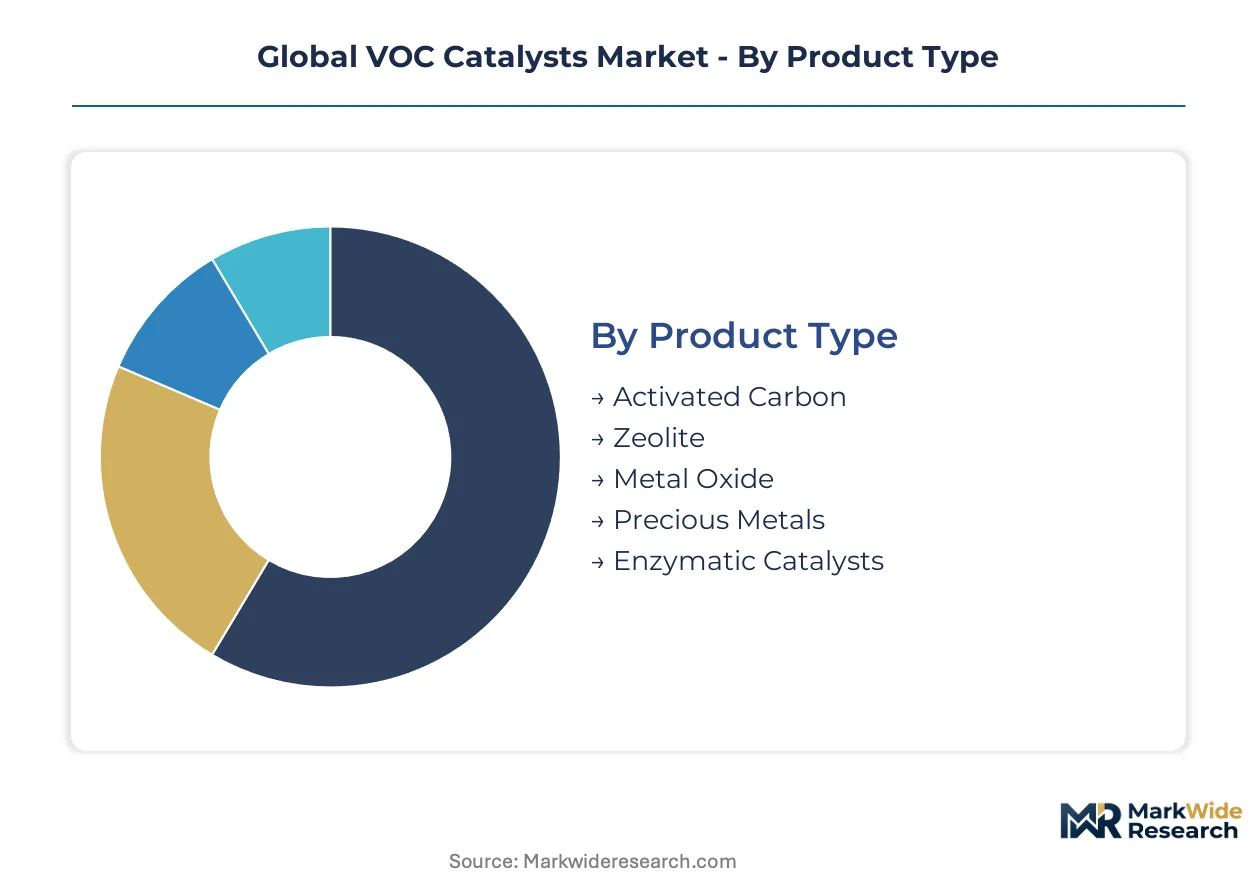
VOC catalyst segmentation reflects divergent regulatory stringency across end-use environments. Product formulations, deployment architectures, and customer procurement patterns fragment along temperature requirements, metal price exposure, and compliance timeline pressures.
Product Type:
EU REACH authorization timelines and cobalt compound sunset dates are forcing reformulation decisions across metal oxide and precious metal categories.
- Precious Metals:Platinum-rhodium-palladium formulations deliver conversion efficiency above 99% in automotive exhaust streams with thermal durability exceeding 800°C. Demand concentrates in Stuttgart and Detroit commercial vehicle corridors where NHTSA-aligned state regulations mandate heavy-duty retrofits. Rhodium spot volatility above fifteen thousand dollars per ounce compresses formulator margins on fixed-price contracts.
- Zeolite:Synthetic aluminosilicate structures enable lower-temperature oxidation windows between 150°C and 350°C, reducing energy opex for continuous-process manufacturers. Chemical processing clusters in Shanghai and Guangdong favor these formulations as China's MEE tightens emission limits under dual carbon goals. Supply concentration in German and Japanese production clusters creates single-source risk for European formulators.
- Metal Oxide:Copper-manganese and cobalt-based compositions compete on material cost stability for steady-state industrial operations.
- Activated Carbon:Adsorption-oxidation hybrid systems serve paint and coating emissions with lower capital thresholds.
- Enzymatic Catalysts:Biological oxidation pathways remain experimental for specialty chemical applications with narrow temperature bands.
Precious metals handle the majority of throughput in automotive channels; zeolite is gaining share fastest in industrial emissions treatment.
Application:
Cost tier differentiation separates continuous-process manufacturing from intermittent-duty automotive and waste gas applications.
- Industrial Emissions Treatment:Petrochemical corridors and refinery complexes deploy fixed-bed precious metal or zeolite systems for high-volume VOC streams. Rotterdam-Antwerp and US Gulf Coast facilities pilot perovskite alternatives to reduce metal price exposure. EU F-Gas Regulation enforcement is compressing deployment timelines across chemical processing clusters.
- Automotive Exhaust Control:Catalytic converters and diesel oxidation catalysts face tightening EPA and CARB certification protocols for NOx and hydrocarbon conversion. Long-term leasing arrangements with guaranteed efficiency clauses are displacing outright purchase in Class 8 truck aftermarket channels.
- Chemical Processing:Reactor vent streams and tank farm vapors require customized catalyst beds for halogenated and oxygenated compound mixtures.
- Paints & Coatings:Solvent recovery and abatement systems for automotive OEM paint shops and industrial coating lines.
- Waste Gas Purification:Landfill biogas and wastewater treatment plant off-gas treatment for siloxane and sulfide contamination.
Industrial emissions treatment carries the highest installed base; automotive exhaust control is expanding most quickly on regulatory pull-through.
End User:
Customer procurement sophistication ranges from integrated chemical majors with captive technical staff to commercial facilities relying on turnkey service contracts.
- Chemical Refineries:Reliance Industries and Indian Oil Corporation greenfield projects in Gujarat and Maharashtra lack established catalyst supply relationships, opening vendor entry points for integrated formulators.
- Vehicle OEMs:Detroit and Stuttgart commercial vehicle manufacturers specify catalyst performance guarantees aligned with EPA and KBA type-approval protocols.
- Manufacturing Plants:Continuous-process operators in chemical, pharmaceutical, and food processing sectors prioritize total cost of ownership over unit catalyst pricing.
- Commercial Facilities:Printing, dry cleaning, and surface coating operations with intermittent duty cycles favor portable or rental scrubber arrangements.
- Research Laboratories:Pilot-scale reactor testing and catalyst characterization services for process licensors and engineering contractors.
Manufacturing plants represent the largest addressable base; chemical refineries show the steepest expansion trajectory on capacity additions.
Deployment:
Volume concentration favors fixed installations, while mobility requirements drive alternative architectures in transportation and emergency response segments.
- Fixed Bed Systems:Granular or pelletized catalyst packed in tubular reactors dominates continuous-process manufacturing with minimal thermal cycling. Legacy thermal oxidizer retrofit integration constraints force custom engineering on sixty percent of replacement projects due to existing ductwork and burner placements.
- Monolith Catalysts:Ceramic honeycomb structures with wash-coated active layers maximize surface area density for automotive exhaust streams with severe space and pressure-drop constraints.
- Fluidized Bed Reactors:Powder catalyst circulation enables superior heat transfer for highly exothermic oxidation reactions in specialty chemical production.
- Mobile Emission Units:Trailer-mounted catalytic oxidizers serve temporary construction, remediation, and event-based emission sources.
- Portable Scrubbers:Compact units for laboratory fume hoods, small coating operations, and emergency spill response with rapid deployment requirements.
Fixed bed systems command the dominant installed capacity; monolith catalysts are climbing the fastest on automotive platform standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in VOC catalysts track precious metal availability and environmental enforcement stringency. Germany and China maintain trade surpluses in formulated catalysts while the United States and India remain net importers of high-performance oxidation systems.
United States
Petrochemical expansions along the Gulf Coast and shale gas processing facilities drive catalyst consumption for vent stream treatment. EPA Maximum Achievable Control Technology standards mandate catalytic destruction for specific source categories. Houston and Port Arthur industrial clusters deploy fixed-bed precious metal systems for refinery off-gas compliance.
Germany
Chemical processing facilities in Ludwigshafen and Leverkusen expand catalytic oxidation capacity ahead of EU F-Gas Regulation deadlines. ECHA REACH registration requirements shape product composition and supply chain documentation for catalyst importers. BASF anchors European supply through its Ludwigshafen manufacturing complex.
China
Industrial clusters around Shanghai and Guangdong pull forward replacement demand for legacy thermal oxidizers under MEE dual carbon goals. Precious metal catalyst formulations capture attention as local environmental enforcement tightens emission limits. Petrochemical corridors in Jiangsu and Zhejiang provinces pilot lower-temperature zeolite systems.
India
Reliance Industries and Indian Oil Corporation greenfield projects in Gujarat and Maharashtra lack established catalyst supply relationships. Central Pollution Control Board mandates tighten across petroleum refining and chemical manufacturing sectors. Jamnagar and Vadodara industrial zones attract vendor entry points for integrated formulators.
Japan
Automotive exhaust catalyst demand sustains through Tokyo and Nagoya manufacturing corridors despite domestic vehicle production shifts. METI-aligned industrial standards emphasize conversion efficiency benchmarks for chemical processing applications. Osaka-based synthetic zeolite production clusters supply regional formulators with lower-temperature oxidation materials.
Global VOC Catalysts Market Competitive Landscape
Concentration sits with integrated precious metal refiners and diversified chemical conglomerates that control upstream material flows. Johnson Matthey and Umicore leverage captive rhodium and palladium sourcing to sustain margin stability across volatile metal cycles. Three archetypes dominate: vertically integrated precious metal specialists, diversified chemical majors with catalyst divisions, and regional formulators serving single-country demand. Competitive moves center on backward integration into metal recovery loops and long-term performance-based service contracts that transfer operational risk from end users.
Among European-anchored diversified players, BASF Catalysts and Clariant Catalysts exemplify contrasting formulation strategies. BASF occupies a position tied to Ludwigshafen-scale chemical manufacturing infrastructure. Clariant represents the specialty formulator archetype emphasizing zeolite-based compositions. Johnson Matthey anchors the precious metal recovery and refining tier with London-originated operations. These three companies illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| Clariant Catalysts |
| TANAKA Precious Metals |
| BASF Catalysts |
| Nikki-Universal Co., Ltd. |
| Haldor Topsoe |
| Johnson Matthey |
| Cataler Corporation |
| Dinos Environmental Technology Holdings Ltd. |
| Umicore |
| Others |
Supply & Pricing Matrix
EU REACH authorization timelines gate both supplier qualification and price differentiation simultaneously, forcing formulators to absorb extended ECHA substance evaluation periods while tiering offerings by registration completeness. Buyers with captive toxicology capabilities command premium positioning against import-dependent distributors facing documentation gaps.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across precious metal, zeolite, and metal oxide formulations. Price differentiation rests on certification grade under EPA MACT standards and volume scale commitments from petrochemical corridor operators. Cost compression in zeolite tiers is intensifying because synthetic aluminosilicate supply concentrates in German and Japanese production clusters. Commercial facilities with intermittent duty cycles exhibit highest price sensitivity; integrated chemical majors with captive technical staff demonstrate lowest sensitivity due to performance guarantee requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites rhodium and palladium flows from South African refiners to Chinese formulators around Shanghai and Guangdong. Supply concentration clusters in Germany for synthetic zeolite production, Japan for ceramic honeycomb substrates, and South Africa for platinum group metal mining. Raw material dependencies span rhodium sponge, palladium chloride, and synthetic mordenite zeolite. Single-source vulnerability in German zeolite production creates formulator exposure. Distribution runs through integrated precious metal refiners with captive recovery loops and regional specialty catalyst distributors serving single-country demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where ECHA REACH registration requirements and EPA MACT certification protocols create switching costs that cement incumbent positions. Network effects concentrate among integrated formulators with backward metal recovery capabilities.
For Market Incumbents: Secure captive rhodium and palladium sourcing through closed-loop refining partnerships to defend against perovskite displacement in mid-temperature oxidation segments. Extend performance-based service contracts with guaranteed conversion efficiency clauses to lock in chemical processing corridor operators ahead of EU F-Gas Regulation deadlines. Capacity addition in Gujarat and Maharashtra addresses Reliance Industries and Indian Oil Corporation greenfield demand before vendor relationships crystallize.
For New Entrants and Emerging Players: Differentiate on lower-temperature zeolite formulations for China's MEE-mandated petrochemical retrofits in Jiangsu and Zhejiang provinces where established relationships remain thin. Target siloxane-contaminated biogas upgrading applications in waste-to-energy facilities as a high-margin niche with limited incumbent focus. Pursue direct technical service partnerships with process licensors lacking catalyst characterization expertise.
For Investors and Strategic Acquirers: ECHA cobalt compound sunset dates reshape the acquisition landscape toward integrated chemical companies with in-house toxicology and registration capabilities. Long-term viability over a five-to-ten year window favors formulators with precious metal recovery infrastructure and European manufacturing footprints. Monitor perovskite pilot adoption rates in US Gulf Coast and Rotterdam-Antwerp facilities as the critical signal for displacement risk in industrial emissions treatment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Recovery | Johnson Matthey and Umicore sustain margin stability across rhodium spot volatility cycles. |
| Long-term Performance-Based Service Contracts | BASF structures guaranteed efficiency clauses with Detroit and Stuttgart commercial vehicle fleet operators. |
| Lower-Temperature Zeolite Formulation Development | Clariant targets 150°C to 350°C oxidation windows for Shanghai and Guangdong chemical processors. |
| Geographic Expansion into Indian Petrochemical Corridors | Greenfield projects in Gujarat and Maharashtra lack established catalyst supply relationships. |
| REACH Registration Investment Ahead of Sunset Dates | European formulators accelerate R&D spending to maintain market access under ECHA authorization timelines. |
Research Methodology
A spread of perspectives from plant managers at chemical processing facilities, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA enforcement databases. Bottom-up catalyst volume estimates triangulated against top-down market value assessments.
Segmentation dimensions modeled span product type across precious metal, zeolite, metal oxide, and alternative formulations; application across industrial emissions treatment, automotive exhaust control, and chemical processing; end user category from integrated refineries to commercial facilities; and deployment architecture from fixed bed to monolith systems. CAGRs derived from regression analysis against regulatory enforcement intensity and capacity addition pipelines. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and China's MEE dual carbon goal implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement stringency or precious metal price stability assumptions would require recalibration. Forecasts reflect documented assumptions about ECHA authorization timelines, EPA MACT standard expansion scope, and perovskite formulation technical maturation. Practitioners should keep alternative scenarios live as cobalt compound substitution rates and biogas upgrading market development evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
North America Industrial Catalyst Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Hydro-Processing Catalysts Market
Catalysts
Industrial Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Natural Zeolites Market
Catalysts
Precious Metal Catalysts Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Catalyst Handling Services Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
Refining Catalysts Market
Catalysts
Copper Bismuth Catalyst Market