
 Catalyst Regeneration Market | 2026-2036
Catalyst Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Catalyst Regeneration Market Analysis
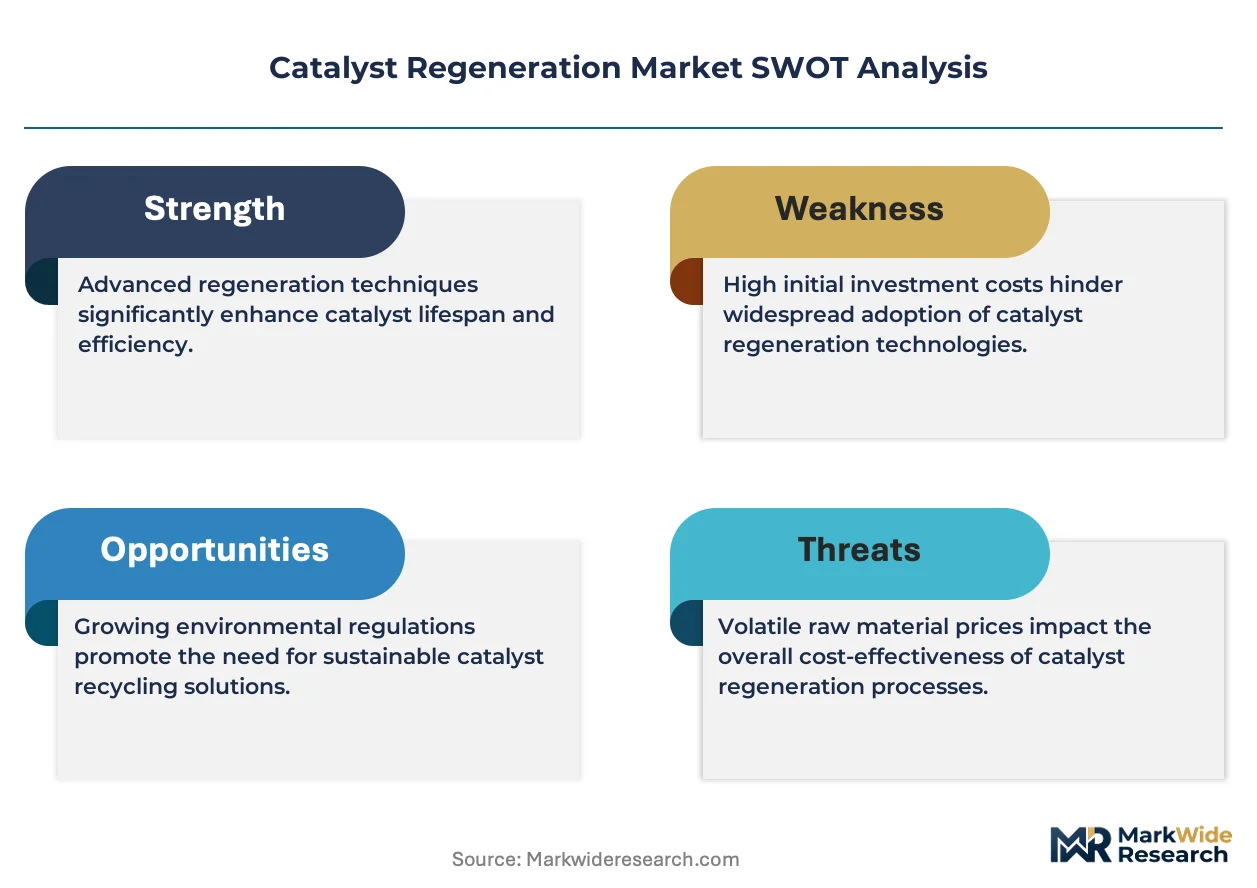
The split between premium regeneration services and commodity reactivation is shifting as refiners demand higher recovery rates for platinum-group metals. Albemarle Corporation leverages its integrated catalyst manufacturing and regeneration network to capture full-lifecycle value from major petrochemical clients. Eurecat sustains leadership through specialized hydroprocessing catalyst recovery capabilities across European and Middle Eastern installations. Porocel competes aggressively on turnaround speed, positioning its mobile regeneration units as alternatives to fixed-site competitors.
Catalyst regeneration encompasses the restoration of spent catalytic materials through controlled thermal oxidation, chemical washing, or oxidative redispersion to recover active surface area and selective poisoning resistance. Thermal regeneration typically operates between 450°C and 550°C in controlled-oxygen environments to combust carbon and sulfur deposits without sintering the active metal crystallites, returning materials to refinery specifications for hydrocracking and hydrotreating duty. Chemical regeneration leads in revenue contribution due to its effectiveness with zeolite-based fluid catalytic cracking catalysts and its compatibility with precious-metal recovery protocols. Biological regeneration represents the fastest-expanding technology category as enzyme-based approaches gain traction for environmental remediation catalysts where thermal methods destroy microbial active sites.
EPA emission standards under the Clean Air Act and EU REACH chemical registration requirements directly shape regeneration demand by elevating the cost of fresh catalyst procurement and spent catalyst disposal. OSHA process safety management rules and ISO 14001 environmental management frameworks further dictate operational standards for regeneration facility permitting and hazardous material handling. Stakeholders must monitor regulatory tightening around spent catalyst classification, as reclassification from non-hazardous to hazardous waste streams would restructure regeneration economics and facility location decisions.
Market Dynamics
Refinery operators face mounting pressure to extend catalyst life cycles as EPA emission standards under the Clean Air Act and EU REACH chemical registration requirements elevate fresh catalyst procurement costs. Thermal and chemical regeneration technologies now compete directly with new material purchases across hydrocracking and hydrotreating applications.
Growth Catalysts
- REACH compliance costs:EU chemical registration requirements compel petrochemical operators to regenerate spent catalysts rather than classify them as hazardous waste streams, extending service contract durations.
- Platinum-group metal recovery:Precious-metal reclamation protocols integrated into chemical regeneration processes recover iridium and ruthenium from spent hydroprocessing catalysts at rates exceeding thermal methods.
- Gulf Coast refining cluster:Concentrated petrochemical capacity along the United States Gulf Coast generates regeneration volumes sufficient to support dedicated mobile service units and fixed-site facilities.
Market Restraints
- Natural gas price volatility:Thermal regeneration operations consuming 450-550°C controlled-oxygen environments face margin compression when feedstock energy costs spike.
- Zeolite sintering limitations:Repeated thermal cycling degrades fluid catalytic cracking catalyst pore structures, capping regeneration cycles at 3-5 turns before permanent deactivation.
- Spent catalyst reclassification risk:EPA hazardous waste designation shifts would impose manifest-tracking and disposal fees restructuring facility economics.
Strategic Opportunities
- Biological regeneration protocols:Enzyme-based restoration methods for environmental remediation catalysts avoid thermal destruction of microbial active sites, opening service contracts in soil and groundwater treatment.
- Mobile unit deployment:Transportable regeneration systems eliminate shipping costs and turnaround delays for remote refinery locations lacking fixed-site infrastructure.
- ISO 14001 certification premiums:Environmental management framework compliance enables pricing differentiation against non-certified competitors in European tender processes.
Industry Challenges
- Process safety management compliance:OSHA rules mandate specialized training for thermal oxidation facility operators, constraining workforce availability and extending hiring timelines.
- Legacy catalyst inventory integration:Decades of accumulated spent material with undocumented composition histories complicate batch processing and quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catalyst Regeneration Market |
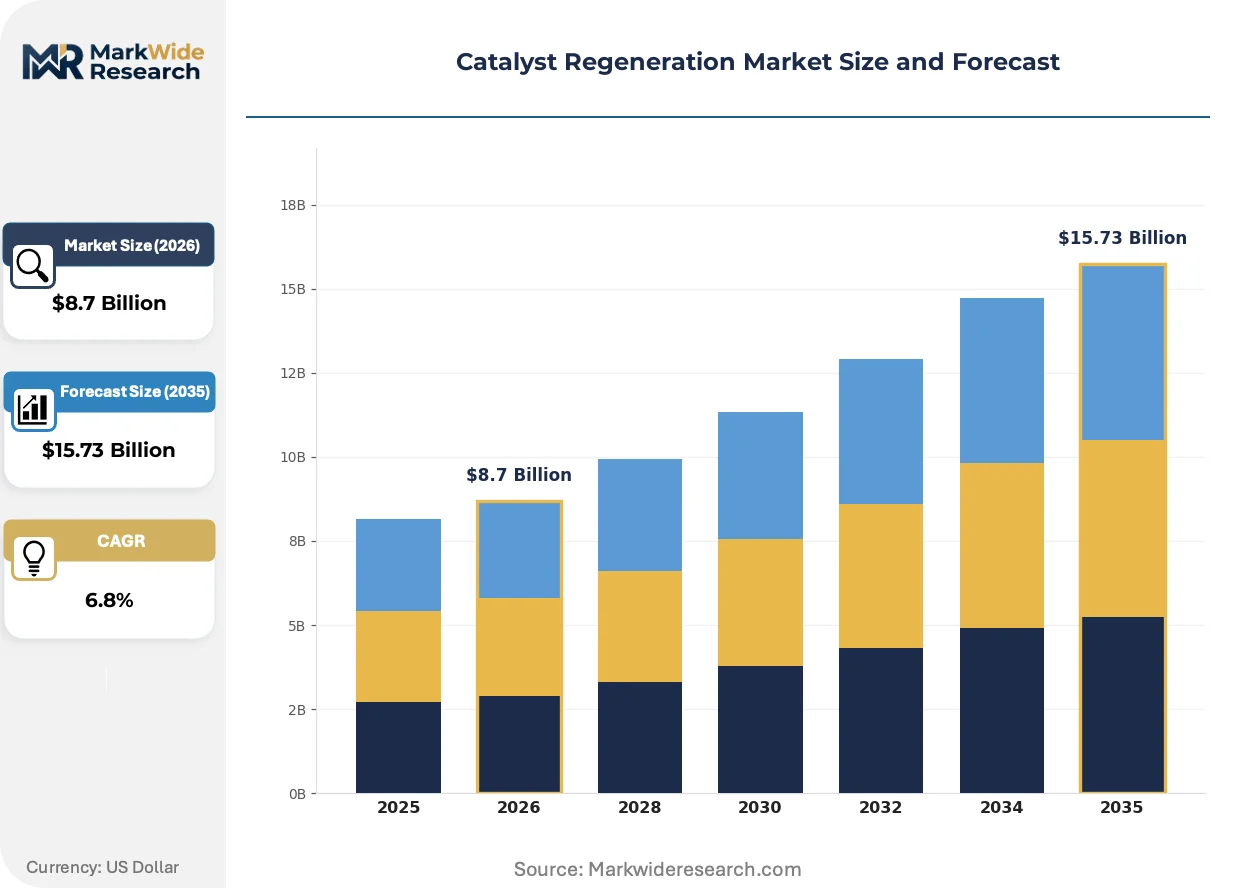
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal, Chemical, Biological, Electrochemical Application: Petrochemical, Automotive, Industrial, Environmental End User: Refineries, Chemical Plants, Power Generation, Waste Management Process Type: Reactivation, Replacement, Reactive Maintenance, Cleaning |
| Companies Covered | Eurecat, Albemarle Corporation, Porocel, BASF, Johnson Matthey, Axens, Nippon Ketjen, Haldor Topsoe, STEAG Energy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catalyst Regeneration Market Emerging Trajectories
Service providers are restructuring regeneration delivery models around speed and proximity rather than centralized processing capacity. Technology investments now prioritize portable systems and biological methods that bypass thermal limitations.
Mobile thermal regeneration units mounted on trailer systems are decentralizing service delivery across the refining sector. Mid-sized independent refiners lacking on-site regeneration infrastructure adopt these units for 48-hour turnaround cycles. Fixed-site competitors face pricing pressure as transportation costs and catalyst inventory carrying charges compress.
EU REACH chemical registration requirements are tightening spent catalyst cross-border movement documentation. Operators must now demonstrate regeneration facility environmental permits match origin-country classification standards. German and Dutch refiners increasingly specify pre-approved service providers to avoid customs delays.
Refinery procurement departments now unbundle catalyst supply from regeneration services, issuing separate tenders for each lifecycle stage. Integrated manufacturers face margin pressure as specialized regenerators win standalone contracts. This pattern concentrates in the United States Gulf Coast corridor where multiple service providers compete for discrete process unit assignments.
Catalyst Regeneration Market Segmentation
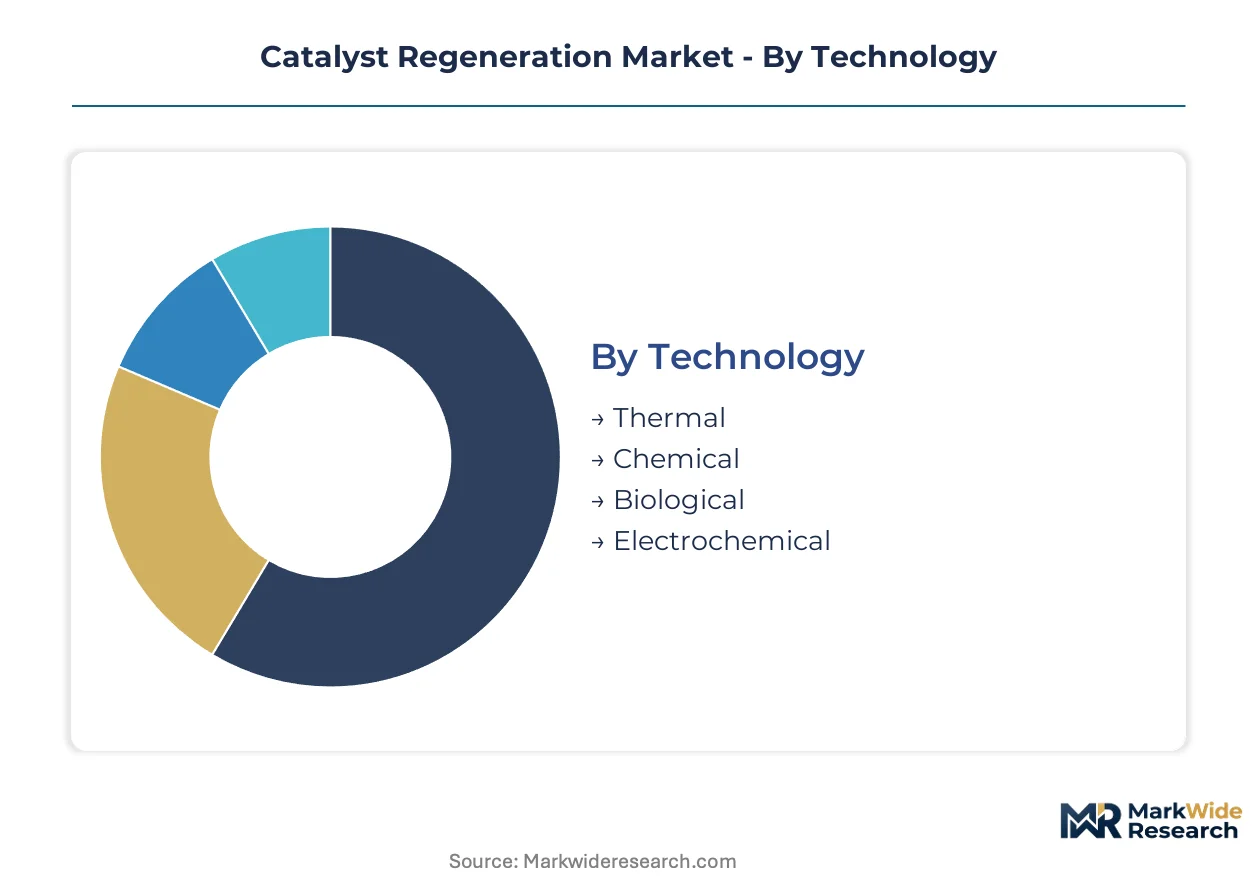
Catalyst regeneration service providers structure offerings around technology intensity and operational constraints. Segment boundaries determine facility investment requirements, permitting complexity, and contract pricing structures across the value chain.
Technology:
Capital deployment varies sharply across regeneration methods, with thermal systems demanding the heaviest fixed-asset investment.
- Thermal:Controlled-oxygen combustion at 450-550°C removes carbon and sulfur deposits from hydroprocessing catalysts. Gulf Coast refineries favor this method for platinum-group metal recovery, though natural gas price spikes compress service margins during energy market volatility.
- Chemical:Acid washing and oxidative redispersion restore zeolite structures in fluid catalytic cracking catalysts. EU REACH compliance costs push petrochemical operators toward chemical protocols that minimize hazardous waste classification risks.
- Biological:Enzyme-based restoration preserves microbial active sites in environmental remediation catalysts.
- Electrochemical:Electrodeposition methods recover precious metals from spent catalyst slurries.
Thermal regeneration absorbs the bulk of installed capacity; biological methods are expanding most quickly.
Application:
Service intensity tracks directly with catalyst replacement frequency and regulatory scrutiny in each sector.
- Petrochemical:Hydrotreating and hydrocracking units in refineries generate the largest regeneration volumes. EPA Clean Air Act standards compel operators to extend catalyst life cycles rather than procure fresh material.
- Automotive:Catalytic converter recycling for platinum, palladium, and rhodium recovery operates at smaller scale but commands premium pricing.
- Industrial:Ammonia synthesis and methanol production catalysts require periodic oxidative treatment.
- Environmental:Soil and groundwater remediation catalysts favor biological regeneration to preserve biocatalytic activity.
Petrochemical applications dominate current service contracts; environmental applications are climbing the fastest.
End User:
Procurement sophistication and contract scale diverge significantly across buyer categories.
- Refineries:Integrated operators unbundle catalyst supply from regeneration services, issuing separate tenders for each lifecycle stage. United States Gulf Coast clusters support dedicated mobile regeneration units.
- Chemical Plants:Specialty chemical producers favor fixed-site regeneration partners with ISO 14001 certification for European tender compliance.
- Power Generation:Selective catalytic reduction catalysts for flue gas denitrification require periodic thermal reactivation.
- Waste Management:Hazardous waste treatment facilities process spent catalysts under EPA manifest-tracking requirements.
Refineries command the largest contract values; waste management end users are gaining share fastest.
Process Type:
Operational integration with client maintenance schedules determines competitive positioning in each service category.
- Reactivation:Full restoration of catalytic activity through thermal or chemical treatment returns materials to original specifications. Turnaround speed differentiates mobile unit providers from fixed-site competitors.
- Replacement:Swap-out services for permanently deactivated catalysts focus on logistics coordination and precious-metal credit reconciliation.
- Reactive Maintenance:Emergency regeneration during unplanned shutdowns commands premium pricing.
- Cleaning:Surface deposit removal without full activity restoration serves as preventive maintenance.
Reactivation services absorb the bulk of facility throughput; reactive maintenance commands the steepest pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast petrochemical corridor generates the highest concentration of catalyst regeneration volumes globally, with clustered refining infrastructure supporting dedicated mobile service units and fixed-site facilities.
United States
EPA Clean Air Act standards compel refinery operators to extend hydroprocessing catalyst life cycles rather than procure fresh material. OSHA process safety management rules mandate specialized training for thermal oxidation facility operators, constraining workforce availability. The Texas-Louisiana Gulf Coast corridor hosts the densest concentration of regeneration demand, with multiple service providers competing for discrete process unit assignments.
Germany
EU REACH chemical registration requirements elevate the cost of fresh catalyst procurement and spent catalyst disposal for petrochemical operators. German and Dutch refiners increasingly specify pre-approved service providers to avoid customs delays from tightened cross-border movement documentation. The Rhine-Ruhr industrial region concentrates regeneration contract awards among ISO 14001-certified facilities.
Netherlands
Rotterdam's port infrastructure facilitates spent catalyst import-export logistics for European regeneration networks. ECHA compliance protocols require regeneration facility environmental permits to match origin-country classification standards. The Port of Rotterdam chemical cluster anchors service demand for zeolite-based fluid catalytic cracking catalyst recovery.
China
Dual carbon goals under MEE directives accelerate refinery demand for catalyst life extension services. GB standards for hazardous waste classification shape spent catalyst handling protocols across petrochemical provinces. The Yangtze River Delta refining corridor generates concentrated regeneration volumes for hydrocracking and hydrotreating applications.
Saudi Arabia
Strategic petroleum reserve operations and downstream expansion drive hydrotreating catalyst regeneration demand. The country's national environmental regulator imposes emissions protocols that favor life-cycle extension over fresh material procurement. The Eastern Province industrial city cluster supports dedicated service contracts for platinum-group metal recovery operations.
Catalyst Regeneration Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the catalyst regeneration sector, with fixed-site thermal facilities requiring substantial furnace and emissions-control investment while mobile unit operators minimize asset exposure. The vendor base stratifies into three tiers: integrated catalyst manufacturers with captive regeneration networks, specialized third-party service providers with technology-specific expertise, and regional operators competing on turnaround speed. Consolidation pressure intensifies as refinery procurement departments unbundle catalyst supply from regeneration services. Dominant competitive moves include geographic expansion of mobile unit fleets and backward integration into precious-metal reclamation capabilities.
Within the integrated manufacturer tier, Albemarle Corporation and BASF exemplify full-lifecycle value capture from major petrochemical clients. Eurecat occupies a position among specialized third-party providers with hydroprocessing catalyst recovery capabilities across European and Middle Eastern installations. Porocel anchors the speed-focused segment, with its mobile regeneration units representing alternatives to fixed-site competitors for mid-sized independent refiners.
| Leading Market Players |
|---|
| Eurecat |
| Albemarle Corporation |
| Porocel |
| BASF |
| Johnson Matthey |
| Axens |
| Nippon Ketjen |
| Haldor Topsoe |
| STEAG Energy Services |
| Others |
Supply Flow & Price Mechanics
Specialized thermal oxidation technicians concentrated along the Texas-Louisiana Gulf Coast command wage premiums that directly expand spreads between premium certified regeneration services and commodity reactivation tiers. Labor-cost differentials between fixed-site facilities with OSHA process safety management compliance and mobile unit operators reshape how refiners segment procurement across turnaround speed and recovery rate specifications.
Pricing Analysis
Value-based pricing anchored to platinum-group metal recovery rates dominates contract structures for hydroprocessing catalyst regeneration. Pricing stratifies across ISO 14001-certified premium tiers, standard fixed-site thermal processing, and economy mobile unit services based on turnaround guarantees and precious-metal credit reconciliation terms. Cost compression in the standard tier intensifies because natural gas price volatility erodes margins for thermal operators running 450-550°C oxidation cycles. Independent refiners with unbundled procurement show highest price sensitivity; integrated majors prioritize recovery rate performance over unit cost.
Supply Chain Analysis
ISO 14001 and EPA permitting qualifications gate facility participation in European and United States tender processes, concentrating active supply among pre-certified operators. Geographic supply concentrates in the United States, Germany, and the Netherlands, where Gulf Coast refining clusters and Rotterdam port infrastructure anchor regeneration networks. Raw material dependencies span natural gas for thermal oxidation, acid chemistries for zeolite restoration, and enzyme formulations for biological protocols. Single-source vulnerability runs through specialized platinum-group metal reclamation capabilities. Distribution feeds from fixed-site hubs and mobile trailer-mounted units directly to refinery turnaround schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where refinery procurement unbundling pressures smaller operators lacking precious-metal recovery capabilities or ISO certification credentials.
For Market Incumbents: Deepen backward integration into platinum-group metal reclamation to capture full-lifecycle value from hydroprocessing catalyst contracts. Expand mobile unit fleet deployment across mid-sized independent refiners to defend against speed-focused competitors. Eurecat's European network demonstrates how geographic density in hydroprocessing recovery creates switching costs. For New Entrants and Emerging Players: EU REACH compliance costs in Germany and the Netherlands open a window for specialized chemical regeneration services targeting zeolite-based fluid catalytic cracking catalysts. Environmental remediation catalysts represent the most penetrable segment, where biological regeneration protocols bypass established thermal incumbents. A go-to-market angle centered on enzyme-based restoration for soil and groundwater treatment operators avoids direct confrontation with fixed-site giants. For Investors and Strategic Acquirers: The window for entry favors asset-light mobile unit operators with established refinery relationships over capital-intensive thermal facility builders. Acquisition targets should display demonstrated turnaround speed capabilities and pre-negotiated precious-metal offtake agreements. Watch for EPA spent catalyst reclassification proposals as the critical inflection signal that would restructure regeneration economics toward hazardous waste handling specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Unit Fleet Expansion | Turnaround speed capabilities capture mid-sized refinery contracts from fixed-site competitors. |
| Backward Integration into Precious-Metal Recovery | In-house platinum-group metal reclamation secures margin capture across catalyst lifecycle stages. |
| ISO 14001 Certification Investment | Environmental management compliance enables European tender participation against uncertified rivals. |
| Biological Regeneration Capability Buildout | Enzyme-based protocols open environmental remediation contracts where thermal methods destroy activity. |
| Long-Term Service Agreement Structuring | Multi-year regeneration contracts with precious-metal credit terms lock in refinery customer relationships. |
Methodological Framework
Document review covered EPA enforcement actions, EU ECHA registration databases, and refinery catalyst procurement disclosures, complemented by interviews with thermal facility operations managers, petrochemical procurement directors, and precious-metal reclamation specialists. Secondary validation drew from OSHA process safety management incident reports, SEC filings of integrated catalyst manufacturers, and customs trade data for spent catalyst cross-border movements. Bottom-up regeneration volume estimates triangulated against top-down petrochemical capacity utilization models.
Historical regeneration contract pricing was cross-referenced against expert panel assessments of technology adoption trajectories across the projection horizon. Segmentation dimensions modeled include regeneration technology type, application sector, end-user category, and process service tier. CAGRs were derived from regression analysis of refinery catalyst replacement frequency against regulatory compliance cost indices. Forecast inputs incorporated natural gas price volatility assumptions and EPA hazardous waste classification risk scenarios.
The model assumes a particular technology adoption path; alternative pathways for biological regeneration would alter the outlook if enzyme-based methods achieve scale in petrochemical applications beyond environmental remediation. Forecasts reflect assumptions about REACH enforcement continuity and OSHA workforce availability constraints. A model refresh is warranted upon material change in EPA spent catalyst classification standards or EU cross-border movement documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Catalase Market
Catalysts
Polymer Catalyst Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Europe Refining Catalysts Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Global Zeolites Market
Catalysts
Global Catalyst Market
Catalysts
North America Industrial Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Biodiesel Catalyst Market