
 Mycotoxin Binders Market | 2026-2036
Mycotoxin Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Mycotoxin Binders Market Outlook
Commercial aquaculture operations is collapsing as the fastest-growing buyer archetype for mycotoxin binders, overtaking traditional livestock procurement patterns. BASF SE leverages its bentonite mining assets to anchor supply security across Southeast Asian shrimp feed markets. Kemin Industries Inc. differentiates through R&D intensity in modified glucomannan formulations for aflatoxin specificity. Cargill Incorporated controls integrated feed-to-protein channels that embed binder specifications directly into grower contracts.
Mycotoxin binders are adsorbent or biotransforming agents, typically composed of aluminosilicate clays, yeast cell wall derivatives, or enzymatic preparations, designed to sequester or degrade fungal metabolites in feed matrices and prevent their absorption in the gastrointestinal tract of animals. Bentonite dominates product type revenue due to its low cost and established efficacy against aflatoxins in poultry and ruminant diets, though activated charcoal commands premium positioning in pet and pharmaceutical applications where broad-spectrum mycotoxin coverage justifies higher inclusion costs. Powder formulations lead volume shipments for feed mill integration, while liquid binders are gaining fastest in aquaculture systems requiring homogeneous distribution in extruded feeds.
The FDA Center for Veterinary Medicine enforces mycotoxin action levels that directly dictate binder inclusion rates in US export-oriented feed operations, while the EU Feed Hygiene Regulation and EFSA mycotoxin opinions set binding maximum levels that reshape formulation standards for suppliers accessing European livestock markets. Brazil's Ministry of Agriculture and China's Ministry of Agriculture and Rural Affairs maintain parallel residue monitoring programs that create divergent compliance pathways for multinational binder suppliers. Stakeholders must monitor the trajectory of enzymatic biotransformation technologies against clay-based adsorption economics as regulatory ceilings tighten and end-users weigh total cost of mycotoxin risk mitigation.
Market Dynamics
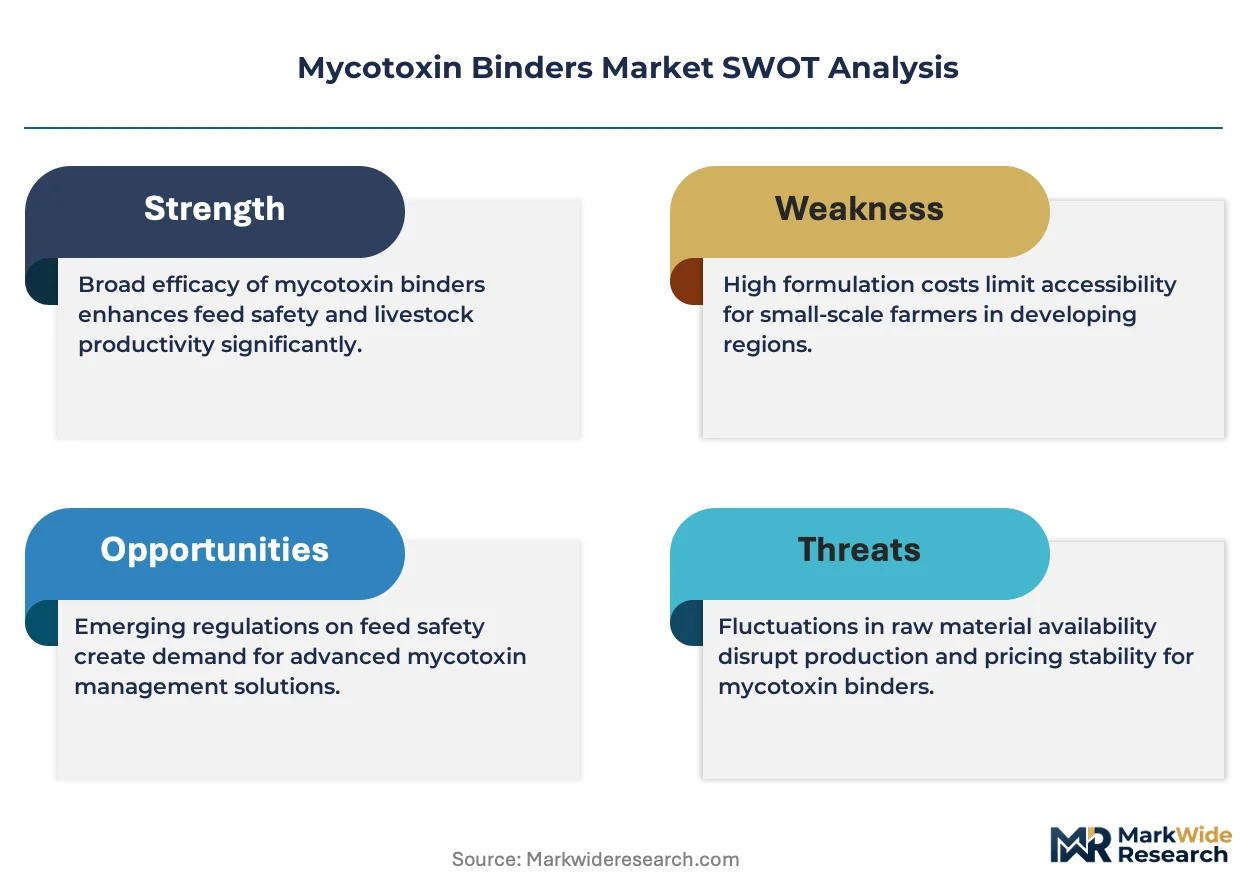
EU Feed Hygiene Regulation tightening and FDA action level enforcement are compressing residue thresholds faster than clay-based adsorption economics can absorb, forcing formulation shifts toward enzymatic biotransformation across export-oriented feed operations.
Growth Catalysts
- Brazilian broiler export certification:Feed safety mandates for EU and Saudi Arabian import channels are accelerating binder inclusion rates in compound feed formulations.
- REACH compliance pathways:EFSA mycotoxin opinions and binding maximum levels are reshaping formulation standards for suppliers accessing European livestock markets.
- Yeast cell wall derivatives:Modified glucomannan technologies are gaining traction in aflatoxin-specific applications where clay-based alternatives face efficacy ceilings.
Market Restraints
- Bentonite supply concentration:Mining asset control in select geographies creates vulnerability for low-cost clay binder availability.
- Activated charcoal cost structure:Premium raw material inputs and processing intensity limit scalability beyond pet and pharmaceutical niche applications.
- Regulatory divergence:Brazil's MAPA and China's MARA maintain non-harmonized residue monitoring programs that fragment compliance pathways for multinational suppliers.
Strategic Opportunities
- Southeast Asian shrimp aquaculture:Commercial aquaculture operations represent underpenetrated demand for homogeneous distribution in extruded feeds.
- Enzymatic-clay hybrid formulations:Convergence of biotransformation and adsorption technologies opens white space between premium and economy positioning.
- Integrated feed-to-protein channels:Direct binder specification embedding into grower contracts bypasses traditional distributor markups.
Industry Challenges
- Formulation science talent scarcity:Specialized expertise in modified glucomannan R&D and enzymatic preparation engineering outpaces academic pipeline output.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and national regulator approval processes extend time-to-market for novel binder technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycotoxin Binders Market |
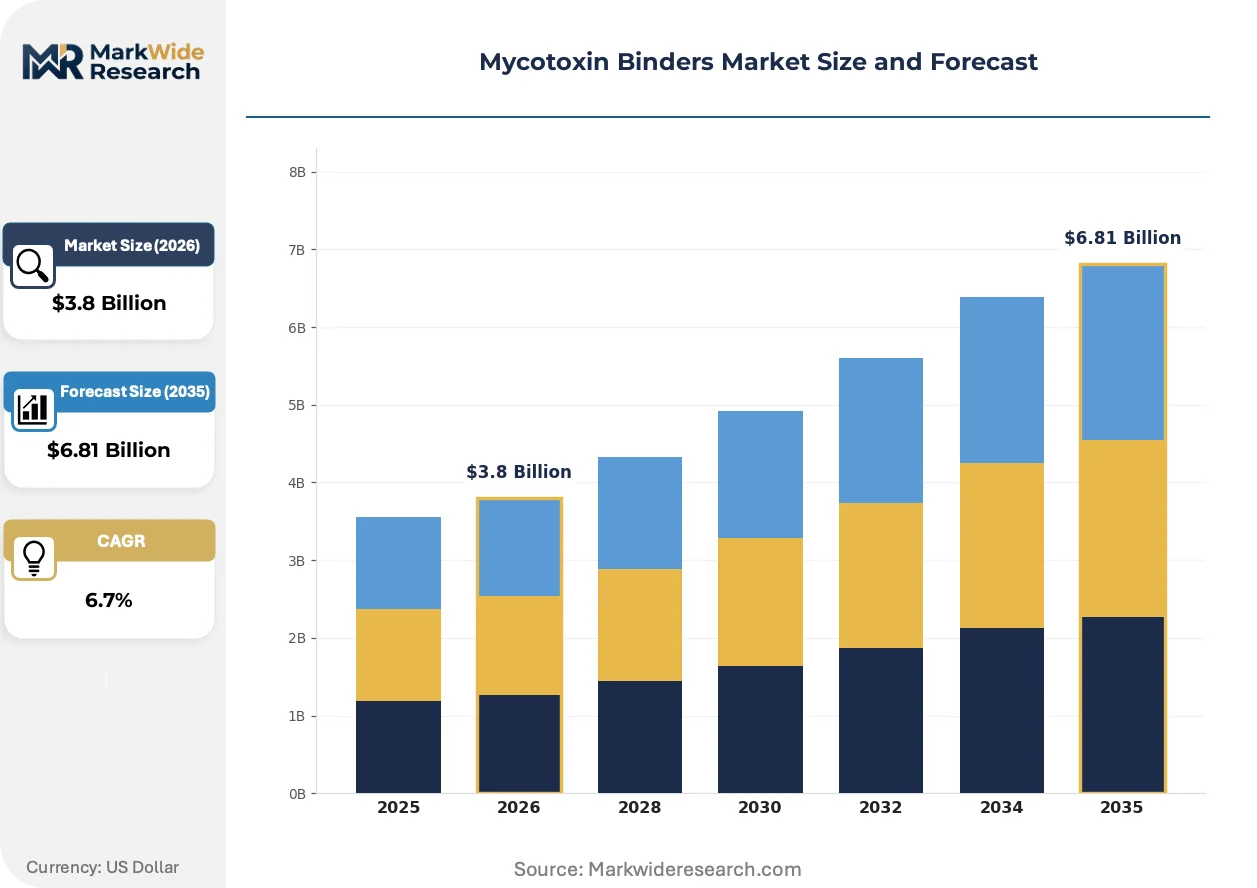
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bentonite, Activated Charcoal, Silicate, Calcium Carbonate Application: Animal Feed, Human Food, Pharmaceutical, Feed Additives Formulation: Liquid, Powder, Granular, Tablet End User: Livestock, Poultry, Aquaculture, Pet Industry |
| Companies Covered | BASF SE, BIOMIN Holding GmbH, Kemin Industries Inc., Alltech Inc., Cargill Incorporated, Selko B.V., Adisseo, Novus International Inc., Nutreco N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycotoxin Binders Market Strategic Shifts
Formulation science is pivoting from passive adsorption toward active biotransformation, reshaping how mycotoxin risk is neutralized across feed matrices and compressing the competitive advantage of legacy clay economics.
Enzymatic mycotoxin biotransformation is decomposing the traditional dominance of aluminosilicate clay binders by converting fungal metabolites into non-toxic derivatives rather than merely sequestering them. Poultry integrators in export-oriented operations are adopting these preparations at accelerating rates where aflatoxin specificity commands premium positioning. The technology is decomposing cost-per-unit efficacy comparisons that previously favored bentonite in high-volume compound feed applications.
EFSA mycotoxin opinions and EU Feed Hygiene Regulation amendments are tightening binding maximum levels faster than legacy formulation portfolios can adapt. Feed mill operators targeting European livestock markets must reformulate inclusion rates or risk channel exclusion. Aquaculture systems requiring homogeneous distribution in extruded feeds face the steepest compliance recalibration under these revised thresholds.
Buyer concentration among poultry integrators is compressing procurement cycles and unbundling after-sales technical service from product supply. Traditional distributor networks serving fragmented livestock operations are losing volume to direct specification channels where grower contracts embed binder requirements. This pattern is most visible in Brazil's scaling broiler export sector, where feed safety certification demands consolidate purchasing authority among integrated protein producers.
Mycotoxin Binders Market Segmentation
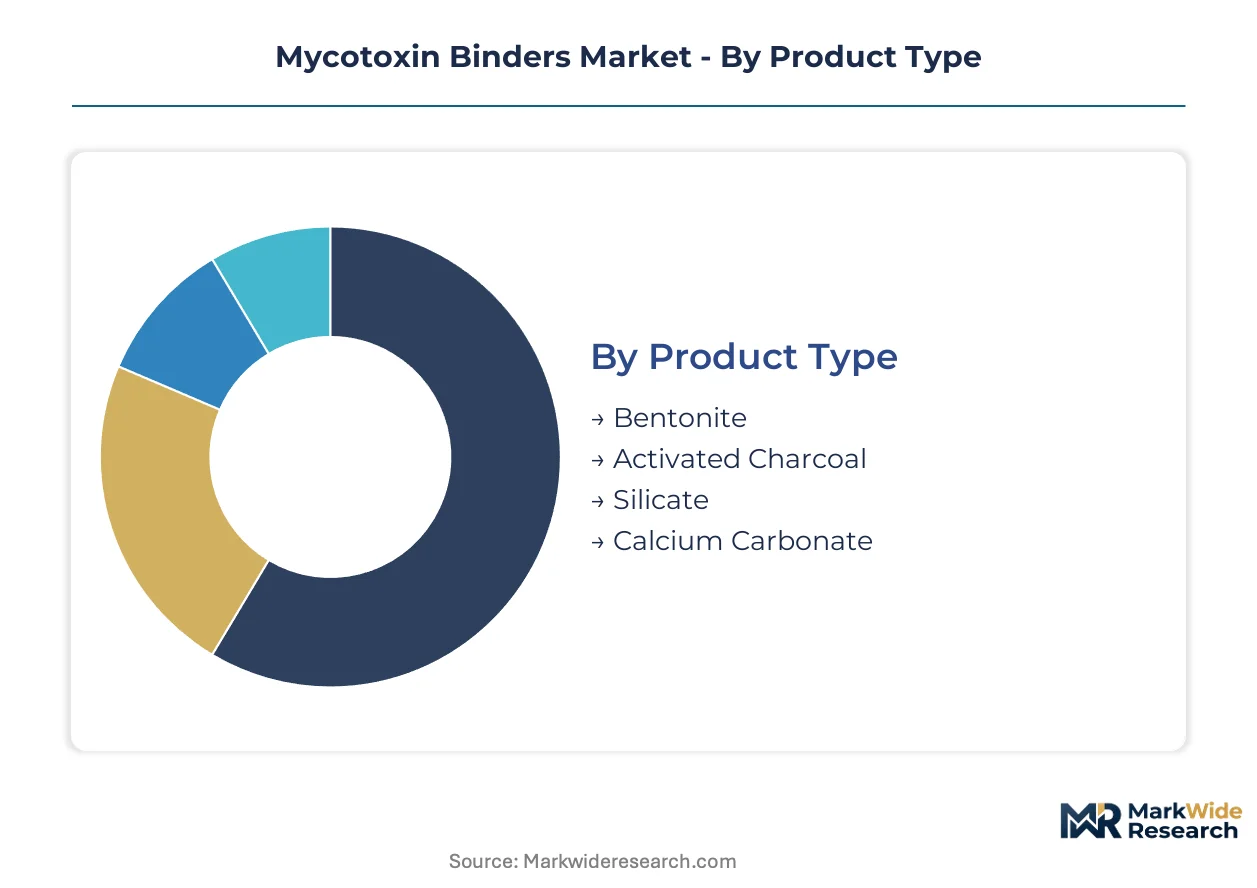
Channel configuration varies sharply across mycotoxin binder categories. Feed mills source powder formulations through direct procurement contracts, while aquaculture operations and pharmaceutical buyers rely on specialized distributors for liquid and tablet grades respectively.
Product Type:
Channel-mix patterns diverge significantly by mineral versus carbon-based chemistry. Bentonite flows predominantly through bulk commodity channels serving high-volume feed mill operations, while activated charcoal routes through specialty chemical distributors targeting pharmaceutical and premium pet food manufacturers.
- Bentonite:Aluminosilicate clay with layered silicate structure delivers established aflatoxin adsorption capacity at economy price points. Demand concentrates in Brazilian broiler export operations where EU Feed Hygiene Regulation compliance mandates reliable low-cost inclusion. The mineral's mining concentration in select geographies creates supply vulnerability during regulatory inspection surges.
- Activated Charcoal:High-surface-area carbonaceous matrix provides broad-spectrum mycotoxin coverage beyond aflatoxin specificity. Pharmaceutical applications in the United States and premium pet food channels absorb volume despite processing intensity that limits scalability. FDA Center for Veterinary Medicine action levels for multiple mycotoxin classes justify premium positioning in export-oriented operations.
- Silicate:Zeolite and diatomaceous earth variants occupy mid-tier positioning between bentonite economy and charcoal premium tiers.
- Calcium Carbonate:Limestone-derived binder functions primarily as a cost-advantaged extender in ruminant feed formulations with moderate mycotoxin loads.
By volume, bentonite leads. By growth pace, activated charcoal is climbing the fastest.
Application:
Cost tier stratification separates commodity feed applications from certified food and pharmaceutical grades. Animal feed tolerates standard purity specifications, while human food and pharmaceutical channels demand refined processing and documentation.
- Animal Feed:Compound feed manufacturers integrate binders at inclusion rates dictated by mycotoxin risk assessment protocols. Poultry integrators in export-oriented markets specify binder grades that satisfy destination country residue thresholds. The segment absorbs the majority of bentonite volume through direct mill procurement.
- Pharmaceutical:Detoxification applications for human mycotoxin exposure require activated charcoal with documented purity certification and batch traceability. Regulatory filing requirements in the United States and Europe create formulation lock-in effects that stabilize supplier relationships.
- Human Food:Cereal and nut processing operations deploy binders during grain conditioning to meet import market maximum residue limits.
- Feed Additives:Premix manufacturers compound binders with vitamins and minerals for distribution through agricultural supply channels.
Animal feed dominates absolute consumption. Pharmaceutical applications command the steepest margin expansion trajectory.
Formulation:
Volume scale and application method determine powder versus liquid preference across end-use segments. Feed mill integration favors bulk powder handling, while extruded aquaculture feeds and pharmaceutical dosing require alternative physical forms.
- Powder:Standard particle size distribution enables pneumatic conveying and uniform mixing in high-throughput feed mill operations. The physical form matches the infrastructure investments of major compound feed producers in Brazil and the United States.
- Liquid:Homogeneous distribution in extruded shrimp feeds and automated dosing systems drives specification in Southeast Asian aquaculture. Viscosity-adjusted formulations penetrate feed matrix porosity more effectively than dry alternatives in high-moisture processing environments.
- Granular:Dust-reduced physical form serves specialty feed operations with handling constraints.
- Tablet:Unit-dose presentation aligns with pharmaceutical dispensing and companion animal direct administration requirements.
Powder formulations lead by tonnage. Liquid binders are expanding most quickly in aquaculture channels.
End User:
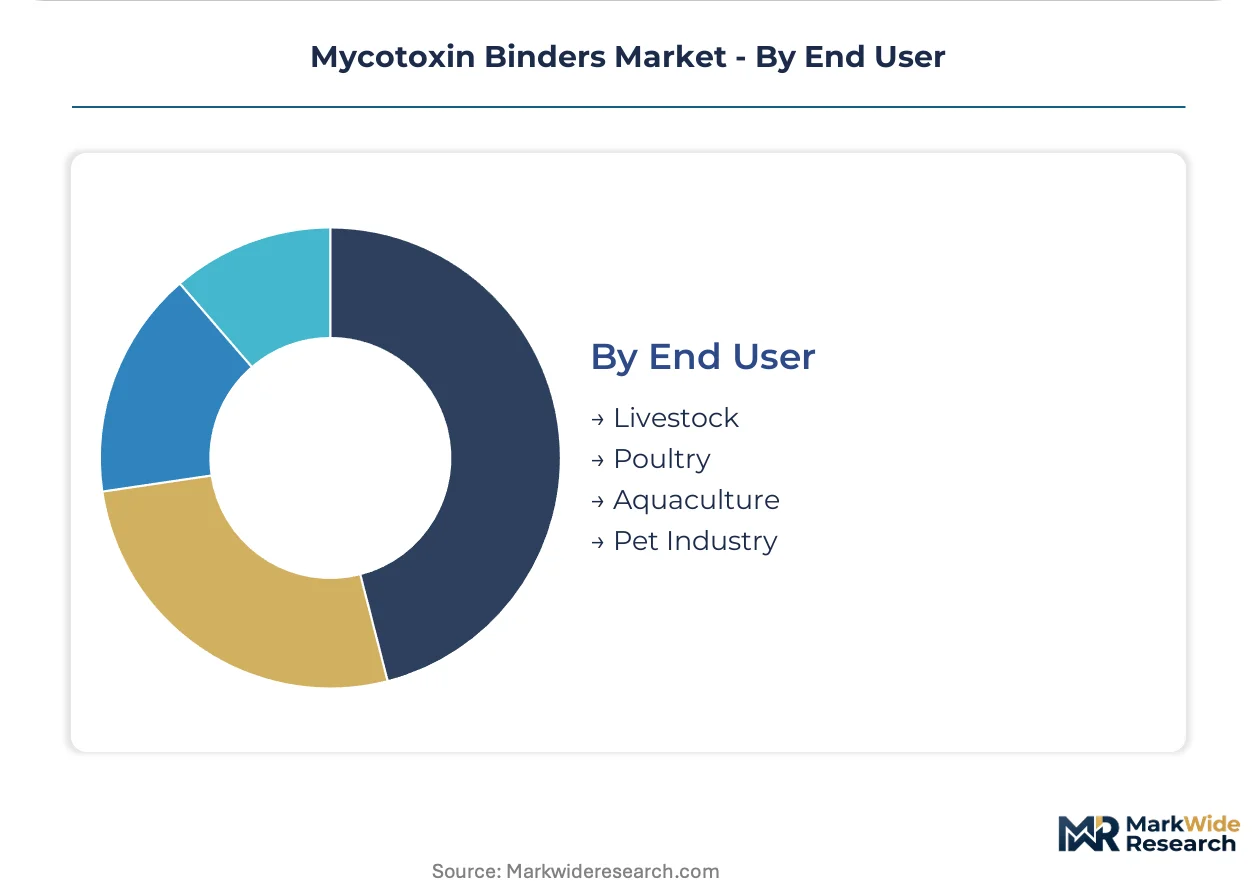
Customer type and procurement authority concentrate demand differently across livestock, poultry, and emerging aquaculture segments. Integrated protein producers consolidate purchasing power, while fragmented livestock operations sustain distributor networks.
- Poultry:Export certification requirements for EU and Saudi Arabian markets embed binder specifications directly into grower contracts. Brazilian integrators scale inclusion rates to meet feed safety mandates that gate market access. The segment's procurement concentration compresses pricing cycles and technical service bundling.
- Aquaculture:Commercial shrimp operations in Southeast Asia represent underpenetrated demand for homogeneous distribution technologies. BASF SE leverages bentonite mining assets to anchor supply security across Vietnamese and Indonesian feed markets.
- Livestock:Ruminant and swine operations sustain steady bentonite consumption through regional feed mill channels.
- Pet Industry:Premium positioning tolerates activated charcoal cost structures for broad-spectrum mycotoxin protection in companion animal nutrition.
Poultry commands the largest volume share. Aquaculture is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bentonite mining assets cluster in select geographies, creating supply vulnerability that reshapes procurement patterns across export-oriented feed operations. Regulatory divergence between major consuming markets fragments compliance pathways for multinational binder suppliers.
United States
Poultry integrators and pharmaceutical manufacturers anchor domestic consumption of activated charcoal and enzymatic preparations. FDA Center for Veterinary Medicine action levels dictate inclusion rates for export-oriented feed operations. The Midwest feed mill corridor concentrates compound feed manufacturing where binder specifications embed directly into grower contracts.
Brazil
Broiler export certification for EU and Saudi Arabian markets accelerates binder inclusion rates in compound feed formulations. MAPA residue monitoring programs create parallel compliance pathways distinct from FDA or EFSA frameworks. São Paulo state's integrated protein producers consolidate purchasing authority through direct specification channels.
Germany
REACH compliance pathways and EFSA mycotoxin opinions reshape formulation standards for suppliers accessing European livestock markets. The country's bentonite processing capacity serves as a distribution hub for EU feed mill operations. Bavaria's agricultural supply chains integrate binder specifications into regional feed safety protocols.
China
MARA residue monitoring programs and domestic feed safety mandates drive specification shifts in the world's largest compound feed market. Yangtze River Delta feed manufacturers source aluminosilicate clays for poultry and aquaculture applications. Shandong Province's shrimp aquaculture operations represent emerging demand for liquid binder formulations.
Vietnam
Commercial shrimp aquaculture operations generate underpenetrated demand for homogeneous distribution technologies in extruded feeds. The Mekong Delta's feed mill infrastructure scales binder inclusion to meet export market certification requirements. Ho Chi Minh City logistics channels connect Southeast Asian aquaculture to global bentonite supply networks.
Mycotoxin Binders Market Competitive Environment
Concentration sits with diversified chemical conglomerates and integrated feed-to-protein channels that control mining assets and direct specification embedding. The vendor base spans three tiers: mining-anchored multinationals with captive bentonite supply, R&D-intensive specialists in modified glucomannan formulations, and regional distributors serving fragmented livestock operations. M&A activity targets enzymatic biotransformation capabilities, while capacity expansion focuses on Southeast Asian aquaculture feed corridors.
Among mining-anchored multinationals, BASF SE exemplifies supply security strategies through bentonite asset control. Kemin Industries Inc. and BIOMIN Holding GmbH occupy positions within the R&D-intensive tier, representing modified glucomannan and enzymatic preparation specialists respectively. Cargill Incorporated anchors the integrated feed-to-protein channel archetype where binder specifications embed directly into grower contracts.
| Leading Market Players |
|---|
| BASF SE |
| BIOMIN Holding GmbH |
| Kemin Industries Inc. |
| Alltech Inc. |
| Cargill Incorporated |
| Selko B.V. |
| Adisseo |
| Novus International Inc. |
| Nutreco N.V. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at bentonite mining operations in Wyoming and Turkey anchors price floors across economy-grade binder tiers, while underutilized enzymatic biotransformation capacity in Western Europe compresses premium pricing elasticity. Scale asymmetry between clay extraction and biotech manufacturing concentrates bargaining power among mining-anchored multinationals serving Brazilian poultry integrators.
Pricing Analysis
Volume-discount tiering structures separate spot-market bentonite purchases from multi-year offtake contracts signed by integrated protein producers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales technical service bundling. Cost compression in standard-tier clay binders is intensifying because Brazilian export certification mandates force reformulation investments. Poultry integrators with direct specification channels exhibit lowest price sensitivity; fragmented Southeast Asian aquaculture operations remain most exposed to spot-price volatility.
Supply Chain Analysis
Bosphorus Strait transit underwrites bentonite flows from Turkish mining districts to EU feed mill corridors, creating logistics vulnerability during regulatory inspection surges. Mining concentration in Wyoming, Turkey, and China feeds raw material dependencies for aluminosilicate clay, yeast cell wall derivatives, and enzymatic preparation feedstocks. Single-source vulnerability concentrates in Wyoming bentonite districts where EPA mining permits face renewal uncertainty. Distribution runs through bulk commodity channels for feed mill procurement and specialty chemical distributors for pharmaceutical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across FDA, EFSA, and national residue monitoring programs fragments compliance pathways, creating specialist niches for enzymatic biotransformation and modified glucomannan technologies that legacy clay portfolios cannot address.
For Market Incumbents: Compound defensive moats by securing captive bentonite mining assets in Wyoming or Turkey to anchor supply security against regulatory inspection disruptions, while accelerating enzymatic R&D investment to offset substitution threats from biotransformation specialists. Certification lock-in effects through EFSA-compliant formulation portfolios protect channel position in EU-bound export operations. For New Entrants and Emerging Players: Differentiate on aflatoxin-specific enzymatic biotransformation efficacy to bypass entrenched bentonite economics in Brazilian broiler export channels. Southeast Asian shrimp aquaculture represents the most penetrable geography, where liquid binder homogeneous distribution technology commands specification premiums. Partner with Vietnamese feed mill operators to bypass established distributor networks. For Investors and Strategic Acquirers: R&D-intensive enzymatic preparation specialists with EFSA-ready formulation pipelines offer the strongest acquisition target archetype for long-term viability across tightening regulatory ceilings. Monitor EFSA mycotoxin opinion amendment velocity as the critical inflection signal for portfolio rebalancing between adsorption and biotransformation exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Mining | Wyoming asset control secures supply security for Brazilian poultry export certification demands. |
| Enzymatic Biotransformation R&D Expansion | EFSA-compliant formulation development displaces legacy clay economics in EU-bound channels. |
| Southeast Asian Aquaculture Partnership | Vietnamese feed mill alliances unlock liquid binder specification channels in shrimp operations. |
| Multi-Jurisdiction Certification Investment | Parallel FDA and EFSA filing capacity accelerates time-to-market for novel binder technologies. |
| Direct Specification Channel Development | Grower contract embedding bypasses distributor markups in Brazil's consolidating protein sector. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with poultry integrator procurement directors, aquaculture feed formulators, bentonite mining operations managers, and enzymatic preparation R&D leads. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, EFSA mycotoxin opinion archives, Brazilian MAPA residue monitoring reports, and customs trade data for aluminosilicate clay flows. Bottom-up volume modeling and top-down value triangulation cross-validated segment-level estimates across the analysis window.
Across the analysis window, projections incorporate product type, application grade, formulation physical form, and end-user procurement authority as core segmentation dimensions. CAGRs derive from regression analysis against regulatory threshold tightening trajectories and export certification expansion patterns in broiler and shrimp channels. Feed safety mandate adoption curves and enzymatic biotransformation cost-reduction slopes inform technology substitution modeling.
Material uncertainties — EFSA opinion amendment timing, Wyoming mining permit renewal outcomes, and Brazilian broiler export volume volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory harmonization resistance and enzymatic preparation scale-up economics. Practitioners should keep alternative scenarios live as EFSA mycotoxin opinion trajectories and Southeast Asian aquaculture certification requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Plastic Antioxidants Market
Additives
Ammonium Acetate Market
Additives
Refinery Fuel Additives Market
Additives
Americas Coating Additives Market
Additives
Paint Additives Market
Additives
Canada Water Enhancer Market
Additives
Driveline Additives Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Trioctyldodecyl Citrate Market
Additives
Gelatin Peptones Market
Additives
Engine Oil Additive Market
Additives
Fuel Additives Market
Additives
Ammonium Phosphatide Market
Additives
Pearlizers Market
Additives
Global Pearlizing Agent Market
Additives
Dispersing Agents Market