
 Global Zeolites Market | 2026-2036
Global Zeolites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zeolites Market Outlook
Modular catalyst loading configurations is broadening buyer choice across refinery and petrochemical sectors. BASF leverages its integrated molecular sieve manufacturing network to supply bundled catalyst-adsorbent systems. Tosoh Corporation anchors Asian demand through specialized zeolite production for automotive emissions control. Clariant competes on formulation customization, offering site-specific catalyst blends that reduce changeout frequency for downstream operators.
Zeolites are crystalline aluminosilicate minerals with defined pore structures typically measuring 0.3 to 2 nanometers, synthesized through hydrothermal crystallization or mined from volcanic deposits for molecular separation and catalytic conversion. Synthetic zeolites dominate value generation due to tunable silica-to-alumina ratios that meet precise catalytic cracking specifications in oil and gas processing. Adsorbent applications capture expanding margin pools as natural gas dehydration and air separation demand intensifies, while ion exchange grades face maturity in conventional detergent markets. Powder and granule forms lead volume throughput, though pelletized configurations gain traction in fixed-bed reactor installations requiring low pressure-drop performance.
EPA emissions standards under the Clean Air Act and REACH registration requirements in Europe constrain formulation chemistries and mandate extensive toxicity testing for new synthetic zeolite introductions. China's Ministry of Ecology and Environment enforces GB standards on volatile organic compound emissions that directly affect catalyst replacement cycles in domestic refineries. Saudi Arabia's SFDA and industrial permitting authorities influence product qualification timelines for suppliers targeting Middle Eastern petrochemical expansions. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification barriers.
Market Dynamics
Refinery operators in Saudi Arabia and the US Gulf Coast are accelerating catalyst replacement cycles to meet tightening sulfur specifications, compressing procurement timelines and forcing suppliers to hold regional inventory positions closer to demand clusters.
Growth Catalysts
- REACH Registration Requirements:European ECHA mandates for synthetic zeolite toxicity documentation are filtering out low-volume competitors and consolidating qualified supplier lists for detergent and emissions control applications.
- Natural Gas Dehydration Demand:LNG export terminal expansions in Qatar and Australia are consuming molecular sieve adsorbents at volumes that justify dedicated production lines for 4A and 13X grades.
- Automotive Emissions Control:China's MEE enforcement of GB18352.6 standards for heavy-duty diesel vehicles is extending zeolite-based SCR catalyst lifecycles beyond previous replacement intervals.
Market Restraints
- Alumina Supply Concentration:Synthetic zeolite production depends on specialty-grade alumina sourced primarily from Chinese refiners, creating input cost volatility when export quotas tighten.
- Energy-Intensive Hydrothermal Synthesis:Crystallization reactors require sustained high-temperature steam, exposing European producers to natural gas price spikes that compress margin structures.
- Silica Gel Substitution:Air separation and drying applications in Southeast Asian industrial parks are partially shifting to silica gel where moisture specifications allow lower-cost alternatives.
Strategic Opportunities
- India's BIS Certification Pathway:Mandatory Bureau of Indian Standards marking for water treatment chemicals creates a qualification barrier that early entrants can leverage for pricing power in municipal procurement.
- Carbon Capture Adsorbents:Direct air capture developers in Iceland and Canada are testing lithium-modified zeolite formulations for CO2 selectivity at ambient temperatures.
- Modular On-Site Synthesis:Containerized hydrothermal units for remote mining camps in Chile and Peru eliminate freight costs for dense molecular sieve products.
Industry Challenges
- Crystallization Process Control:Batch-to-batch variance in silica-to-alumina ratios requires skilled technicians to monitor pH and temperature profiles, creating talent scarcity in emerging production regions.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA PMN notifications, REACH dossier submissions, and China's MEE new chemical registrations extend product launch cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zeolites Market |
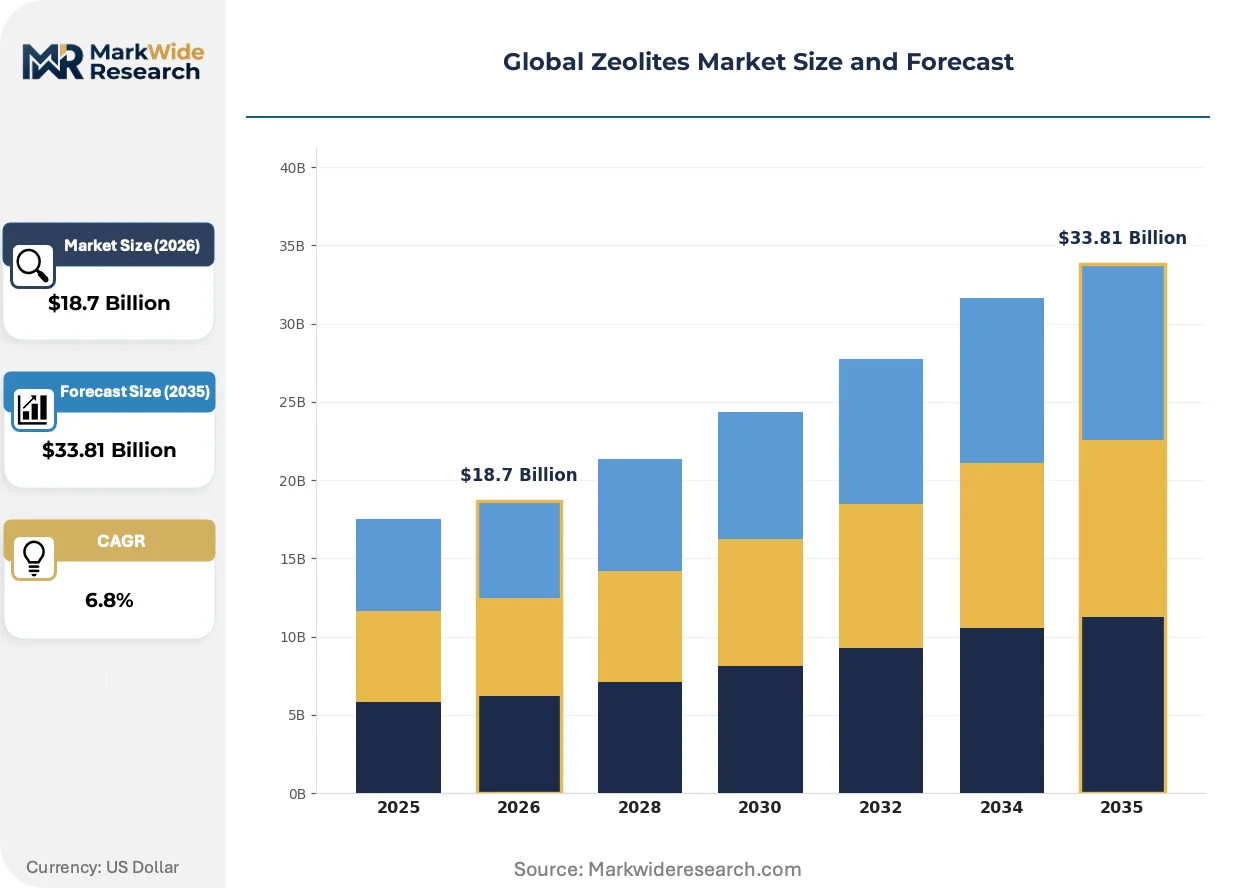
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Zeolites, Synthetic Zeolites, Modified Zeolites, Specialty Zeolites End Use Industry: Construction, Agriculture, Oil & Gas, Water Treatment Application: Catalysts, Adsorbents, Ion Exchange, Soil Amendments Form: Powder, Granules, Pellets, Crystals |
| Companies Covered | BASF, Honeywell International Inc., W. R. Grace & Co., Clariant, Tosoh Corporation, Arkema, Zeolyst International Inc., ZEOCEM, Resonac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zeolites Market Strategic Shifts
Zeolite chemistry is diverging along two paths: precision-tuned synthetic structures for catalytic applications and functionalized natural clinoptilolite for agricultural and environmental remediation markets previously served by commodity materials.
Hierarchical zeolites combining micropore crystallinity with engineered mesopore networks are expanding into fluid catalytic cracking units where diffusion limitations previously constrained heavy oil conversion efficiency. Saudi Aramco's Riyadh refinery and ExxonMobil's Baytown complex have adopted these dual-pore configurations for residuum processing. The technology is expanding into markets previously dominated by amorphous silica-alumina catalysts by demonstrating measurable yield improvements on high-metal feeds.
Europe's F-Gas Regulation phase-down schedules are mandating replacement of fluorinated refrigerants in industrial cooling systems, indirectly stimulating demand for zeolite-based adsorption chillers in German chemical parks and Dutch greenhouse operations. BASF's Ludwigshafen site and Dow's Terneuzen complex have piloted zeolite-water working pairs for waste-heat recovery. The regulatory pressure is compressing payback thresholds for capital-intensive adsorption equipment, accelerating procurement decisions that previously stalled on first-cost comparisons.
Refinery procurement teams are unbundling catalyst supply from technical service contracts, creating direct material sourcing relationships that bypass traditional integrated supplier arrangements. This pattern is most visible along the US Gulf Coast where Motiva's Port Arthur facility and Marathon's Galveston Bay refinery have separated catalyst selection from reactor loading supervision. The disintermediation is forcing molecular sieve producers to build in-house technical service capabilities or partner with independent loading contractors to retain account control.
Global Zeolites Market Segmentation
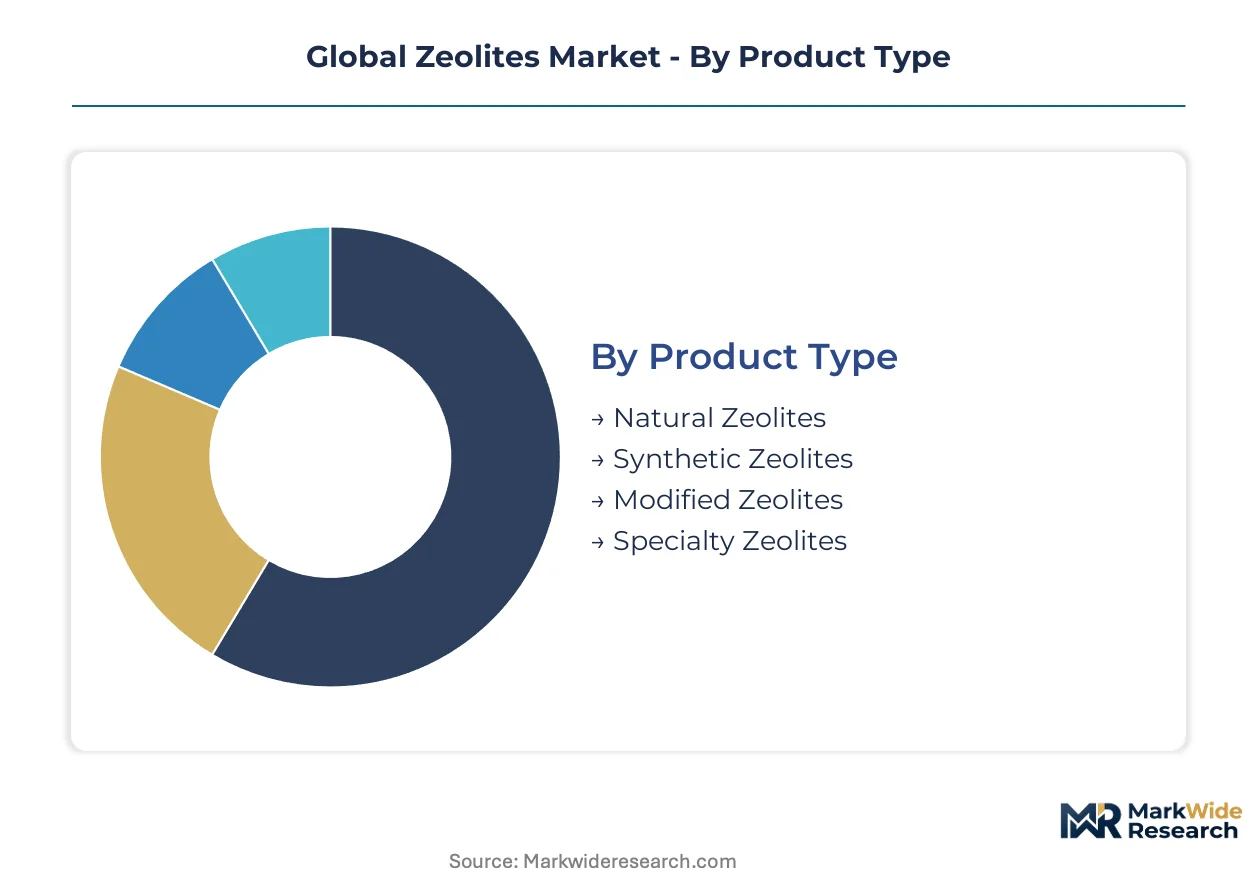
Zeolite market segmentation reveals distinct value capture mechanisms across synthetic versus natural product streams, with embedded catalytic applications commanding premium pricing against standalone adsorbent deployments. Understanding these structural divides enables suppliers to align production assets with margin concentration points rather than volume alone.
Product Type:
Integration depth varies sharply—synthetic grades embed directly into refinery process streams while natural variants serve standalone environmental and agricultural applications.
- Synthetic Zeolites:Hydrothermally crystallized aluminosilicates with tunable silica-to-alumina ratios between 2 and 200, enabling precise pore size engineering. Demand concentrates in FCC units across Saudi Arabia's Jubail Industrial City and the US Gulf Coast, driven by tightening sulfur specifications that compress catalyst replacement cycles.
- Natural Zeolites:Mined clinoptilolite and mordenite deposits with fixed pore structures typically 0.4 to 0.7 nanometers. Agricultural soil amendment applications in Australia's wheat belt and California's Central Valley absorb volume, constrained by inconsistent batch quality that limits specification-grade uptake.
- Modified Zeolites:Ion-exchanged or metal-impregnated variants for enhanced selectivity in emissions control.
- Specialty Zeolites:Ultra-high-purity grades for pharmaceutical and electronics applications requiring sub-ppm contamination thresholds.
Volume placements concentrate in Synthetic Zeolites; the faster expansion belongs to Modified Zeolites.
End Use Industry:
Cost tier stratification separates capital-intensive process integration from commoditized bulk consumption patterns.
- Oil & Gas:Fluid catalytic cracking and hydrocracking catalysts represent the highest value-per-ton segment. Refinery operators in Rotterdam and Singapore prioritize technical service bundling over material cost, embedding zeolites deep within continuous process economics.
- Water Treatment:Municipal and industrial ion exchange applications for hardness removal and radionuclide capture. Germany's Rhine-Ruhr utilities and Japan's Kansai region drive specification-grade demand, constrained by REACH and JIS certification timelines.
- Construction:Lightweight aggregate and pozzolanic cement additive applications in bulk concrete.
- Agriculture:Slow-release fertilizer carriers and soil moisture retention in arid cropping systems.
Margin capture peaks in Oil & Gas; Agriculture shows the steepest expansion trajectory as water stress intensifies irrigation efficiency requirements.
Application:
Customer type divergence splits between process-integrated refiners and specification-driven discrete buyers.
- Catalysts:Shape-selective cracking and isomerization in petrochemical value chains. Hierarchical zeolites with engineered mesopore networks are gaining share in residuum processing at ExxonMobil's Baytown complex and Saudi Aramco's Riyadh refinery.
- Adsorbents:Molecular sieves for natural gas dehydration and air separation. Qatar's North Field LNG expansion and Australia's Prelude FLNG consume 4A and 13X grades at volumes justifying dedicated production lines.
- Ion Exchange:Detergent builders and water softening applications facing maturity in developed markets.
- Soil Amendments:Cation exchange capacity enhancement for nutrient retention in sandy soils.
Technology leadership resides in Catalysts; Adsorbents are climbing the fastest on LNG infrastructure buildout.
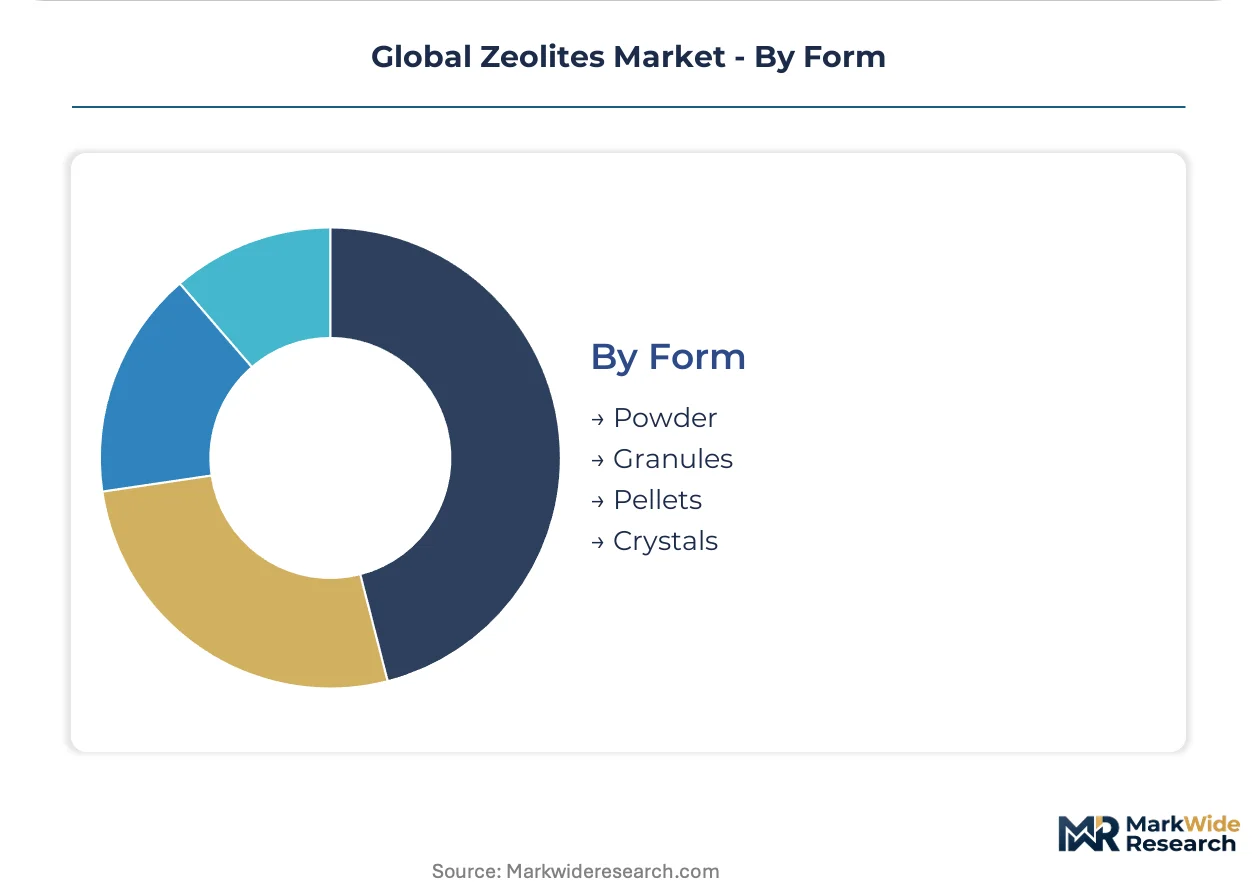
Form:
Supply concentration aligns with reactor engineering requirements across fixed-bed versus fluidized configurations.
- Pellets:Extruded cylindrical forms optimized for low pressure-drop in packed bed reactors. German chemical parks and Dutch greenhouse operations specify pelletized zeolites for adsorption chiller integration under F-Gas Regulation compliance timelines.
- Powder:Fine particulate grades for fluidized catalytic cracking and cement blending. Bulk handling infrastructure at US Gulf Coast refineries and China's Ningbo-Zhoushan port cluster supports high-throughput consumption.
- Granules:Intermediate sizing for water treatment column packing and agricultural broadcast spreading.
- Crystals:High-purity single-crystal forms for research and specialty electronics applications.
Procurement scale favors Powder; Pellets gain share fastest on waste-heat recovery system deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic zeolite production concentrates in Germany, Japan, and the United States while consumption clusters in Saudi Arabia, Qatar, and China's coastal refinery zones. This geographic mismatch shapes freight economics and regional inventory strategies.
United States
Gulf Coast refineries in Texas and Louisiana drive catalyst replacement demand as EPA Clean Air Act sulfur specifications tighten. The Port Arthur and Galveston Bay complexes compress procurement timelines, forcing suppliers to maintain regional stockpiles. Shale gas processing facilities in the Permian Basin consume molecular sieve adsorbents for dehydration units.
Germany
Rhine-Ruhr water utilities specification-grade demand for ion exchange applications accelerates under REACH registration mandates. BASF's Ludwigshafen complex anchors synthetic zeolite production for European FCC catalyst supply. F-Gas Regulation compliance timelines stimulate zeolite-water adsorption chiller installations in Dutch greenhouse operations served by German chemical parks.
Saudi Arabia
Jubail Industrial City and Yanbu petrochemical complexes represent the highest-value catalyst consumption nodes globally. SFDA and industrial permitting authorities extend product qualification timelines for foreign suppliers. Residuum processing upgrades at Saudi Aramco's Riyadh refinery adopt hierarchical zeolite configurations for heavy oil conversion.
China
Ningbo-Zhoushan port cluster and coastal refinery zones consume powder-grade zeolites at bulk throughput volumes. MEE enforcement of GB18352.6 standards extends SCR catalyst lifecycles for heavy-duty diesel vehicles. Specialty-grade alumina export quotas from domestic refiners generate input cost volatility for synthetic zeolite producers.
Japan
Kansai region water treatment utilities and automotive emissions control manufacturers drive specification-grade demand. Tosoh Corporation's specialized production anchors Asian supply for zeolite-based SCR systems. JIS certification requirements constrain qualification timelines for imported molecular sieve products.
Global Zeolites Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across catalyst, adsorbent, and ion exchange segments. The vendor base organizes into three tiers: integrated chemical majors with captive molecular sieve production, independent catalyst formulators with technical service bundling, and regional mining operations supplying natural clinoptilolite grades. Consolidation pressures intensify as refinery procurement teams unbundle catalyst supply from reactor loading contracts, forcing material producers to build in-house technical capabilities or partner with independent contractors.
Among diversified chemical majors, BASF and Clariant exemplify the integrated formulation archetype with bundled catalyst-adsorbent system offerings. Tosoh Corporation represents the Asia-Pacific specialist model with concentrated zeolite production for automotive emissions control applications. These three anchors illustrate divergent geographic and segment positioning strategies without implying specific market share claims.
| Leading Market Players |
|---|
| BASF |
| Honeywell International Inc. |
| W. R. Grace & Co. |
| Clariant |
| Tosoh Corporation |
| Arkema |
| Zeolyst International Inc. |
| ZEOCEM |
| Resonac |
| Others |
Value Chain & Pricing Dynamics
Europe's F-Gas Regulation phase-down schedules gate qualified supply for zeolite-based adsorption chillers while compressing payback thresholds that separate premium-tier pricing access from commoditized alternatives. Buyers in German chemical parks and Dutch greenhouse operations face procurement timelines that reward pre-qualified suppliers with pricing power while filtering out uncertified competitors.
Pricing Analysis
Cost-down pressure on standard-grade synthetic zeolites accelerates because refinery procurement teams in Texas and Louisiana are unbundling catalyst supply from technical service contracts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered formulations from commodity grades, with price differentiation driven by certification tier and after-sales technical bundling. Margin tightening in powder-grade bulk supply traces to silica gel substitution in Southeast Asian drying applications. Municipal water utilities in Germany and Japan show lowest price sensitivity due to specification-grade mandates, while agricultural soil amendment buyers in Australia's wheat belt drive hardest negotiations on volume.
Supply Chain Analysis
China's Ministry of Ecology and Environment domestic-content preferences for refinery catalyst replacement cycles are reshaping sourcing patterns for specialty-grade alumina inputs. Synthetic zeolite production concentrates in Germany, Japan, and the United States, drawing from bauxite refiners, high-purity silica sources, and sodium hydroxide suppliers. Single-source vulnerability sits with Chinese alumina export quotas that generate input cost volatility when tightening. Distribution runs through regional inventory positions maintained close to Saudi Arabia's Jubail Industrial City and Qatar's LNG export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration requirements in Europe have erected a cost-of-compliance moat that consolidates qualified supplier lists and protects margin structures for dossier-compliant synthetic zeolite producers.
For Market Incumbents: Cement technical service capabilities in-house or through exclusive loading contractor partnerships to retain account control as Gulf Coast refineries separate catalyst selection from reactor supervision. BASF's integrated molecular sieve network demonstrates how backward integration into hydrothermal crystallization assets defends against silica gel substitution threats in air separation markets. For New Entrants and Emerging Players: Lithium-modified zeolite formulations for direct air capture applications represent a technology-first wedge into carbon capture markets where incumbent catalyst producers hold limited patent positions. India's BIS certification pathway for water treatment chemicals offers the most penetrable regulatory entry point, with municipal procurement tenders rewarding early qualified entrants with pricing power. For Investors and Strategic Acquirers: Containerized on-site synthesis deployments in Chilean and Peruvian mining camps are the leading indicator that modular production economics are disrupting traditional freight-heavy distribution models. Acquisition targets should concentrate on regional mining operations with clinoptilolite deposits and formulation capabilities for agricultural soil amendment expansion. Watch hierarchical zeolite adoption rates at residuum processing units as the signal for technology substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | Captive sourcing from Chinese refiners mitigates export quota volatility for European producers. |
| REACH Dossier Expansion | Extended toxicity documentation filters detergent-grade competitors from qualified supplier lists. |
| Modular On-Site Synthesis Deployment | Containerized hydrothermal units eliminate freight costs for remote mining camp molecular sieve demand. |
| Hierarchical Zeolite R&D Partnership | Dual-pore configurations with Saudi Aramco's Riyadh refinery demonstrate residuum processing yield improvements. |
| Technical Service Capability Buildout | In-house reactor loading supervision retains account control as procurement teams unbundle catalyst supply contracts. |
Study Parameters
Trade databases, ECHA registration filings, and SEC 10-K disclosures formed the secondary backbone, supplemented by primary interviews with refinery procurement managers, catalyst R&D directors, molecular sieve plant operators, and water utility specification engineers. Bottom-up and top-down triangulation validated synthetic versus natural zeolite volume splits across catalytic and adsorbent applications.
Bottom-up modeling anchored segment-level projections across the analysis window, with top-down cross-checks against petrochemical capacity expansion announcements and LNG infrastructure buildout timelines. Segmentation dimensions included product type, end-use industry, application function, and geographic production hub. CAGRs derived from regression analysis of historical replacement cycle compression and regulatory-driven specification upgrades.
Several conditions sit outside the modeled scope, including unannounced alumina export quota adjustments, abrupt F-Gas Regulation acceleration timelines, and breakthrough non-zeolitic adsorbent technologies. Forecasts reflect documented assumptions about hydrothermal synthesis energy costs and certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Polymer Catalyst Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Environmental Catalysts Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Hydrodesulfurization Catalyst Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Global VOC Catalysts Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
South America Refining Catalysts Market
Catalysts
North America Industrial Catalyst Market
Catalysts
North America Zeolite Market