
 Global Viral Vector Manufacturing Market | 2026-2036
Global Viral Vector Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Viral Vector Manufacturing Market Foresight
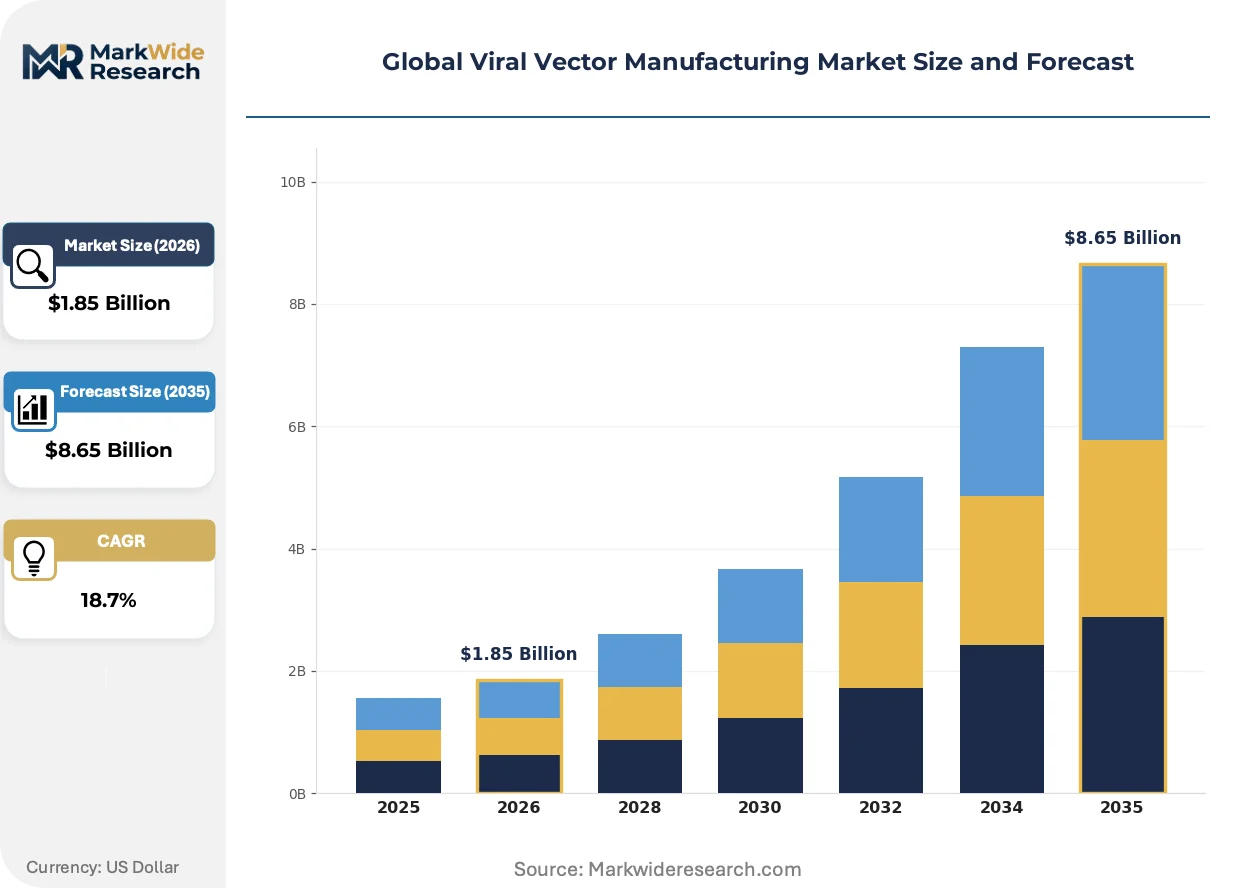
EU MDR is expanding compliance burdens for viral vector suppliers seeking European market access. Lonza Group AG anchors capacity investments across Swiss and US production nodes. Thermo Fisher Scientific leverages its analytical instrumentation portfolio to control upstream quality workflows. Charles River Laboratories International, Inc. competes through integrated testing and release services that compress batch turnaround times.
Viral vector manufacturing encompasses the bioproduction of engineered viruses used to deliver genetic material into target cells, typically requiring suspension or adherent cell culture systems with titers measured in infectious units per milliliter. These vectors serve as the delivery backbone for gene therapies, cancer vaccines, and CAR-T cell engineering programs. Lentivirus and adeno-associated virus segments capture the dominant share of current capacity bookings, reflecting their established safety profiles in clinical applications. Suspension cell culture technology leads scalability economics, while stable producer cell lines represent the fastest-growing technology investment area as sponsors pursue reduced cost-of-goods targets.
FDA, EMA, and WHO standards collectively govern viral vector release specifications, with potency assays and replication-competent virus testing forming non-negotiable gatekeeping requirements. Japan's PMDA has tightened vector characterization guidelines, adding analytical depth expectations for Asian market entrants. Stakeholders must monitor regulatory divergence between FDA's platform technology guidance and EMA's evolving ATMP framework, as compliance strategy choices will determine which geographic markets remain accessible without redundant manufacturing runs.
Market Dynamics
Stable producer cell lines are compressing batch-to-batch variability and collapsing cost-of-goods targets for lentivirus and AAV programs, forcing contract manufacturers to retool legacy transient transfection infrastructure or surrender high-volume contracts to integrated biopharma sponsors.
Growth Catalysts
- FDA Accelerated Approval:The FDA's regenerative medicine advanced therapy designation compresses Phase 1-to-approval timelines, pulling forward capacity commitments from gene therapy developers.
- Oncology Vector Demand:CAR-T engineering programs in solid tumor indications are booking multi-year manufacturing slots ahead of clinical data readouts.
- Suspension Culture Economics:Single-use bioreactor trains at 2000L scale are displacing adherent platform costs by factors of three to five in COGS modeling.
Market Restraints
- Plasmid Supply Concentration:GMP-grade plasmid DNA production concentrates among fewer than ten qualified suppliers globally, creating input bottlenecks for transient transfection workflows.
- Replication-Competent Virus Testing Burden:FDA and EMA both mandate RCV assays with 10^-6 sensitivity thresholds, adding six to eight weeks to release timelines.
- AAV Empty Capsid Fractionation:Analytical ultracentrifugation and ion-exchange chromatography steps for separating empty from full capsids consume 15-25% of downstream processing costs.
Strategic Opportunities
- Japan PMDA Alignment:Vector characterization guidelines issued by Japan's PMDA create first-mover advantages for Western manufacturers investing in extended release assays.
- Allogeneic Cell Therapy Convergence:Off-the-shelf CAR-T and iPSC-derived programs require lentivirus at tenfold the per-patient volume of autologous approaches.
- Continuous Bioprocessing Integration:Perfusion cell culture linked to continuous capture chromatography is collapsing facility footprints and enabling distributed manufacturing nodes.
Industry Challenges
- Vector Analytical Talent Scarcity:Potency assay development and orthogonal analytical method qualification require hybrid skill sets spanning virology, molecular biology, and regulatory science that remain underrepresented in labor markets.
- Facility Flexibility Constraints:Dedicated suites for AAV versus lentivirus production create asset stranding risks when demand shifts between vector types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Viral Vector Manufacturing Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adenovirus, Lentivirus, Retrovirus, Adeno-associated Virus, Herpes Simplex Virus Technology: Suspension Cell Culture, Adherent Cell Culture, Transient Transfection, Stable Producer Cell Lines, Helper Virus-Free Systems Application: Gene Therapy, Vaccine Development, Immunotherapy, Cell Therapy, Research & Development End User: Biopharmaceutical Companies, Contract Manufacturing Organizations, Academic Institutions, Research Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc., Lonza Group AG, Charles River Laboratories International, Inc., Oxford Biomedica, Catalent Inc., FUJIFILM Diosynth Biotechnologies, WuXi AppTec, Merck KGaA, Takara Bio Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Viral Vector Manufacturing Market Shifts & Advancements
Gene therapy manufacturing workflows are fragmenting across distributed production nodes, with technology investments concentrating on modular platforms that collapse facility construction timelines and enable geographic proximity to clinical sites.
Stable producer cell lines are decentralizing viral vector supply chains by eliminating the plasmid transfection bottleneck that has constrained transient production economics. Biopharma sponsors with internalized platforms are capturing cost advantages of 40-60% at commercial scale. This technology is compressing the viable addressable market for contract manufacturers lacking stable line capabilities.
EMA's evolving ATMP framework is diverging from FDA platform technology guidance on comparability protocol acceptance, creating compliance strategy fragmentation for sponsors seeking transatlantic approval. Manufacturers must now maintain dual analytical packages or accept delayed European market entry. Vector developers with early EMA engagement are securing scientific advice pathways that compress later-stage regulatory risk.
Biopharma procurement teams are consolidating supplier relationships around integrated testing-and-release partnerships that compress batch turnaround times. CDMOs with captive analytical development groups are displacing point-solution testing houses in vendor selections. This consolidation is most visible among Boston and San Francisco Bay Area gene therapy clusters where sponsor-analytical service integration has become a default sourcing criterion.
Global Viral Vector Manufacturing Market Segmentation
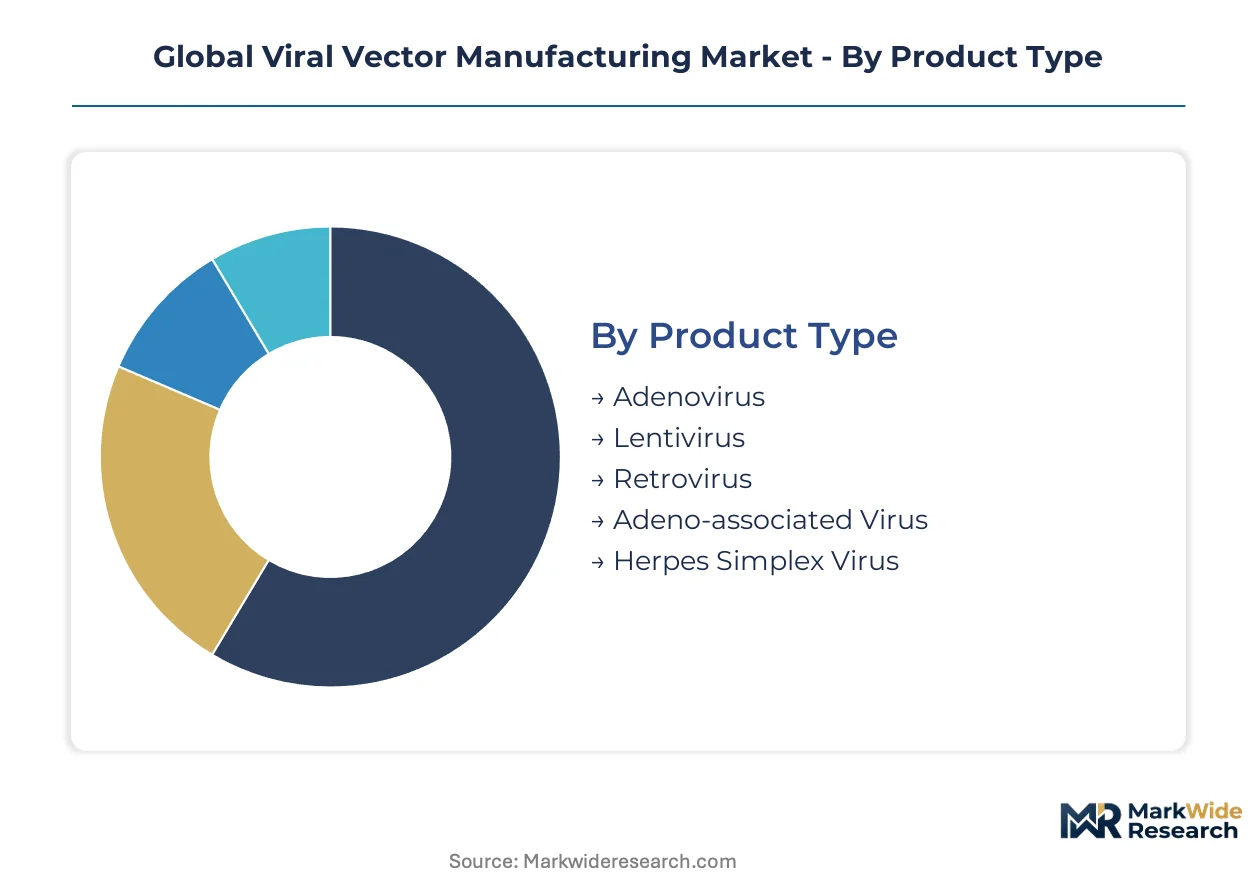
Viral vector manufacturing segments reflect divergent technical requirements across gene therapy modalities. Procurement patterns vary sharply between integrated biopharma sponsors and externalized development programs.
Product Type:
Adeno-associated virus and lentivirus segments dominate standalone therapeutic applications, while adenovirus and herpes simplex virus embed primarily in vaccine and oncolytic platforms respectively.
- Adeno-associated Virus:Single-stranded DNA parvovirus with serotype-dependent tissue tropism specifications. Boston and San Francisco Bay Area gene therapy developers anchor procurement volumes for AAV9 and AAV5 variants in CNS and ocular indications. FDA accelerated approval pathways pull forward multi-year capacity commitments.
- Lentivirus:RNA retrovirus with stable integration capacity for dividing and non-dividing cells. Allogeneic CAR-T engineering programs in solid tumor indications book manufacturing slots ahead of clinical readouts. Stable producer cell lines are compressing batch-to-batch variability for this segment.
- Adenovirus:Double-stranded DNA virus with high transduction efficiency in epithelial cells. Vaccine development programs, particularly pandemic response platforms, drive episodic demand spikes.
- Retrovirus:Gamma-retroviral vectors with established safety profiles in hematopoietic stem cell gene therapy. Academic research laboratories sustain baseline procurement volumes.
- Herpes Simplex Virus:Large DNA virus with 150kb cargo capacity for oncolytic applications. Immunotherapy developers exploit its natural neurotropism for glioblastoma targeting.
Adeno-associated virus leads volumes today; lentivirus is gaining share fastest.
Technology:
Cost tier stratification separates legacy adherent platforms from suspension systems and emerging stable line technologies, with capital intensity and COGS structure determining competitive viability.
- Suspension Cell Culture:Scalable bioproduction in chemically defined media without microcarrier dependence. Single-use bioreactor trains at 2000L scale displace adherent platform costs by factors of three to five. Lonza Group AG and Thermo Fisher Scientific anchor capacity investments across Swiss and US production nodes.
- Stable Producer Cell Lines:Integrated vector expression systems eliminating plasmid transfection requirements. Biopharma sponsors with internalized platforms capture cost advantages of 40-60% at commercial scale. This technology is compressing the viable addressable market for contract manufacturers lacking stable line capabilities.
- Transient Transfection:Plasmid-based expression in HEK293 or HEK293T systems. GMP-grade plasmid DNA production concentrates among fewer than ten qualified suppliers globally, creating input bottlenecks.
- Adherent Cell Culture:Microcarrier-dependent or flask-based production with lower scalability ceilings. Legacy contract manufacturers retain adherent suites for clinical-phase programs with modest volume requirements.
- Helper Virus-Free Systems:Packaging cell lines with integrated helper functions eliminating wild-type contamination risks. EMA's ATMP framework and FDA platform technology guidance both emphasize helper virus absence in release specifications.
Suspension cell culture leads volumes today; stable producer cell lines are expanding most quickly.
Application:
Customer maturity separates commercial-stage gene therapy from preclinical research, with regulatory pathway complexity and reimbursement risk determining procurement authority concentration.
- Gene Therapy:In vivo and ex vivo genetic medicine programs requiring GMP-grade vectors with full regulatory dossiers. FDA regenerative medicine advanced therapy designation compresses Phase 1-to-approval timelines, pulling forward capacity commitments.
- Cell Therapy:CAR-T, CAR-NK, and iPSC-derived product engineering with patient-specific or allogeneic vector requirements. Off-the-shelf programs require lentivirus at tenfold the per-patient volume of autologous approaches.
- Vaccine Development:Viral vector platforms for infectious disease prophylaxis, including pandemic preparedness stockpiling. Adenovirus and vesicular stomatitis virus backbones dominate this application.
- Immunotherapy:Oncolytic virus and cancer vaccine applications leveraging vector immunogenicity. Solid tumor indications drive demand for tumor-targeting specificity enhancements.
- Research & Development:Preclinical and discovery-phase vector production with reduced release testing burdens. Academic institutions and early-stage biotechnology companies sustain this segment.
Gene therapy leads volumes today; cell therapy is climbing the fastest.
End User:
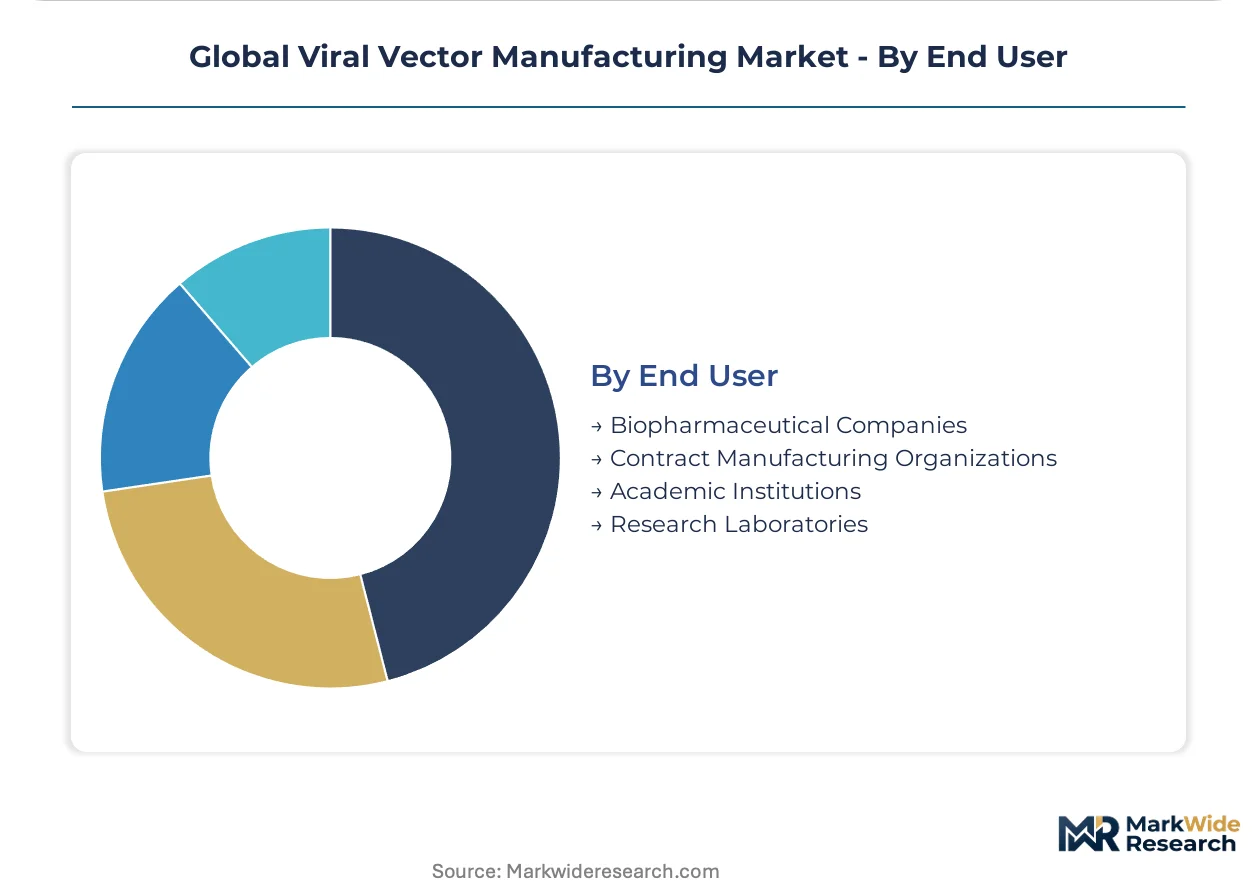
Supply chain configuration separates vertically integrated biopharma sponsors from externalized development models, with analytical capabilities and batch turnaround speed determining vendor selection.
- Biopharmaceutical Companies:Integrated sponsors with captive manufacturing or preferred CDMO partnerships. Charles River Laboratories International, Inc. competes through integrated testing and release services that compress batch turnaround times for this customer class.
- Contract Manufacturing Organizations:Externalized production specialists with platform technology offerings. CDMOs with captive analytical development groups displace point-solution testing houses in vendor selections.
- Academic Institutions:Research-grade vector production for investigator-initiated trials and preclinical studies. Procurement volumes concentrate at institutions with affiliated medical centers in Boston and San Francisco Bay Area clusters.
- Research Laboratories:Discovery-phase vector needs with reduced regulatory documentation requirements. Japan's PMDA tightened vector characterization guidelines add analytical depth expectations for Asian market entrants from this segment.
Biopharmaceutical companies lead volumes today; contract manufacturing organizations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy talent clusters in Boston and the San Francisco Bay Area anchor United States procurement volumes. Swiss and German manufacturing nodes concentrate stable producer cell line expertise. Japanese regulatory tightening creates compliance differentiation for Western manufacturers.
United States
FDA regenerative medicine advanced therapy designation compresses Phase 1-to-approval timelines for gene therapy developers. The agency's platform technology guidance enables comparability protocol acceptance that accelerates manufacturing changes. Boston and San Francisco Bay Area biotech clusters book multi-year viral vector capacity commitments ahead of clinical data readouts.
Switzerland
Lonza Group AG anchors capacity investments across Swiss production nodes serving European and North American sponsors. Swissmedic maintains alignment with EMA's evolving ATMP framework while offering streamlined scientific advice pathways. Basel-region facilities concentrate suspension cell culture expertise for lentivirus and AAV programs at commercial scale.
Germany
EMA's ATMP framework divergence from FDA guidance creates dual analytical package requirements for transatlantic sponsors. Merck KGaA leverages German chemical manufacturing heritage into GMP-grade plasmid DNA supply for transient transfection workflows. Heidelberg and Munich clusters house analytical development groups qualifying potency assays for European market entry.
Japan
PMDA tightened vector characterization guidelines add analytical depth expectations for Asian market entrants. Japanese sponsors booking lentivirus capacity for allogeneic CAR-T programs require extended release assays. Tokyo-Osaka biotech corridors attract Western CDMOs investing in localized testing capabilities.
United Kingdom
Oxford Biomedica anchors stable producer cell line capabilities from Oxfordshire manufacturing sites. MHRA post-Brexit regulatory autonomy enables accelerated access pathways diverging from EMA timelines. London-Cambridge biotech corridor procurement concentrates in integrated testing-and-release partnerships.
Global Viral Vector Manufacturing Market Competitive Landscape
The competitive structure tilts toward integrated life science conglomerates with captive analytical portfolios. CDMO specialists compete through batch turnaround compression and regulatory dossier integration. Three archetypes dominate: diversified laboratory services conglomerates, pure-play viral vector specialists, and diversified pharmaceutical service platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players position for stable producer cell line transitions.
Among diversified laboratory services conglomerates, Thermo Fisher Scientific Inc. and Charles River Laboratories International, Inc. exemplify the integrated testing-and-release model displacing point-solution vendors. Lonza Group AG occupies a position representing Swiss-based manufacturing scale specialists competing through geographic node distribution. These three anchors illustrate how regulatory dossier depth and analytical captive capabilities determine vendor selection in Boston and San Francisco Bay Area procurement clusters.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Lonza Group AG |
| Charles River Laboratories International, Inc. |
| Oxford Biomedica |
| Catalent Inc. |
| FUJIFILM Diosynth Biotechnologies |
| WuXi AppTec |
| Merck KGaA |
| Takara Bio Inc. |
| Others |
Supply & Pricing Matrix
GMP-grade plasmid DNA spot pricing volatility cascades through viral vector manufacturing tiers, compressing margins for transient transfection-dependent CDMOs while amplifying cost advantages for sponsors with stable producer cell line capabilities. This input cost sensitivity stratifies procurement power across integrated biopharma sponsors, externalized development programs, and academic research buyers.
Pricing Analysis
Bundled testing-and-release contracts versus unbundled manufacturing-only engagements define the pricing architecture for viral vector procurement. Three-tier pricing structure across premium, standard, and economy levels separates sponsors requiring full regulatory dossier support from research-grade buyers with reduced documentation needs. Pricing pressure stems from stable producer cell line adoption collapsing cost-of-goods targets for lentivirus and AAV programs. Academic institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while commercial-stage gene therapy developers prioritize batch turnaround speed over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with the concentrated GMP-grade plasmid DNA supplier base spanning the United States, Germany, and Switzerland. Viral vector production draws from HEK293 cell banks, recombinant helper plasmids, and chemically defined media formulations as critical inputs. Tariff exposure on European-sourced analytical instrumentation amplifies facility construction cost inflation for Asian market entrants. Distribution runs through integrated CDMO partnerships that compress batch release timelines for Boston and San Francisco Bay Area gene therapy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The viral vector manufacturing market reads as a late-cycle quality story as FDA regenerative medicine advanced therapy designation pulls demand toward GMP-grade specifications with full regulatory dossiers. Sponsors now prioritize analytical depth and batch consistency over unit cost minimization.
For Market Incumbents: Acquire stable producer cell line platforms to defend against integrated biopharma sponsors internalizing manufacturing capabilities. Incumbent CDMOs must retrofit transient transfection infrastructure or surrender high-volume contracts to sponsors with captive stable line operations. Capacity expansion in Swiss and German nodes anchors European market access amid EMA's evolving ATMP framework divergence from FDA guidance. For New Entrants and Emerging Players: Continuous bioprocessing technology offers entry wedge into the distributed manufacturing node segment serving decentralized cell therapy production. White-space targets include Japan's PMDA-aligned extended release assay capabilities and perfusion-linked continuous capture chromatography platforms. Allogeneic CAR-T engineering programs in solid tumor indications represent the most penetrable application segment for modular facility offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with CDMOs possessing captive analytical development groups displacing point-solution testing houses in vendor selections. Long-term viability over a five-to-ten year window favors platforms with demonstrated EMA scientific advice pathway navigation and FDA platform technology guidance alignment. The signal to watch is sponsor consolidation around integrated testing-and-release partnerships compressing batch turnaround times.| Strategic Initiative | Industry Significance |
|---|---|
| Stable Producer Cell Line Acquisition | Captive stable line platforms compress COGS by 40-60% at commercial scale for lentivirus programs. |
| PMDA-Aligned Analytical Investment | Extended release assay capabilities secure first-mover positioning in Japan's tightened regulatory environment. |
| Continuous Bioprocessing Integration | Perfusion culture linked to continuous capture chromatography collapses facility footprints for distributed nodes. |
| Integrated Testing-and-Release Partnership | CDMOs with captive analytical groups displace point-solution vendors in Boston and San Francisco procurement clusters. |
| Dual Regulatory Package Maintenance | Parallel FDA and EMA analytical dossiers prevent delayed European market entry from framework divergence. |
Research Methodology
Bottom-up gene therapy developer procurement modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads, vector manufacturing executives, hospital procurement managers, and analytical development directors combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CDMO capacity disclosure documents. Triangulation across these sources anchors segmentation-specific volume and value estimates.
Input-output matrices mapping vector type demand against technology platform supply capacity generate forecast outputs across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application modality, and end-user archetype alongside regional regulatory cluster differentiation. CAGRs derive from capacity expansion announcements, sponsor pipeline progression, and technology transition curves for stable producer cell line adoption.
The model holds under sustained FDA accelerated approval pathway utilization and EMA ATMP framework evolution; deviation in plasmid supply concentration or replication-competent virus testing regulatory stringency would shift capacity booking patterns and pricing trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market