
 Gene Panel Market | 2026-2036
Gene Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Panel Market Intelligence
Hybridization capture combined with massively parallel sequencing is rewriting how gene panels are designed and manufactured for clinical-grade output. Illumina leverages its installed base of sequencing instruments to sustain captive demand for its proprietary panel chemistries. Thermo Fisher Scientific anchors the competitive landscape through backward integration into reagent manufacturing and instrument platforms. QIAGEN differentiates by occupying the sample-to-insight workflow with automated nucleic acid extraction upstream of panel analysis.
A gene panel comprises a curated set of genes, typically ranging from dozens to several hundred, selected for simultaneous analysis via next-generation sequencing or PCR-based amplification to detect variants with clinical or research significance. Manufacturing employs oligonucleotide probe synthesis, target enrichment through hybridization capture, and quality control against reference standards such as those from the National Institute of Standards and Technology. Targeted panels dominate current clinical volume due to their cost efficiency and interpretability for known disease-associated genes, while custom panels represent the fastest-expanding segment as pharmaceutical companies design bespoke content for companion diagnostic development. Next-generation sequencing technology leads the technology split, though PCR retains share in laboratories requiring rapid turnaround for hotspot mutation detection.
The FDA regulates gene panels as in vitro diagnostics or laboratory-developed tests depending on commercial distribution model, directly shaping validation requirements and market access timelines. CLIA certification administered by the Centers for Medicare and Medicaid Services governs analytical performance standards for clinical laboratories performing gene panel testing. The European Union's In Vitro Diagnostic Regulation introduces new conformity assessment hurdles for panels marketed in member states. Stakeholders must monitor evolving reimbursement decisions from Medicare contractors and private payers, as coverage determinations for expanded gene panels will dictate whether clinical adoption outpaces current laboratory investment cycles.
Market Dynamics
Hybridization capture chemistry standardization is compressing manufacturing cost curves while simultaneously raising performance floors for clinical-grade gene panels, forcing smaller reagent suppliers to exit or specialize in narrow custom applications.
Growth Catalysts
- Hereditary Cancer Screening Expansion:Clinical diagnostic laboratories in the United States are scaling multi-gene hereditary cancer panels as Medicare contractors clarify reimbursement pathways for BRCA1/2 and Lynch syndrome testing.
- Companion Diagnostic Mandates:FDA guidance requiring validated biomarker testing prior to oncology drug administration is pulling pharmaceutical sponsors toward co-developed gene panel content.
- Hybridization Capture Efficiency:Advances in probe design algorithms and oligonucleotide synthesis are reducing hands-on time for targeted enrichment workflows in high-throughput sequencing facilities.
Market Restraints
- Oligonucleotide Supply Concentration:Synthesis capacity for high-fidelity capture probes clusters among a handful of specialized chemical manufacturers, creating input bottlenecks during demand surges.
- Laboratory-Developed Test Regulatory Uncertainty:FDA draft guidance on LDT enforcement is extending validation timelines and capital commitment horizons for hospital-based molecular pathology laboratories.
- PCR-Based Hotspot Testing:Rapid turnaround requirements in acute oncology settings preserve demand for digital PCR and amplification refractory mutation systems as substitutes for full panel sequencing.
Strategic Opportunities
- Pharmacogenomic Panel Integration:Polypharmacy management in geriatric populations creates white space for preemptive CYP2D6 and CYP2C19 testing alongside oncology content.
- Automated Sample-to-Insight Workflows:Integration of nucleic acid extraction robotics with cloud-based variant interpretation platforms is opening new channel economics for mid-volume hospital laboratories.
- EU IVDR Conformity Assessment:Early movers completing notified body certification for class C in vitro diagnostics are securing preferential distribution positioning across Germany, France, and the Netherlands.
Industry Challenges
- Bioinformatics Interpretation Bottleneck:Variant of uncertain significance classification consumes disproportionate genetic counselor and molecular pathologist FTE capacity relative to wet-lab processing.
- Multi-Instrument Validation Burden:Clinical laboratories maintaining both Illumina and Thermo Fisher sequencing platforms face duplicated analytical validation costs for equivalent gene panel content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Panel Market |
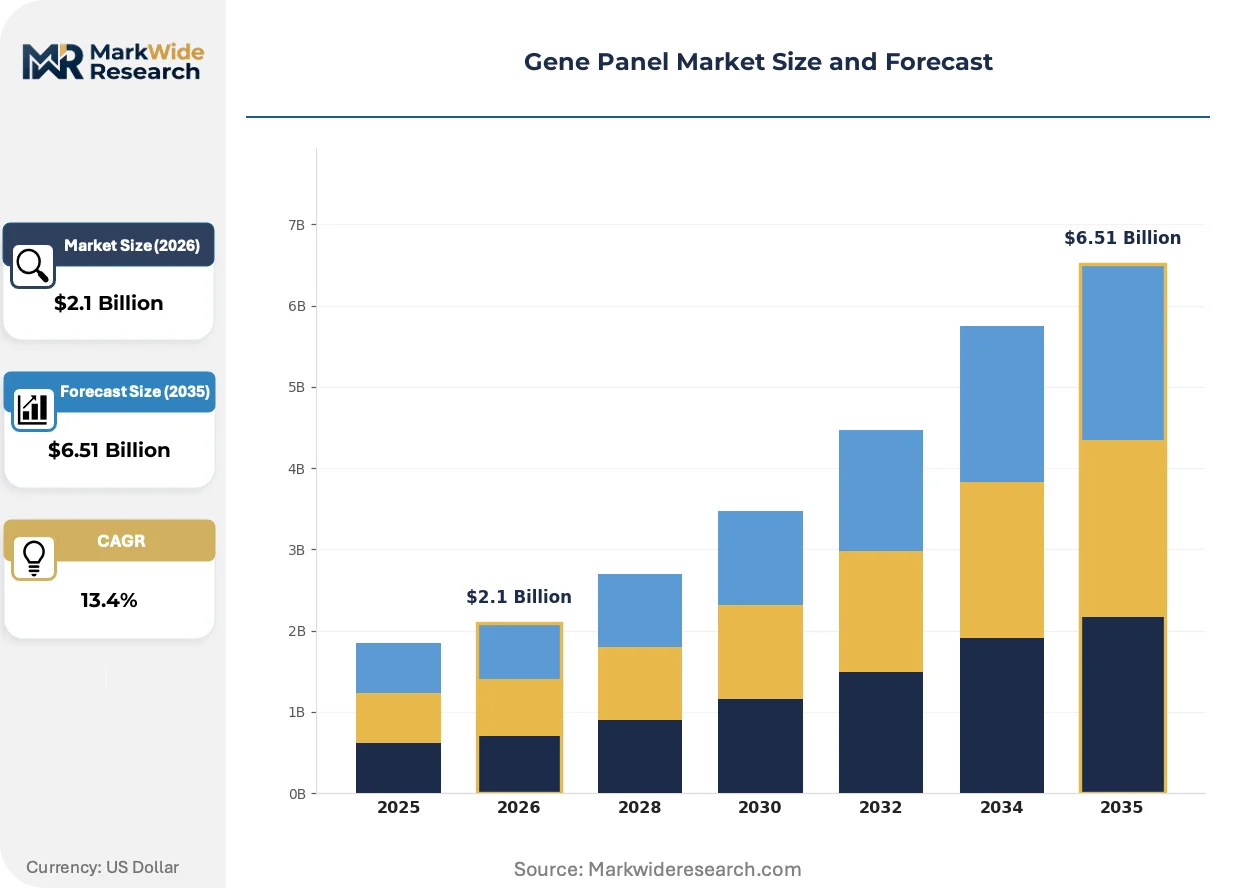
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Panels, Exome Sequencing Panels, Whole Genome Panels, Custom Panels Technology: Next-Generation Sequencing, PCR, Microarray, Sanger Sequencing End User: Hospitals, Diagnostic Labs, Research Institutions, Pharmaceutical Companies Application: Oncology, Rare Diseases, Prenatal Testing, Infectious Diseases |
| Companies Covered | Illumina, Thermo Fisher Scientific, Agilent Technologies, QIAGEN, F. Hoffmann-La Roche, Eurofins Scientific, BGI, Twist Bioscience, Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Panel Market Strategic Shifts & Innovations
Gene panel architecture is fragmenting into modular, indication-specific content blocks that laboratories can reconfigure without full revalidation, compressing product development cycles and enabling faster response to emerging clinical evidence.
Amplicon-based enrichment is collapsing the cost floor for targeted resequencing in laboratories with limited bioinformatics infrastructure. Community hospital pathology departments are adopting these streamlined workflows for hereditary cancer screening. The technology is collapsing the traditional performance gap between research-grade and clinical-grade output for small gene sets.
The European Union's In Vitro Diagnostic Regulation is mandating clinical evidence requirements for class C devices that previously operated under self-certification. Gene panel manufacturers are restructuring quality management systems to accommodate notified body audits and post-market surveillance obligations. Oncology companion diagnostic panels face the steepest conformity assessment hurdles, compressing the vendor base toward enterprises with dedicated regulatory affairs capacity.
Point-of-care molecular testing is fragmenting demand away from centralized reference laboratories toward hospital-based rapid turnaround units. Emergency oncology departments are acquiring tabletop sequencing instruments with pre-validated solid tumor gene panels. This behavioral shift is most pronounced in United States health systems pursuing vertical integration of precision medicine services under single episode-of-care reimbursement structures.
Gene Panel Market Segmentation
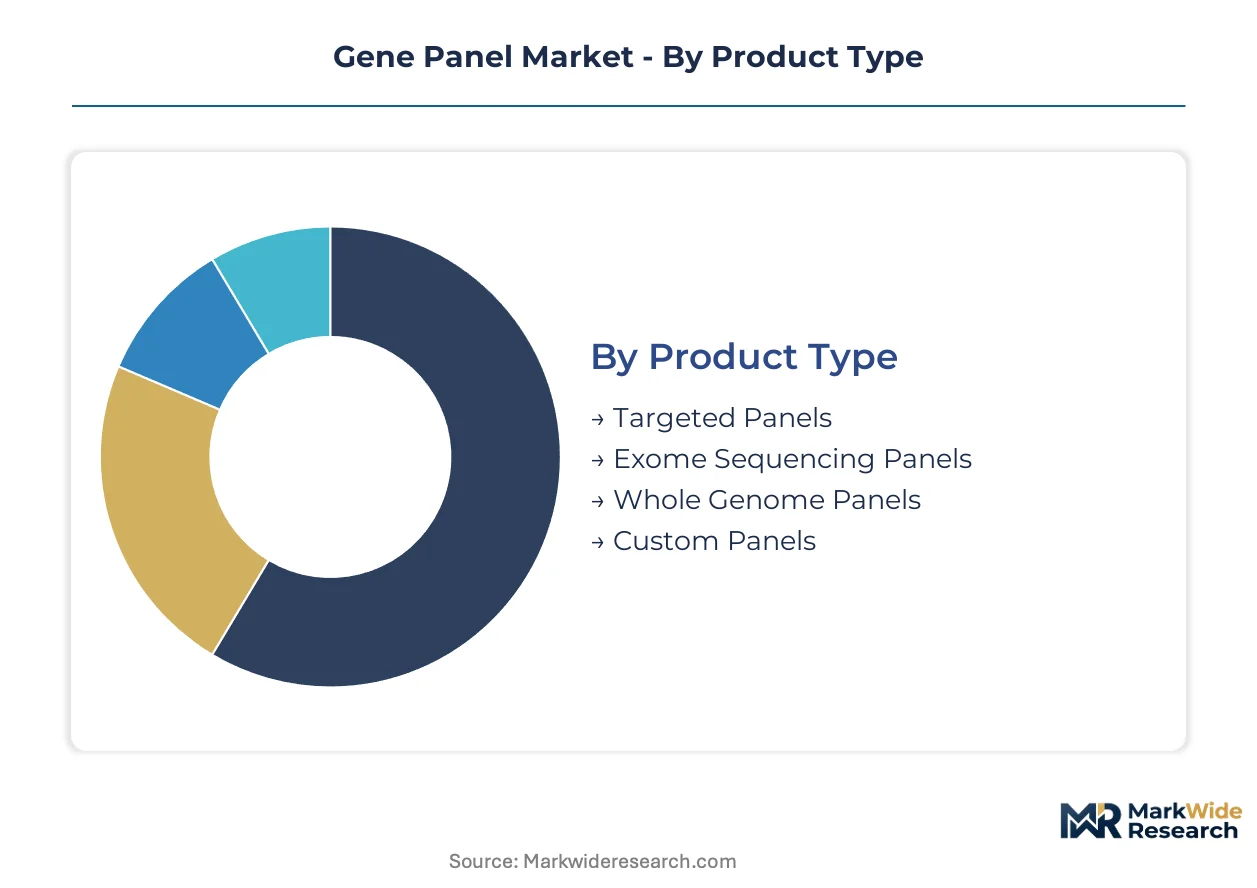
Gene panel segmentation reveals how technical specifications, clinical workflows, and regulatory pathways fragment purchasing decisions across healthcare systems. Manufacturers must align probe design, validation depth, and distribution channels to the distinct procurement criteria of each segment cluster.
Product Type:
Cost tier determines validation burden and reimbursement eligibility across panel architectures, with narrower gene sets commanding lower price points but facing compressed margins.
- Targeted Panels:Curated sets of 10-500 genes selected for specific disease associations, manufactured through hybridization capture or amplicon enrichment. Demand concentrates in United States hospital laboratories processing hereditary cancer referrals under Medicare contractor coverage determinations for BRCA1/2 and Lynch syndrome screening. Analytical validation costs scale linearly with gene count, favoring mid-sized panels that balance clinical actionability with interpretability.
- Custom Panels:Bespoke gene content designed for pharmaceutical companion diagnostic programs or rare disease research consortia. Pharmaceutical sponsors in the United States and Germany are commissioning co-developed panels to satisfy FDA and EMA biomarker testing mandates for oncology drug approval pathways. Manufacturing requires flexible oligonucleotide synthesis partnerships and modular validation frameworks to accommodate iterative content revisions.
- Exome Sequencing Panels:Protein-coding region coverage for undiagnosed genetic disease programs.
- Whole Genome Panels:Comprehensive genomic interrogation for research applications and complex structural variant detection.
Targeted Panels hold installed capacity. Custom Panels is rotating up the share rankings.
Technology:
Application urgency dictates platform selection, with turnaround time requirements fragmenting demand between high-throughput sequencing and rapid amplification methods.
- Next-Generation Sequencing:Massively parallel sequencing of millions of DNA fragments enables simultaneous variant detection across hundreds of genes. United States clinical diagnostic laboratories dominate installed instrument bases, with Illumina and Thermo Fisher platforms anchoring high-volume hereditary cancer and oncology workflows. Hybridization capture chemistry standardization is compressing reagent costs while raising analytical performance floors.
- PCR:Amplification-based detection of known mutations delivers results in hours rather than days. Emergency oncology departments in United States health systems preserve PCR demand for EGFR and KRAS hotspot testing where treatment decisions cannot await sequencing turnaround. Digital PCR and amplification refractory mutation systems retain share in acute care settings despite lower multiplexing capacity.
- Microarray:Solid-state hybridization for copy number variation and SNP genotyping in prenatal and constitutional applications.
- Sanger Sequencing:Gold-standard orthogonal confirmation method for variant validation in clinical reporting workflows.
Next-Generation Sequencing holds installed capacity. PCR is rotating up the share rankings.
End User:
Customer type shapes procurement scale, with centralized reference laboratories demanding bulk reagent contracts and hospital laboratories prioritizing automated workflow integration.
- Diagnostic Labs:High-throughput reference facilities processing thousands of gene panel tests monthly. United States national laboratories such as Quest Diagnostics and LabCorp negotiate multi-year reagent supply agreements with manufacturers, leveraging volume to compress per-test costs. CLIA certification requirements and FDA in vitro diagnostic regulations govern analytical validation and quality management systems.
- Pharmaceutical Companies:Sponsors of companion diagnostic development programs requiring bespoke panel content and regulatory submission support. Oncology drug developers in the United States and Switzerland are co-investing in gene panel validation to satisfy FDA and Swissmedic biomarker testing prerequisites for targeted therapy approval. Procurement emphasizes regulatory affairs capacity and notified body relationships for EU IVDR conformity.
- Hospitals:Mid-volume molecular pathology departments with limited bioinformatics infrastructure.
- Research Institutions:Academic medical centers and genomics consortia driving exploratory panel applications.
Diagnostic Labs holds installed capacity. Pharmaceutical Companies is rotating up the share rankings.
Application:
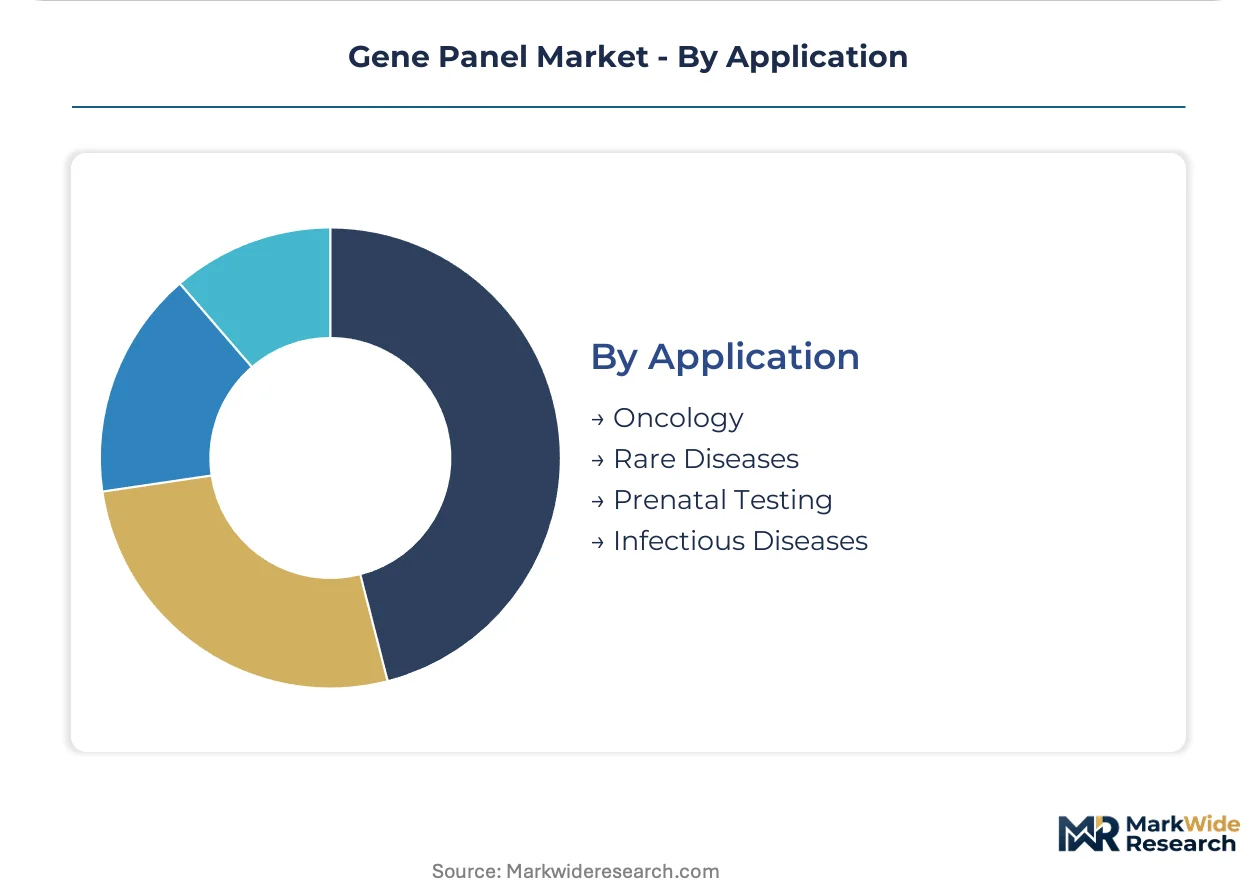
Volume concentration varies by disease prevalence and reimbursement maturity, with oncology commanding the largest share of clinical-grade panel deployment.
- Oncology:Solid tumor and hematologic malignancy profiling for therapy selection and clinical trial enrollment. United States cancer centers are expanding multi-gene panel adoption as Medicare contractors clarify coverage for comprehensive genomic profiling. FDA guidance requiring validated biomarker testing prior to targeted therapy administration is pulling pharmaceutical sponsors toward co-developed panel content.
- Rare Diseases:Exome and targeted panel sequencing for undiagnosed genetic conditions in pediatric and adult populations. Academic medical centers in Germany, France, and the Netherlands are consolidating rare disease expertise through national genomic medicine programs under EU-funded research frameworks. Diagnostic yield improvements are driving panel expansion beyond single-gene testing for Mendelian disorders.
- Prenatal Testing:Non-invasive and invasive screening for fetal aneuploidy and single-gene conditions.
- Infectious Diseases:Pathogen detection and antimicrobial resistance profiling in outbreak and clinical microbiology settings.
Oncology holds installed capacity. Rare Diseases is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratories and pharmaceutical sponsors concentrate purchasing power in markets with mature reimbursement frameworks and biomarker testing mandates. National regulatory pathways for in vitro diagnostics shape where manufacturers prioritize distribution partnerships and clinical validation investments.
United States
Medicare contractors have clarified coverage determinations for BRCA1/2 and Lynch syndrome screening, accelerating multi-gene panel adoption in hospital-based molecular pathology departments. The FDA regulates commercial gene panels as in vitro diagnostics while exercising enforcement discretion over laboratory-developed tests, creating dual pathways that extend validation timelines for hospital laboratories. The Boston-Cambridge corridor anchors companion diagnostic development, with pharmaceutical sponsors co-investing in panel validation to satisfy biomarker testing prerequisites for oncology drug approvals.
Germany
National genomic medicine programs under EU-funded research frameworks are consolidating rare disease expertise through academic medical centers in Berlin and Heidelberg. The EU In Vitro Diagnostic Regulation introduces notified body conformity assessment requirements that compress the vendor base toward enterprises with dedicated regulatory affairs capacity. The Munich-Stuttgart axis concentrates pharmaceutical R&D investment, where sponsors commission bespoke gene panels to satisfy EMA biomarker testing mandates for targeted therapy development.
China
NMPA regulatory reforms are streamlining in vitro diagnostic registration pathways for oncology companion diagnostics, pulling domestic and multinational manufacturers toward localized clinical validation studies. Government-funded precision medicine initiatives in Shanghai and Shenzhen are expanding sequencing infrastructure in tertiary hospitals. The Yangtze River Delta cluster dominates domestic manufacturing of oligonucleotide synthesis equipment and reagent chemistries.
United Kingdom
NHS Genomic Medicine Service contracts are consolidating hereditary cancer screening into regional genomic laboratory hubs in Manchester, Birmingham, and London. The Medicines and Healthcare products Regulatory Agency aligns with EU IVDR transition timelines for post-market surveillance obligations. The Cambridge-London corridor maintains concentration in academic-industry partnerships for rare disease panel development.
Switzerland
Swissmedic biomarker testing requirements for oncology drug approvals are pulling pharmaceutical sponsors toward co-validated gene panel content. Basel anchors Roche's global diagnostics headquarters and associated supplier ecosystems for hybridization capture chemistries. The country's centralized healthcare procurement system favors long-term supply agreements with manufacturers demonstrating ISO 13485 quality management certification.
Gene Panel Market Key Industry Players
Channel-controlling players compete with product-specialist players across three structural tiers. Sequencing platform manufacturers leverage installed instrument bases to sustain captive demand for proprietary chemistries, while independent reagent suppliers pursue modular probe design capabilities to serve custom panel workflows. Strategic archetypes include vertically integrated platform-chemistry combinations, sample-to-insight workflow specialists, and flexible oligonucleotide synthesis partners. Competitive moves concentrate on regulatory submission partnerships for companion diagnostic co-development and automation integration for mid-volume hospital laboratories.
Among sequencing platform manufacturers, Illumina and Thermo Fisher Scientific anchor competitive positioning through backward integration into reagent manufacturing. QIAGEN occupies the sample-to-insight workflow archetype with automated nucleic acid extraction systems upstream of panel analysis. These three entities represent the dominant competitive anchors, with specialization depth determining relative positioning across clinical diagnostic and pharmaceutical sponsor segments.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| Agilent Technologies |
| QIAGEN |
| F. Hoffmann-La Roche |
| Eurofins Scientific |
| BGI |
| Twist Bioscience |
| Guardant Health |
| Others |
Cost & Logistics Intelligence
Oligonucleotide synthesis capacity clusters in the Yangtze River Delta and South Korea, anchoring margin pools with probe manufacturers and hybridization capture chemistry suppliers who command premium pricing during demand surges for clinical-grade gene panels.
Pricing Analysis
Cost-plus contracts with oligonucleotide suppliers index to phosphoramidite precursor costs and synthesis throughput, insulating panel manufacturers from raw material volatility while compressing flexibility. Pricing stratifies across premium, standard, and economy tiers based on analytical validation depth and FDA in vitro diagnostic classification, with pharmaceutical companion diagnostic programs showing least price sensitivity due to regulatory co-development requirements. Cost compression in standard-tier targeted panels is intensifying as hybridization capture chemistry standardization erodes reagent differentiation. Hospital-based molecular pathology laboratories exhibit highest price sensitivity, prioritizing per-test economics under fixed Medicare reimbursement schedules.
Supply Chain Analysis
Extended payment terms from sequencing platform manufacturers to oligonucleotide suppliers stretch working capital cycles, with supply-chain finance facilities emerging among mid-tier reagent vendors to bridge cash flow gaps. Manufacturing concentration rests on China, South Korea, and the United States for phosphoramidite precursors, oligonucleotide synthesizers, and sequencing instruments respectively. Critical dependencies include high-fidelity DNA polymerases, magnetic bead purification systems, and certified reference materials. Single-source vulnerability concentrates in specialized probe design software and NIST-traceable variant standards. Distribution runs through direct sales forces for pharmaceutical sponsors and diagnostic laboratory contracts, with group purchasing organizations intermediating hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene panel architecture is fragmenting into modular content blocks, a disruption accelerated by FDA guidance mandating validated biomarker testing prior to oncology drug administration and compressing product development cycles for clinical-grade output.
For Market Incumbents: Build regulatory submission moats through dedicated FDA and EMA companion diagnostic partnership teams, co-investing in panel validation with pharmaceutical sponsors to lock out emerging entrants. Deepen backward integration into oligonucleotide synthesis capacity in South Korea and China to secure probe supply during demand surges. Acquire automated nucleic acid extraction robotics capabilities to defend sample-to-insight workflow positioning against QIAGEN's integrated platform threat. For New Entrants and Emerging Players: Pursue pharmacogenomic panel integration for polypharmacy management in geriatric populations, a white-space segment underserved by oncology-focused incumbents. Target mid-volume hospital laboratories in United States health systems pursuing vertical integration of precision medicine services under episode-of-care reimbursement. Deploy cloud-based variant interpretation platforms as the go-to-market angle, circumventing bioinformatics infrastructure barriers that constrain community hospital adoption. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed oligonucleotide synthesis specialists and regional diagnostic laboratory chains with CLIA-certified molecular pathology capacity. Long-term viability hinges on EU IVDR conformity assessment completion and notified body relationships for class C in vitro diagnostics. Watch FDA draft guidance on laboratory-developed test enforcement as the signal for validation timeline compression and capital commitment horizon extension.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Secures FDA biomarker testing mandates for oncology drug approvals with pharmaceutical sponsors. |
| EU IVDR Notified Body Certification | Unlocks distribution positioning across Germany, France, and Netherlands for class C devices. |
| Automated Sample-to-Insight Workflow Integration | Captures mid-volume hospital laboratory demand with nucleic acid extraction robotics. |
| Modular Gene Panel Architecture Development | Enables reconfiguration without full revalidation for faster clinical evidence response. |
| Point-of-Care Sequencing Instrument Deployment | Fragments demand from centralized reference labs toward emergency oncology departments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare coverage determinations, and EU IVDR notified body certification databases. Primary interviews engaged clinical laboratory directors, pharmaceutical regulatory affairs leads, genetic counselor program managers, and hospital procurement officers across the United States, Germany, and China. Secondary validation drew from ClinicalTrials.gov companion diagnostic listings, SEC 10-K instrument manufacturer disclosures, and national genomic medicine program reports. Bottom-up gene panel test volume estimates triangulate against top-down sequencing reagent market sizing.
Forecast inputs span product type segmentation across targeted, custom, and exome architectures; technology splits between next-generation sequencing and PCR; and end-user channels including diagnostic laboratories, pharmaceutical sponsors, and hospital systems. Modeled variables incorporate hybridization capture chemistry cost curves, CLIA certification expansion rates, and Medicare contractor coverage clarification timelines. CAGRs derive from segment-level volume projections weighted by reimbursement maturity and regulatory pathway velocity.
Macroeconomic conditions sit as an overlay; deviation in biotech venture funding availability or pharmaceutical R&D budget allocation would shift the trajectory. Forecasts reflect assumptions regarding FDA enforcement discretion continuity and EU IVDR transition timeline adherence. Regulatory restriction tightening, oligonucleotide supply disruption, or bioinformatics interpretation bottleneck intensification would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market