
 Europe Digital Battlefield Market | 2026-2036
Europe Digital Battlefield Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Battlefield Market Analytics
European defense electronics manufacturing is broadening output capacity for next-generation combat management systems. BAE Systems leverages deep sovereign partnerships across the United Kingdom to sustain long-term platform integration contracts. Rheinmetall anchors German land-system digitization programs through its combat vehicle electronics division. Thales Group competes across Franco-Belgian-Dutch corridors with sensor-to-shooter network architectures.
The Europe Digital Battlefield encompasses integrated software-hardware ecosystems that fuse real-time intelligence, communications, and command-and-control functions for military operations, typically operating over encrypted waveforms with sub-100-millisecond latency thresholds for fire-coordination loops. Communication Systems and Artificial Intelligence segments currently command the largest margin pools as NATO allies prioritize resilient beyond-line-of-sight networks and predictive logistics algorithms. Cloud Computing deployment models for battlefield edge nodes represent the fastest-expanding structural category, though On-Premises hardened infrastructure retains dominance in nuclear command-and-control contexts.
EMA and EDA procurement frameworks shape cross-border defense technology access, while EU AI Act risk-classification rules constrain autonomous weapon system development pathways. REACH and RoHS compliance requirements filter component suppliers for battlefield hardware destined for European arsenals. Stakeholders must track how forthcoming EU defence-industry consolidation mandates redistribute platform-versus-subsystem contract boundaries across member state procurement authorities.
Market Dynamics
NATO's networked command modernization is compressing procurement cycles for AI-enabled fire-coordination systems, forcing defense electronics suppliers to restructure R&D roadmaps around EU AI Act certification timelines rather than traditional platform upgrade schedules.
Growth Catalysts
- European Defence Fund co-financing:Joint procurement frameworks pool member state budgets for cross-border sensor-to-shooter networks, lowering per-unit system costs for national armies.
- Sub-100-millisecond latency requirements:NATO's fire-coordination loop standards mandate edge-computing upgrades, pulling hardened battlefield servers into frontline vehicle electronics.
- France:The nation's Scorpion armored vehicle program embeds digital battle management systems as standard, creating reference architectures adopted by Belgian and Czech land forces.
Market Restraints
- Gallium nitride foundry concentration:European radar and electronic warfare subsystem suppliers depend on a limited semiconductor fabrication base, exposing programs to single-source chokepoints.
- EU AI Act high-risk system classification:Autonomous target recognition modules face mandatory conformity assessments that extend development timelines by 18-24 months.
- Legacy waveform incompatibility:New encrypted IP-based networks cannot interoperate with existing narrowband combat net radios without gateway investments that strain maintenance budgets.
Strategic Opportunities
- Poland:Accelerated defense modernization under the Homeland Defence Act creates demand gaps for indigenous command-and-control integration partners.
- Quantum-resistant cryptography:Post-quantum algorithm standardization by ETSI offers first-mover positioning for communications security vendors.
- Cloud-edge hybrid architectures:Containerized battlefield applications deployed via Kubernetes orchestration enable software-defined capability upgrades without hardware swaps.
Industry Challenges
- Cleared software engineering talent scarcity:National security vetting pipelines cannot match demand for developers with both NATO SECRET clearances and AI/ML specializations.
- Cross-domain integration complexity:Air-land-maritime data link standardization across national stovepipes requires bilateral technical agreements that stall multi-national program milestones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Battlefield Market |
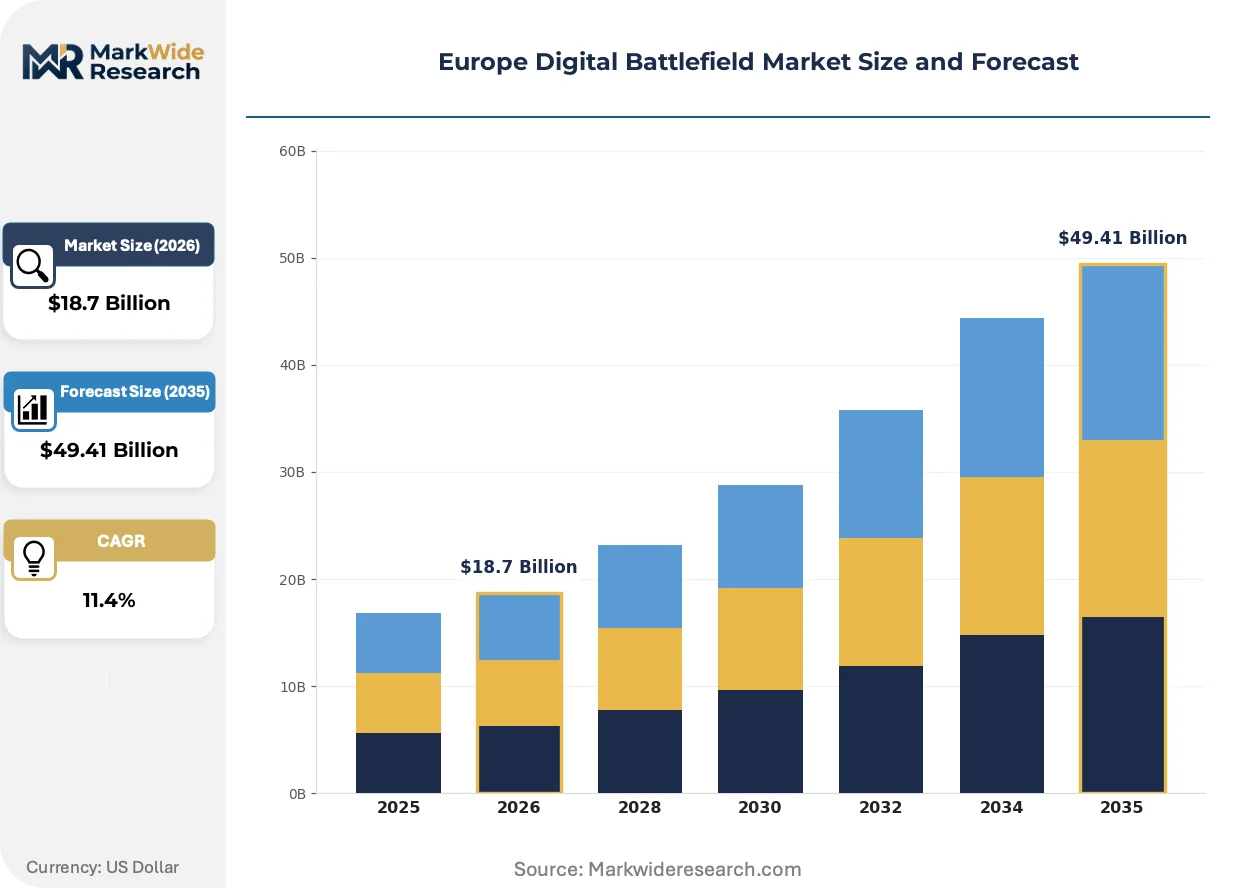
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Software, Communication Systems, Decision Support Tools, Training Equipment Technology: Augmented Reality, Virtual Reality, Artificial Intelligence, Cloud Computing End User: Military Organizations, Defense Contractors, Security Agencies, Research Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | BAE Systems, Rheinmetall, Airbus Defence & Space, Leonardo, Thales Group, Saab AB, ATOS SE, Elbit Systems Ltd, L3Harris Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Battlefield Market Evolving Landscape
Battlefield digitization is shifting from platform-centric upgrades to ecosystem-wide software architectures, compressing the boundary between tactical communications and command intelligence.
Software-defined radio (SDR) waveforms are replacing fixed-frequency hardware in combat vehicle electronics, enabling spectrum agility against electronic warfare threats. German and French land systems commands are mandating SDR modularity in new procurements. This flexibility is converging with open systems architecture standards, collapsing proprietary subsystem lock-in that previously protected incumbent suppliers.
EU AI Act risk-classification rules now govern autonomous target engagement algorithms, requiring human-in-the-loop documentation for lethal decision support tools. Defense ministries in the Netherlands and Spain are rewriting technical specifications to embed these audit requirements. The artificial intelligence segment faces the steepest compliance cost inflation as developers retrain models on explainable decision trees.
Buyer organizations are unbundling hardware procurement from software sustainment, separating platform purchase contracts from algorithm update subscriptions. British Army and Swedish Armed Forces pilot programs now treat predictive maintenance analytics as distinct budget lines. This shift is most visible in Nordic countries, where defense materiel administrations lack internal AI development capacity and rely on vendor-managed service layers.
Europe Digital Battlefield Market Segmentation
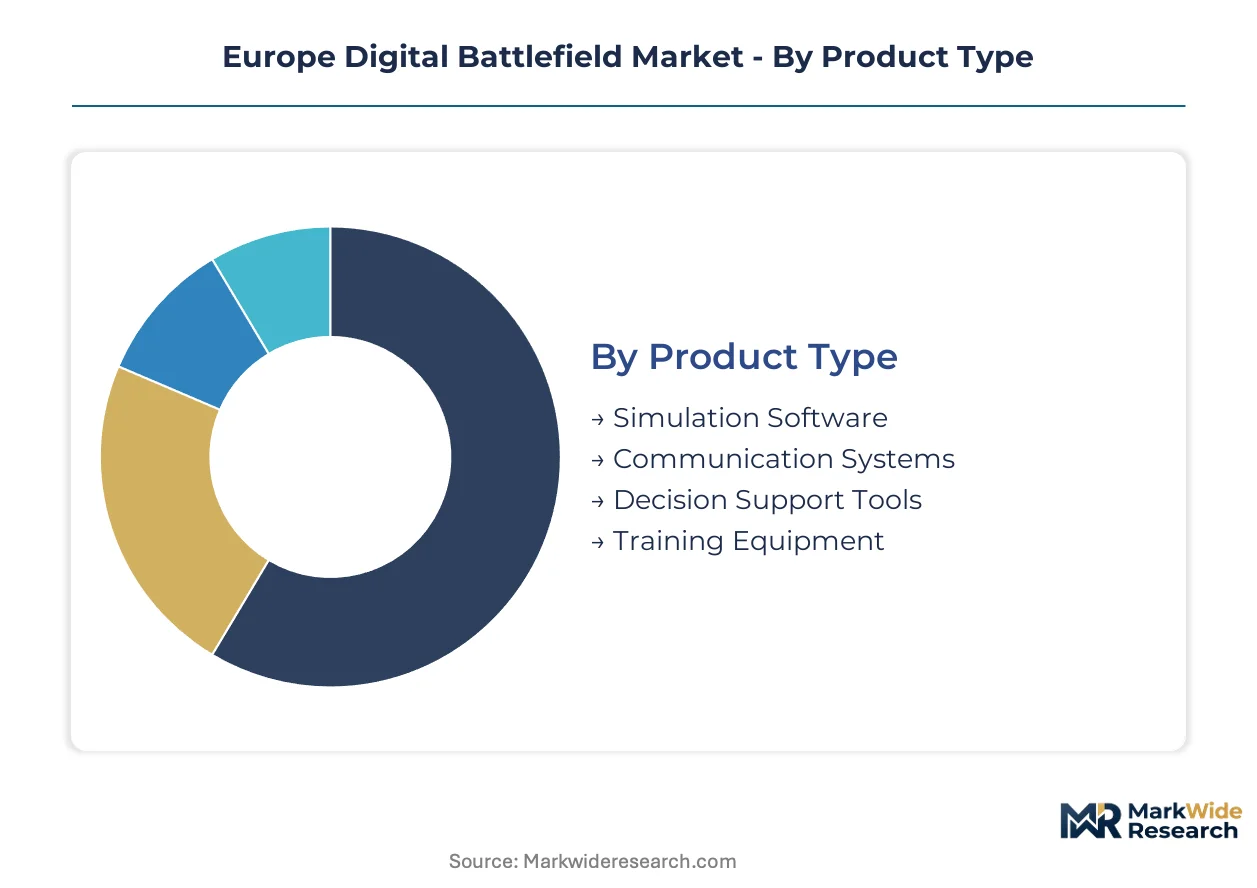
Segmentation in the Europe Digital Battlefield Market reveals how procurement budgets fragment across hardware-intensive platforms versus software-centric services. Capital deployment patterns differ sharply between sovereign defense ministries and cross-border consortium frameworks.
Product Type:
Capital-intensity varies dramatically across product categories, with hardware platforms demanding multiyear sovereign investment cycles while software tools attract faster procurement through defense innovation funds.
- Communication Systems:Hardened military-grade networks integrate software-defined radio waveforms with quantum-resistant encryption protocols. German and French land forces are consolidating procurement around NATO's ESSOR waveform standards, driving interoperability mandates across Belgian and Dutch joint programs.
- Artificial Intelligence:Machine learning pipelines for predictive logistics and target recognition require substantial GPU cluster investments at national data centers. EU AI Act high-risk system classifications extend development timelines for autonomous engagement algorithms, compressing vendor margins.
- Simulation Software:Synthetic training environments replicate electromagnetic spectrum conditions for electronic warfare rehearsal. British Army synthetic collective training contracts prioritize vendor-managed service models.
- Decision Support Tools:Command-and-control dashboards fuse multi-source intelligence into actionable fire-coordination recommendations. Polish defense modernization programs under the Homeland Defence Act create demand gaps for indigenous integration partners.
- Training Equipment:Physical simulators and tactical engagement systems replicate vehicle crew procedures. Nordic defense materiel administrations lack internal development capacity and rely on external sustainment layers.
Most installed capacity flows through Communication Systems. Expansion is steepest in Artificial Intelligence.
Technology:
Technology segments stratify by maturity curve, with established digital infrastructure competing against emerging immersive and distributed computing paradigms for platform integration slots.
- Cloud Computing:Containerized battlefield applications deployed via Kubernetes orchestration enable software-defined capability upgrades without hardware swaps. British Army and Swedish Armed Forces pilot programs treat predictive maintenance analytics as distinct budget lines.
- Artificial Intelligence:Explainable decision trees replace black-box neural networks for lethal decision support tools. Netherlands and Spain defense ministries embed audit requirements in technical specifications.
- Augmented Reality:Heads-up displays overlay tactical data onto physical environments for dismounted soldier situational awareness. French Scorpion vehicle programs mandate AR integration for crew stations.
- Virtual Reality:Immersive rehearsal systems replicate complex operational environments for mission planning. German land systems commands prioritize VR modularity in new procurement frameworks.
Cloud Computing is gaining share fastest among technology segments. Artificial Intelligence retains the largest committed R&D allocation.
End User:
End user categories reflect distinct procurement authority structures, with sovereign military organizations controlling platform budgets while contractors and research institutions access innovation funding streams.
- Military Organizations:National armed forces direct platform-centric modernization through defense ministry acquisition channels. NATO's networked command modernization compresses procurement cycles for AI-enabled fire-coordination systems.
- Defense Contractors:Prime system integrators subcontract subsystem development to specialized electronics suppliers. BAE Systems leverages deep sovereign partnerships across the United Kingdom for long-term integration contracts.
- Security Agencies:Domestic intelligence and border security services procure surveillance and counter-terrorism digital infrastructure. EMA and EDA procurement frameworks shape cross-border technology access.
- Research Institutions:University and government laboratories validate emerging concepts through European Defence Fund co-financing. Joint procurement frameworks pool member state budgets for cross-border sensor-to-shooter networks.
Defense Contractors absorb the largest subcontracting volume. Research Institutions are climbing the fastest in funding allocation.
Deployment:
Deployment models segment by infrastructure sovereignty requirements, with hardened on-site systems competing against distributed architectures for resilience against electronic warfare threats.
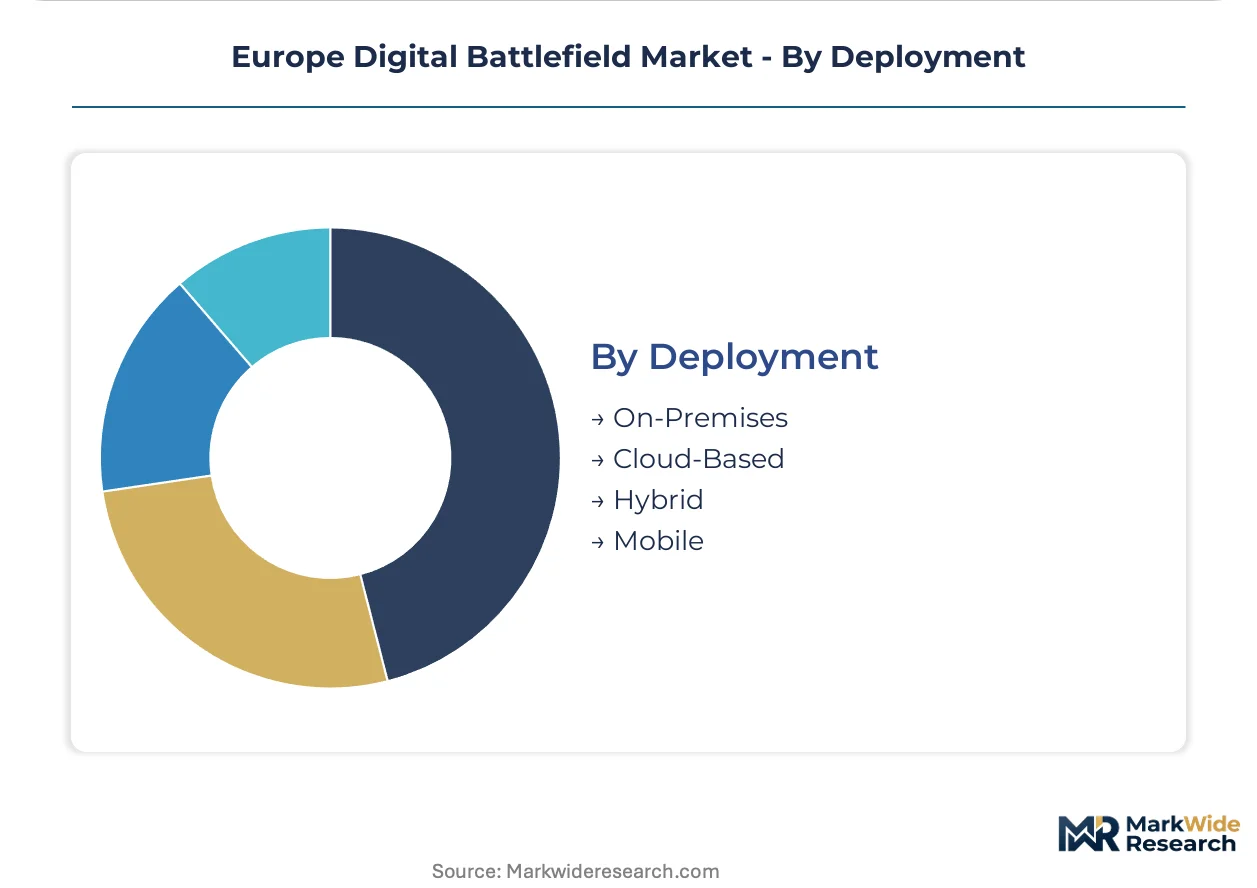
- On-Premises:Hardened battlefield servers in frontline vehicle electronics meet sub-100-millisecond latency thresholds for fire-coordination loops. Nuclear command-and-control contexts mandate air-gapped infrastructure.
- Hybrid:Cloud-edge architectures synchronize tactical data between forward nodes and rear-area processing centers. Containerized applications enable capability upgrades without hardware swaps.
- Cloud-Based:Centralized processing pools support logistics and intelligence functions with relaxed latency constraints. Nordic defense administrations rely on vendor-managed service layers.
- Mobile:Dismounted soldier systems and vehicle-mounted tactical networks operate under contested electromagnetic spectrum conditions. Spectrum agility against electronic warfare threats drives software-defined radio adoption.
On-Premises retains dominance in committed infrastructure. Hybrid architectures show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany channels substantially higher land-system digitization investment than France, though both nations anchor NATO's networked command modernization through divergent procurement frameworks.
Germany
Rheinmetall anchors combat vehicle electronics production for the Bundeswehr's land-system digitization programs. The European Defence Fund co-financing mechanisms pool member state budgets for cross-border sensor-to-shooter networks. Bavaria's defense industrial corridor concentrates subsystem fabrication for hardened battlefield servers meeting sub-100-millisecond latency thresholds.
United Kingdom
BAE Systems leverages sovereign partnerships across British defense infrastructure for long-term platform integration contracts. NATO's ESSOR waveform standards drive interoperability mandates through Ministry of Defence acquisition channels. The South West England cluster houses electronics manufacturing for encrypted beyond-line-of-sight military networks.
France
The Scorpion armored vehicle program embeds digital battle management systems as standard reference architectures adopted by Belgian and Czech land forces. EU AI Act risk-classification rules constrain autonomous target recognition module development pathways. The Île-de-France region concentrates Thales Group's sensor-to-shooter network architecture design centers.
Poland
Accelerated defense modernization under the Homeland Defence Act creates demand gaps for indigenous command-and-control integration partners. REACH and RoHS compliance requirements filter component suppliers for battlefield hardware destined for Polish arsenals. The Warsaw-Łódź corridor attracts subcontracting relationships for combat vehicle electronics fabrication.
Netherlands
Dutch defense ministries rewrite technical specifications to embed EU AI Act audit requirements for lethal decision support tools. EMA and EDA procurement frameworks shape cross-border technology access for Royal Netherlands Army modernization. The Eindhoven-Tilburg region hosts simulation software development for synthetic collective training environments.
Europe Digital Battlefield Market Competitive Landscape
British and German producers anchor one tier; Franco-Italian specialists hold adjacent positions in sensor and platform integration. The vendor base concentrates around prime system integrators subcontracting to specialized electronics suppliers, creating a tiered structure with sovereign champions at the apex. Three archetypes dominate: land-system electronics houses, communications security vendors, and cross-domain platform integrators. Competitive moves center on strategic partnerships for waveform standardization and portfolio diversification into AI-enabled decision support tools.
Within the land-system electronics tier, Rheinmetall GmbH and BAE Systems plc exemplify sovereign-anchored platform integration specialists. Thales Group S.A. occupies a position bridging Franco-Belgian-Dutch corridors with network-centric architectures. These three entities represent the dominant competitive anchors shaping procurement boundaries across NATO member state defense ministries.
| Leading Market Players |
|---|
| BAE Systems |
| Rheinmetall |
| Airbus Defence & Space |
| Leonardo |
| Thales Group |
| Saab AB |
| ATOS SE |
| Elbit Systems Ltd |
| L3Harris Technologies |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense electronics producers anchor European supply capacity, translating state-supported R&D into pricing discipline that resists commoditization despite procurement budget pressures. This ownership structure concentrates supply planning around long-term platform integration cycles rather than spot-market responsiveness, embedding cost predictability into multi-year contracts.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for hardened battlefield servers and software-defined radio modules. Three-tier pricing structure across mission-critical, standard military, and economy commercial-off-the-shelf levels dominates procurement frameworks, with certification grade under EU AI Act and NATO ESSOR interoperability standards driving differentiation. Cost compression in edge-computing hardware is intensifying because gallium nitride foundry investments lag demand, while defense contractors show least price sensitivity due to sovereign co-financing mechanisms.
Supply Chain Analysis
Regional distribution centers in Bavaria, South West England, and Île-de-France coordinate hub-and-spoke patterns for classified component logistics. Manufacturing concentrates in Germany, France, and the United Kingdom, with semiconductor fabrication drawing from Taiwan, the United States, and domestic European foundries. Gallium nitride substrates, quantum-resistant encryption chipsets, and hardened server chassis represent critical input dependencies. Single-source vulnerability in GaN wafer supply creates structural risk. Distribution runs through national defense materiel administrations with NATO SECRET clearance protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European defense digitization represents a late-cycle quality story as NATO allies shift procurement toward AI-enabled decision support tools with sub-100-millisecond latency specifications.
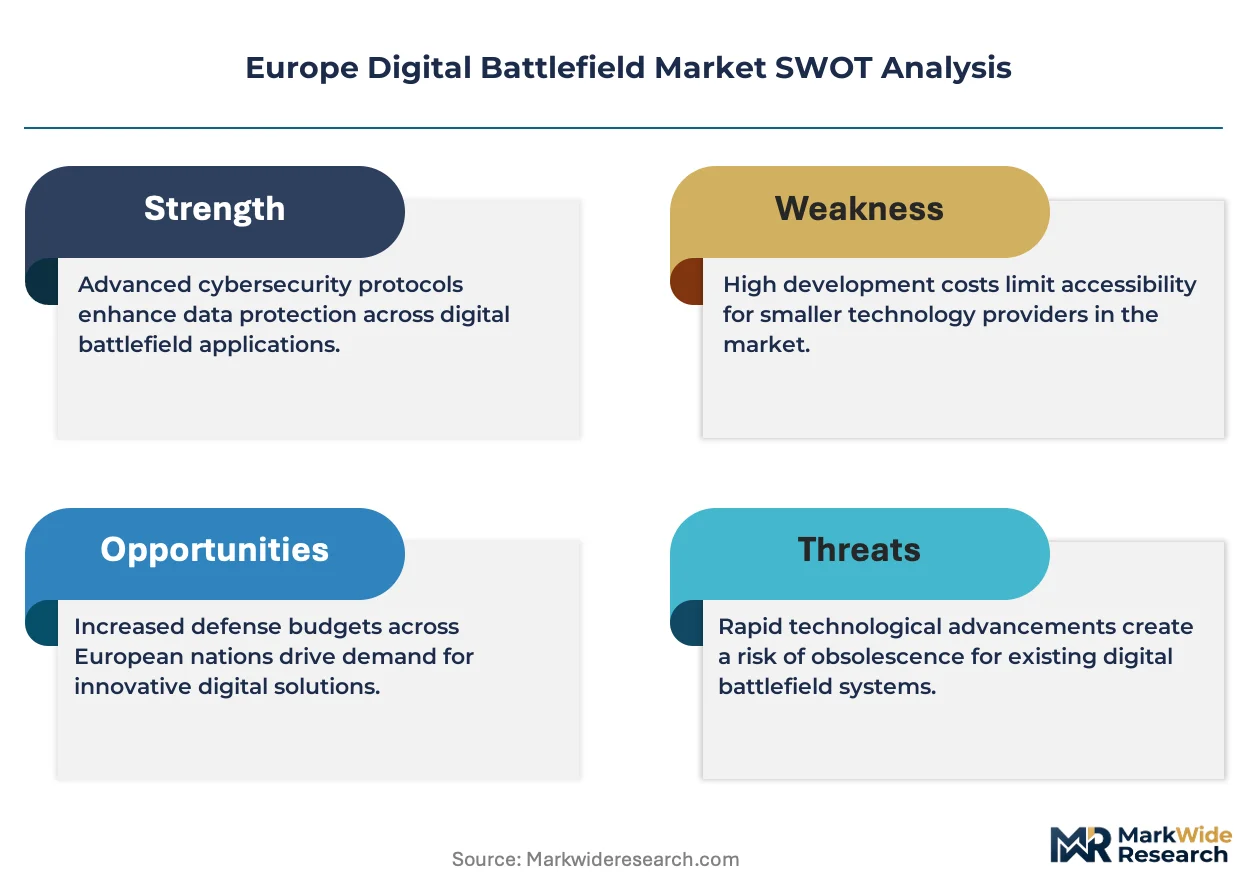
For Market Incumbents: Anticipate margin compression from EU AI Act compliance timelines extending development cycles by 18-24 months. Defensive consolidation through backward integration into gallium nitride component supply secures against single-source chokepoints. Certification investment in explainable decision-tree architectures for lethal support tools protects platform integration contracts from emerging AI specialists. For New Entrants and Emerging Players: Capture white-space in Polish command-and-control integration gaps created by Homeland Defence Act acceleration. Quantum-resistant cryptography modules offer the most penetrable segment given ETSI standardization timelines. Go-to-market through vendor-managed service layers addresses Nordic defense administrations lacking internal AI development capacity. For Investors and Strategic Acquirers: Prime system integrators with sovereign platform relationships are the most active acquirer in this space. Long-term viability rests on software-defined capability upgrade revenue streams decoupled from hardware replacement cycles. Acquisition targets should show Kubernetes-orchestrated containerized battlefield applications. The signal to watch is EU defence-industry consolidation mandates redistributing platform-versus-subsystem contract boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Thales Group and Rheinmetall embed audit-ready explainable AI to secure French and German platform contracts. |
| Software-Defined Radio Waveform Standardization | NATO ESSOR adoption across Belgian and Dutch forces collapses proprietary lock-in for incumbent communications suppliers. |
| Cloud-Edge Hybrid Architecture Deployment | British Army pilot programs treat predictive maintenance analytics as distinct subscription revenue lines. |
| Quantum-Resistant Cryptography Development | ETSI post-quantum algorithm standardization offers first-mover positioning for communications security vendors. |
| Cross-Border Sensor-to-Shooter Network Integration | European Defence Fund co-financing pools member state budgets for Franco-German-Dutch joint procurement frameworks. |
Research Methodology
Bottom-up defense ministry procurement modeling reconciled against top-down prime contractor order-book tracking forms the analytical core of this study. Primary interviews with program managers at national armed forces, platform integration engineers at Rheinmetall and BAE Systems, EDA procurement officers, and AI/ML specialists with NATO SECRET clearances combined with secondary validation from EDA annual reports, NATO capability targets, EU AI Act regulatory filings, and national defense budget appropriations documents. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of land-system digitization spending patterns informed projection frameworks across the modeling period. Segmentation dimensions modeled include product type, deployment architecture, end-user procurement authority, and national regulatory cluster. CAGRs derive from weighted capacity expansion schedules and procurement cycle compression factors. Forecast inputs incorporate EU AI Act implementation timelines and NATO networked command modernization milestones.
Underlying measurement precision varies by segment; Communication Systems and Artificial Intelligence carry tighter precision than Simulation Software due to disclosed contract values. Forecasts reflect documented assumptions about sovereign budget continuity and waveform interoperability adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Military Tent and Shelter Market