
 Global CBRN Defense Market | 2026-2036
Global CBRN Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Global CBRN Defense Market Analysis
A shift from single-source to multi-source procurement is repositioning how defense ministries secure CBRN capabilities. Teledyne FLIR leverages thermal imaging integration across detection platforms to sustain technology leadership. Rheinmetall Defence anchors European supply through armored vehicle-integrated protection systems. Smiths Group PLC competes on portable detection footprint, differentiating its product line for mobile military units.
CBRN defense encompasses protective equipment, detection architectures, and decontamination systems engineered to counter chemical, biological, radiological, and nuclear threats, with filtration systems typically rated at 99.97% particulate efficiency against aerosolized agents. Detection systems dominate procurement budgets as militaries prioritize early warning over passive protection, while AI integration represents the fastest-expanding technology segment as autonomous threat identification reduces operator response latency. Training services occupy a mature, stable margin pool anchored by recurring certification requirements.
FDA, EPA, and NATO Standardization Office frameworks govern equipment interoperability and chemical agent testing protocols, with CE marking under EU MDR and REACH compliance creating divergent certification pathways for transatlantic suppliers. Japan's METI coordinates national stockpile standards with JIS specifications for domestic manufacturers. Stakeholders must monitor how emerging dual-use export controls reshape component sourcing across allied defense industrial bases.
Market Dynamics
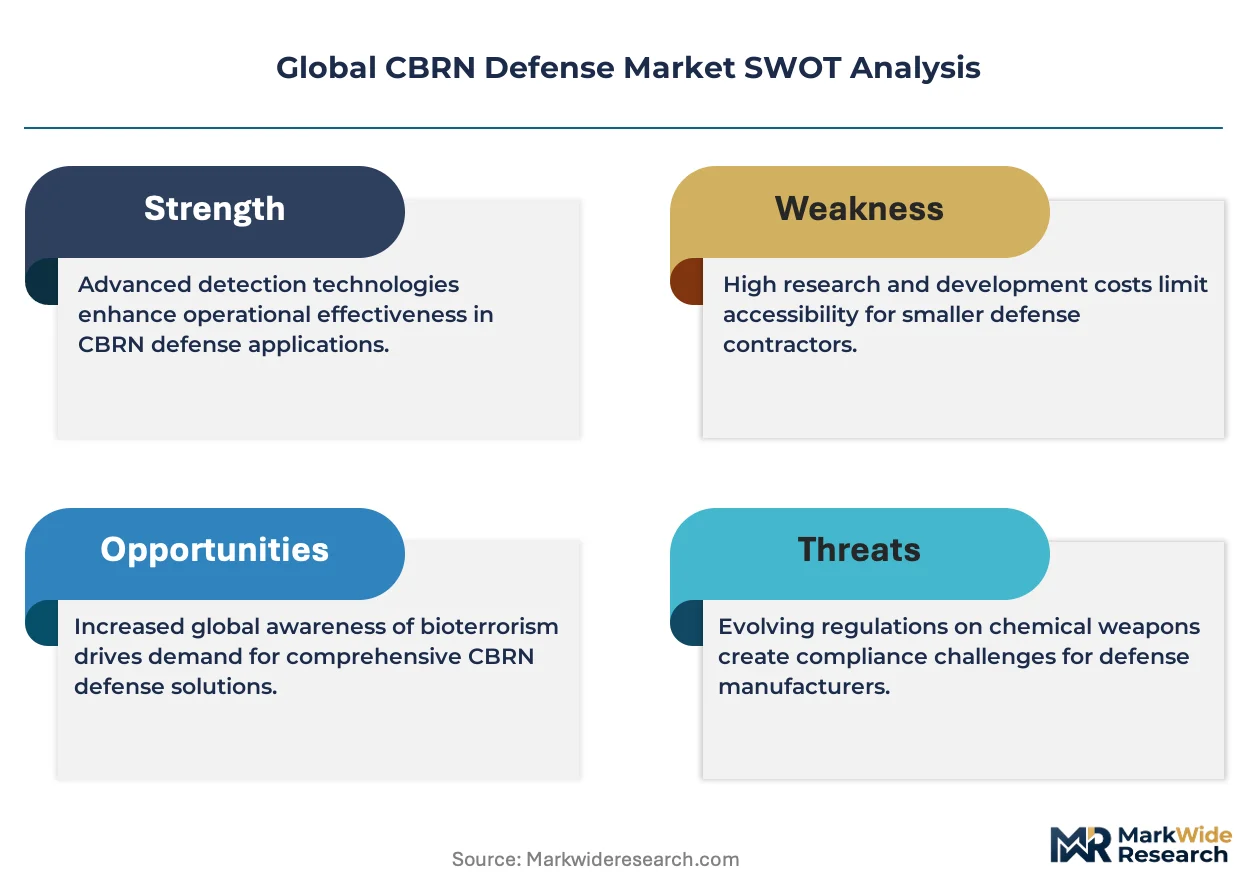
Multi-source procurement mandates from NATO defense ministries are fragmenting supplier relationships and compressing contract cycles, forcing incumbents to restructure pricing architectures and localize production footprints.
Growth Catalysts
- EU Green Deal chemical hazard protocols:Tighter equipment certification requirements under REACH and EU MDR are mandating next-generation detection sensitivity standards. Defense ministries across Germany, France, and Italy must replace legacy inventories.
- AI-enabled autonomous threat identification:Machine learning integration reduces operator response latency in battlefield conditions. Military procurement agencies prioritize early warning systems over passive protection.
- Japan's METI stockpile modernization:JIS specification updates for domestic manufacturers are accelerating replacement cycles for aging CBRN defense infrastructure in Tokyo and Osaka industrial corridors.
Market Restraints
- Specialized filtration media concentration:Activated carbon and HEPA substrate supply concentrates among a limited set of chemical suppliers, creating input cost volatility for 99.97% efficiency-rated systems.
- Dual-use export control expansion:Emerging component sourcing restrictions across allied defense industrial bases complicate cross-border supply chain configuration for detection electronics.
- Interoperability certification delays:Divergent NATO Standardization Office and FDA testing protocols extend equipment validation timelines, freezing procurement decisions.
Strategic Opportunities
- Urban mass transit integration:Unpenetrated demand exists for portable detection footprints in Tokyo, London, and New York subway authorities seeking mobile unit deployment.
- Training service unbundling:Recurring certification requirements for military operators create recurring revenue pools independent of hardware sales cycles.
- Thermal imaging convergence:Integration of infrared detection with chemical sensors enables multi-threat identification from single platforms.
Industry Challenges
- Legacy system integration complexity:Armored vehicle-integrated protection systems must interface with decades-old command architectures without full platform replacement.
- Specialized operator skill scarcity:AI-augmented detection systems require personnel trained in both chemical agent identification and machine learning interface management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CBRN Defense Market |
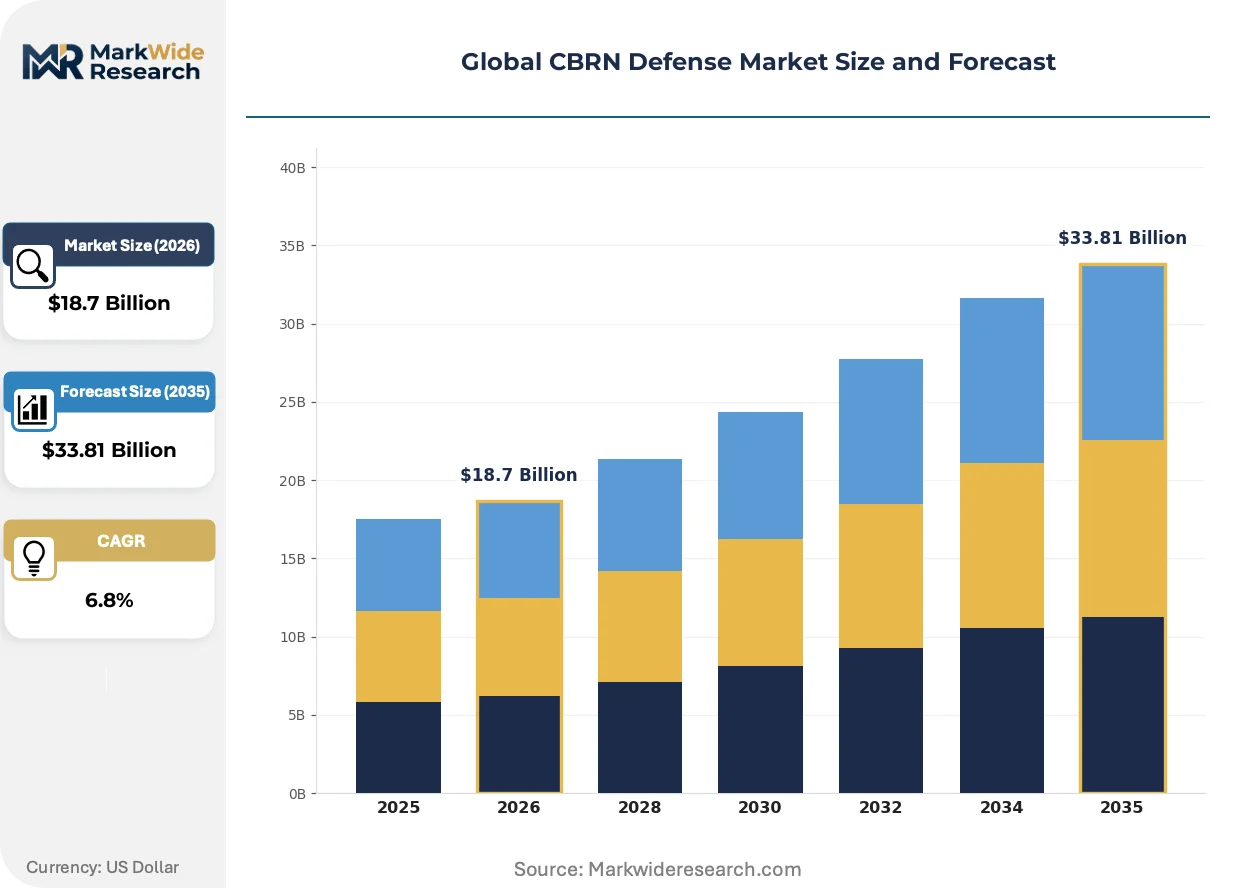
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Suits, Detection Systems, Decontamination Equipment, Training Services Application: Military, Civilian Defense, Emergency Services, Industrial Safety End User: Government Agencies, Defense Contractors, First Responders, Private Security Technology: Filtration Systems, Chemical Sensors, Robotics, AI Integration |
| Companies Covered | Teledyne FLIR LLC, Argon Electronics (UK) Ltd, Thales Group, Battelle, Avon Polymer Products Limited, Rheinmetall Defence, Bruker Corporation, Leidos Inc., Smiths Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CBRN Defense Market Emerging Trajectories
Synthetic biology threat proliferation and autonomous platform deployment are compressing the gap between detection and response, reshaping how defense agencies prioritize capability investments.
AI-driven spectral analysis is consolidating standalone detection modalities into unified threat identification platforms. Military units in Germany and the United States are field-testing these systems at accelerated procurement cycles. The technology is consolidating vendor portfolios as multi-function platforms displace single-purpose equipment.
REACH compliance deadlines under the EU Green Deal are forcing reformulation of decontamination chemistries and detection reagents. Industrial consequence includes accelerated R&D spending on biodegradable neutralizing agents. Portable detection manufacturers serving mobile military units face the steepest certification cost increases.
Defense ministries are unbundling hardware procurement from training and sustainment services. Traditional prime contractors face disintermediation as specialized training providers secure direct certification contracts. This pattern is most visible in United States Army and Marine Corps modernization programs.
Global CBRN Defense Market Segmentation
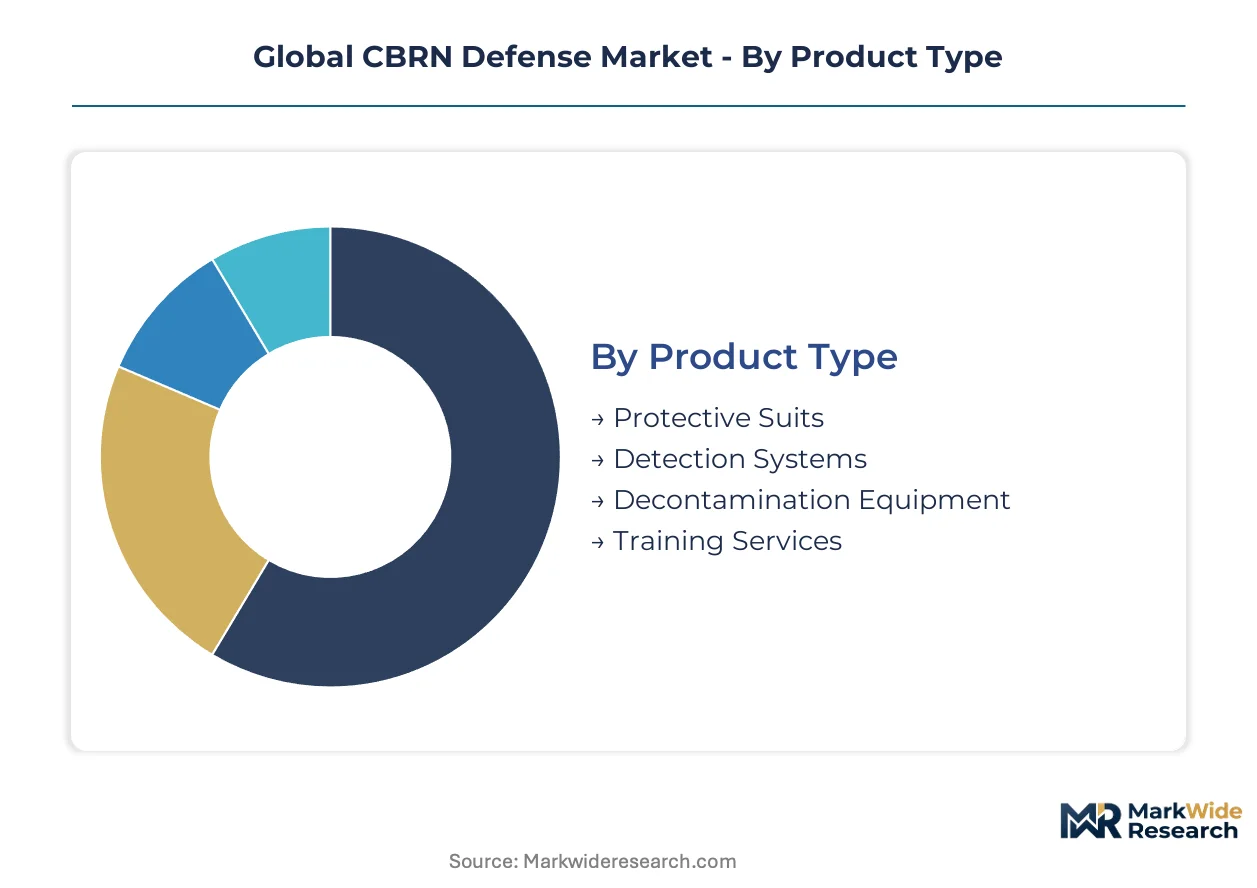
Segmentation in CBRN defense reveals how procurement priorities diverge between mass-volume protective equipment and premium-priced autonomous detection platforms. Understanding these splits exposes where margin pools concentrate and which technology trajectories command capital allocation from defense ministries.
Product Type:
Detection Systems anchor procurement budgets at premium pricing tiers, while Protective Suits generate volume through mandatory inventory replacement cycles across NATO forces.
- Detection Systems:Spectral analysis platforms integrating chemical sensors with thermal imaging achieve 99.97% aerosolized agent identification accuracy. United States Army modernization programs prioritize these over passive protection, compressing procurement cycles for autonomous threat identification capabilities.
- Protective Suits:Full-body encapsulation garments with activated carbon filtration layers meet NATO Standardization Office interoperability protocols. German Bundeswehr and French Armée de Terre maintain mandated replacement schedules, creating predictable volume demand independent of threat environment.
- Decontamination Equipment:Mobile shower systems and neutralizing agent sprayers for vehicle and personnel cleansing operations.
- Training Services:Recurring certification programs for military operators and first responders governed by national stockpile standards.
Today's leader: Detection Systems. Tomorrow's challenger: Training Services.
Application:
Military end-use concentrates R&D investment and commands performance premiums, while Civilian Defense applications face tighter budget constraints and divergent certification pathways.
- Military:Armored vehicle-integrated protection systems and portable detection footprints for mobile units operating in contested environments. Japan's Self-Defense Forces and United States Marine Corps drive specifications for AI-enabled platforms reducing operator response latency.
- Civilian Defense:Urban mass transit detection networks and public shelter filtration systems. Tokyo Metropolitan Government and London Underground authorities represent unpenetrated demand for portable deployment configurations.
- Emergency Services:Rapid-response kits for fire departments and hazardous materials teams requiring JIS or CE marking compliance.
- Industrial Safety:Chemical plant perimeter monitoring and worker protection systems under REACH and EPA frameworks.
Military segments capture margin. Civilian segments expand addressable market breadth.
End User:
Government Agencies control sovereign procurement authority, while Defense Contractors intermediate technology integration and sustainment services.
- Government Agencies:Defense ministries and homeland security departments specifying NATO Standardization Office or FDA testing protocols. Germany's BAAINBw and Japan's METI coordinate national stockpile standards directly with domestic manufacturers.
- Defense Contractors:System integrators consolidating subcomponent supply and managing localization requirements under emerging dual-use export controls.
- First Responders:Municipal fire and police departments procuring through federal grant programs with equipment certification mandates.
- Private Security:Corporate protection units at critical infrastructure facilities requiring portable detection capabilities.
Sovereign buyers set specifications. Contractor intermediaries capture implementation value.
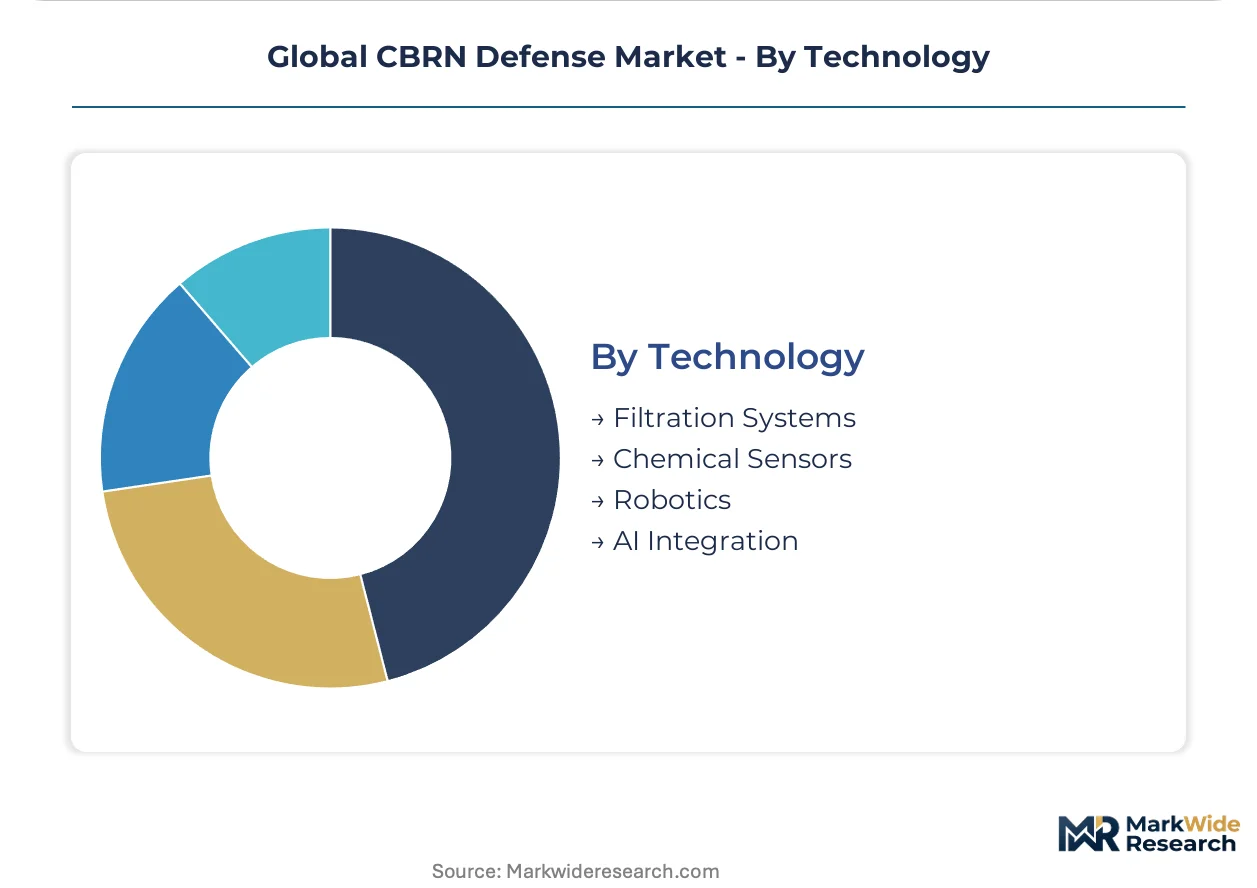
Technology:
AI Integration commands development resources and procurement premiums, while Filtration Systems represent mature, cost-optimized infrastructure.
- AI Integration:Machine learning algorithms enabling autonomous spectral analysis and multi-threat identification from unified platforms. Field testing accelerates in Germany and the United States as militaries consolidate vendor portfolios around multi-function systems.
- Filtration Systems:HEPA substrates and activated carbon media rated at 99.97% particulate efficiency. Supply concentrates among limited chemical suppliers, creating input cost volatility for manufacturers.
- Chemical Sensors:Point detection and standoff identification technologies for specific agent classes.
- Robotics:Unmanned platforms for reconnaissance and decontamination in contaminated environments.
AI Integration climbs the fastest. Filtration Systems defend installed base revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense procurement anchors CBRN modernization budgets, with military specifications cascading to allied standardization frameworks across NATO and Indo-Pacific security partnerships.
United States
Army and Marine Corps modernization programs prioritize AI-enabled detection platforms that reduce operator response latency in contested environments. FDA and EPA testing protocols govern chemical agent validation for domestic manufacturers. The Washington DC-Boston corridor concentrates system integrators managing NATO Standardization Office interoperability requirements.
Germany
Bundeswehr armored vehicle-integrated protection systems drive demand for legacy platform compatibility without full replacement cycles. BAAINBw procurement authority enforces REACH and EU MDR certification timelines under EU Green Deal chemical hazard protocols. Bavaria's defense industrial cluster hosts manufacturers localizing production footprints for multi-source NATO mandates.
Japan
Self-Defense Forces stockpile modernization accelerates replacement cycles for aging detection infrastructure in Tokyo and Osaka industrial corridors. METI coordinates JIS specification updates with domestic manufacturers to reduce import dependency. The Kanto region concentrates portable detection R&D for mobile unit deployment specifications.
United Kingdom
London Underground authority procurement represents unpenetrated demand for portable detection footprints in urban mass transit networks. CE marking under EU MDR creates divergent certification pathways for transatlantic suppliers post-Brexit. The Southeast England defense cluster manages NATO interoperability testing for armored platform integration.
France
Armée de Terre maintains mandated protective suit replacement schedules independent of threat environment fluctuations. ANSM and CNIL frameworks govern dual-use export control compliance for detection electronics. The Provence-Alpes-Côte d'Azur region concentrates decontamination equipment manufacturers serving Mediterranean naval bases.
Global CBRN Defense Market Vendor Landscape
Global majors compete with regional champions across technology integration and sovereign procurement access. The vendor base separates into three tiers: thermal imaging specialists anchoring premium detection platforms, armored vehicle system integrators capturing vehicle-integrated contracts, and portable equipment fabricators serving mobile military units. Consolidation pressures intensify as multi-source procurement mandates fragment supplier relationships. Dominant competitive moves include strategic partnerships for AI algorithm licensing and geographic expansion through in-country production facilities.
Within the thermal imaging tier, Teledyne FLIR LLC exemplifies sensor convergence strategies. Rheinmetall Defence occupies a position in European armored platform integration. Smiths Group PLC anchors the portable detection segment for mobile unit specifications. These three represent distinct competitive archetypes responding to NATO procurement fragmentation.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Argon Electronics (UK) Ltd |
| Thales Group |
| Battelle |
| Avon Polymer Products Limited |
| Rheinmetall Defence |
| Bruker Corporation |
| Leidos Inc. |
| Smiths Group PLC |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between NATO Standardization Office-validated systems and commercial-grade equipment manifests in both procurement premiums and supply chain localization requirements. REACH and EU MDR compliance timelines force tiered sourcing strategies, with German and Japanese manufacturers absorbing qualification costs while spot-market suppliers face exclusion from defense ministry contracts.
Pricing Analysis
Activated carbon and HEPA substrate volatility passes through to 99.97% efficiency-rated filtration systems, compressing margins for portable detection manufacturers. Three-tier pricing structure across NATO-certified, CE-marked, and commercial-grade equipment reflects divergence in testing protocol stringency. Cost compression in protective suits intensifies because Bundeswehr and French Armée de Terre mandate volume replacement schedules independent of threat cycles. Civilian defense buyers exhibit highest price sensitivity, while military procurement agencies prioritize performance premiums over unit economics.
Supply Chain Analysis
CE marking under EU MDR and FDA testing protocols gates component sourcing for detection electronics, fragmenting qualified supplier pools. Germany, Japan, and the United States anchor specialized filtration media production, drawing from activated carbon substrate and spectral sensor chip inputs. Single-source vulnerability concentrates in HEPA membrane supply for 99.97% efficiency systems. Distribution runs through defense ministry procurement authorities and NATO Standardization Office certification channels rather than open commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in CBRN defense rests on AI-enabled platform consolidation displacing single-purpose equipment, while training service unbundling captures recurring revenue independent of hardware cycles.
For Market Incumbents: To counter multi-source procurement fragmentation, anchor NATO Standardization Office interoperability certification as a switching-cost barrier. Backward integration into activated carbon filtration media reduces input cost volatility from chemical supplier concentration. Direct training certification contracts with United States Army and Marine Corps modernization programs bypass prime contractor disintermediation.
For New Entrants and Emerging Players: Capture unpenetrated urban mass transit demand in Tokyo, London, and New York subway authorities seeking portable detection footprints. Municipal procurement through federal grant programs offers lower certification barriers than sovereign defense ministry contracts. Position on rapid deployment specifications and JIS compliance for Japanese METI-coordinated stockpiles.
For Investors and Strategic Acquirers: Consolidation pressure builds where AI algorithm licensing gaps separate thermal imaging specialists from spectral analysis platform integrators. Five-to-ten year viability favors vendors with captive training certification revenue and armored vehicle integration relationships. Watch for METI JIS specification updates accelerating Japanese domestic manufacturer preference as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Licensing Partnership | Machine learning integration reduces operator response latency for German Bundeswehr field testing programs. |
| In-Country Production Facility Establishment | Bavaria defense cluster localization satisfies NATO multi-source procurement mandates for Rheinmetall-tier suppliers. |
| Training Certification Direct Contracting | United States Army unbundling creates recurring revenue pools independent of hardware procurement cycles. |
| Thermal Imaging Sensor Convergence | Teledyne FLIR integration strategies consolidate multi-threat identification into single-platform specifications. |
| Biodegradable Decontamination Chemistry R&D | REACH compliance deadlines under EU Green Deal force reformulation of neutralizing agent supply chains. |
Methodological Framework
Bottom-up military procurement modeling reconciled against top-down detection system production tracking forms the analytical core of this study. Primary interviews with defense ministry procurement officers, NATO Standardization Office certification specialists, armored vehicle platform engineers, and hazardous materials training directors combined with secondary validation from FDA 510(k) filings, ECHA REACH registration databases, METI JIS specification updates, and customs trade data for activated carbon and HEPA substrate flows. Triangulation across bottom-up segment builds and top-down supplier capacity assessments ensures coherence in volume and value outputs.
Historical trendline analysis of replacement cycle timing, AI integration adoption curves, and certification cost trajectories informed projection framework construction across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology, with additional granularity on NATO versus non-NATO procurement authority. CAGRs derived from weighted average of historical growth pattern extrapolation and driver-based elasticity modeling, incorporating METI stockpile modernization schedules and EU Green Deal chemical hazard protocol implementation timelines as industry-specific inputs.
Dual-use export control expansion, REACH compliance deadline acceleration, and synthetic biology threat classification revisions are the dominant revision risks to forecast assumptions. A model refresh is warranted upon material change in NATO Standardization Office testing protocol harmonization or JIS specification update timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Global Soldier Modernization Market