
 Military Optoelectronic System Market | 2026-2036
Military Optoelectronic System Market Size, Share, and Industry Trends Forecast 2026-2036
Military Optoelectronic System Market Insights
Market Context
US defense prime contractors is restructuring their optoelectronic supply chains around domestic rare-earth processing and gallium arsenide wafer fabrication. Lockheed Martin leverages captive production of focal plane arrays to secure margins on next-generation targeting systems. Teledyne FLIR sustains technology leadership in uncooled microbolometer architectures for soldier-borne thermal weapon sights. L3Harris anchors its position through classified programs spanning image intensification and laser designator fusion.
Technical Definition and Segments
A military optoelectronic system integrates photonic sensors, signal processors, and display modules to detect, track, and identify objects across ultraviolet through long-wave infrared spectra, typically operating at detection ranges from hundreds of meters to exceed twenty kilometers depending on aperture and atmospheric conditions. The technology serves commanders who require passive or active electro-optical capability for precision engagement in denied electromagnetic environments. Thermal imagers built on microbolometer arrays now dominate procurement budgets as forces prioritize passive targeting in electronic warfare-contested theaters. Night vision devices remain the most mature segment with replacement cycles driving steady revenue, while laser rangefinders represent the fastest-expanding category due to distributed fire-control architecture in ground combat vehicles. Image intensifiers concentrate margin pools among sole-source tube suppliers with ITAR-controlled manufacturing lines.
Regulatory Environment
The US International Traffic in Arms Regulations and the State Department's Directorate of Defense Trade Controls constrain technology transfer for image intensifier tubes and cooled infrared detectors, effectively segmenting the vendor base between cleared domestic producers and restricted foreign participants. The EU's REACH chemicals framework and RoHS substance restrictions complicate sourcing of mercury cadmium telluride detector materials and certain phosphor compounds used in intensifier tubes. Stakeholders must monitor how emerging export control harmonization between the US, Japan, and Australia reshapes component availability for allied defense programs.
Market Dynamics
Defense procurement offices are consolidating sensor suites into single-aperture multi-spectral systems, compressing vendor lists and forcing component suppliers to integrate across ultraviolet through long-wave infrared capabilities.
Growth Catalysts
- ITAR-controlled tube modernization:The US State Department's Directorate of Defense Trade Controls is accelerating replacement cycles for Gen III image intensifiers across NATO ground forces.
- Multi-spectral targeting pod demand:Unmanned aerial vehicle programs require fused electro-optical and infrared sensors for contested littoral operations.
- Gallium arsenide substrate availability:Domestic wafer fabrication expansion in the United States is securing supply chains for focal plane array production.
Market Restraints
- Rare-earth processing concentration:China's dominance in neodymium and europium refining creates chokepoints for phosphor compounds used in intensifier tubes.
- Mercury cadmium telluride cost volatility:Cooled infrared detector materials face price instability due to cadmium supply constraints and REACH authorization requirements.
- RoHS substance restrictions:The EU's framework limits certain phosphor chemistries, complicating tube manufacturing for European defense programs.
Strategic Opportunities
- Uncooled microbolometer penetration:Soldier-borne thermal weapon sights are displacing legacy night vision in Indo-Pacific expeditionary units.
- Laser designator fusion:Integration of rangefinding and target marking capabilities opens white space in ground vehicle fire-control architectures.
- AUKUS export harmonization:Emerging alignment between the US, UK, and Australia on technology transfer rules streamlines component sourcing for allied programs.
Industry Challenges
- Image intensifier tube engineering scarcity:ITAR-cleared fabrication facilities face workforce gaps in photocathode deposition and microchannel plate assembly.
- Legacy system integration friction:New multi-spectral sensors must interface with decades-old vehicle power and data bus architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Optoelectronic System Market |
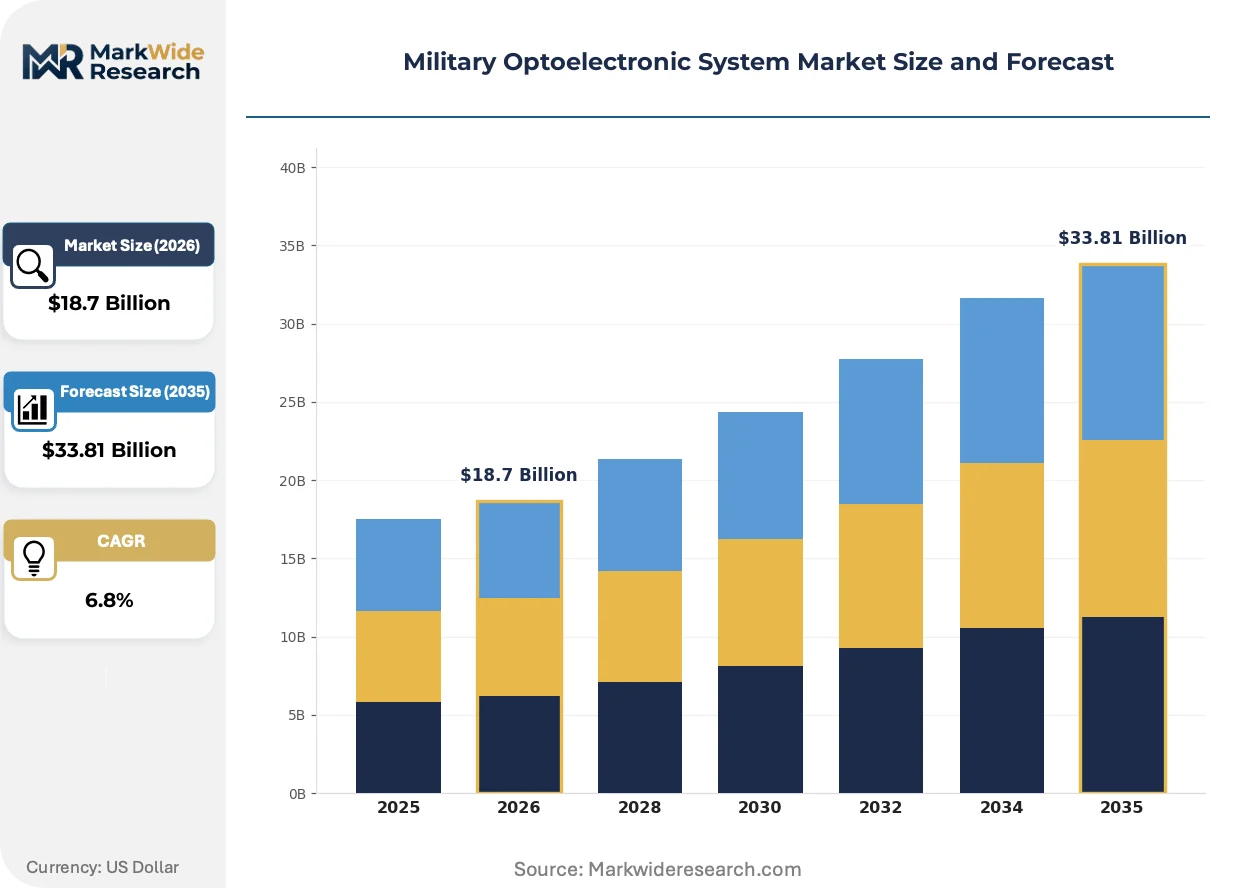
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Night Vision Devices, Laser Rangefinders, Thermal Imagers, Target Designators, Image Intensifiers Technology: Infrared, Laser, Charge Coupled Device, Microbolometer, Photodiode Application: Surveillance, Target Acquisition, Reconnaissance, Fire Control, Battlefield Management End User: Ground Forces, Naval Units, Airborne Squadrons, Defense Contractors |
| Companies Covered | Lockheed Martin Corporation, Teledyne FLIR, L3Harris Technologies, Leonardo S.p.A., BAE Systems, RTX Corporation, Thales Group, Elbit Systems, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Optoelectronic System Market Trends and Innovations
Photonic integration is collapsing discrete sensor functions into unified apertures, while regulatory pressure on hazardous materials accelerates chemistry substitutions across the supply base.
Short-wave infrared sensors based on indium gallium arsenide focal plane arrays is rewriting target identification protocols by enabling see-through-haze capability at tactical ranges. Marine expeditionary units are fielding these systems for ship-to-shore operations. The technology is compressing procurement timelines as forces prioritize passive targeting in electronic warfare-contested theaters.
REACH authorization processes for mercury cadmium telluride are tightening material sourcing requirements across European defense programs. Manufacturers must document substitution plans for restricted substances or secure time-limited exemptions. Cooled infrared detector production is migrating toward alternative substrate materials to preempt regulatory discontinuation.
Defense agencies are bundling sensor hardware with predictive maintenance analytics under multi-year availability contracts. Traditional transactional procurement of discrete units is yielding to performance-based arrangements covering operational readiness. The United Kingdom's Defence Equipment and Support organization is piloting these models for armored vehicle electro-optical suites.
Military Optoelectronic System Market Segmentation
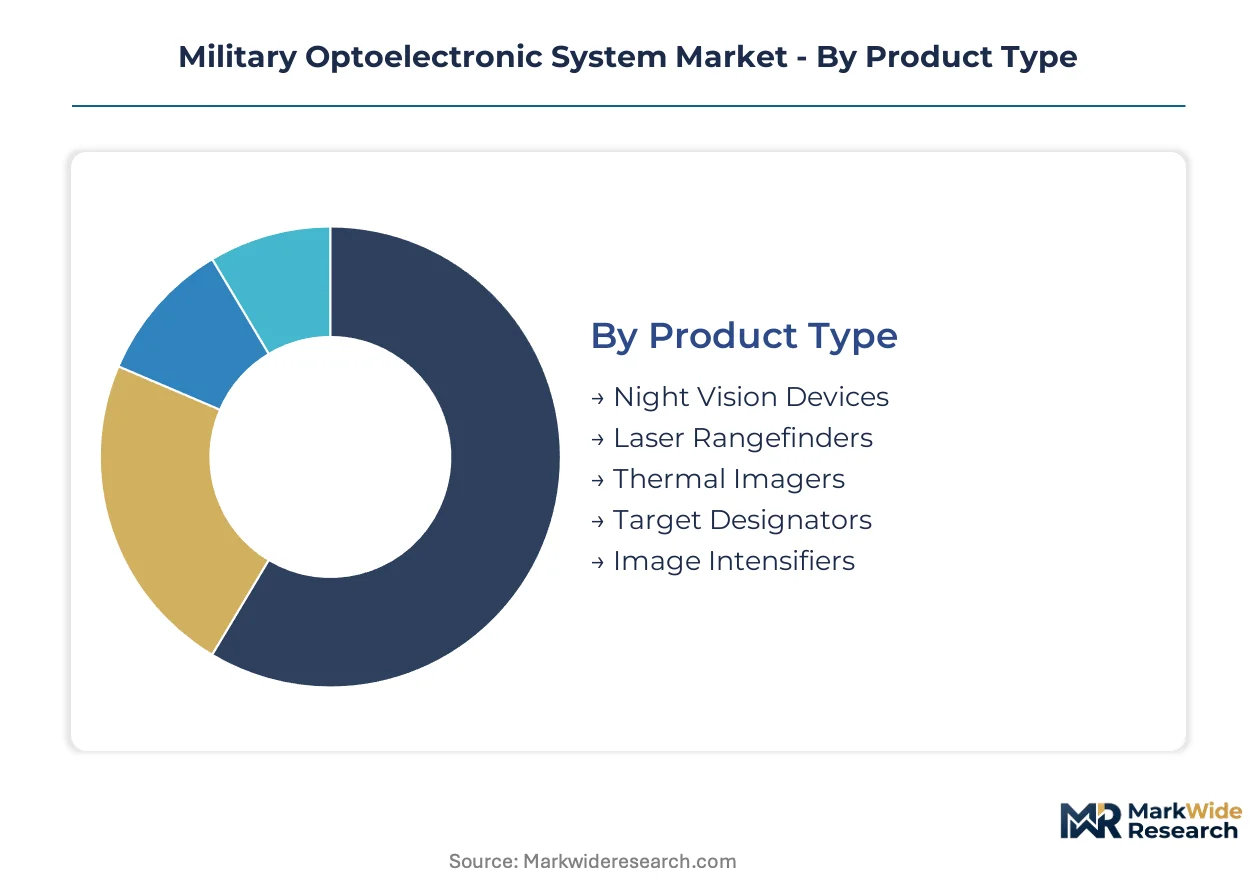
Military optoelectronic procurement concentrates in segments where ITAR compliance and focal plane array fabrication create defendable margin pools. Technology selection determines supply chain resilience, while application requirements dictate sensor fusion complexity and integration timelines.
Product Type:
Capital intensity peaks in segments requiring ITAR-cleared manufacturing infrastructure and exotic material processing capabilities.
- Thermal Imagers:Uncooled microbolometer arrays eliminate cryogenic cooling subsystems, reducing unit cost and maintenance burden for expeditionary ground forces. The US Marine Corps and British Army prioritize these for Indo-Pacific littoral operations where passive targeting defeats electronic warfare countermeasures.
- Night Vision Devices:Image intensifier tubes built on gallium arsenide photocathodes deliver Gen III performance for helmet-mounted and weapon-mounted applications. Replacement cycles across NATO ground forces sustain procurement velocity despite maturity in tube architectures.
- Laser Rangefinders:Eye-safe 1550nm sources integrated into ground vehicle fire-control systems enable distributed precision engagement.
- Target Designators:Pulsed laser modules for terminal guidance require thermal management and beam stabilization subsystems.
- Image Intensifiers:Discrete tube production concentrates among sole-source suppliers with controlled manufacturing lines.
Most installed capacity flows through Night Vision Devices. Expansion is steepest in Thermal Imagers.
Technology:
Volume concentration tracks with uncooled detector architectures that bypass export control restrictions on cryogenic cooling technologies.
- Microbolometer:Vanadium oxide and amorphous silicon focal plane arrays dominate soldier-borne thermal weapon sights. Teledyne FLIR and BAE Systems anchor production in the United States and United Kingdom for NATO and AUKUS procurement programs.
- Infrared:Mercury cadmium telluride and indium antimonide detectors deliver long-wave and mid-wave performance for airborne targeting pods. REACH authorization pressures in Europe are accelerating migration to alternative substrate materials.
- Laser:Solid-state and fiber laser sources enable rangefinding, designation, and directed infrared countermeasure functions.
- Charge Coupled Device:Silicon-based visible sensors persist in legacy surveillance platforms requiring daylight imaging.
- Photodiode:Indium gallium arsenide arrays enable short-wave infrared imaging for see-through-haze target identification.
Procurement volume concentrates in Microbolometer production. Technology transition is most rapid in Infrared substrate materials.
Application:
Customer spending correlates with sensor fusion requirements and platform integration complexity across operational domains.
- Target Acquisition:Multi-spectral sensor suites combining short-wave infrared, mid-wave infrared, and laser rangefinding enable positive identification at extended standoff ranges. US Air Force and Royal Australian Air Force programs for contested Indo-Pacific operations drive specification tightening.
- Fire Control:Ballistic computers fused with electro-optical sensors require MIL-STD-1553 and Ethernet data bus compatibility for armored vehicle retrofit programs.
- Surveillance:Persistent stare capabilities for base perimeter and border security applications.
- Reconnaissance:Handheld and vehicle-mounted systems for dismounted scout and cavalry formations.
- Battlefield Management:Networked sensor feeds integrated into command-and-control architectures.
Integration investment concentrates in Fire Control retrofits. Capability expansion is most pronounced in Target Acquisition fusion systems.
End User:
Budget authority and procurement timelines diverge sharply between operational military units and prime contractor integration programs.
- Ground Forces:Individual and crew-served weapon systems drive volume demand for helmet-mounted displays, thermal weapon sights, and laser target markers. US Army PEO Soldier and British Army HQ Field Army coordinate modernization roadmaps with synchronized fielding schedules.
- Airborne Squadrons:Targeting pod and navigation sensor procurement concentrates in fast-jet and unmanned aerial vehicle programs. NATO alliance members are accelerating multi-spectral pod acquisitions for distributed maritime operations.
- Naval Units:Shipboard electro-optical fire-control and infrared search-and-track systems for surface combatants.
- Defense Contractors:Subsystem integration for platform prime contracts including ground vehicle and aircraft manufacturers.
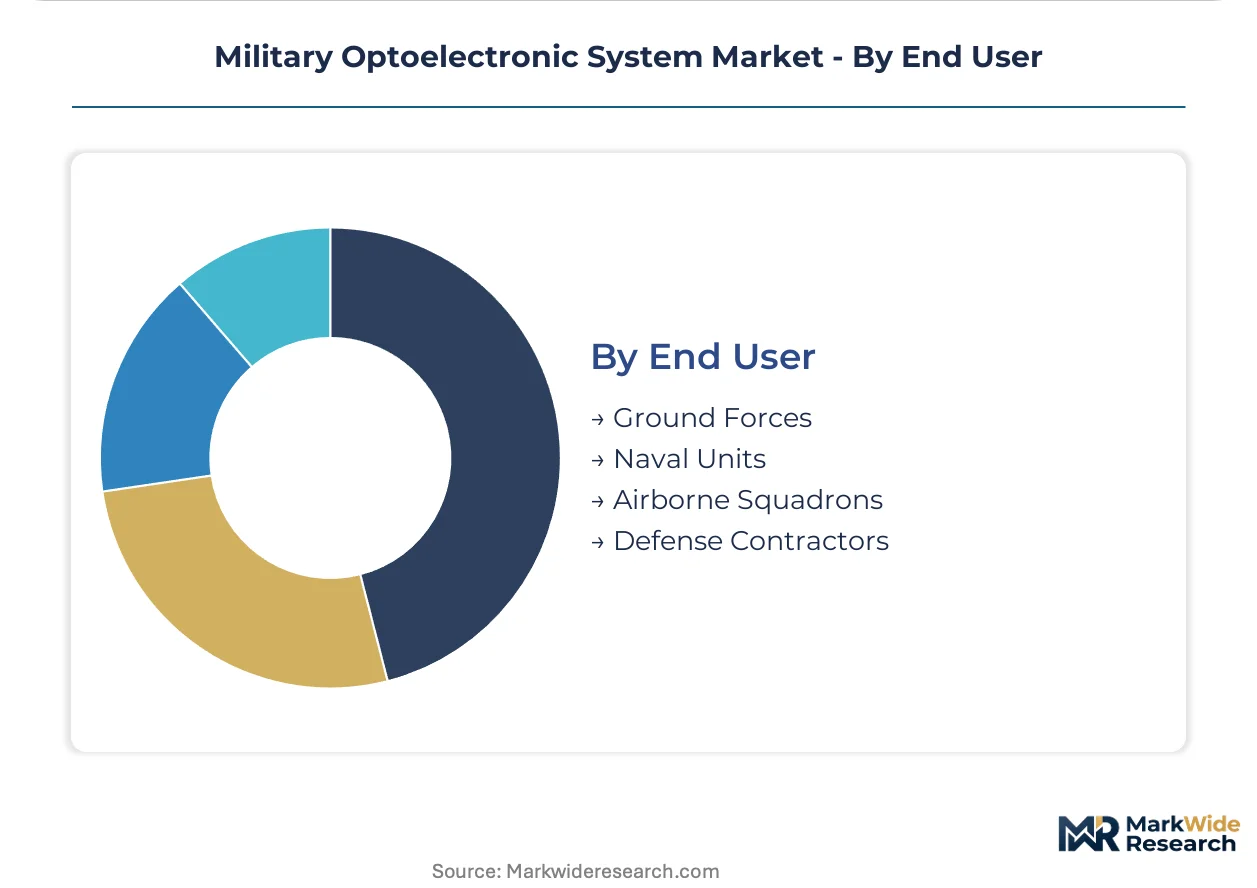
Program execution concentrates through Defense Contractors. Direct procurement velocity is highest in Ground Forces modernization accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as ITAR compliance costs in the United States push component sourcing toward allied nations with harmonized export frameworks. Gallium arsenide wafer fabrication and rare-earth processing investments are migrating to jurisdictions offering streamlined defense trade controls.
United States
The Department of Defense's night vision goggle modernization roadmap is accelerating Gen III image intensifier procurement across NATO ground forces. ITAR regulations enforced by the State Department's Directorate of Defense Trade Controls constrain technology transfer for cooled infrared detectors. Domestic rare-earth processing investments in Mountain West states are securing phosphor compound supply chains for tube manufacturing.
Germany
The Bundeswehr's distributed electro-optical sensor network programs are driving demand for multi-spectral targeting systems in contested littoral environments. REACH authorization requirements administered by ECHA are tightening mercury cadmium telluride sourcing for European defense programs. Industrial clusters in Bavaria and Baden-Württemberg host focal plane array integration facilities serving NATO procurement.
United Kingdom
The Defence Equipment and Support organization is piloting performance-based availability contracts for armored vehicle electro-optical suites. RoHS substance restrictions complicate phosphor chemistry selection for intensifier tube production. Scottish and Midlands manufacturing bases are expanding uncooled microbolometer assembly for soldier-borne thermal weapon sights.
Australia
AUKUS export harmonization is streamlining component sourcing for allied defense programs across the Indo-Pacific theater. The country's national defense regulator is aligning technology transfer rules with US and UK frameworks. Industrial concentration in South Australia and Victoria is supporting submarine and maritime patrol sensor integration programs.
Japan
METI is coordinating gallium arsenide substrate expansion to secure focal plane array supply chains for indigenous defense programs. Short-wave infrared sensor development for ship-to-shore operations is accelerating in maritime expeditionary units. Manufacturing clusters in the Nagoya and Tokyo regions are advancing indium gallium arsenide detector fabrication for see-through-haze capabilities.
Military Optoelectronic System Market Competitive Landscape
United States producers anchor the prime contractor tier; European and Israeli specialists hold subsystem integration positions. The vendor structure concentrates around cleared manufacturing facilities with ITAR-compliant production lines. Three archetypes dominate: domestic primes with captive focal plane array production, foreign specialists in uncooled detector architectures, and sole-source tube suppliers with controlled manufacturing lines. Competitive moves center on backward integration into rare-earth processing and strategic partnerships for multi-spectral sensor fusion.
Within the prime contractor tier, Lockheed Martin Corporation and Northrop Grumman Corporation represent the integrated systems archetype with in-house production capabilities. Teledyne FLIR exemplifies the specialist position in uncooled microbolometer architectures. These three companies occupy positions that reflect the market's segmentation between ITAR-cleared domestic production and technology-licensed foreign participation.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Teledyne FLIR |
| L3Harris Technologies |
| Leonardo S.p.A. |
| BAE Systems |
| RTX Corporation |
| Thales Group |
| Elbit Systems |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
Gen III image intensifier modernization mandates across NATO ground forces are compressing procurement timelines and forcing suppliers to absorb qualification costs, which concentrates pricing power among sole-source tube manufacturers with ITAR-cleared facilities. This demand pressure cascades backward through gallium arsenide wafer and rare-earth phosphor supply tiers, amplifying cost pass-through for uncooled microbolometer alternatives.
Pricing Analysis
Direct-to-prime contracting eliminates distributor margins for multi-spectral targeting pod programs, while transactional spot purchasing governs replacement tube orders for fielded night vision devices. Price differentiation tracks ITAR certification tier and cryogenic cooling complexity, with cooled infrared detectors commanding substantial premiums over uncooled arrays. Cost compression in helmet-mounted displays is intensifying because British Army and US Marine Corps procurement offices are consolidating orders under multi-year availability contracts. Ground forces modernization accounts exhibit highest price sensitivity as budget authority fragments across individual soldier equipment line items, whereas airborne targeting pod programs demonstrate lowest sensitivity due to platform integration complexity.
Supply Chain Analysis
Workforce scarcity in photocathode deposition and microchannel plate assembly concentrates production in Mountain West states of the United States, Bavaria in Germany, and Scottish manufacturing clusters. Raw material dependencies center on neodymium and europium refining for phosphor compounds, gallium arsenide substrate fabrication for focal plane arrays, and mercury cadmium telluride crystal growth for cooled detectors. Single-source vulnerability pervades ITAR-cleared tube manufacturing where sole-source suppliers control microchannel plate production. Distribution runs through defense prime contractor integration facilities rather than open market channels, with component flows directed into Lockheed Martin and Northrop Grumman assembly lines for platform-level delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ITAR refresh cycles and REACH authorization milestones for mercury cadmium telluride are accelerating replacement demand across allied defense programs.
For Market Incumbents: Hedge against rare-earth processing chokepoints by securing captive supply of europium and neodymium through Mountain West refining investments. Deepen backward integration into gallium arsenide wafer fabrication to defend margins on focal plane array production as Teledyne FLIR expands uncooled microbolometer capacity. Prioritize ITAR compliance infrastructure as the primary barrier against emerging foreign specialists seeking AUKUS technology transfer alignment. For New Entrants and Emerging Players: Mid-tier European defense contractors underserved by sole-source tube suppliers present accessible entry points for alternative short-wave infrared sensor architectures. Laser rangefinder fusion for ground vehicle fire-control systems offers the most penetrable white space, with Indo-Pacific expeditionary units prioritizing distributed precision engagement capabilities. Pursue strategic licensing arrangements with Japanese indium gallium arsenide detector fabricators to bypass ITAR restrictions on cooled infrared technologies. For Investors and Strategic Acquirers: Asymmetric upside sits with uncooled microbolometer specialists possessing AUKUS-cleared production lines and established NATO procurement relationships. Long-term viability hinges on regulatory harmonization trajectory rather than technology displacement risk, with five-to-ten-year windows favoring sensor fusion capabilities over discrete component plays. Monitor ECHA REACH authorization decisions for mercury cadmium telluride as the critical inflection signal for cooled infrared substrate material substitution.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR-Cleared Manufacturing Expansion | Mountain West facility investments secure phosphor compound supply chains for Gen III tube production. |
| Multi-Spectral Sensor Fusion Development | Short-wave infrared integration with thermal imaging enables see-through-haze targeting for Indo-Pacific operations. |
| AUKUS Export Harmonization Alignment | Technology transfer rule convergence streamlines component sourcing for Australian submarine and maritime patrol programs. |
| Performance-Based Availability Contracting | UK Defence Equipment and Support pilots shift procurement from transactional units to operational readiness guarantees. |
| Alternative Substrate Material Migration | European manufacturers preempt REACH discontinuation by transitioning cooled infrared production beyond mercury cadmium telluride. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with program executives at US Army PEO Soldier, British Army HQ Field Army, and NATO acquisition offices with secondary validation through Directorate of Defense Trade Controls filings, ECHA REACH authorization databases, and defense procurement contract announcements. Bottom-up triangulation across microbolometer unit shipments and top-down reconciliation against prime contractor revenue disclosures anchored market sizing.
Historical reference periods spanning completed night vision goggle modernization cycles and multi-spectral targeting pod fielding timelines informed the projection horizon. Segmentation modeling incorporated product type, detector technology, application complexity, and end-user budget authority across ground forces, airborne squadrons, and naval units. CAGRs were derived from fitted growth curves calibrated to procurement velocity in Indo-Pacific theater accounts and replacement cycle acceleration under ITAR-controlled tube programs.
Inputs from prime contractor earnings disclosures and defense agency budget justifications were available through the study window; gaps in classified program expenditure introduce uncertainty bands around targeting pod and laser designator estimates. Forecasts reflect assumptions regarding AUKUS harmonization progress and REACH authorization timelines for restricted detector materials. Material deviation in ECHA regulatory decisions or State Department ITAR enforcement posture warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Land Digital Battlefield Market