
 Anthrax Treatment Market | 2026-2036
Anthrax Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anthrax Treatment Market Outlook
Premium biodefense procurement is decoupling from standard hospital antibiotic purchasing, as government stockpiles now command dedicated manufacturing lines and distinct regulatory pathways. Emergent BioSolutions anchors the US government segment through long-term procurement agreements for anthrax vaccines. Bayer AG leverages its established fluoroquinolone portfolio to sustain hospital and clinic demand for post-exposure prophylaxis. SIGA Technologies competes in the antitoxin niche with specialized countermeasures for inhalation anthrax.
Anthrax treatment encompasses pharmaceutical interventions targeting Bacillus anthracis infection, including antibiotics that inhibit bacterial protein synthesis, antitoxins that neutralize protective antigen and lethal factor components, and vaccines composed of cell-free filtrate antigens that stimulate protective immunity. Antibiotics occupy the largest volume share due to established ciprofloxacin and doxycycline protocols, while antitoxins capture premium pricing through limited manufacturing sources and biodefense stockpile mandates. The injectable delivery mode dominates emergency response applications, whereas oral formulations sustain outpatient post-exposure prophylaxis programs.
FDA Emergency Use Authorization frameworks and BARDA advanced research and development contracts shape product development timelines and market access for novel anthrax countermeasures. The CDC Strategic National Stockpile requirements dictate procurement volumes and storage specifications for approved vaccines and therapeutics. Stakeholders must monitor shifts in government biodefense budgeting and the progression of next-generation recombinant protective antigen vaccines through regulatory review.
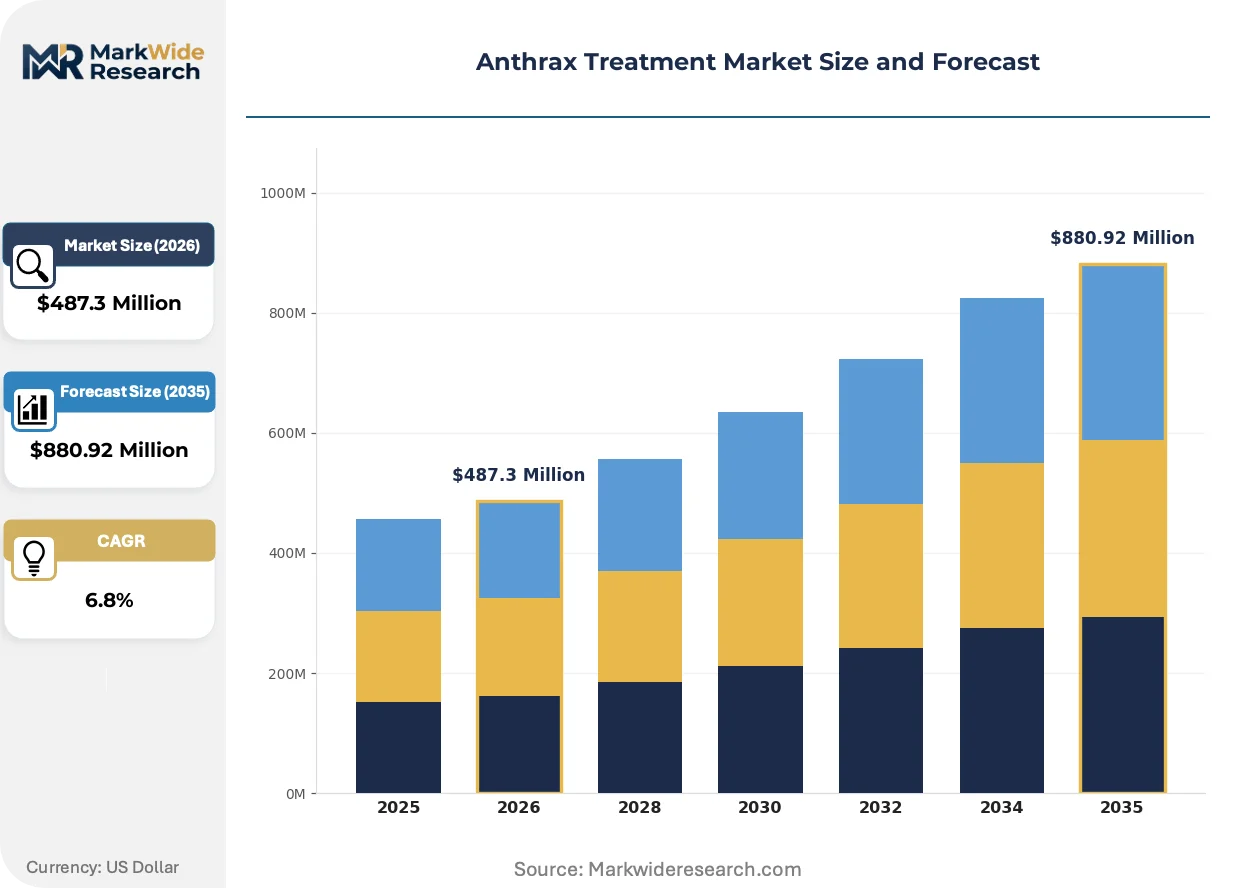
Market Dynamics
Government stockpile procurement is decoupling from commercial pharmaceutical channels, creating parallel supply chains where biodefense contracts command dedicated manufacturing capacity and distinct regulatory pathways.
Growth Catalysts
- BARDA Advanced Development Contracts:US government funding de-risks clinical trials for novel anthrax countermeasures, accelerating regulatory submission timelines for developers.
- Strategic National Stockpile Mandates:CDC requirements for multi-year vaccine and antitoxin reserves create predictable, high-volume demand independent of hospital purchasing cycles.
- Emerging Vector-Based Platforms:Recombinant protective antigen vaccines using adenoviral delivery systems promise faster immune response and reduced dosing schedules.
Market Restraints
- Single-Source Manufacturing Concentration:Domestic fill-finish capacity for injectable biodefense products concentrates at Emergent BioSolutions' Baltimore facility, creating geographic supply vulnerability.
- Fluoroquinolone Resistance Surveillance:CDC tracking of Bacillus anthracis isolates with altered ciprofloxacin susceptibility threatens standard post-exposure prophylaxis protocols.
- Extended Stability Requirements:FDA mandates for 10-year shelf-life specifications force costly formulation engineering and accelerated aging studies.
Strategic Opportunities
- Next-Generation Recombinant Vaccines:Altimmune and Vaxart oral tablet candidates could displace cold-chain-dependent injectable stockpiles with room-temperature-stable alternatives.
- Animal Health Crossover:USDA-licensed livestock anthrax vaccines offer technology transfer pathways for human biodefense applications with established manufacturing bases.
- Allied Stockpile Harmonization:UK Health Security Agency and Canadian Public Health Agency procurement specifications increasingly align with US FDA standards, opening export pathways.
Industry Challenges
- Animal Rule Validation:Efficacy demonstration for inhalation anthrax countermeasures requires non-human primate studies that face ethical scrutiny and capacity constraints.
- Post-Exposure Diagnostic Gaps:Rapid point-of-care Bacillus anthracis detection lags therapeutic development, complicating timely antitoxin administration in civilian settings.
- Workforce Security Clearance Bottlenecks:Personnel at biodefense manufacturing sites require DHS facility security clearance processes that extend hiring timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anthrax Treatment Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antitoxins, Vaccines, Supportive Care End User: Hospitals, Clinics, Emergency Response Teams, Pharmacies Delivery Mode: Injectable, Oral, Intranasal, Intravenous Application: Post-Exposure Prophylaxis, Treatment, Prevention, Research |
| Companies Covered | Bayer AG, Nighthawk Biosciences, Emergent BioSolutions, Bavarian Nordic, GC Biopharma, Pfizer, Paratek Pharmaceuticals, SIGA Technologies, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anthrax Treatment Market Strategic Shifts
Product development is bifurcating between incremental improvements to approved antibiotics and disruptive platform technologies targeting the limitations of existing stockpiled countermeasures.
Recombinant protective antigen subunit vaccines are electrifying clinical development pipelines by enabling precision engineering of immunogenic epitopes while eliminating the reactogenicity associated with cell-free filtrate preparations. BARDA-funded developers including Altimmune and Vaxart are advancing oral and intranasal formulations that promise self-administration during mass casualty events. This modality shift is compressing the cold-chain infrastructure requirements that currently dominate Strategic National Stockpile logistics and storage costs.
FDA Animal Rule guidance revisions are tightening efficacy standards for inhalation anthrax therapeutics, requiring survival endpoints in two animal species rather than one. The industrial consequence is expanded non-human primate study demand that strains contracted research organization capacity. Antitoxin developers face the steepest compliance burden, as SIGA Technologies' tecovirimat pathway established precedents that subsequent sponsors must match or exceed.
Hospital pharmacy buyers are consolidating post-exposure prophylaxis procurement through group purchasing organizations, displacing direct manufacturer relationships that historically governed fluoroquinolone antibiotic distribution. This channel compression squeezes margin capture for generic ciprofloxacin and doxycycline suppliers while favoring sole-source antitoxin contracts with government pricing protections. The shift is most visible in US health system networks where emergency preparedness coordinators now centralize biodefense pharmaceutical decisions at the enterprise level.
Anthrax Treatment Market Segmentation
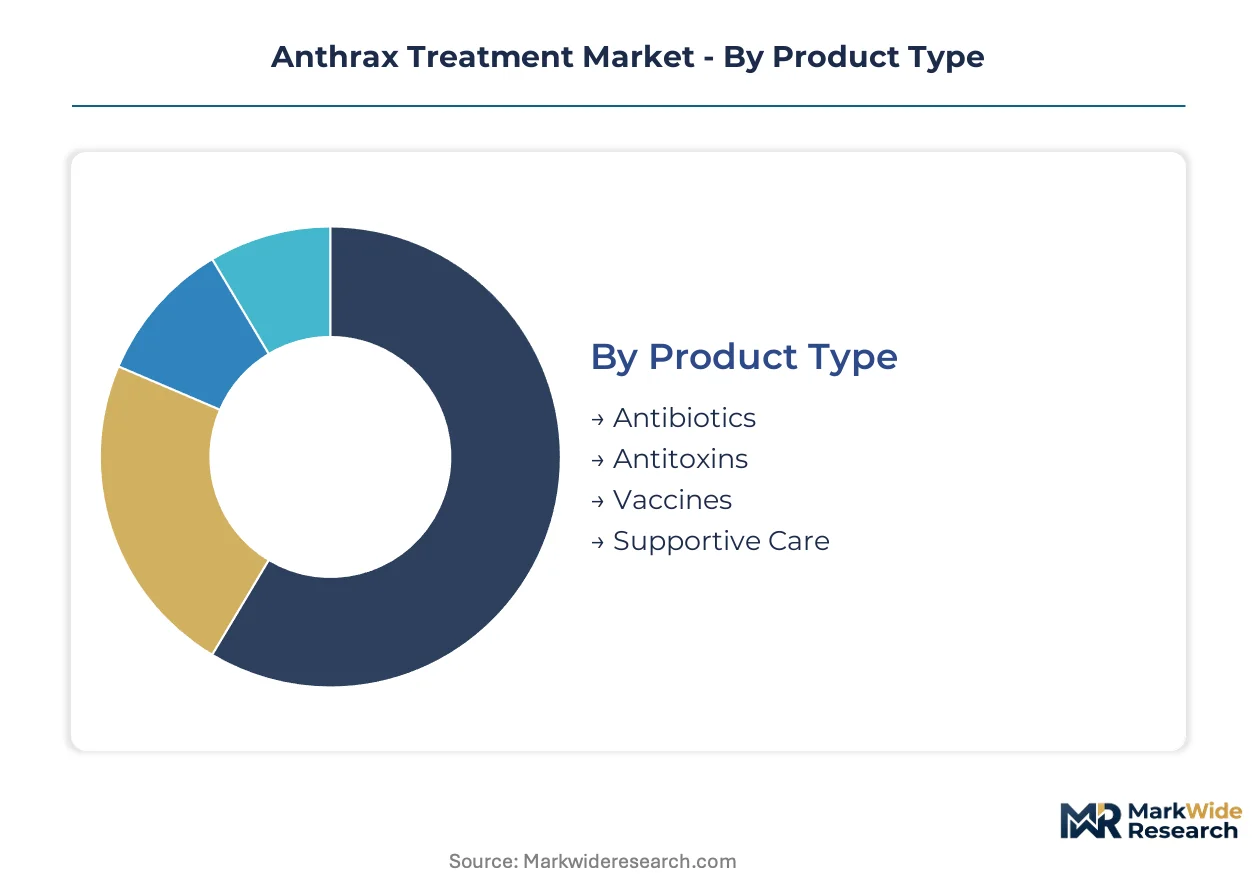
Segmentation in the anthrax treatment market reveals divergent regulatory pathways and procurement channels across product categories. Government stockpile requirements impose distinct FDA approval standards that reshape competitive dynamics within each segment.
Product Type:
BARDA funding eligibility and FDA Emergency Use Authorization pathways concentrate differently across product categories, with vaccines and antitoxins commanding dedicated biodefense procurement budgets while antibiotics flow through standard pharmaceutical channels.
- Antibiotics:Fluoroquinolones and tetracyclines inhibit bacterial protein synthesis through DNA gyrase and ribosomal targeting. Hospital procurement concentrates in the United States for post-exposure prophylaxis stockpiles, constrained by CDC surveillance of emerging ciprofloxacin resistance patterns.
- Antitoxins:Monoclonal antibody formulations neutralize protective antigen and lethal factor components of anthrax toxin. BARDA advanced development contracts accelerate regulatory timelines for these injectable countermeasures, with manufacturing capacity concentrating at domestic fill-finish facilities.
- Vaccines:Cell-free filtrate and recombinant protective antigen preparations stimulate protective immunity. Strategic National Stockpile mandates drive multi-year procurement commitments independent of commercial hospital purchasing cycles.
- Supportive Care:Fluid resuscitation and vasopressor adjuncts manage systemic inflammatory response in severe inhalation cases.
Antibiotics sit at the top of the volume ranking, with antitoxins climbing the fastest.
End User:
Procurement authority and funding sources fragment demand across institutional buyers, with federal agencies commanding premium pricing through sole-source contracts while health systems consolidate purchasing through group purchasing organizations.
- Hospitals:Emergency departments and pharmacy buyers manage post-exposure prophylaxis protocols using oral fluoroquinolone stockpiles. Enterprise-level preparedness coordinators now centralize biodefense pharmaceutical decisions across US health system networks.
- Clinics:Outpatient facilities administer extended doxycycline regimens for cutaneous anthrax exposure.
- Emergency Response Teams:First responders deploy field-stabilized antitoxin kits under CDC Strategic National Stockpile distribution protocols.
- Pharmacies:Retail channels face compressed margins on generic ciprofloxacin as group purchasing organizations displace direct manufacturer relationships.
Hospitals anchor procurement volume, though emergency response teams are expanding most quickly following federal preparedness grants.
Delivery Mode:
Cold-chain infrastructure requirements and self-administration feasibility reshape stockpile logistics, with next-generation formulations targeting room-temperature stability to displace injectable dependence.
- Injectable:Intravenous and intramuscular formulations dominate emergency response applications for antitoxins and vaccines. FDA mandates for 10-year shelf-life specifications force costly formulation engineering at domestic manufacturing sites.
- Oral:Tablet and suspension formulations sustain outpatient post-exposure prophylaxis programs using ciprofloxacin and doxycycline.
- Intranasal:Mucosal delivery platforms promise rapid immune response without needle administration.
- Intravenous:Hospital-based infusion protocols support severe inhalation anthrax cases requiring intensive care.
Injectable formats retain the largest stockpile allocation, with intranasal candidates gaining share fastest through BARDA-funded platform development.
Application:
Clinical use cases stratify across prophylactic, therapeutic, and research contexts, with regulatory burden escalating from prevention through post-exposure intervention to active disease management.
- Post-Exposure Prophylaxis:Extended antibiotic regimens prevent infection progression following confirmed Bacillus anthracis exposure. US health departments coordinate distribution through the CDC Strategic National Stockpile.
- Treatment:Combination antibiotic and antitoxin protocols address active inhalation or cutaneous disease.
- Prevention:Pre-exposure vaccination protects military personnel and laboratory workers with occupational risk.
- Research:Non-human primate studies under FDA Animal Rule guidance validate efficacy for inhalation countermeasures.
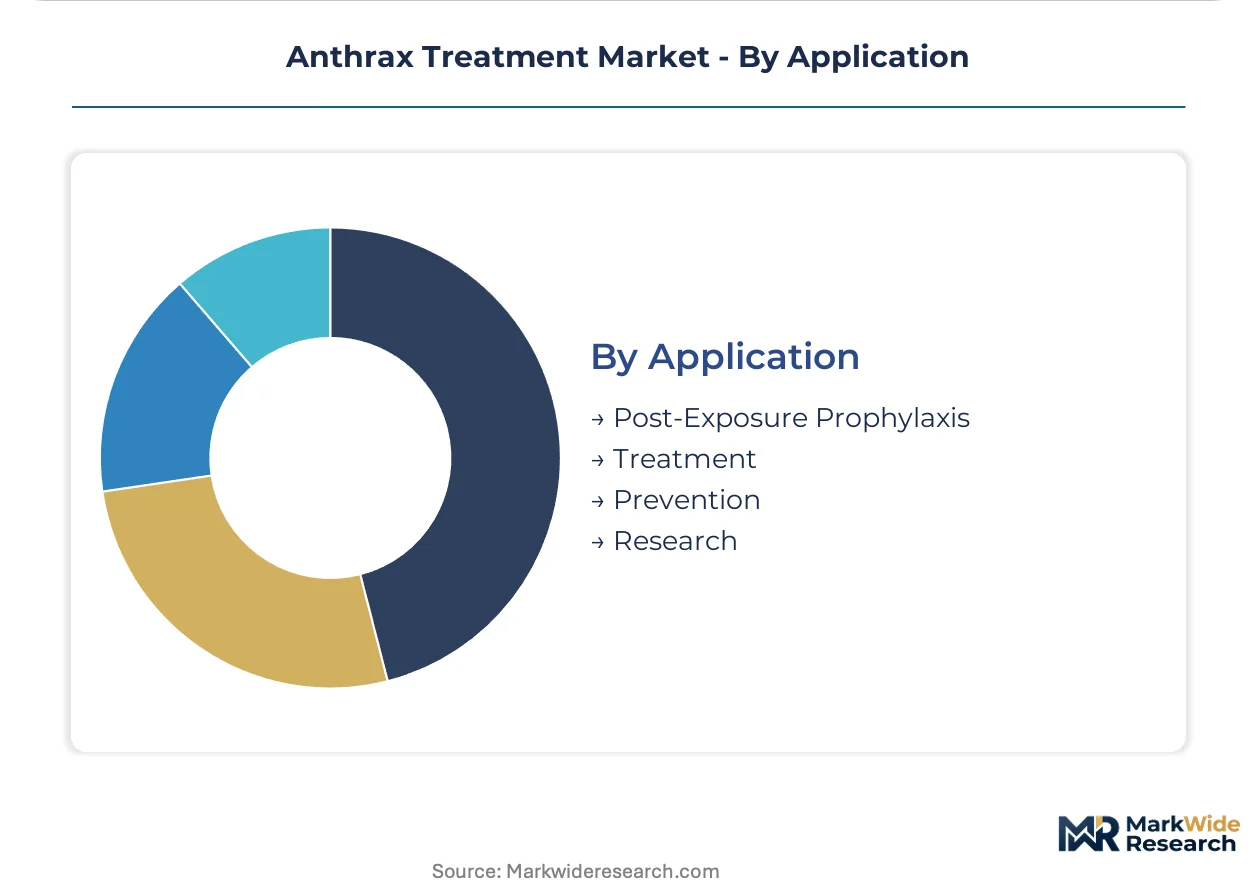
Post-exposure prophylaxis commands the largest procurement volumes, with research applications showing the steepest expansion trajectory as Animal Rule standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands procurement volumes that dwarf other national markets, while the United Kingdom and Canada are harmonizing stockpile specifications with FDA standards to unlock export pathways for domestic manufacturers.
United States
The CDC Strategic National Stockpile drives multi-year procurement commitments for anthrax vaccines and antitoxins through sole-source contracts. BARDA advanced development contracts de-risk clinical trials and accelerate regulatory submission timelines for novel countermeasures. Manufacturing capacity concentrates at domestic fill-finish facilities in Maryland, where dedicated biodefense production lines operate under DHS security protocols.
United Kingdom
The UK Health Security Agency is expanding procurement specifications to align with US FDA standards, creating demand for room-temperature-stable vaccine formulations. British regulators reference FDA Emergency Use Authorization pathways when evaluating anthrax countermeasures for national stockpile inclusion. Development activity clusters around Oxford and Cambridge, where recombinant protective antigen research programs receive government biodefense funding.
Germany
Bavarian-based pharmaceutical manufacturers leverage established fluoroquinolone production infrastructure to supply hospital antibiotic stockpiles across the European Union. German regulators at the Paul-Ehrlich-Institut coordinate with EMA on biodefense product approval standards. The Rhine-Main region hosts specialized cold-chain logistics providers that service government vaccine storage requirements.
Canada
The Public Health Agency of Canada maintains anthrax countermeasures within the National Emergency Stockpile System, with procurement increasingly mirroring US CDC specifications. Health Canada regulators participate in trilateral biodefense harmonization initiatives with FDA and UK counterparts. Manufacturing partnerships concentrate in Ontario and Quebec, where facilities produce antibiotics for both human and veterinary anthrax applications.
Israel
Israeli biodefense procurement prioritizes dual-use countermeasures applicable to both military and civilian emergency response scenarios. The Israel Institute for Biological Research maintains independent validation capabilities for inhalation anthrax therapeutics. Tel Aviv-area defense contractors collaborate with international partners on next-generation recombinant vaccine platforms.
Anthrax Treatment Market Competitive Environment
Top-tier vendors anchor government stockpile procurement through long-term sole-source agreements, while mid-tier antibiotic suppliers compete through hospital group purchasing organization channels. The market structure bifurcates between biodefense contractors with dedicated manufacturing security clearances and commercial pharmaceutical distributors serving standard post-exposure prophylaxis demand. Strategic archetypes include integrated biodefense specialists, diversified fluoroquinolone manufacturers, and emerging platform technology developers. Competitive moves center on capacity reservation for government contracts and technology licensing for next-generation recombinant formulations.
Within the integrated biodefense tier, Emergent BioSolutions and SIGA Technologies exemplify archetypes of domestic stockpile contractors with specialized manufacturing capabilities. Bayer AG occupies a position representing established pharmaceutical conglomerates with fluoroquinolone portfolios that sustain hospital and clinic demand. These three companies illustrate the competitive spectrum from sole-source government dependence to diversified commercial antibiotic distribution.
| Leading Market Players |
|---|
| Bayer AG |
| Nighthawk Biosciences |
| Emergent BioSolutions |
| Bavarian Nordic |
| GC Biopharma |
| Pfizer |
| Paratek Pharmaceuticals |
| SIGA Technologies |
| GlaxoSmithKline |
| Others |
Value Chain & Pricing Dynamics
FDA stability mandates for decade-long shelf-life specifications gate qualified supply access and premium-tier pricing power, as only domestic fill-finish facilities with DHS security clearances can meet BARDA contract requirements for injectable biodefense countermeasures.
Pricing Analysis
Capacity additions in Maryland are reshaping price floors for injectable anthrax vaccines and antitoxins. Contract-based long-term offtake dominates, with sole-source government agreements commanding premium pricing over hospital group purchasing organization channels. Price differentiation rests on FDA Emergency Use Authorization tier and DHS facility security clearance status. Cost compression in oral antibiotic tiers is intensifying because generic ciprofloxacin suppliers face margin squeeze from consolidated procurement. Emergency response teams show highest price sensitivity, while biodefense stockpile agencies accept premium pricing for assured supply.
Supply Chain Analysis
Regional distribution centers in Maryland, Bavaria, and Ontario form a hub-and-spoke pattern for cold-chain vaccine logistics. Geographic supply concentrates in the United States, Germany, and Canada for finished dose manufacturing. Raw material dependencies include recombinant protective antigen substrates, specialized glass vial formats, and validated cold-chain packaging. Single-source vulnerability at Emergent BioSolutions' Baltimore facility creates geographic concentration risk. Distribution runs through CDC Strategic National Stockpile allocation protocols for government contracts, with hospital group purchasing organizations handling commercial antibiotic flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through next-generation recombinant vaccine platforms that displace cold-chain infrastructure costs and capture premium stockpile pricing.
For Market Incumbents: Hedge fluoroquinolone revenue erosion by accelerating recombinant protective antigen vaccine development through BARDA advanced development contracts. Secure DHS facility security clearances for additional fill-finish sites to reduce single-source vulnerability. Channel control through long-term CDC Strategic National Stockpile agreements remains the priority lever against emerging oral tablet competitors. For New Entrants and Emerging Players: Allied government stockpile agencies in the United Kingdom and Canada represent underserved buyer archetypes with procurement specifications harmonizing toward FDA standards. Oral and intranasal vaccine formulations offer the most penetrable segment against incumbent injectable dependence. Pursue technology licensing partnerships with USDA-licensed livestock vaccine manufacturers to leverage established production bases for human biodefense crossover. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier antibiotic suppliers facing group purchasing organization margin compression. Long-term viability favors platform technology developers with BARDA funding visibility and room-temperature-stable formulation capabilities. Watch FDA Animal Rule guidance revisions as the signal indicating regulatory compliance cost escalation for antitoxin developers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Emergency Use Authorization accelerates market access for novel anthrax countermeasures beyond standard review timelines. |
| Manufacturing Scale-Up | Domestic fill-finish capacity expansion at DHS-cleared facilities reduces single-source geographic concentration risk. |
| Pipeline Diversification | Recombinant protective antigen platforms displace cell-free filtrate vaccines with reduced reactogenicity profiles. |
| Licensing Agreement | USDA livestock vaccine technology transfer opens established manufacturing bases for human biodefense applications. |
| Long-term Supply Agreement | CDC Strategic National Stockpile sole-source contracts provide predictable revenue independent of hospital purchasing cycles. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down government stockpile tracking forms the analytical core. Primary interviews with biodefense procurement officers, regulatory affairs leads at vaccine developers, hospital pharmacy directors, and BARDA program managers combined with secondary validation from FDA filings, BARDA contract announcements, CDC Strategic National Stockpile inventory disclosures, and ClinicalTrials.gov protocol registrations. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of government contract awards and hospital purchasing patterns informed projection frameworks across product type, delivery mode, end user, and application segments. CAGRs derived from modeled procurement volumes reflect BARDA funding trajectories, CDC stockpile replenishment schedules, and next-generation vaccine development timelines. Industry-specific forecast inputs include FDA Animal Rule study completion rates and allied government stockpile harmonization progress.
Underlying measurement precision varies by segment; government stockpile procurement carries tighter precision than hospital antibiotic purchasing due to contract transparency. Forecasts reflect documented assumptions regarding BARDA funding continuity and regulatory pathway timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market