
 Cough Syrup Market | 2026-2036
Cough Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Cough Syrup Market Intelligence
Plant-based extraction and clean-label formulation is tilting R&D investment away from synthetic actives toward botanical derivatives with demonstrated mucolytic properties. Johnson & Johnson leverages its pediatric brand equity to sustain shelf presence across North American pharmacy chains. Boehringer Ingelheim International GmbH anchors European positioning through heritage respiratory expertise and clinician detailing networks.
Cough syrup denotes a liquid oral dosage containing antitussive, expectorant, or mucolytic agents dissolved in viscous aqueous or hydroalcoholic bases, typically dosed via calibrated cup or syringe to ensure precise milliliter delivery for age-appropriate efficacy. The product serves both symptomatic relief of upper respiratory irritation and adjunctive management in post-viral bronchial congestion. Dry cough syrup formulations command premium positioning due to dextromethorphan supply constraints and stricter scheduling controls, while pediatric syrup segments compete on palatability engineering and colorant-free claims. Online distribution channels are capturing fastest volume expansion as telehealth prescribing and direct-to-patient fulfillment normalize post-pandemic purchasing behavior.
FDA, EMA, and India's CDSCO collectively govern active pharmaceutical ingredient purity, child-resistant packaging mandates, and marketing claim substantiation that determine market access and label expansion potential. WHO guidelines on rational use of cough and cold medicines in children under six years further constrain formulation strategies and promotional boundaries. Stakeholders must monitor evolving scheduling decisions for codeine and dextromethorphan across major jurisdictions to anticipate portfolio restructuring requirements and regional revenue exposure shifts.
Market Dynamics
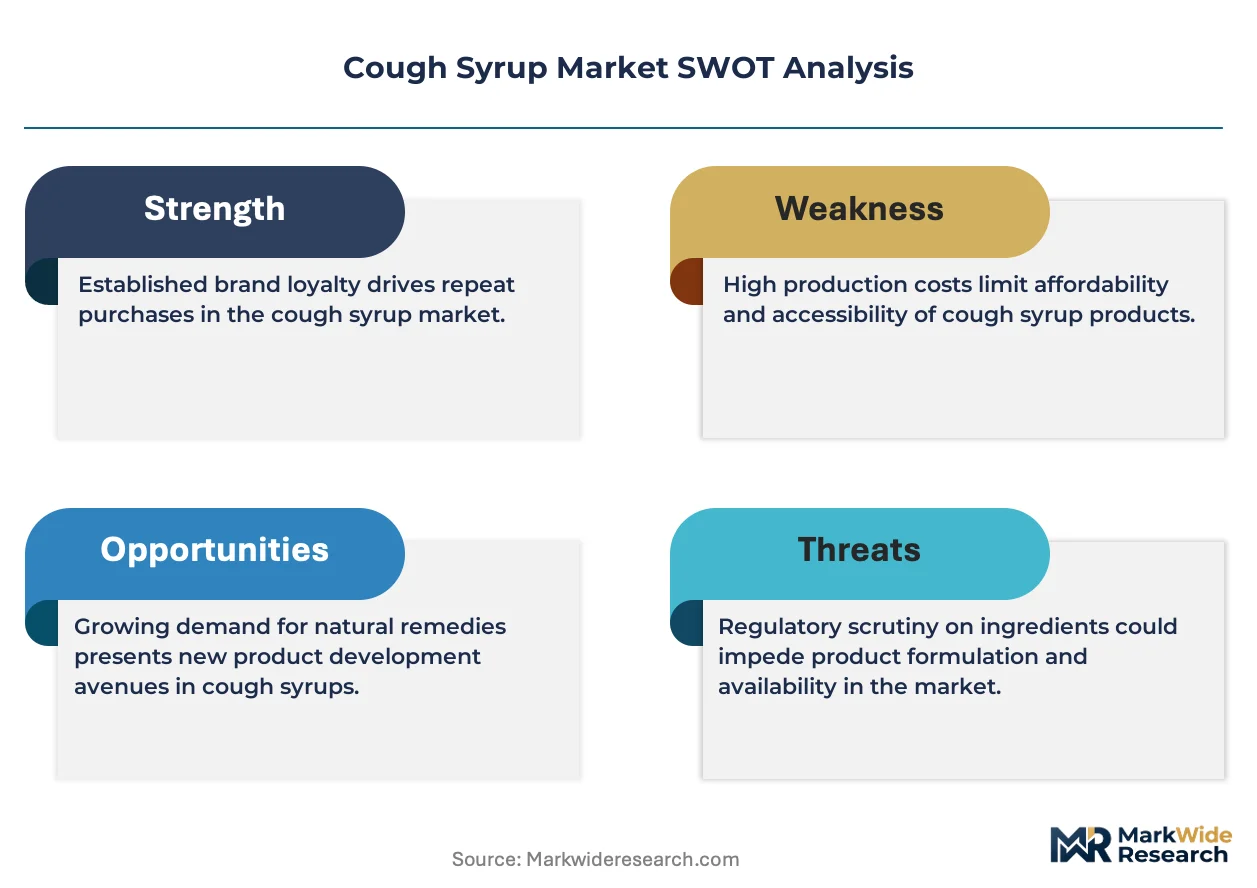
Reformulation pressure from opioid scheduling restrictions is forcing manufacturers to rebuild active ingredient portfolios around non-narcotic antitussives, compressing legacy dextromethorphan supply chains while accelerating botanical mucolytic development timelines.
Growth Catalysts
- Pediatric household stocking:Post-pandemic medicine cabinet replenishment cycles in India and Southeast Asia sustain volume baselines for sugar-free and colorant-free formulations.
- EMA labeling harmonization:Standardized age-grading symbols enable cross-border SKU rationalization, reducing regulatory fragmentation for multinational portfolios.
- Telehealth prescribing normalization:Direct-to-patient fulfillment through pharmacy-integrated platforms expands addressable reach beyond traditional retail pharmacy footprints.
Market Restraints
- API supply concentration:Dextromethorphan precursor manufacturing clusters in eastern China create single-source vulnerability for dry cough formulations.
- Codeine scheduling escalation:WHO rational-use guidelines and national pharmacy restrictions in multiple jurisdictions eliminate residual revenue from legacy opioid-containing lines.
- Palatability engineering costs:Masking bitterness in high-concentration guaifenesin suspensions requires proprietary polymer systems that inflate per-unit COGS.
Strategic Opportunities
- Vietnam pharmacy modernization:Chain consolidation in Ho Chi Minh City and Hanoi creates shelf-space leverage for branded pediatric lines with clinician detailing support.
- Plant-extraction IP development:Patentable fractionation processes for ivy leaf and thyme derivatives offer defensible positioning against commoditized synthetic actives.
- Subscription replenishment models:Seasonal allergy-cough combination protocols via direct-to-consumer platforms capture recurring revenue in temperate-climate households.
Industry Challenges
- Formulation stability expertise:Hydroalcoholic base preservation without parabens requires rare compounding chemists conversant in natural preservative systems.
- Child-resistant packaging certification:ISO 8317 compliance testing for multi-dose bottles extends time-to-market by four to six months for new SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cough Syrup Market |
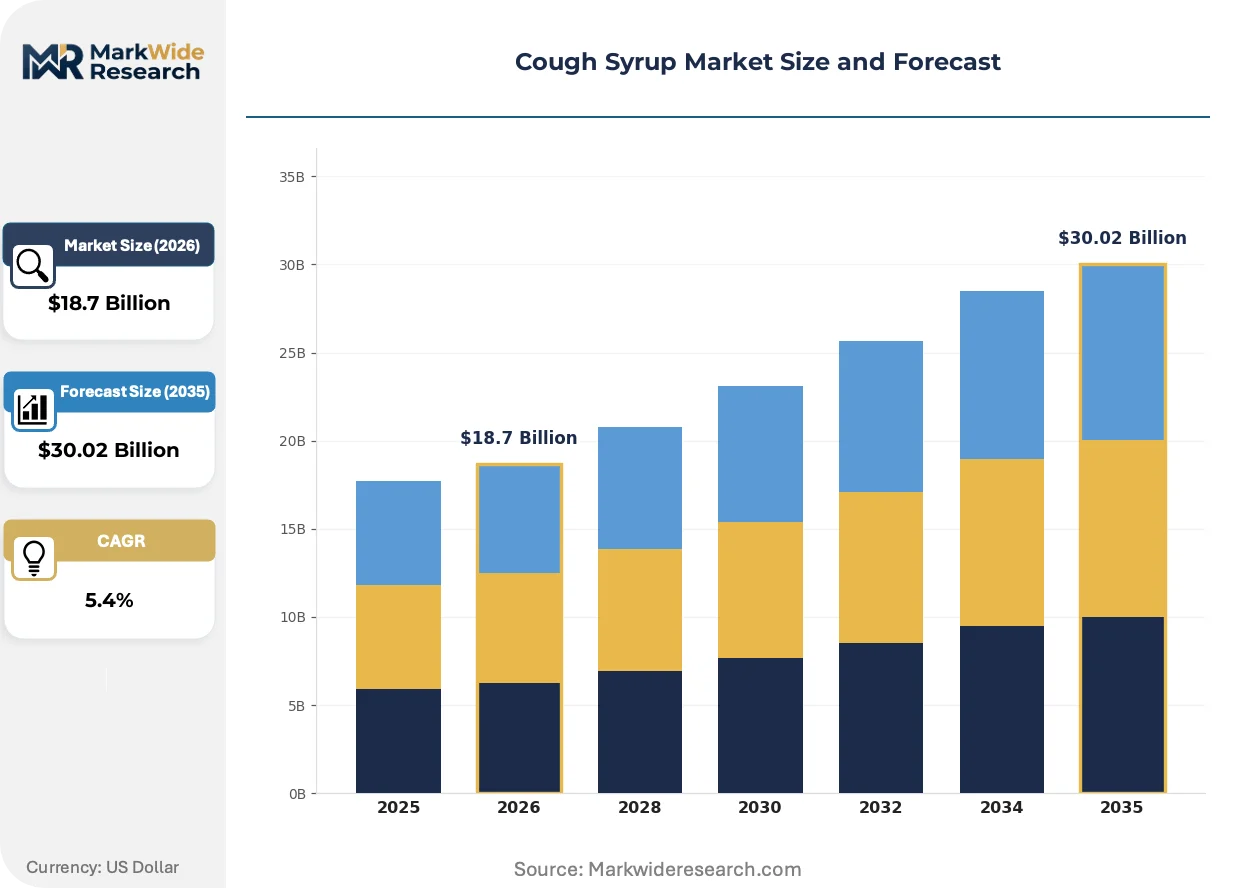
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Cough Syrup, Wet Cough Syrup, Pediatric Syrup, Herbal Syrup Formulation: Liquid, Syrup, Tablet, Powder End User: Adults, Children, Hospitals, Pharmacies Distribution Channel: Online, Pharmacy, Health Store, Supermarket |
| Companies Covered | Novartis AG, Bayer AG, Johnson & Johnson, Abbott Laboratories, Reckitt Benckiser Group plc, Pfizer Inc., Sanofi SA, Boehringer Ingelheim International GmbH, GlaxoSmithKline PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cough Syrup Market Strategic Shifts & Innovations
Clean-label ingredient migration and algorithmic flavor-masking systems are compressing traditional formulation development cycles while opening premium positioning for heritage botanical brands.
Botanical mucolytic extraction technology is migrating from batch solvent processing to continuous supercritical CO2 systems. Pediatric-focused manufacturers in Germany and Switzerland are retrofitting mid-scale facilities to capture terpene fraction consistency. This shift is compressing extract standardization timelines from eighteen months to under six months.
FDA's 2023 guidance on cough-cold efficacy claim substantiation now mandates pediatric pharmacokinetic data for any new antitussive submission. The industrial consequence is a tripling of clinical trial costs for novel actives. Dry cough segments with existing grandfathered claims are consolidating shelf presence while newcomers retreat to expectorant positioning.
Parental purchasing through pharmacy-integrated telehealth platforms now accounts for the fastest volume expansion in seasonal categories. Traditional clinic-to-pharmacy referral chains are losing script capture to video-consultation services with embedded e-prescription fulfillment. This channel rotation is most visible in US suburban markets with high dual-income household density.
Cough Syrup Market Segmentation
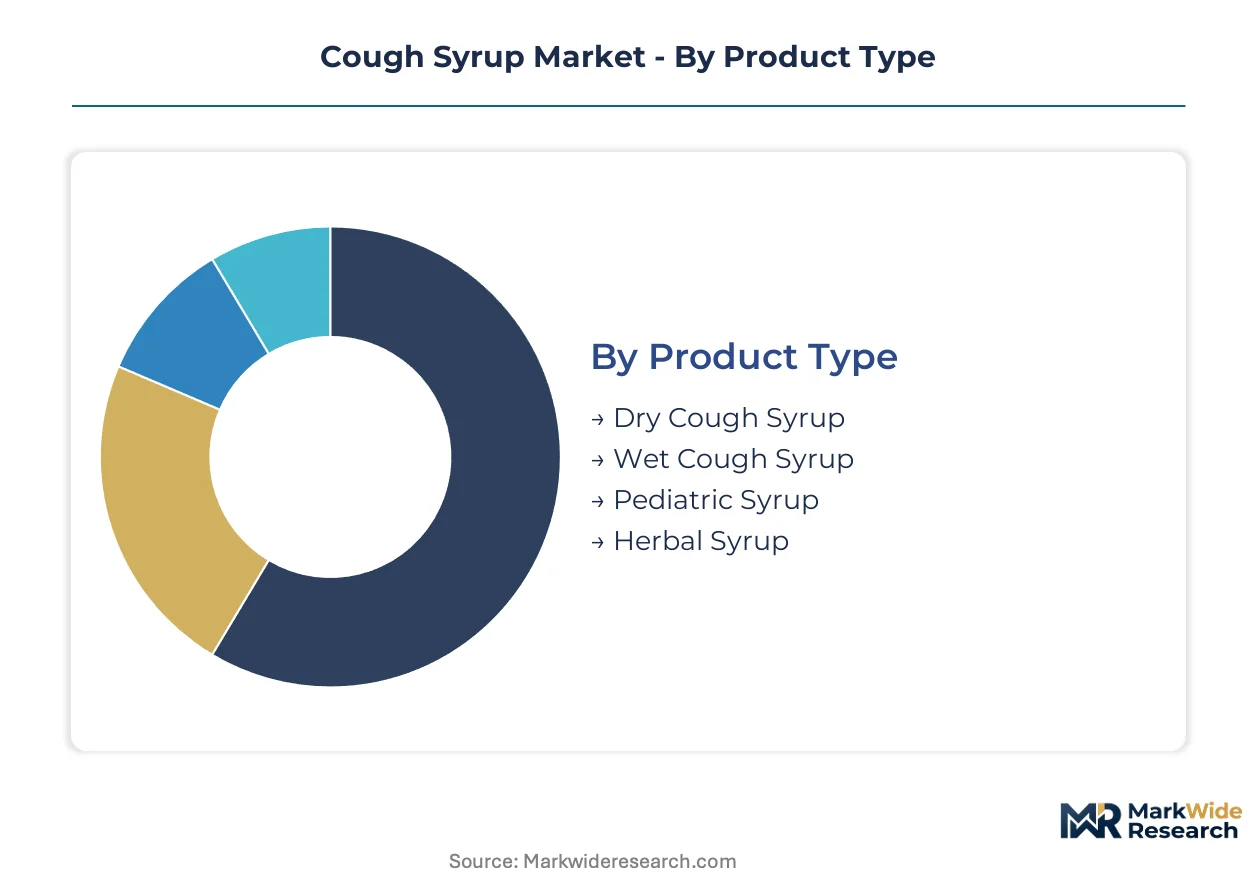
Cough syrup manufacturers segment portfolios across four dimensions to align formulation investment with regulatory pathways and channel economics. Product type and distribution channel decisions concentrate margin capture, while formulation and end-user targeting determine clinical validation requirements.
Product Type:
Cost tier stratification separates premium-positioned formulations from commodity expectorants, with pediatric and dry cough variants commanding manufacturing complexity premiums.
- Dry Cough Syrup:Dextromethorphan-based formulations suppress cough reflex through central nervous system action. Demand concentrates in US and European pharmacy chains where scheduling restrictions have compressed supply availability. Reformulation toward non-narcotic antitussives is accelerating R&D timelines for manufacturers holding grandfathered claims.
- Pediatric Syrup:Sugar-free, colorant-free formulations with calibrated dosing systems serve household medicine cabinet replenishment cycles. Palatability engineering through proprietary polymer masking systems drives per-unit cost inflation. India and Southeast Asia sustain volume baselines through post-pandemic stocking behavior.
- Wet Cough Syrup:Guaifenesin expectorants reduce mucus viscosity for productive cough management. Standardized manufacturing enables cost-competitive positioning.
- Herbal Syrup:Ivy leaf and thyme derivatives leverage clean-label migration trends. Supercritical CO2 extraction investments concentrate in German and Swiss facilities.
Dry Cough Syrup holds installed capacity. Pediatric Syrup is rotating up the share rankings.
Formulation:
Application suitability determines packaging, stability, and dosing precision requirements across acute care and self-medication contexts.
- Liquid:Hydroalcoholic or aqueous bases enable rapid absorption and flexible dose titration. Demand concentrates in hospital and acute care settings where precise milliliter delivery supports IV-to-oral transition protocols. Paraben-free preservation systems require rare compounding expertise.
- Syrup:Viscous aqueous bases with suspended actives dominate retail pharmacy and household segments. Viscosity engineering for pediatric palatability drives formulation differentiation. Southeast Asian markets show concentrated demand for high-viscosity variants.
- Tablet:Compressed solid dosage forms support travel and workplace compliance. Shelf stability advantages reduce cold-chain dependency.
- Powder:Reconstitutable sachets address portability and dose-flexibility needs. Concentrated manufacturing in India serves price-sensitive export markets.
Liquid formulations hold installed capacity. Syrup is rotating up the share rankings.
End User:
Customer type segmentation separates institutional procurement from direct-to-patient fulfillment, with distinct regulatory and margin profiles.
- Adults:Self-medication drives pharmacy and online channel concentration. Combination cold-cough protocols support subscription replenishment models in temperate-climate US suburban markets with high dual-income household density.
- Children:FDA pediatric pharmacokinetic requirements and WHO rational-use guidelines constrain formulation strategies. India and Southeast Asia sustain volume through household stocking cycles for sugar-free variants.
- Hospitals:Institutional procurement emphasizes unit-dose packaging and formulary compliance. EMA labeling harmonization enables cross-border SKU rationalization for multinational suppliers.
- Pharmacies:Chain consolidation in Vietnam and Indonesia creates shelf-space leverage for branded lines with clinician detailing support.
Adult self-medication holds installed capacity. Pediatric segments are climbing the fastest.
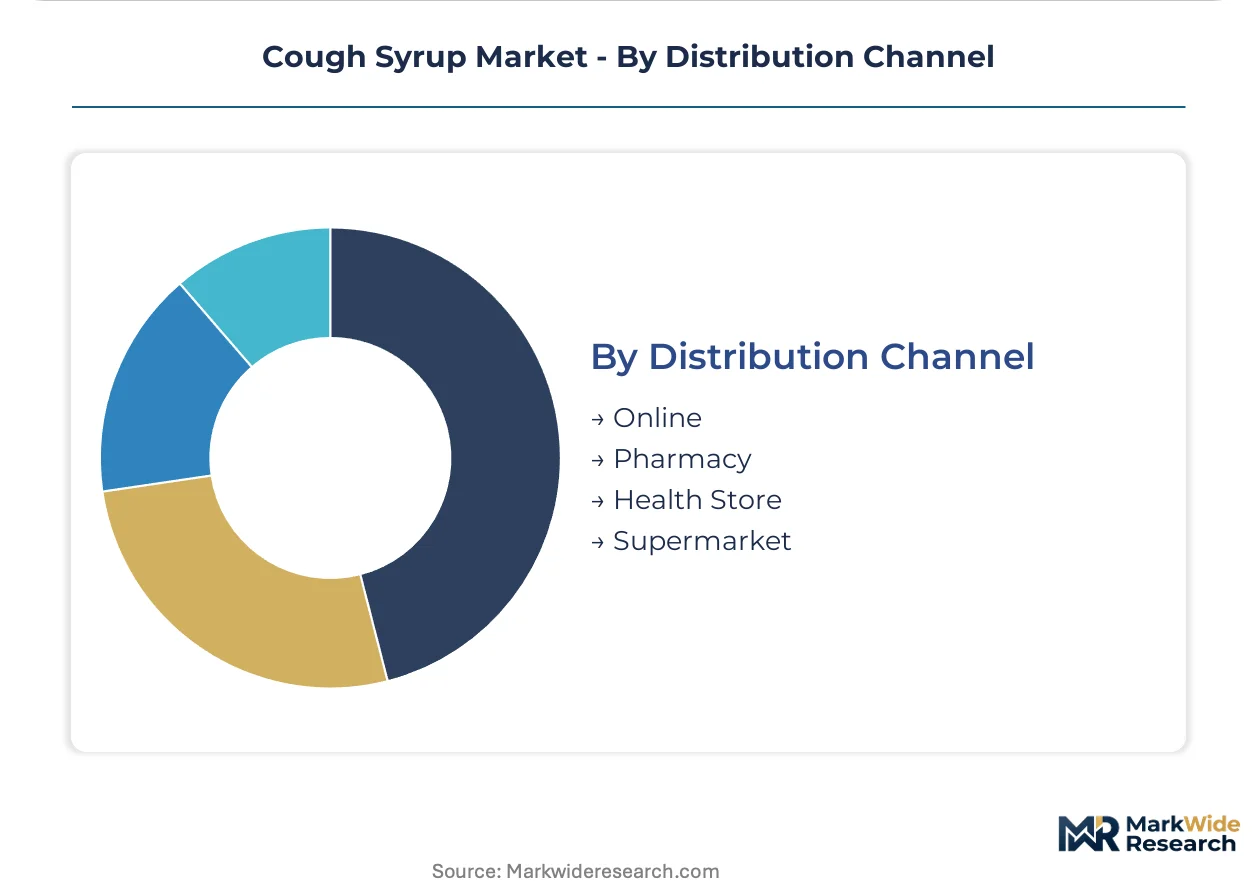
Distribution Channel:
Volume concentration shifts from traditional retail footprints toward pharmacy-integrated telehealth platforms.
- Online:Pharmacy-integrated telehealth platforms with embedded e-prescription fulfillment capture fastest volume expansion. US suburban markets with high dual-income household density show concentrated adoption. Direct-to-patient fulfillment normalizes post-pandemic purchasing behavior.
- Pharmacy:Chain consolidation in Ho Chi Minh City and Hanoi creates shelf-space leverage for branded pediatric lines. Clinician detailing networks sustain European positioning.
- Health Store:Clean-label and botanical positioning targets wellness-oriented consumers. Heritage brand equity supports premium pricing.
- Supermarket:Mass-market penetration for standardized expectorants. Price competition compresses margin profiles.
Pharmacy holds installed capacity. Online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports cough syrup formulations to Southeast Asian and African markets, while Germany ships botanical extracts to North American clean-label brands. This trade-flow pattern concentrates manufacturing investment in Indian pharmaceutical clusters and Swiss-German extraction facilities.
United States
Pediatric household replenishment and telehealth prescribing sustain volume baselines. FDA's 2023 efficacy claim substantiation guidance mandates pediatric pharmacokinetic data for novel antitussives. New Jersey-based manufacturing anchors supply for pharmacy-integrated e-prescription platforms.
Germany
Herbal syrup demand and clinician detailing networks concentrate European positioning. EMA labeling harmonization enables cross-border SKU rationalization for multinational portfolios. Bavarian extraction facilities retrofit supercritical CO2 systems for ivy leaf and thyme derivatives.
India
Post-pandemic medicine cabinet stocking cycles drive sugar-free pediatric volumes. CDSCO governs active pharmaceutical ingredient purity and child-resistant packaging mandates. Mumbai and Hyderabad pharmaceutical clusters scale regional distribution for Southeast Asian export markets.
Vietnam
Chain consolidation in Ho Chi Minh City and Hanoi creates shelf-space leverage for branded lines. The national pharmaceutical regulator enforces packaging standards aligned with ASEAN harmonization. Pharmacy modernization investments concentrate foreign manufacturer attention on clinician detailing support.
Switzerland
Clean-label migration and premium botanical positioning command manufacturing complexity premiums. Swissmedic oversees marketing claim substantiation and extract standardization protocols. Basel-area facilities lead continuous extraction technology adoption for terpene fraction consistency.
Cough Syrup Market Key Industry Players
Channel-controlling players compete with product-specialist players across pharmacy, telehealth, and direct-to-consumer vectors. The vendor base stratifies into heritage pharmaceutical conglomerates, pediatric-focused consumer health divisions, and botanical extraction specialists. Three archetypes dominate: vertically integrated API-to-shelf operators, brand-equity-leveraged consumer health units, and patent-focused botanical fractionation developers. Capacity expansion in Vietnamese pharmacy chains and strategic partnerships for telehealth platform integration represent the dominant competitive moves.
Among heritage pharmaceutical conglomerates, Novartis AG and Bayer AG exemplify the vertically integrated archetype with API-to-shelf control. Johnson & Johnson occupies a position representing brand-equity-leveraged consumer health positioning through pediatric-focused lines. Boehringer Ingelheim International GmbH anchors the European respiratory heritage tier with clinician detailing networks.
| Leading Market Players |
|---|
| Novartis AG |
| Bayer AG |
| Johnson & Johnson |
| Abbott Laboratories |
| Reckitt Benckiser Group plc |
| Pfizer Inc. |
| Sanofi SA |
| Boehringer Ingelheim International GmbH |
| GlaxoSmithKline PLC |
| Others |
Cost & Logistics Intelligence
Overcapacity in eastern Chinese dextromethorphan precursor facilities is compressing contract pricing for dry cough formulations while simultaneously eroding supplier leverage in price renegotiations with multinational buyers.
Pricing Analysis
Cost-plus contracts with API indexation dominate procurement between Indian formulation manufacturers and Chinese precursor suppliers. Three-tier pricing structure across premium pediatric lines, standard expectorants, and economy wet cough variants reflects palatability engineering investments and certification grade. Pricing pressure stems from CDSCO-mandated child-resistant packaging upgrades that inflate per-unit COGS. Pediatric segments show lowest price sensitivity due to parental willingness-to-pay for sugar-free, colorant-free claims, while wet cough commoditization drives intense supermarket price competition.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Vietnamese pharmacy chains consolidating shelf space in Ho Chi Minh City and Hanoi. Dextromethorphan precursor manufacturing clusters in eastern China, guaifenesin synthesis in India, and supercritical CO2 extraction facilities in Germany form the tripartite supply backbone. Single-source vulnerability concentrates in Chinese API precursors subject to export license variability. Distribution runs through pharmacy-integrated telehealth platforms capturing fastest volume expansion in US suburban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth prescribing normalization is transforming cough syrup distribution into a platform-economics environment where e-prescription fulfillment interoperability determines script capture rates.
For Market Incumbents: Pre-empt subscription replenishment model adoption by integrating with pharmacy-integrated telehealth platforms before platform gatekeepers consolidate fulfillment relationships. Backward integration into supercritical CO2 extraction capacity in Switzerland or Germany secures terpene fraction consistency for clean-label positioning against commoditized synthetic actives.
For New Entrants and Emerging Players: Pursue white-space targeting in Vietnamese pharmacy modernization by securing clinician detailing partnerships with chain consolidators in Ho Chi Minh City and Hanoi. Direct-to-consumer subscription models for seasonal allergy-cough combination protocols offer the most penetrable entry vector in US suburban dual-income households.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among botanical extraction specialists with patentable fractionation processes for ivy leaf and thyme derivatives. Long-term viability over the projection horizon favors acquisition targets with captive supercritical CO2 capacity and existing Swissmedic or EMA extract standardization protocols. Watch for FDA scheduling decisions on dextromethorphan as the inflection signal requiring portfolio restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Swiss and German facilities capture terpene consistency for clean-label premium positioning. |
| Telehealth Platform Integration | Pharmacy-embedded e-prescription fulfillment expands addressable reach beyond traditional retail footprints. |
| Botanical IP Development | Patentable ivy leaf and thyme fractionation processes create defensible positioning against synthetic commoditization. |
| Vietnamese Pharmacy Chain Partnership | Clinician detailing support with Ho Chi Minh City and Hanoi consolidators secures shelf-space leverage. |
| Pediatric Formulation Reformulation | Sugar-free, colorant-free engineering aligns with FDA pharmacokinetic requirements and WHO rational-use guidelines. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with respiratory brand managers, pediatric formulation scientists, pharmacy procurement directors, and telehealth platform integration specialists. Secondary validation drew from FDA 2023 guidance documents, EMA labeling harmonization protocols, CDSCO packaging mandates, WHO rational-use guidelines, and ClinicalTrials.gov pediatric pharmacokinetic study registrations. Bottom-up volume modeling across product type, formulation, end user, and distribution channel segments was triangulated against top-down value estimates derived from trade flow analysis.
Calibration against historical volume trajectories and regulatory milestone timing anchored growth rate derivation across the projection horizon. Segmentation dimensions modeled include dry cough, pediatric, wet cough, and herbal product types; liquid, syrup, tablet, and powder formulations; adult, children, hospital, and pharmacy end users; and online, pharmacy, health store, and supermarket distribution channels. API supply concentration indices and telehealth penetration curves served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated API-to-shelf operators or platform-native direct-to-consumer entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Vasopressin Antagonists Market