
 Middle East and Africa Small Molecule Sterile Injectable Drugs Market | 2026-2036
Middle East and Africa Small Molecule Sterile Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Small Molecule Sterile Injectable Drugs Market Foresight
Multi-source API procurement is consolidating across the Middle East and Africa small molecule sterile injectable drugs supply base. Hikma Pharmaceuticals PLC leverages regional manufacturing assets in Egypt and Jordan to sustain cost-competitive lyophilized powder output. Pfizer Inc. anchors hospital channel access through direct tender participation with Gulf health authorities. Teva Pharmaceutical Industries Ltd. competes on portfolio breadth, extending its injectable generics presence across Sub-Saharan African markets.
Small molecule sterile injectable drugs comprise chemically synthesized active pharmaceutical ingredients formulated as pyrogen-free liquid or reconstitutable dosage forms, manufactured under aseptic processing conditions with terminal sterilization or filtration. These products deliver precise bioavailability for critical therapies where oral administration proves ineffective or contraindicated. Antibiotics and antineoplastics occupy the dominant volume positions, reflecting infectious disease burden and oncology expansion across the region. Lyophilized powders command premium positioning due to extended shelf stability requirements in climates with challenging cold chain infrastructure. Intravenous administration leads route preference in hospital settings, while subcutaneous formulations gain traction in homecare transitions.
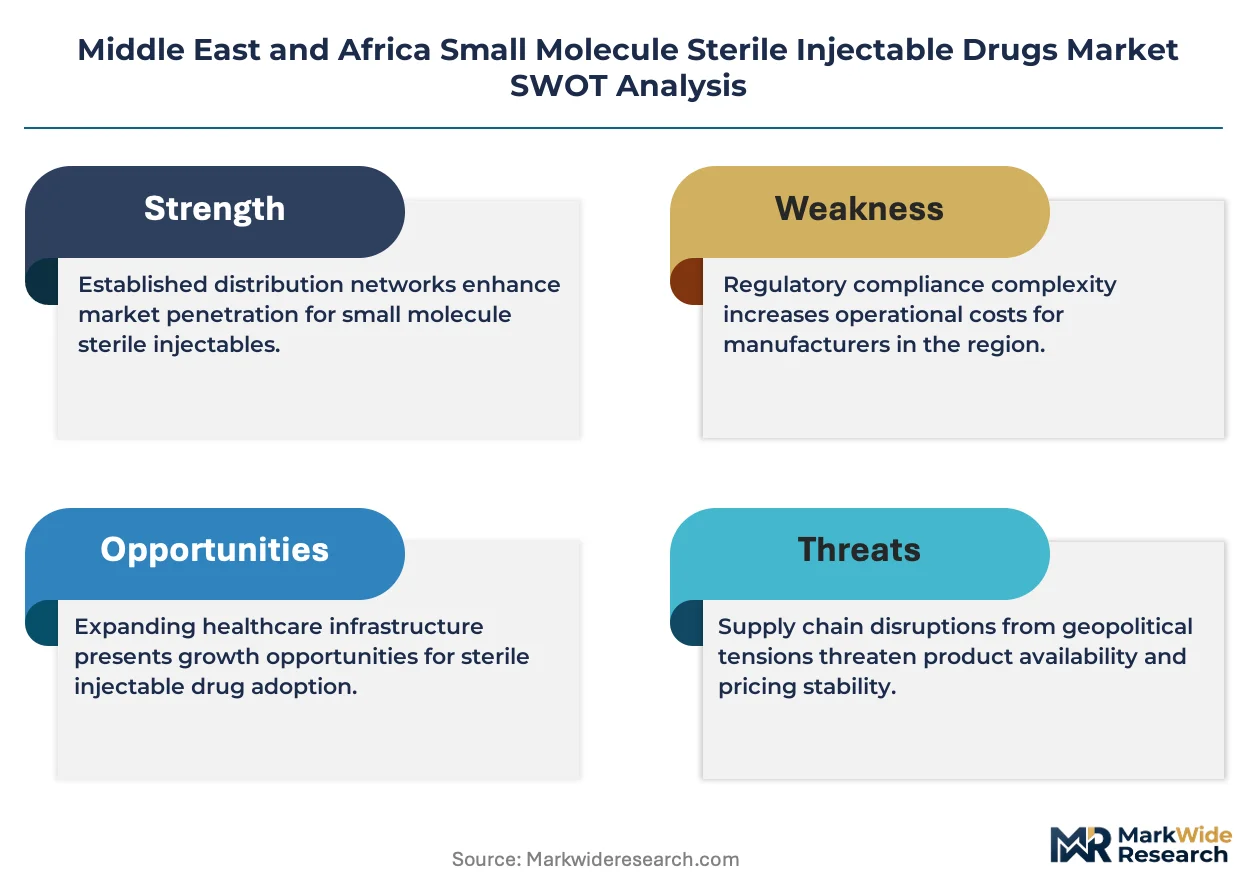
South Africa's SAHPRA, Saudi Arabia's SFDA, and Egypt's EDA enforce divergent batch release and stability testing requirements that fragment registration timelines for multinational suppliers. The EU's MDR-equivalent technical standards increasingly influence Gulf Cooperation Authority procurement specifications, raising documentation burdens for non-European manufacturers. Stakeholders must monitor harmonization initiatives between African Medicines Agency formation and existing national regulatory pathways to anticipate centralized approval advantages.
Market Dynamics
Hospital procurement centralization across Gulf Cooperation Authority member states is compressing supplier margins while amplifying volume concentration. Tertiary care networks in Saudi Arabia and the United Arab Emirates now consolidate antibiotic and antineoplastic purchasing through Ministry of Health tender platforms, favoring manufacturers with regional fill-finish capabilities.
Growth Catalysts
- SFDA centralized purchasing mandates:Saudi Arabia's regulatory authority drives volume commitments for aqueous solution formulations through national tender aggregation, reducing transaction costs for qualified suppliers.
- Oncology expansion in tertiary hospitals:Antineoplastic demand accelerates as chemotherapy protocols standardize across Cairo, Johannesburg, and Riyadh treatment centers.
- Lyophilization technology adoption:Regional manufacturers deploy advanced freeze-drying systems to extend shelf stability in climates with limited cold chain infrastructure.
Market Restraints
- API import dependency:Active pharmaceutical ingredient supply concentrates on Asian contract manufacturers, exposing regional formulators to freight cost volatility and customs delays.
- SAHPRA sterility testing protocols:South Africa's health product regulatory authority enforces batch release timelines that extend working capital cycles for multinational entrants.
- Biologic substitution pressure:Monoclonal antibodies and biosimilars displace small molecule antineoplastics in premium oncology segments across Gulf private hospital networks.
Strategic Opportunities
- Sub-Saharan African distribution gaps:Nigeria and Kenya present underpenetrated hospital channels where injectable antibiotic demand exceeds qualified supplier presence.
- EDA localization incentives:Egypt's drug authority offers accelerated registration pathways for manufacturers establishing domestic fill-finish operations.
- Homecare subcutaneous transitions:Subcutaneous formulation demand rises as oncology patients shift from infusion centers to ambulatory settings in South African metropolitan areas.
Industry Challenges
- Aseptic processing technician scarcity:Qualified personnel shortages constrain batch throughput expansion at regional manufacturing facilities.
- Stability testing documentation burdens:Divergent batch release requirements between SAHPRA, SFDA, and EDA fragment regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Small Molecule Sterile Injectable Drugs Market |
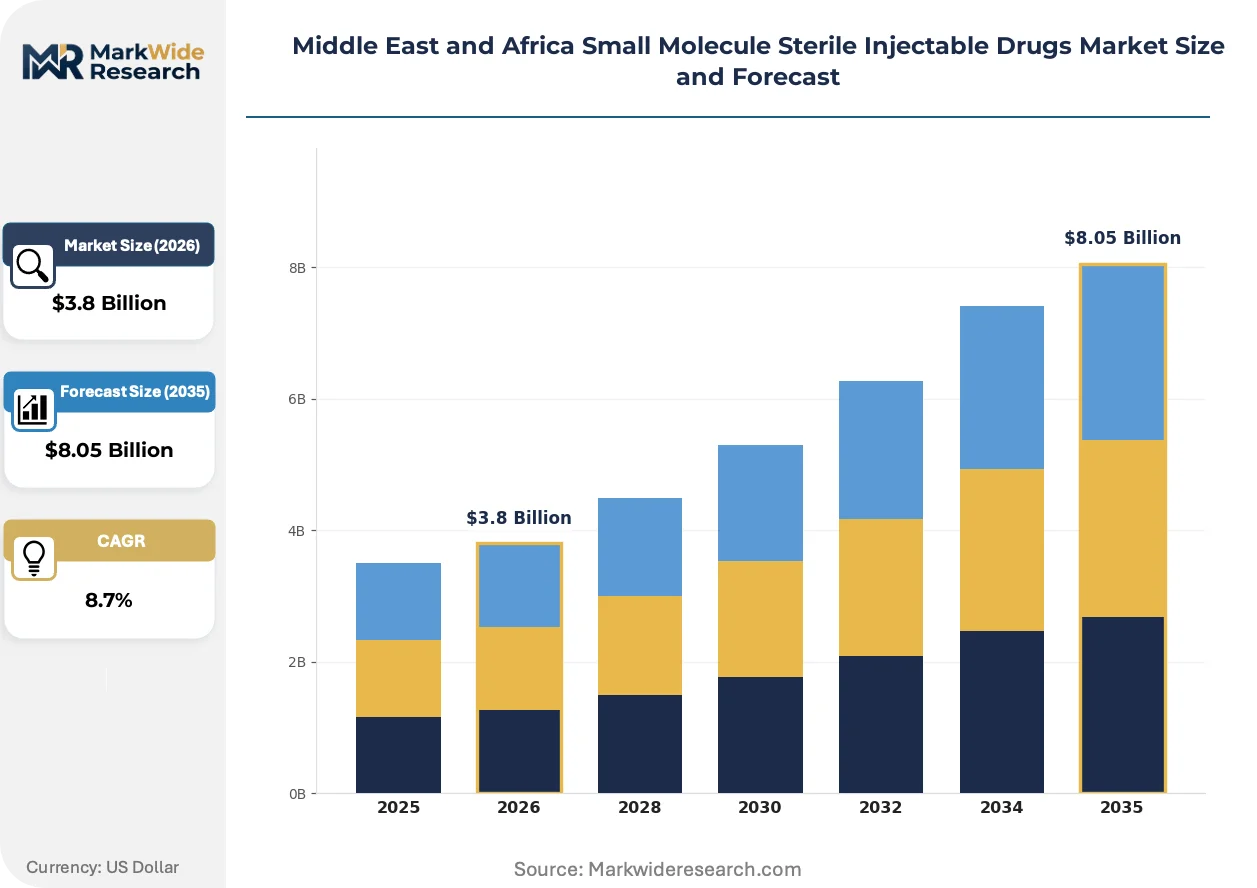
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Antineoplastics, Vaccines End User: Hospitals, Clinics, Homecare, Research Labs Formulation: Aqueous Solutions, Lyophilized Powders, Emulsions, Suspensions Route of Administration: Intravenous, Intramuscular, Subcutaneous, Intra-articular |
| Companies Covered | Hikma Pharmaceuticals PLC, Sanofi, Pfizer Inc., AstraZeneca, Merck Sharp & Dohme Corp., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Gilead Sciences, Inc., Ateco Pharma, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Small Molecule Sterile Injectable Drugs Market Shifts & Advancements
Formulation technology and regulatory harmonization are reshaping competitive positioning across the Middle East and Africa small molecule sterile injectable landscape. Manufacturers now prioritize technologies that reduce cold chain dependency while navigating fragmented approval pathways.
Blow-fill-seal aseptic processing technology is consolidating market share among regional antibiotic manufacturers. Egyptian and Jordanian facilities deploy this continuous manufacturing approach to reduce particle contamination risk in liquid injectable production. Hospital procurement committees in Saudi Arabia and the United Arab Emirates now specify BFS-derived products in tender documentation, compressing demand for conventional vial filling lines.
EU MDR-equivalent technical standards are reshaping Gulf Cooperation Authority procurement specifications. Health authorities in Qatar, Kuwait, and Oman now require CE-marked device components for combination products, elevating documentation burdens for non-European suppliers. Injectable drug-device combination manufacturers must retrofit quality management systems to satisfy dual regulatory recognition.
Centralized tender platforms are displacing fragmented hospital-level purchasing across Gulf health systems. Ministry of Health aggregators in Saudi Arabia now manage antibiotic and antineoplastic procurement through unified digital portals, consolidating buyer power. This concentration is most visible in Riyadh and Jeddah tertiary networks, where annual volume commitments exceed individual hospital procurement scales by an order of magnitude.
Middle East and Africa Small Molecule Sterile Injectable Drugs Market Segmentation
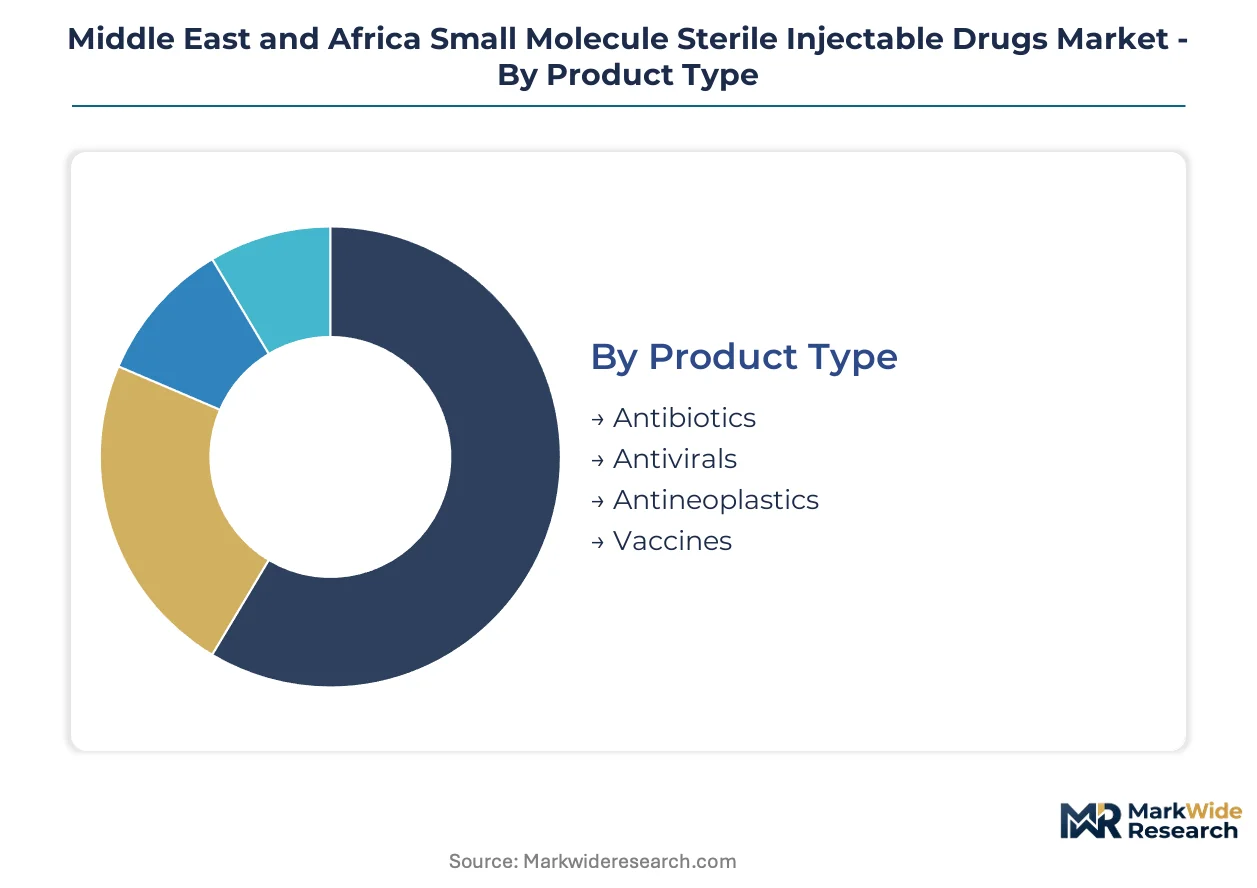
Segmentation in the Middle East and Africa small molecule sterile injectable drugs market reveals how capital requirements, regulatory complexity, and distribution infrastructure shape competitive entry points. Manufacturers prioritize segments where formulation technology and cold chain capabilities align with regional procurement specifications.
Product Type:
Antineoplastics and antibiotics demand the heaviest upfront investment in specialized containment facilities and cytotoxic handling infrastructure across regional manufacturing hubs.
- Antibiotics:Beta-lactam and cephalosporin formulations require dedicated fermentation-derived API processing lines with validated sterility assurance. Hospital procurement in Saudi Arabia and the United Arab Emirates concentrates demand through Ministry of Health tender platforms, favoring suppliers with regional fill-finish capacity.
- Antineoplastics:Cytotoxic small molecules necessitate isolator technology and dedicated manufacturing suites with occupational exposure band controls. Tertiary oncology centers in Cairo, Johannesburg, and Riyadh drive volume as chemotherapy protocols standardize across Gulf and Sub-Saharan African networks.
- Antivirals:Nucleoside analog injectables serve hepatitis and HIV treatment programs with shorter production runs and lower capital barriers.
- Vaccines:Sterile injectable vaccines occupy a distinct regulatory pathway with separate cold chain requirements from therapeutic small molecules.
Antibiotics absorb the bulk of installed capacity; antineoplastics are expanding most quickly.
End User:
Customer concentration patterns determine margin structures, with institutional buyers wielding disproportionate negotiating leverage through centralized procurement mechanisms.
- Hospitals:Tertiary care networks in Gulf Cooperation Authority member states aggregate antibiotic and antineoplastic demand through unified digital tender portals. Saudi Arabia's Ministry of Health and the United Arab Emirates' health authorities now manage annual volume commitments that exceed individual hospital procurement scales by an order of magnitude.
- Homecare:Subcutaneous formulation demand accelerates as oncology patients transition from infusion centers to ambulatory settings in South African metropolitan areas and Gulf private networks.
- Clinics:Secondary care facilities in Nigeria and Kenya present distribution gaps where injectable antibiotic demand exceeds qualified supplier presence.
- Research Labs:Clinical trial supply and investigator-initiated studies require small-batch sterile manufacturing with expedited batch release timelines.
Hospitals command the dominant share of commercial volume; homecare channels demonstrate the steepest expansion trajectory.
Formulation:
Technology selection directly constrains which markets manufacturers can serve given regional cold chain limitations and stability testing requirements.
- Lyophilized Powders:Freeze-dried formulations extend shelf stability beyond liquid alternatives, commanding premium positioning in climates with challenging cold chain infrastructure. Egyptian and Jordanian manufacturers deploy advanced lyophilization systems to supply Gulf markets where SAHPRA and SFDA enforce divergent stability testing protocols.
- Aqueous Solutions:Ready-to-administer liquid injectables dominate hospital procurement in Saudi Arabia, where centralized purchasing mandates specify aqueous formulations for antibiotic and antineoplastic tenders.
- Emulsions:Lipid-based parenteral nutrition and propofol formulations require specialized homogenization equipment with limited regional manufacturing presence.
- Suspensions:Insoluble drug delivery systems occupy niche therapeutic applications with constrained volume across Middle East and Africa markets.
Aqueous solutions capture the majority of tender volume; lyophilized powders are gaining share fastest in premium segments.
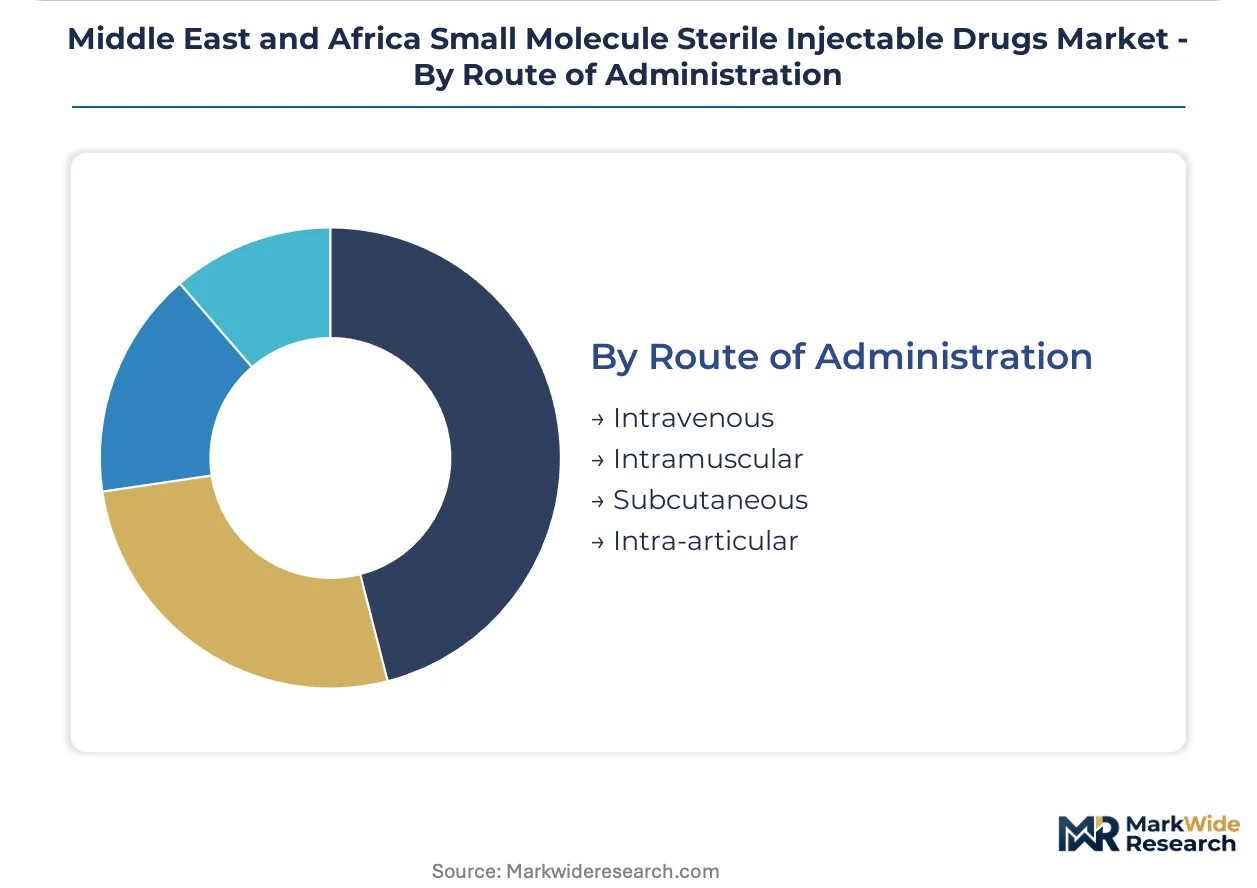
Route of Administration:
Delivery method selection shapes patient care settings and determines whether manufacturers compete for hospital contracts or ambulatory distribution partnerships.
- Intravenous:Infusion-based administration dominates antibiotic and antineoplastic delivery in tertiary hospital settings across Riyadh, Jeddah, Dubai, and Johannesburg treatment centers.
- Subcutaneous:Self-administration capability enables homecare transitions for maintenance oncology therapies in South African metropolitan areas and Gulf private networks.
- Intramuscular:Depot formulations and vaccine delivery utilize this route with established distribution through national immunization programs.
- Intra-articular:Joint injection therapies serve rheumatology and orthopedic segments with localized demand concentration in urban hospital clusters.
Intravenous administration retains the largest installed base; subcutaneous delivery is climbing the fastest as ambulatory care expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient import corridors through Egypt and Jordan anchor sterile injectable manufacturing capacity across the Middle East and Africa region.
Saudi Arabia
Ministry of Health centralized tender platforms aggregate antibiotic and antineoplastic demand through unified digital portals. SFDA mandates batch release documentation that aligns with EU MDR-equivalent technical standards for combination products. Riyadh and Jeddah tertiary care networks now manage annual volume commitments exceeding individual hospital procurement scales by an order of magnitude.
United Arab Emirates
MOHAP procurement specifications increasingly require CE-marked device components for injectable drug-device combinations. Private hospital networks in Dubai and Abu Dhabi drive demand for premium lyophilized formulations with extended shelf stability. The Emirates' logistics infrastructure supports regional distribution hub functions for Gulf Cooperation Authority markets.
South Africa
SAHPRA enforces sterility testing protocols that extend batch release timelines and elevate working capital cycles for multinational suppliers. Tertiary oncology centers in Johannesburg and Cape Town standardize chemotherapy protocols driving antineoplastic volume. Metropolitan homecare transitions accelerate subcutaneous formulation demand for maintenance therapies.
Egypt
EDA localization incentives offer accelerated registration pathways for manufacturers establishing domestic fill-finish operations. Egyptian facilities deploy blow-fill-seal aseptic processing technology for liquid antibiotic production serving Gulf export markets. Cairo-based manufacturing clusters leverage regional API sourcing corridors through Jordanian transit routes.
Nigeria
Hospital channel underpenetration creates distribution gaps where injectable antibiotic demand exceeds qualified supplier presence. The national pharmaceutical regulator maintains import licensing requirements that fragment registration timelines for multinational entrants. Lagos and Abuja metropolitan clusters concentrate tertiary care procurement capacity with limited domestic manufacturing presence.
Middle East and Africa Small Molecule Sterile Injectable Drugs Market Competitive Landscape
Capacity expansion dominates the current landscape as regional manufacturers deploy advanced lyophilization and blow-fill-seal systems to reduce cold chain dependency. The vendor base separates into three strategic archetypes: multinational pharmaceutical conglomerates with direct tender participation capabilities, regional specialists leveraging Middle Eastern manufacturing assets, and generic injectable suppliers extending presence across Sub-Saharan African distribution networks. Geographic expansion through EDA localization partnerships and portfolio diversification into subcutaneous formulations represent the dominant competitive moves reshaping market positioning.
Among regional manufacturing specialists, Hikma Pharmaceuticals PLC exemplifies the Middle Eastern production archetype through Egyptian and Jordanian facility networks. Pfizer Inc. and Teva Pharmaceutical Industries Ltd. occupy positions within the multinational tier, with the former anchoring hospital channel access through Gulf health authority relationships and the latter representing generic portfolio breadth strategies across African markets.
| Leading Market Players |
|---|
| Hikma Pharmaceuticals PLC |
| Sanofi |
| Pfizer Inc. |
| AstraZeneca |
| Merck Sharp & Dohme Corp. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Gilead Sciences, Inc. |
| Ateco Pharma |
| Others |
Supply & Pricing Matrix
CE-mark certification divergence between premium combination products and commodity vials manifests in both procurement premiums and supplier qualification burdens across Gulf hospital networks. Manufacturers with MDR-aligned device documentation command tender advantages in Saudi Arabia and the United Arab Emirates, while non-certified suppliers face price compression in Egyptian and Jordanian export channels.
Pricing Analysis
Warranty-bundled stability guarantees separate premium lyophilized formulations from unbundled aqueous solutions in Ministry of Health tenders. Contract-based long-term offtake dominates hospital procurement, with price differentiation driven by cold chain reliability certification and Gulf fill-finish proximity. Cost compression in standard aqueous antibiotics intensifies as centralized tender platforms aggregate buyer power. Public hospital networks exhibit highest price sensitivity; private oncology centers in Dubai and Abu Dhabi demonstrate lowest sensitivity due to brand loyalty and extended stability requirements.
Supply Chain Analysis
Single-source vulnerability sits with Indian and Chinese API manufacturers feeding Egyptian and Jordanian formulators. Active pharmaceutical ingredient supply draws from fermentation-derived beta-lactam corridors in India, synthetic chemistry hubs in China, and specialty cytotoxic precursors from European contract manufacturers. Tariff exposure on customs delays through Red Sea shipping lanes elevates working capital cycles for regional finishers. Distribution runs through Ministry of Health digital tender portals in Saudi Arabia, with secondary channels via South African metropolitan wholesalers serving Sub-Saharan African clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is transitioning from conventional vial filling to blow-fill-seal continuous manufacturing, with lyophilization technology displacing legacy batch processing in climates with limited cold chain infrastructure.
For Market Incumbents: Deepen backward integration into API sourcing corridors through Egyptian and Jordanian manufacturing assets to defend margin position against Asian contract manufacturer price competition. Invest in isolator technology and cytotoxic handling certification to maintain tender access as SFDA and MOHAP elevate combination product standards. Prioritize EDA localization partnerships to secure accelerated registration pathways before competitor capacity additions. For New Entrants and Emerging Players: Begin with subcutaneous formulation development for South African homecare transitions, where oncology patient ambulatory shifts outpace qualified supplier presence. Target Nigerian and Kenyan hospital channels where injectable antibiotic demand exceeds distribution infrastructure. Pursue blow-fill-seal technology licensing from established Egyptian manufacturers to bypass capital-intensive lyophilization barriers. For Investors and Strategic Acquirers: Re-rating potential sits with regional fill-finish specialists given EDA localization incentives and Gulf tender aggregation trends. Long-term viability favors manufacturers with dual regulatory recognition spanning SAHPRA sterility protocols and SFDA MDR-equivalent standards. Monitor harmonization progress between African Medicines Agency formation and existing national pathways as inflection indicator for centralized approval advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Freeze-drying investment extends shelf stability for Gulf climates with challenging cold chain infrastructure. |
| EDA Localization Partnership | Egyptian drug authority incentives accelerate registration timelines for domestic fill-finish operations. |
| Blow-Fill-Seal Technology Adoption | Continuous aseptic processing reduces particle contamination risk in liquid antibiotic production lines. |
| Subcutaneous Formulation Development | Self-administration capability captures oncology homecare transitions in South African metropolitan areas. |
| SFDA Regulatory Alignment | EU MDR-equivalent documentation satisfies Saudi tender requirements for combination product procurement. |
Research Methodology
Multi-period observation of hospital tender awards, batch release timelines, and manufacturing capacity utilization anchored the trend analysis, supplemented by interviews with regulatory affairs leads at Gulf health authorities, hospital procurement managers in Riyadh and Johannesburg, formulary directors at South African oncology networks, and aseptic processing technicians at Egyptian fill-finish facilities. Secondary validation drew from SAHPRA registration databases, SFDA guidance documents, EDA incentive circulars, Ministry of Health tender portals, and trade flow records through Jordanian transit corridors. Bottom-up facility capacity assessments triangulated against top-down therapeutic demand modeling.
Input-output matrices mapped active pharmaceutical ingredient throughput to finished dosage form output across Egyptian, Jordanian, and South African manufacturing hubs. Segmentation dimensions spanned product type, formulation technology, route of administration, end-user channel, and regional regulatory cluster. CAGRs were derived from volume trajectory fitting against tender aggregation trends and oncology protocol standardization rates. Forecast inputs incorporated lyophilization system deployment schedules and EDA localization incentive uptake patterns.
Underlying measurement precision varies by segment; lyophilized powder and antineoplastic categories carry tighter precision than aqueous antibiotic and clinic channel estimates due to concentrated manufacturer disclosure. Forecasts reflect assumptions on regulatory harmonization timelines and cold chain infrastructure investment flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Medical Nitroglycerin Spray Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Short-Acting Insulin Market