
 Antihistamines Market | 2026-2036
Antihistamines Market Size, Share, and Industry Trends Forecast 2026-2036
Antihistamines Market Outlook
Self-medicating consumers is rotating toward professional healthcare channels as reimbursement frameworks expand for allergy immunotherapy adjuncts. Sanofi leverages its consumer health division to sustain pharmacy shelf presence across Europe. Johnson & Johnson anchors the North American OTC segment through retail channel density. Pfizer competes on prescription-grade antihistamine portfolios in hospital formularies.
Antihistamines constitute a class of histamine receptor antagonists that block H1 receptors to suppress allergic inflammatory responses, with second-generation molecules engineered for reduced blood-brain barrier permeability to minimize sedation. Their primary commercial purpose spans symptomatic management of allergic rhinitis, urticaria, and pruritus across outpatient and self-care settings. Second-generation tablets command the largest revenue pool due to once-daily dosing compliance, while pediatric syrups represent the fastest-expanding formulation segment as caregivers seek age-appropriate delivery. Prescription channels retain higher margin structures for novel combination therapies, whereas OTC allergy relief applications dominate unit volume through supermarket and e-commerce distribution.
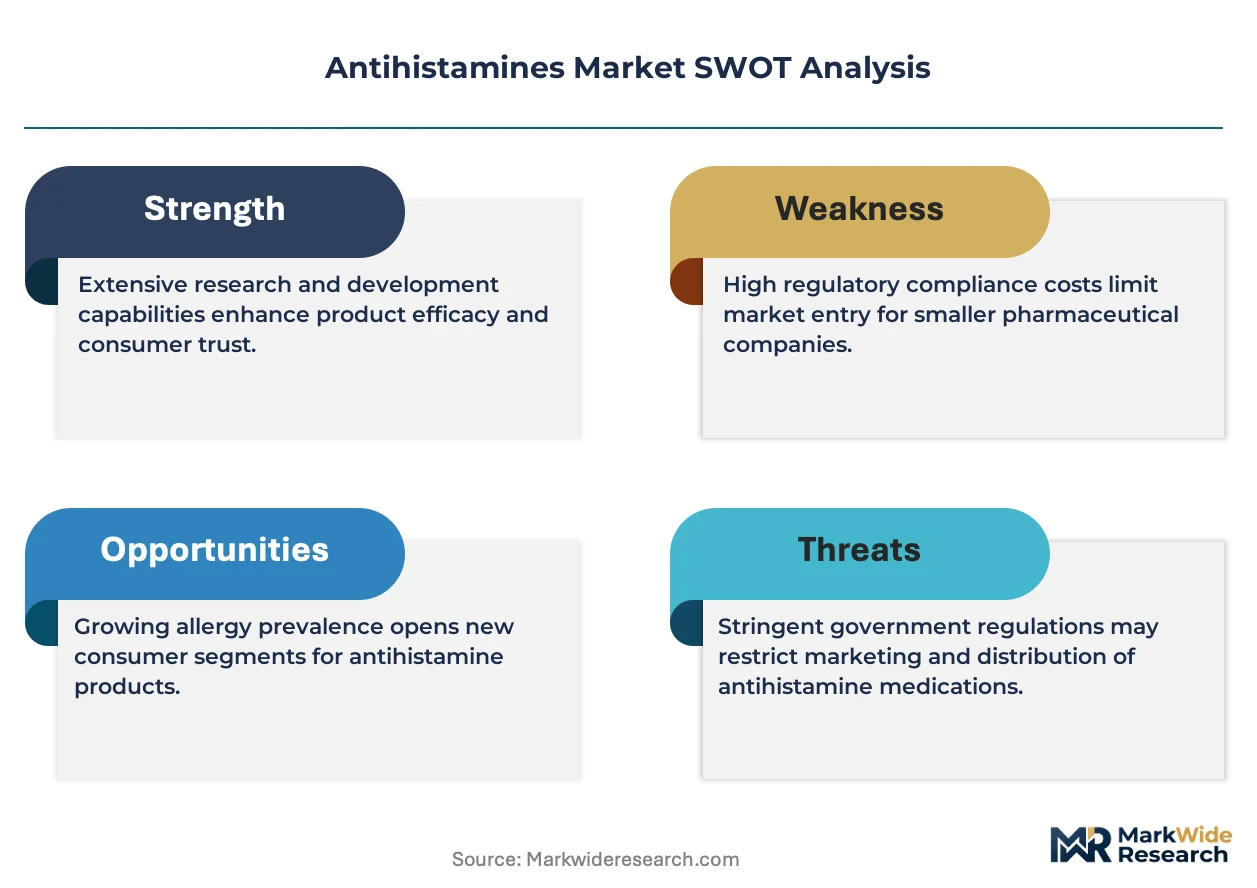
FDA OTC monograph reform and EMA pharmacovigilance requirements are tightening bioequivalence standards for generic antihistamine entrants, elevating documentation costs for smaller manufacturers. REACH compliance in Europe and EPA environmental assessment protocols for active pharmaceutical ingredients are additionally constraining synthesis pathways for first-generation compounds. Stakeholders must monitor evolving monograph classifications and regional purity mandates to align pipeline investments with compliance trajectories.
Market Dynamics
FDA OTC monograph reform is compressing formulation timelines for generic entrants while pediatric demand pulls manufacturers toward age-appropriate delivery systems. Second-generation molecules with reduced blood-brain barrier permeability now dominate prescription formularies as sedation-free profiles become baseline expectations.
Growth Catalysts
- Allergy immunotherapy reimbursement expansion:United States commercial payers now cover antihistamine adjuncts for sublingual immunotherapy protocols, channeling self-medicating consumers into professional healthcare settings.
- Pediatric syrup formulation innovation:Caregivers in Germany and France increasingly demand alcohol-free, dye-free liquid formulations that align with EMA pediatric investigation plan requirements.
- EMA pharmacovigilance harmonization:Standardized adverse event reporting across EU member states accelerates cross-border approval pathways for novel combination therapies.
Market Restraints
- API synthesis pathway constraints:REACH compliance in Europe and EPA environmental assessment protocols in the United States restrict chlorpheniramine and diphenhydramine manufacturing routes.
- Generic bioequivalence documentation costs:Smaller manufacturers face elevated analytical chemistry burdens to demonstrate pharmacokinetic parity under tightened FDA standards.
- First-generation compound obsolescence:Sedating antihistamines face substitution pressure from second-generation molecules in hospital discharge protocols and retail pharmacy substitution practices.
Strategic Opportunities
- Underpenetrated Latin American markets:Brazil's ANVISA streamlines OTC registration for second-generation antihistamines, opening pharmacy channel expansion for multinational portfolios.
- Combination therapy with leukotriene inhibitors:Fixed-dose montelukast-cetirizine formulations address refractory allergic rhinitis in Japanese allergy clinics.
- E-commerce direct-to-consumer channels:Subscription-based allergy relief platforms in Australia bypass traditional pharmacy markup structures.
Industry Challenges
- Formulation scientist talent scarcity:Pediatric taste-masking expertise and controlled-release polymer chemistry skills command premium compensation in contract manufacturing organizations.
- Legacy stability testing backlog:FDA monograph reform requires retrospective validation of decades-old generic formulations, congesting contract analytical laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antihistamines Market |
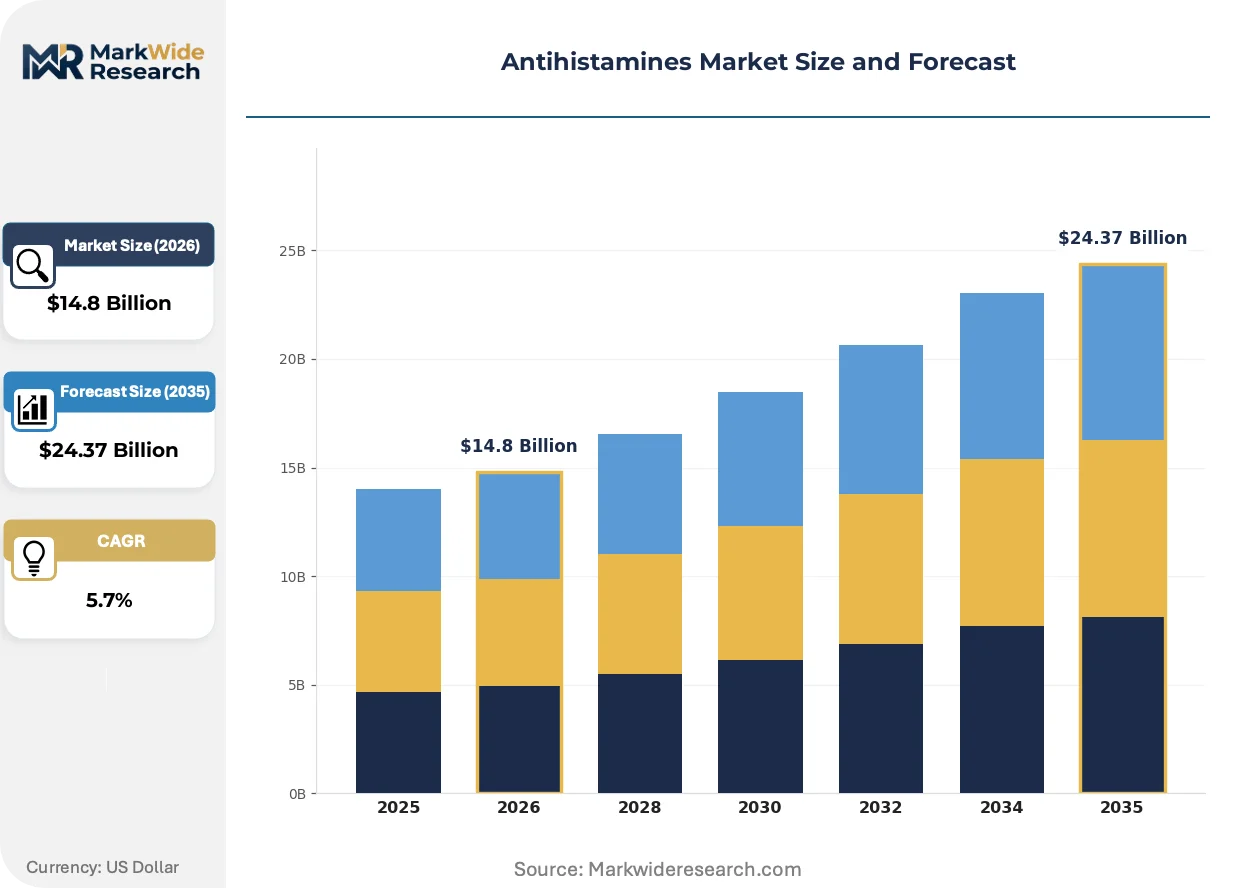
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: First-Generation, Second-Generation, Prescription, OTC Application: Allergy Relief, Cold Symptoms, Motion Sickness, Sleep Aid Formulation: Tablets, Syrups, Nasal Sprays, Inhalers End User: Adults, Pediatrics, Geriatrics, Healthcare Providers |
| Companies Covered | Merck & Co., Sanofi, Johnson & Johnson, AstraZeneca, GlaxoSmithKline, Novartis, Bayer, Almirall, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antihistamines Market Strategic Shifts
Orally disintegrating tablet technologies and intranasal spray delivery systems are compressing the competitive moat around traditional solid oral dosage forms. Regulatory pressure on excipient safety and environmental fate of active pharmaceutical ingredients is simultaneously reshaping formulation priorities.
Nanostructured lipid carrier systems for intranasal delivery is supplanting conventional aqueous spray formulations in European prescription markets. Allergy specialists in Switzerland and the Netherlands prescribe these carriers for rapid onset without systemic exposure. The technology is compressing the efficacy gap between oral and intranasal administration, eroding tablet dominance in seasonal rhinitis management.
EMA's revised guideline on environmental risk assessments for human pharmaceuticals now mandates fate-and-transport studies for all new molecular entities and significant formulation changes. Active pharmaceutical ingredient manufacturers must submit data on aquatic toxicity and biodegradation. Generic sponsors targeting the EU market are responding by reformulating with biodegradable polymer excipients and redesigning synthesis routes to eliminate persistent metabolites.
Subscription-based allergy management platforms now bundle diagnostic testing, personalized antihistamine regimens, and telehealth follow-up into single monthly fees. Direct-to-consumer channels in the United States and United Kingdom are capturing patients who previously self-selected OTC products through retail pharmacies. This model concentrates demand data with platform operators, shifting negotiating leverage away from traditional wholesale and retail pharmacy networks.
Antihistamines Market Segmentation
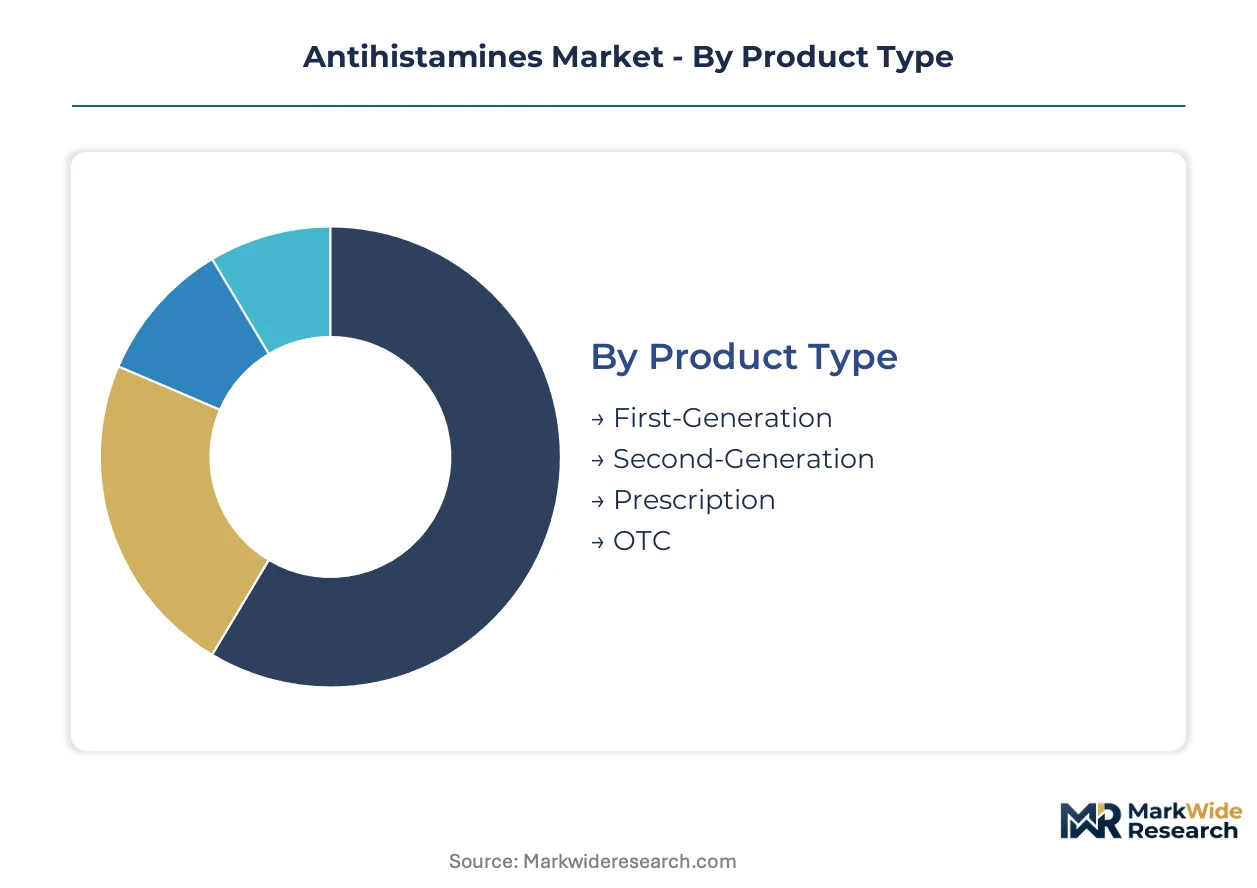
Antihistamine manufacturers align portfolio investments with distinct efficacy-sedation tradeoffs, age-appropriate delivery requirements, and channel-specific margin structures. Segmentation clarity determines which molecules capture prescription formulary placement versus retail shelf space.
Product Type:
Second-generation molecules face intensifying substitution pressure from novel combination therapies and intranasal delivery systems that bypass oral bioavailability constraints entirely.
- Second-Generation:Engineered for reduced blood-brain barrier permeability, these H1 antagonists deliver non-sedating efficacy for allergic rhinitis and chronic urticaria. Demand concentrates in United States commercial payer formularies where sedation-free profiles determine prior authorization pathways. FDA OTC monograph reform accelerates generic entry, compressing branded pricing power.
- OTC:Self-selection channels dominate unit volume through supermarket and e-commerce distribution, with cetirizine and loratadine commanding pharmacy shelf presence. Caregivers in Germany and France increasingly favor alcohol-free liquid variants for household stockpiling.
- First-Generation:Diphenhydramine and chlorpheniramine retain niche demand for acute allergic reactions despite sedation liabilities.
- Prescription:Novel combination therapies with leukotriene inhibitors target refractory cases in hospital discharge protocols.
OTC formulations anchor the volume base while prescription-grade combination therapies gain share at the steepest rate.
Application:
Cost tier differentiation separates symptomatic management commodities from premium immunotherapy adjuncts reimbursed under expanding United States commercial payer frameworks.
- Allergy Relief:Seasonal and perennial allergic rhinitis management drives the largest revenue pool, with second-generation oral tablets and intranasal sprays competing for patient preference. EMA pharmacovigilance harmonization accelerates cross-border approval for novel delivery systems in Netherlands and Switzerland allergy clinics.
- Sleep Aid:First-generation sedating properties repurposed for insomnia generate pharmacy traffic through nighttime formulation branding. United States retail channels exploit this dual-use positioning despite FDA scrutiny on marketing claims.
- Cold Symptoms:Multi-symptom relief combinations with decongestants face formulation constraints under tightened monograph standards.
- Motion Sickness:Meclizine and dimenhydrinate retain stable demand in travel retail and maritime supply channels.
Allergy relief applications dominate revenue concentration while sleep aid positioning climbs the fastest among repurposed indications.
Formulation:
Customer type requirements dictate delivery system priorities, with pediatric caregivers and geriatric patients pulling manufacturers toward age-appropriate administration formats.
- Tablets:Once-daily solid oral dosage forms command manufacturing scale efficiencies and supply chain density. Second-generation tablet dominance faces erosion from orally disintegrating technologies that bypass swallowing difficulties in geriatric populations.
- Syrups:Alcohol-free, dye-free liquid formulations align with EMA pediatric investigation plan requirements and caregiver preferences in France and Germany. Taste-masking expertise commands premium contract manufacturing rates.
- Nasal Sprays:Nanostructured lipid carrier systems in European prescription markets deliver rapid onset with reduced systemic exposure.
- Inhalers:Dry powder and metered-dose formats target lower respiratory allergic manifestations with limited current penetration.
Tablets retain the broadest installed base while syrup formulations expand most quickly on pediatric demand pull.
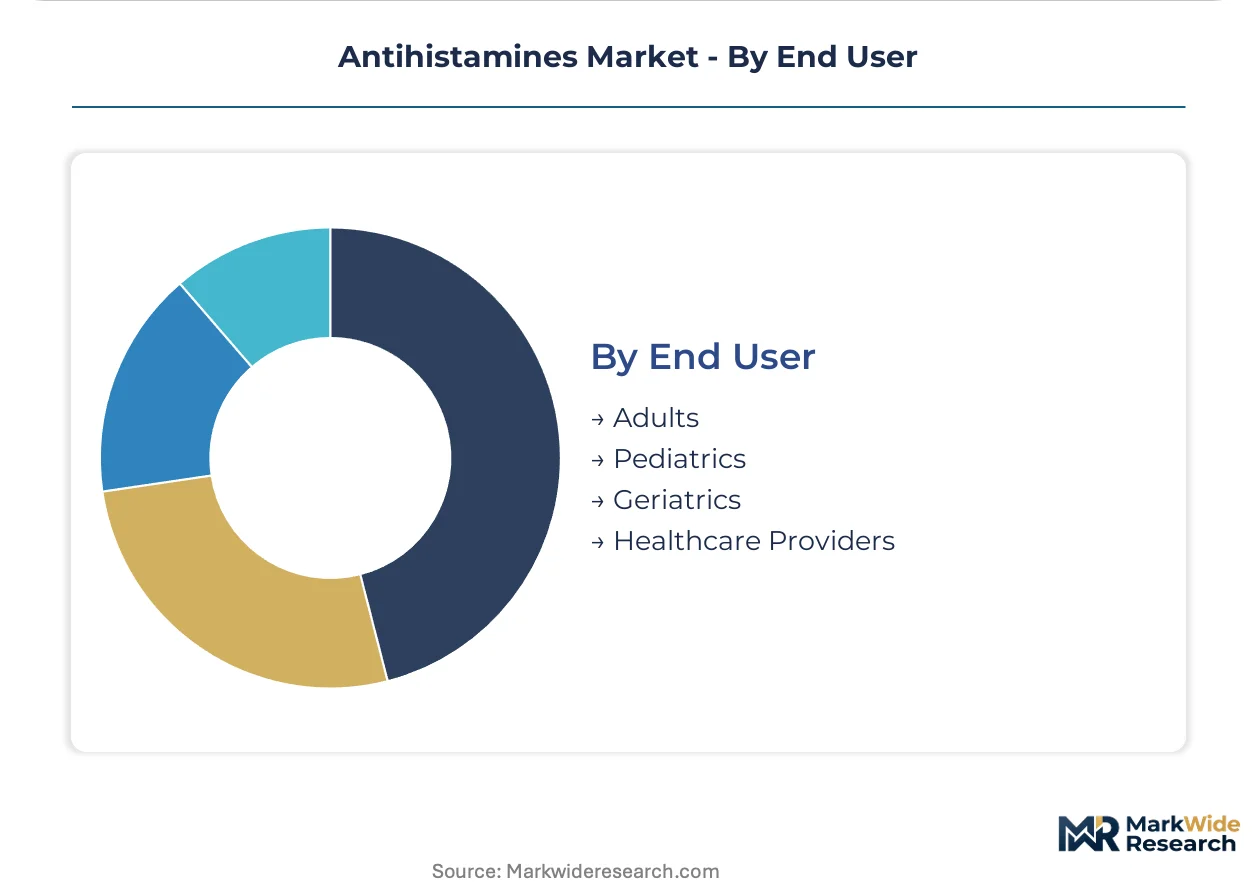
End User:
Volume concentration among adult self-medicating consumers contrasts with margin concentration in pediatric and healthcare provider channels where reimbursement and safety requirements elevate pricing.
- Adults:Working-age populations drive OTC self-selection through pharmacy and e-commerce channels, with once-daily compliance determining brand loyalty. United States subscription-based allergy platforms now capture this demographic through bundled diagnostic and telehealth services.
- Pediatrics:Caregiver demand for age-appropriate, alcohol-free formulations generates the steepest formulation innovation investment. EMA pediatric investigation plans and FDA pediatric labeling requirements create regulatory moats for compliant manufacturers.
- Geriatrics:Polypharmacy interactions and swallowing difficulties push demand toward orally disintegrating tablets and liquid alternatives.
- Healthcare Providers:Hospital formularies and allergy clinic protocols determine prescription-grade adoption for refractory cases.
Adult self-medication anchors volume throughput while pediatric applications attract the steepest R&D allocation and pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical exporters supply generic antihistamine APIs to formulation manufacturers across Germany, the United States, and Brazil. Finished dosage form trade flows from Switzerland and the United Kingdom toward Middle Eastern and Southeast Asian markets.
United States
Commercial payer reimbursement expansion for sublingual immunotherapy protocols pulls self-medicating consumers into professional healthcare channels. FDA OTC monograph reform tightens bioequivalence documentation requirements for generic entrants. New Jersey and Pennsylvania host dense clusters of contract manufacturing organizations serving pediatric syrup formulation demand.
Germany
Caregivers in Bavaria and North Rhine-Westphalia increasingly demand alcohol-free, dye-free liquid antihistamine formulations for household stockpiling. EMA pediatric investigation plan requirements create regulatory moats for compliant manufacturers. The Frankfurt-Rhine-Main pharmaceutical corridor concentrates formulation innovation investment for EMA-aligned export markets.
India
CDSCO streamlined approval pathways for second-generation antihistamine generics accelerate domestic production scale-up. Maharashtra and Gujarat host API synthesis facilities supplying cetirizine and loratadine intermediates to European formulators. Hyderabad's contract research sector specializes in taste-masking chemistry for pediatric liquid dosage development.
Brazil
ANVISA regulatory harmonization with FDA standards reduces registration timelines for multinational OTC portfolios. São Paulo and Rio de Janeiro pharmacy chains expand shelf space for non-sedating antihistamine alternatives. Southeast regional distributors channel imported finished dosages toward underpenetrated Northeast and Central-West markets.
Switzerland
Basel-area allergy clinics prescribe nanostructured lipid carrier intranasal systems for rapid-onset seasonal rhinitis management. Swissmedic maintains stringent pharmacovigilance standards that accelerate cross-border recognition across EU member states. The country's precision formulation sector supplies high-margin prescription-grade delivery technologies to German and French hospital formularies.
Antihistamines Market Competitive Environment
Player mix skews toward diversified pharmaceutical conglomerates with consumer health divisions alongside specialized respiratory and allergy-focused developers. Market structure concentrates around multinational portfolios spanning both prescription formulary placement and OTC retail channel density. Two strategic archetypes dominate: vertically integrated API-to-formulation operators controlling synthesis pathways, and brand-asset licensors leveraging trademark recognition across pharmacy networks. Competitive moves center on pediatric formulation patent filings and e-commerce direct-to-consumer platform partnerships.
Among diversified pharmaceutical conglomerates, Sanofi and Johnson & Johnson exemplify the dual-channel archetype spanning hospital formularies and retail pharmacy shelf presence. Pfizer occupies a position within the prescription-grade specialist tier, anchoring hospital discharge protocol adoption for refractory allergic rhinitis cases. Merck & Co. represents the research-intensive archetype with pipeline investment in novel combination therapies. These three entities collectively illustrate how scale, channel breadth, and therapeutic focus differentiate competitive positioning across reimbursement and self-pay segments.
| Leading Market Players |
|---|
| Merck & Co. |
| Sanofi |
| Johnson & Johnson |
| AstraZeneca |
| GlaxoSmithKline |
| Novartis |
| Bayer |
| Almirall |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day API inventory buffers in European formulation facilities compress margin recovery timelines when Indian intermediate suppliers face environmental compliance audits. This lead-time exposure concentrates pricing power with vertically integrated API-to-formulation operators who control loratadine and cetirizine synthesis pathways.
Pricing Analysis
Second-generation non-sedating antihistamines command 40-60% premiums over first-generation diphenhydramine and chlorpheniramine commodities in United States pharmacy channels. Three-tier pricing structure across branded prescription, generic prescription, and OTC economy levels segments buyer archetypes by reimbursement access and sedation sensitivity. Price differentiation hinges on FDA bioequivalence certification tier and pediatric formulation complexity. Cost compression in generic OTC tablets is intensifying because FDA monograph reform elevates analytical chemistry documentation burdens for smaller manufacturers. Retail pharmacy chains exhibit highest price sensitivity, while hospital formularies purchasing novel combination therapies show lowest sensitivity due to prior authorization capture.
Supply Chain Analysis
Just-in-time API procurement dominates among European and North American formulators, though strategic stockpiling of cetirizine dihydrochloride intermediates is emerging among contract manufacturers serving pediatric syrup demand surges. Active pharmaceutical ingredient synthesis concentrates in India, China, and Switzerland, with Maharashtra and Gujarat facilities supplying loratadine and cetirizine intermediates to German and United States formulators. Raw material dependencies include piperazine derivatives, chlorobenzene feedstocks, and specialty polymer excipients for controlled-release matrices. Single-source vulnerability from Indian API export concentration creates exposure to CDSCO environmental enforcement actions. Distribution runs through regional pharmaceutical wholesalers, direct hospital contracting, and e-commerce direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antihistamines market sits in early-cycle expansion as pediatric formulation innovation and immunotherapy reimbursement expansion open professional healthcare channels to allergy management products previously confined to self-medication.
For Market Incumbents: Compound formulary placement advantages by securing pediatric investigation plan compliance ahead of EMA deadlines, while acquiring taste-masking chemistry capabilities from Hyderabad contract research organizations to defend against emerging entrant disruption in alcohol-free liquid segments. Backward integration into biodegradable polymer excipient supply buffers REACH compliance costs. For New Entrants and Emerging Players: Lead with nanostructured lipid carrier intranasal delivery platforms targeting Swiss and Dutch allergy clinic protocols, where rapid-onset efficacy commands prescription-grade pricing. Brazil's ANVISA-harmonized OTC registration pathway offers the most penetrable geography for second-generation antihistamine market entry. Deploy direct-to-consumer subscription models bundling diagnostic testing to bypass entrenched wholesale pharmacy networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates spinning consumer health divisions with dense retail pharmacy shelf presence but stagnant R&D pipelines. Long-term viability centers on immunotherapy adjuvant positioning and pediatric formulation patent estates. Acquisition target archetype: mid-cap specialists with EMA-aligned pediatric investigation plans and captive API synthesis in India. The signal to watch is FDA monograph reform implementation pace, as accelerated bioequivalence documentation requirements will consolidate generic manufacturing toward capital-rich operators.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Patent Filing | EMA investigation plan compliance creates regulatory moats against generic substitution in France and Germany. |
| API Synthesis Backward Integration | Captive loratadine intermediate production in Maharashtra buffers REACH compliance cost volatility. |
| E-commerce Direct-to-Consumer Launch | Subscription allergy platforms in Australia and United States bypass traditional pharmacy markup structures. |
| Combination Therapy Pipeline Diversification | Fixed-dose montelukast-cetirizine formulations address refractory cases in Japanese allergy clinics. |
| Biodegradable Excipient Reformulation | EMA environmental risk assessment compliance eliminates persistent metabolite liabilities in aquatic toxicity profiles. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. This study combined primary interviews with industry stakeholders and secondary data triangulation, applying bottom-up patient-volume modeling and top-down reimbursement framework analysis to cross-validate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including treatment line, dosage form, administration route, patient population, and regional regulatory cluster. CAGRs were derived from patient volume trajectories, pricing elasticity assumptions, and penetration rate modeling. Forecast inputs incorporated immunotherapy reimbursement expansion timelines and pediatric formulation innovation investment cycles.
Underlying assumptions cover FDA monograph reform implementation pace, EMA pharmacovigilance harmonization completion, and REACH compliance cost trajectories, with deviation risk concentrated in Indian API export regulatory enforcement and United States commercial payer prior authorization pathway changes. Revision becomes warranted when pediatric investigation plan compliance thresholds cross regulatory deadline boundaries or when environmental assessment mandates expand beyond current API synthesis coverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Hypertensive Emergency Medications Market