
 Acetaminophen Market | 2026-2036
Acetaminophen Market Size, Share, and Industry Trends Forecast 2026-2036
Acetaminophen Market Analysis
The EU Green Deal's pharmaceutical sustainability requirements is expanding the market for green chemistry-derived acetaminophen precursors across European supply chains. Granules India Ltd. anchors the global API supply with backward integration into para-aminophenol manufacturing. Teva Pharmaceutical Industries Ltd. competes through its vertically controlled distribution network across North American retail channels. Mallinckrodt Pharmaceuticals specializes in hospital-grade injectable formulations for perioperative pain management.
Acetaminophen, chemically N-acetyl-para-aminophenol, functions as a centrally acting analgesic and antipyretic with a typical oral bioavailability exceeding 80 percent and hepatic metabolism via glucuronidation. The compound serves as a first-line monotherapy for mild-to-moderate pain and fever reduction across pediatric, adult, and geriatric populations. Tablets dominate volume consumption in mature markets where retail pharmacy chains and supermarket private-label programs drive bulk purchasing. Extended Release formulations capture disproportionate margin pools due to formulation complexity and patent-protected delivery technologies that limit generic competition.
The FDA enforces current Good Manufacturing Practice standards for acetaminophen API facilities, while the EMA's REACH framework governs chemical precursor handling across European production sites. India's CDSCO mandates bioequivalence documentation for domestic generic acetaminophen products entering institutional tenders. The US EPA regulates para-cresol and phenol emissions from API synthesis operations, raising compliance costs for legacy manufacturing assets. Stakeholders must monitor evolving hepatotoxicity labeling requirements and pediatric dosing restrictions as regulators reassess over-the-counter exposure limits.
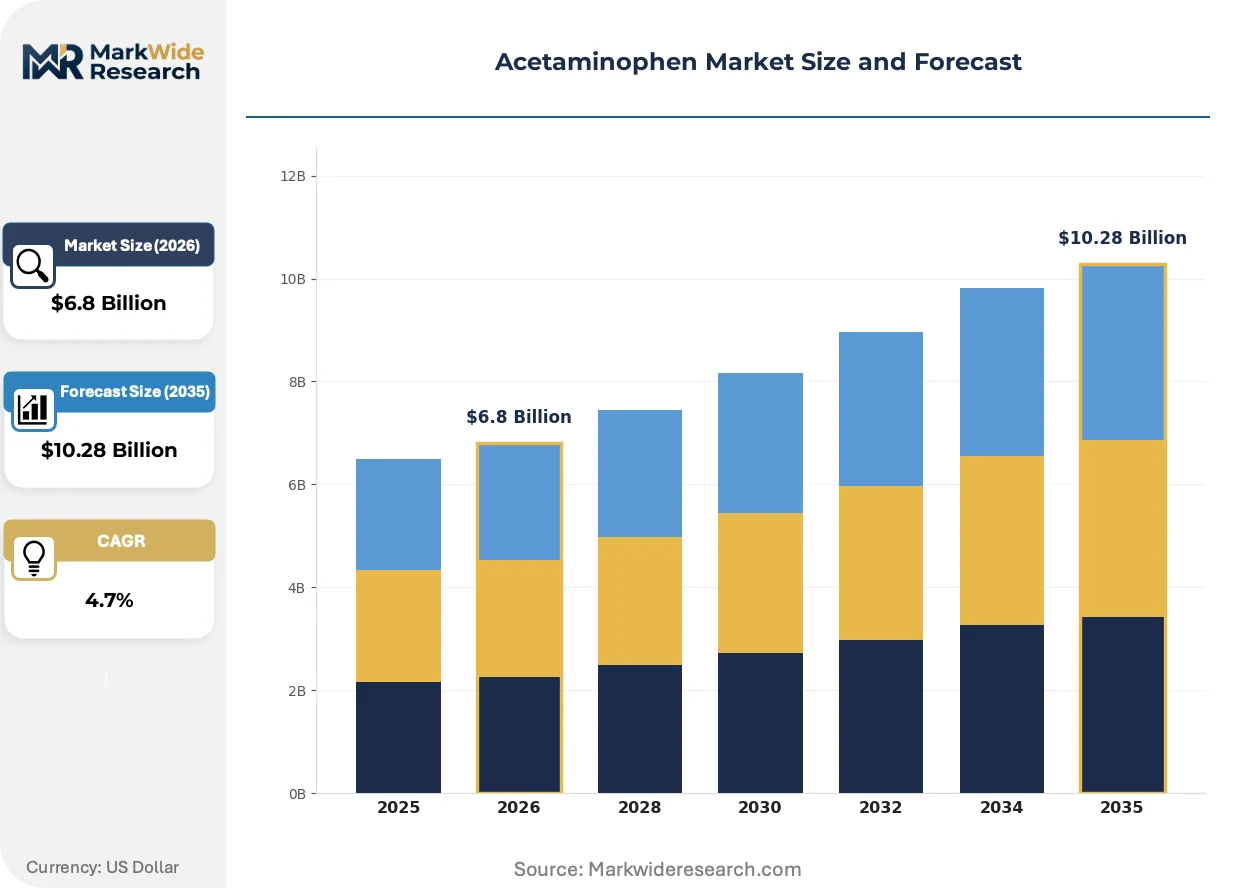
Market Dynamics
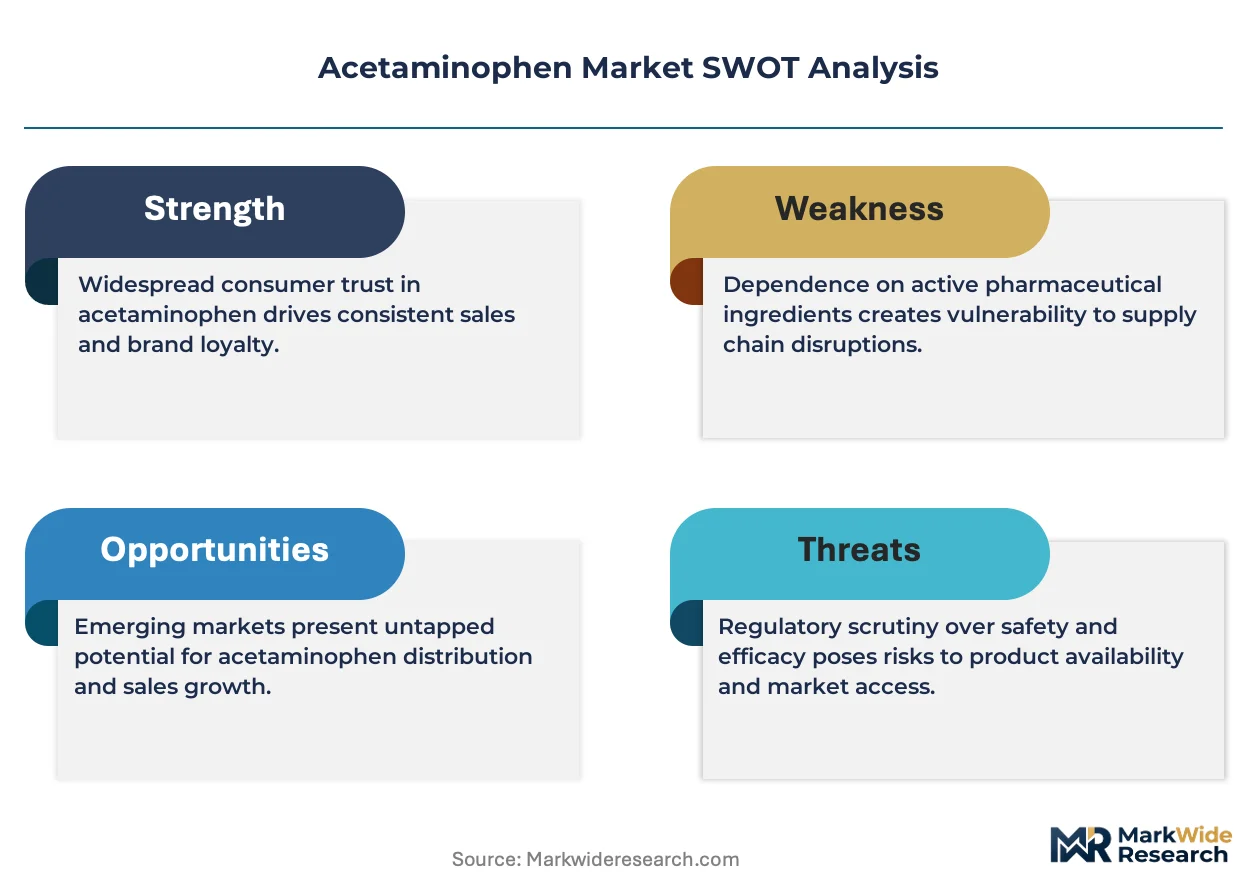
Hospital formulary consolidation and tightened FDA manufacturing standards for active pharmaceutical ingredients are compressing supplier margins while favoring high-volume domestic manufacturers with upgraded purification infrastructure.
Growth Catalysts
- Surgical Volume Recovery:Hospital procurement of intravenous acetaminophen formulations is accelerating across the United States and Western Europe as elective procedure backlogs clear.
- REACH Framework Compliance:The EMA's chemical precursor handling mandates are driving API producers toward green chemistry-derived para-aminophenol manufacturing in European supply chains.
- Generic Substitution Policies:United States Medicaid and Medicare formulary rules favoring therapeutic equivalence are channeling volume toward high-capacity domestic tablet manufacturers.
Market Restraints
- Para-Aminophenol Price Volatility:Feedstock costs for the key acetaminophen precursor fluctuate with phenol and nitrobenzene commodity markets, squeezing API producer margins.
- Indian API Supply Concentration:Backward-integrated manufacturers in Hyderabad and Visakhapatnam control critical para-aminophenol capacity, creating single-source vulnerability for Western formulators.
- Hepatotoxicity Labeling Friction:FDA and EMA reassessments of over-the-counter exposure limits are extending regulatory review timelines for new combination products.
Strategic Opportunities
- Pediatric Dosing Innovation:Liquid suspension and orally disintegrating tablet formats for weight-based administration remain underdeveloped relative to adult solid-dose saturation.
- EU Green Deal Incentives:Pharmaceutical sustainability requirements are creating first-mover advantage for API producers with bio-based para-aminophenol synthesis routes.
- Extended-Release Formulation Patents:Delivery technology protected through layer-coating and matrix systems limits generic competition in the high-margin chronic pain segment.
Industry Challenges
- Multi-Jurisdictional Compliance Talent:Simultaneous FDA cGMP, EMA REACH, and CDSCO bioequivalence documentation requirements strain regulatory affairs staffing at mid-size API exporters.
- Legacy Asset Emissions Retrofit:US EPA para-cresol and phenol emission controls demand capital deployment at aging synthesis facilities without guaranteed offtake price recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetaminophen Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid, Powder End User: Retail Pharmacies, Online Pharmacies, Hospitals, Clinics Formulation: Immediate Release, Extended Release, Effervescent, Suppository Dose: 500 mg, 650 mg, 1000 mg, Others |
| Companies Covered | GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Mallinckrodt Pharmaceuticals, Dr. Reddy’s Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Granules India Ltd., Sanofi, Bayer AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetaminophen Market Emerging Trajectories
Continuous manufacturing and real-time release testing are displacing batch processing in acetaminophen API synthesis, while regulatory pressure on solvent use accelerates green chemistry adoption.
Continuous flow reactor technology is automating para-aminophenol nitration and hydrogenation steps that previously required batch vessel turnaround. Large-scale API producers in India and the United States are retrofitting Hyderabad and Puerto Rico facilities with plug-flow systems that cut residence times from hours to minutes. This compression is automating quality control sampling and reducing in-process inventory holding costs.
The EU Green Deal's pharmaceutical sustainability requirements are mandating solvent recovery rates and bio-based feedstock quotas for European-market API. EMA guidance on mass efficiency metrics is forcing reformulation of traditional acetylation routes that relied on acetic anhydride in pyridine. German and Swiss contract manufacturers are responding with enzymatic transacetylation processes using immobilized lipases.
Hospital procurement consolidation through group purchasing organizations is compressing supplier rosters and unbundling technical service from product pricing. United States health system alliances are replacing individual hospital formulary decisions with centralized therapeutic class reviews. This concentration is most visible in the southeastern United States, where regional GPOs have reduced intravenous acetaminophen vendors from six to two approved suppliers.
Acetaminophen Market Segmentation
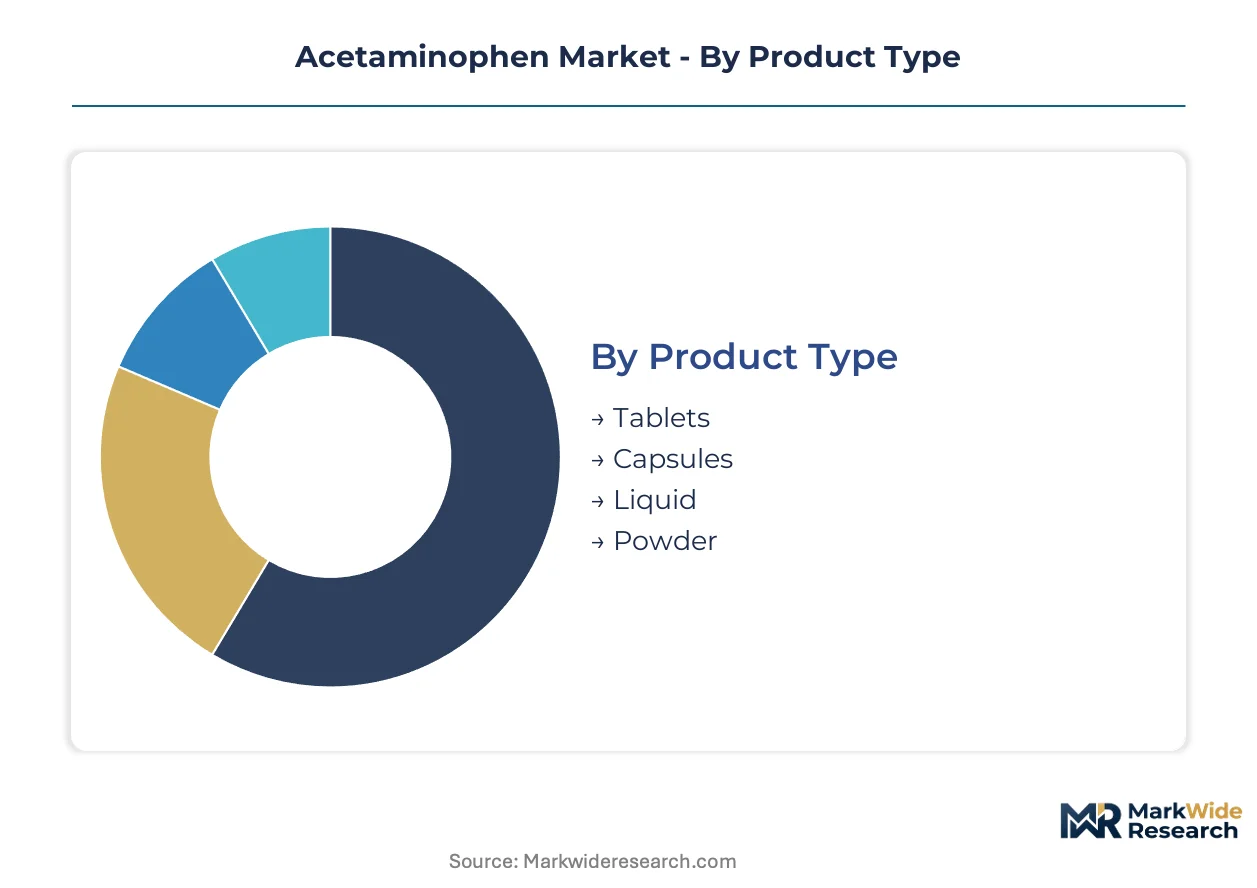
Acetaminophen's segmentation structure reflects divergent margin economics between commoditized oral solids and specialized hospital formats. Product type and formulation choices determine regulatory pathway complexity, manufacturing capital intensity, and distribution channel access.
Product Type:
Tablets command volume leadership while liquids capture pediatric and geriatric premium positioning.
- Tablets:Compressed solid-dose formats dominate procurement volumes across United States retail pharmacy chains and supermarket private-label programs. FDA bioequivalence documentation requirements favor high-capacity domestic manufacturers with continuous manufacturing lines.
- Liquid:Suspension and solution formats address weight-based pediatric dosing and dysphagia populations in long-term care facilities. Hospital formulary consolidation in the southeastern United States is channeling procurement toward three approved suppliers with validated sterile filling capabilities.
- Capsules:Gelatin and HPMC shell formats offer taste masking for combination products with bitter actives. CDSCO bioequivalence mandates for Indian institutional tenders favor locally manufactured hard gelatin variants.
- Powder:Bulk API and finished sachet formats serve compounding pharmacies and over-the-counter reconstitution products. REACH framework precursor handling requirements constrain European manufacturing of direct-to-consumer powder SKUs.
Mature deployment sits with Tablets. Newer deployment is concentrated in Liquid.
End User:
Channel structure separates high-volume retail substitution from specialized hospital injectable procurement.
- Retail Pharmacies:Chain drugstores and independent pharmacies drive generic substitution through Medicaid and Medicare formulary compliance. United States reimbursement rules channel 90-day supply dispensing toward high-volume tablet manufacturers with verified supply continuity.
- Hospitals:Perioperative pain management protocols specify intravenous acetaminophen for enhanced recovery after surgery pathways. Group purchasing organization consolidation has compressed southeastern United States vendor rosters from six to two approved suppliers.
- Online Pharmacies:Direct-to-consumer platforms and mail-order fulfillment serve chronic pain patients with 90-day extended-release prescriptions. FDA DSCSA track-and-trace requirements impose serialization infrastructure costs on e-commerce-focused distributors.
- Clinics:Urgent care and ambulatory surgery centers stock immediate-release formulations for same-day procedure protocols. Indian CDSCO state licensing variations create compliance fragmentation for multi-clinic operators.
Volume leadership resides with Retail Pharmacies. Margin expansion is climbing the fastest in Hospitals.
Formulation:
Release kinetics differentiate commoditized immediate-release from patent-protected extended-delivery platforms.
- Immediate Release:Rapid dissolution tablets and capsules serve acute pain and fever reduction with onset under 30 minutes. United States generic substitution policies channel procurement toward bioequivalent domestic manufacturers with validated dissolution profiles.
- Extended Release:Layer-coated and matrix-controlled delivery systems maintain therapeutic plasma concentrations over 8-hour dosing intervals. Patent-protected technologies limit generic competition in osteoarthritis and chronic back pain segments.
- Effervescent:Rapid-dissolving granule formulations address pediatric compliance and rapid onset requirements in European markets. EMA stability testing mandates for effervescent systems extend regulatory review timelines relative to conventional solids.
- Suppository:Rectal delivery formats serve vomiting patients and preoperative pediatric populations where oral administration is contraindicated. Manufacturing complexity and limited demand constrain supplier participation to specialized contract manufacturers.
Commodity positioning dominates Immediate Release. Value capture is expanding most quickly in Extended Release.
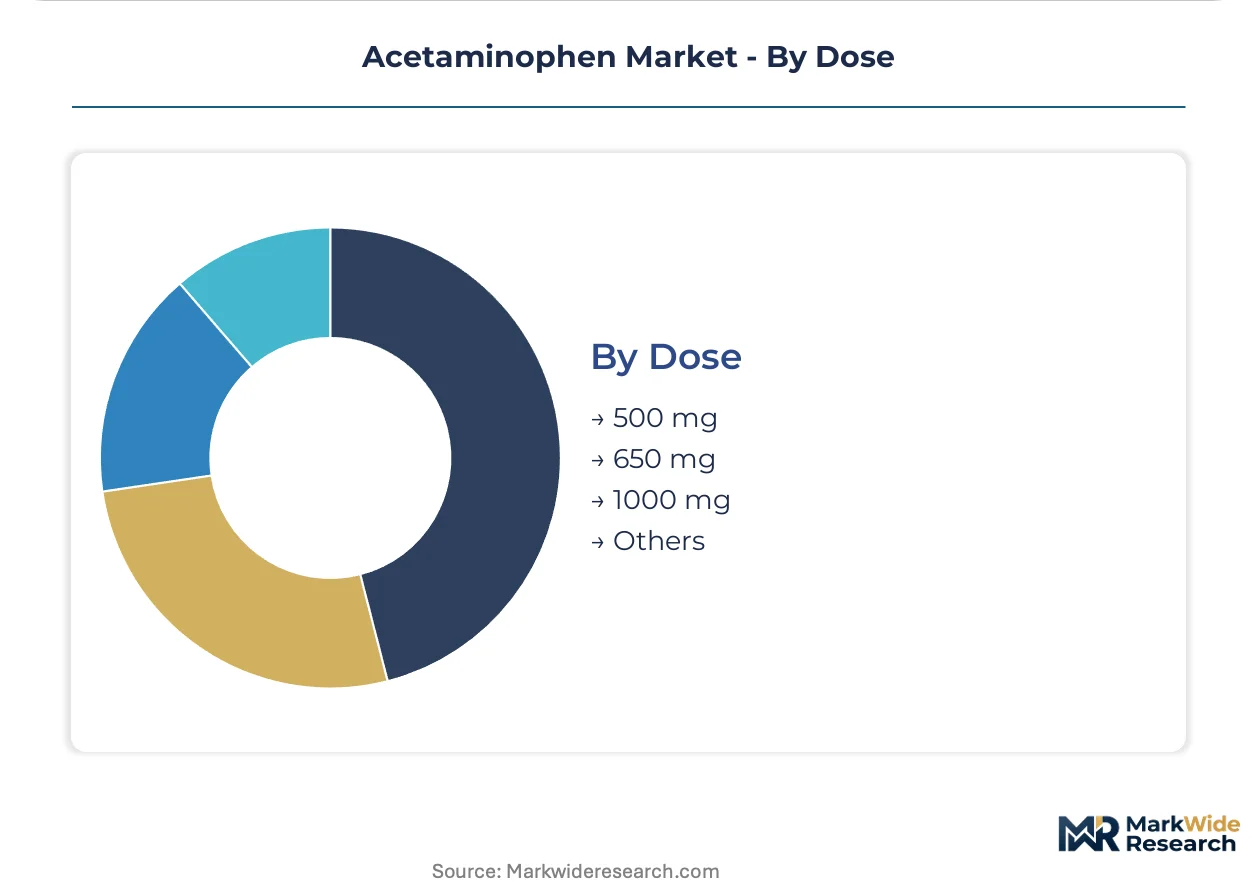
Dose:
Strength tiering aligns with adult standard dosing, prescription escalation, and combination product constraints.
- 500 mg:Standard adult unit dose for over-the-counter monotherapy and combination cold products. FDA hepatotoxicity labeling requirements cap recommended daily intake, constraining single-unit strength escalation.
- 650 mg:Extended-release and arthritis-strength formats deliver sustained plasma concentrations with reduced dosing frequency. United States retail pharmacy chains favor this strength for private-label arthritis positioning.
- 1000 mg:Prescription-grade unit doses serve hospital intravenous formulations and severe pain protocols. DEA scheduling exemptions for acetaminophen enable distribution through standard pharmaceutical wholesale channels.
- Others:Pediatric weight-based strengths and combination opioid-acetaminophen products at 325 mg and 750 mg fill niche therapeutic gaps. CDSCO pediatric dosing restrictions in India limit commercial viability of sub-500 mg standalone products.
Volume concentration sits with 500 mg. Regulatory and clinical momentum is gaining share fastest in 1000 mg.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors global acetaminophen API production, with backward-integrated manufacturers in Telangana supplying para-aminophenol to Western formulators under tightened FDA and EMA standards.
United States
Hospital procurement of intravenous formulations is accelerating as surgical volumes recover across the southeastern states. FDA tightened manufacturing standards for active pharmaceutical ingredients are prompting Puerto Rico-based facilities to upgrade purification capabilities. Continuous manufacturing retrofits in Carolina manufacturing corridors are automating quality control sampling.
Germany
Green chemistry-derived acetaminophen precursors are expanding across European supply chains under EU Green Deal mandates. EMA REACH framework compliance is driving enzymatic transacetylation processes using immobilized lipases at Swiss and German contract manufacturers. Bavarian chemical clusters are responding with solvent recovery rate investments.
India
CDSCO bioequivalence documentation requirements are channeling domestic generic acetaminophen toward institutional tenders in Maharashtra and Gujarat. Backward-integrated manufacturers in Visakhapatnam control critical para-aminophenol capacity, creating supply concentration for Western formulators. Telangana-based API exporters are retrofitting facilities with plug-flow reactor systems.
Switzerland
Swissmedic oversight of hospital-grade formulations is reinforcing quality positioning for perioperative pain management products. Contract manufacturers in Basel and Zurich are adopting mass efficiency metrics under EMA guidance on pharmaceutical sustainability. Alpine chemical corridors are specializing in high-purity API for European hospital procurement.
United Kingdom
NHS formulary consolidation is compressing supplier rosters for generic acetaminophen tablets across England and Scotland. MHRA alignment with EMA REACH precursor handling requirements is constraining legacy manufacturing assets without emission control retrofits. Midlands-based distributors are centralizing procurement for retail pharmacy chains.
Acetaminophen Market Vendor Landscape
The competitive structure tilts toward high-volume API manufacturers with backward integration into para-aminophenol production. Supplier margins are compressing under hospital formulary consolidation and multi-jurisdictional compliance requirements. Three archetypes dominate: backward-integrated Indian API specialists, vertically controlled North American distributors, and European green chemistry innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure offtake agreements under tightened FDA standards.
Among Indian API specialists, Granules India Ltd. and Dr. Reddy's Laboratories Ltd. exemplify the backward-integrated archetype with captive para-aminophenol supply. Teva Pharmaceutical Industries Ltd. occupies a position representing vertically controlled distribution across North American retail channels. These three anchors illustrate how geographic specialization and supply chain configuration determine competitive positioning under divergent regulatory pressures.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Mallinckrodt Pharmaceuticals |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Granules India Ltd. |
| Sanofi |
| Bayer AG |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Phenol commodity index movements cascade directly into acetaminophen API pricing tiers, with feedstock volatility compressing margins at non-integrated formulators while backward-integrated manufacturers in Telangana capture cost pass-through advantages across hospital procurement contracts.
Pricing Analysis
Hospital formulary consolidation anchors value-based pricing around surgical throughput outcomes and supply continuity guarantees rather than unit cost alone. Three-tier pricing structure across patented extended-release, bioequivalent immediate-release, and private-label economy tablets separates margin pools by formulation complexity and regulatory certification tier. Cost compression in commodity oral solids is intensifying because Medicaid generic substitution policies channel volume toward high-capacity domestic manufacturers with validated dissolution profiles. Retail pharmacy chains exhibit highest price sensitivity through 90-day supply tendering, while hospital GPOs prioritize supply security over per-unit cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for pharmaceutical manufacturing are reshaping sourcing patterns for Western formulators seeking to diversify beyond Hyderabad and Visakhapatnam API clusters. Supply concentrates in India, the United States, and Germany, with para-aminophenol production drawing from phenol and nitrobenzene feedstocks anchored in commodity chemical markets. Single-source vulnerability pervades the para-aminophenol intermediate tier where Telangana-based backward-integrated producers control critical capacity. Distribution runs through pharmaceutical wholesale channels with hospital GPO consolidation compressing vendor rosters in the southeastern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetaminophen API supply is structurally constrained by para-aminophenol capacity concentration in Telangana, propping pricing power for integrated manufacturers while stranding non-integrated formulators in margin compression.
For Market Incumbents: Anchor market position through captive para-aminophenol capacity expansion and continuous manufacturing retrofits that automate quality control sampling. Hospital formulary consolidation threatens supplier roster exclusion; defend through long-term offtake agreements with southeastern United States GPOs. Certification investment in EMA REACH-compliant green chemistry routes secures European procurement preference under EU Green Deal mandates. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the most penetrable route around entrenched wholesale distribution. Target pediatric liquid suspension formats where weight-based dosing innovation remains underdeveloped relative to adult solid-dose saturation. White-space exists in bio-based para-aminophenol synthesis for European sustainability-compliant supply chains. For Investors and Strategic Acquirers: The window for entry favors backward-integrated API specialists with proven FDA cGMP compliance and hospital-grade sterile filling capabilities. Long-term viability hinges on regulatory moats tightening under multi-jurisdictional documentation requirements that strain mid-size exporter staffing. Watch for FDA warning letter issuance rates as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Para-Aminophenol | Captive precursor supply insulates margin from phenol commodity volatility and secures hospital procurement continuity. |
| Continuous Manufacturing Retrofit | Plug-flow reactor automation at Hyderabad and Puerto Rico facilities compresses residence times and reduces in-process inventory costs. |
| Green Chemistry Route Development | Enzymatic transacetylation using immobilized lipases satisfies EMA mass efficiency metrics under EU Green Deal pharmaceutical sustainability requirements. |
| Hospital GPO Consolidation Partnership | Long-term offtake agreements with southeastern United States group purchasing organizations defend vendor roster position against supplier compression. |
| Pediatric Formulation Innovation | Liquid suspension and orally disintegrating tablet development addresses weight-based dosing gaps in hospital perioperative protocols. |
Methodological Framework
Independent corroboration across FDA inspection databases, EMA REACH compliance filings, and Indian CDSCO institutional tender records underwrites the qualitative findings on supplier concentration and regulatory burden distribution. Primary interviews with API plant managers, hospital formulary directors, pharmaceutical procurement leads at group purchasing organizations, and regulatory affairs specialists at multi-jurisdictional exporters combined with secondary validation from customs trade data, SEC 10-K pharmaceutical segment disclosures, and hospital procurement database extracts. Bottom-up capacity modeling and top-down therapeutic class demand estimation triangulate volume and value outputs.
Rate-of-change decomposition across the analysis window separates volume growth from price/mix effects and regulatory cost pass-through. Segmentation dimensions modeled include product type, end-user channel, formulation release kinetics, dose strength tier, and regional regulatory cluster. CAGRs derive from trend extrapolation of surgical volume recovery, generic substitution policy enforcement, and green chemistry adoption curves calibrated against historical API pricing elasticity to phenol feedstock movements.
The model holds under sustained FDA cGMP enforcement and EMA REACH precursor handling compliance; deviation in Indian export policy restrictions or para-aminophenol feedstock supply disruption would shift capacity utilization and pricing power assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market