
 Glycerol Fructose and Sodium Chloride Injection Market | 2026-2036
Glycerol Fructose and Sodium Chloride Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Glycerol Fructose and Sodium Chloride Injection Market Insights
The capital-intensity divergence between sterile manufacturing specialists and commodity formulators is collapsing as multi-chamber bag technology and aseptic filling standards become baseline requirements. B. Braun Melsungen AG leverages its vertically integrated sterile infrastructure to dominate European hospital contracts. Kelun Group anchors volume production across Asia through backward integration into active pharmaceutical ingredient synthesis. Fresenius Kabi AG differentiates via clinical nutrition bundling that embeds glycerol-fructose combinations within broader metabolic therapy portfolios.
Glycerol Fructose and Sodium Chloride Injection constitutes a parenteral solution combining osmotic diuretic glycerol with fructose and sodium chloride in isotonic or hypertonic formulations, typically manufactured via WFI-based compounding followed by terminal sterilization or aseptic processing for heat-labile components. The formulation primarily reduces intracranial pressure in acute neurological settings while providing caloric substrate and electrolyte repletion. Combination Injection commands premium positioning due to clinical convenience and reduced pharmacy compounding error risk, whereas Electrolyte Replacement applications within the Application dimension represent the mature revenue base now yielding to Nutritional Supplement growth in perioperative protocols. Intravenous delivery mode occupies the dominant share, though Intraosseous administration is gaining traction in emergency and military medicine where vascular access fails.
FDA enforces cGMP and sterility assurance levels for parenteral products that shape facility investment thresholds, while China's NMPA and EMA's GMP Annex 1 revisions on sterile medicinal products collectively elevate barrier technology and isolator requirements across manufacturing footprints. These regulatory frameworks compress the viable producer base to firms capable of sustained compliance capital deployment. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs for glycerol and fructose specifications, as divergence here would fragment formulation strategies and complicate multi-regional supply architectures.
Market Dynamics
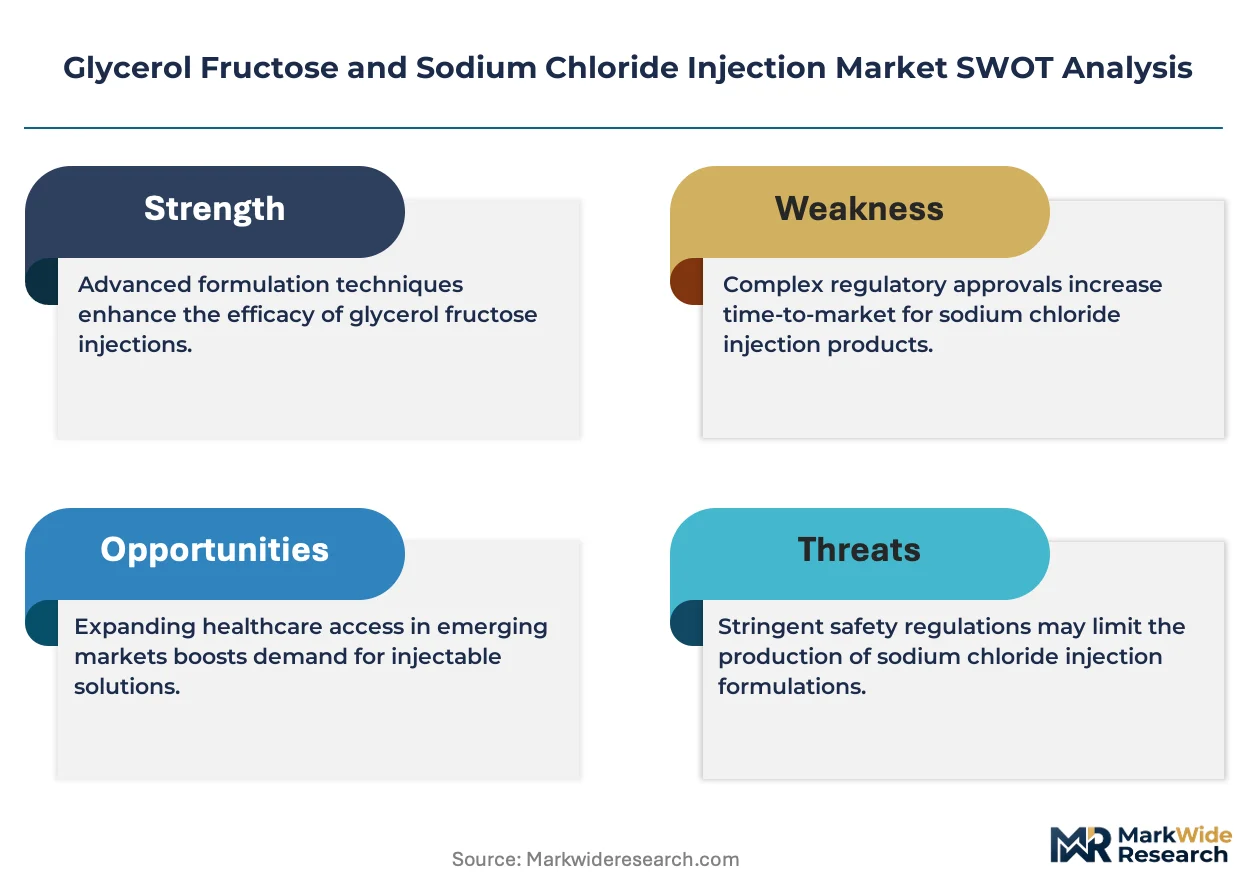
Hospital procurement consolidation and NMPA sterility protocol tightening are compressing the viable supplier base to manufacturers with isolator-equipped aseptic lines and sustained compliance capital deployment capabilities.
Growth Catalysts
- Neurological emergency protocols:Rising intracranial pressure management in trauma centers drives combination injection preference over pharmacy-compounded alternatives.
- EMA GMP Annex 1 revision:Barrier technology mandates elevate entry barriers, protecting incumbent sterile specialists with validated isolator infrastructure.
- Perioperative metabolic support:Surgical volume recovery in tertiary hospitals expands nutritional supplement applications beyond traditional electrolyte replacement.
Market Restraints
- API supply concentration:Fructose and glycerol active pharmaceutical ingredient production clusters in China, creating single-source vulnerability for non-integrated formulators.
- Terminal sterilization limitations:Heat-labile fructose degradation constrains sterilization modality options, forcing costlier aseptic processing for premium formulations.
- Compounding pharmacy substitution:Hospital 503B facilities with in-house sterile compounding capabilities threaten packaged combination injection volume in cost-sensitive accounts.
Strategic Opportunities
- Emergency medicine intraosseous delivery:Military and field hospital protocols create new administration modality demand beyond traditional intravenous lines.
- India hospital infrastructure expansion:CDSCO regulatory alignment with ICH standards opens pathway for multi-chamber bag technology introduction in tertiary care construction.
- Clinical nutrition bundling:Metabolic therapy portfolio embedding enables glycerol-fructose positioning within broader parenteral nutrition procurement contracts.
Industry Challenges
- Aseptic processing workforce scarcity:Qualified personnel for isolator operation and media fill validation represent critical bottlenecks in capacity expansion timelines.
- Multi-regional pharmacopeial divergence:USP, EP, and ChP monograph specification gaps complicate unified formulation strategies for cross-border supply architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycerol Fructose and Sodium Chloride Injection Market |
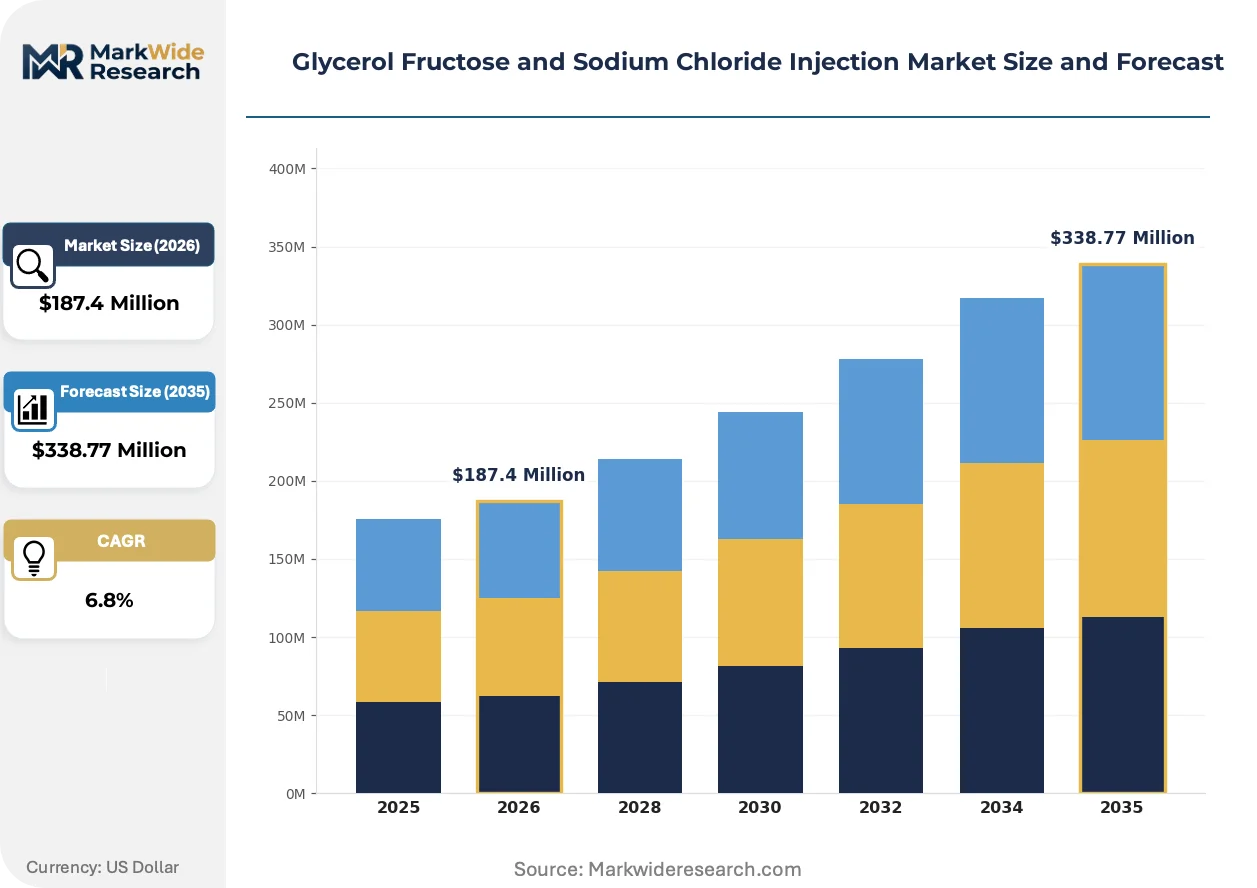
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycerol Injection, Fructose Injection, Sodium Chloride Injection, Combination Injection Application: Electrolyte Replacement, Nutritional Supplement, Hydration Therapy, Pharmaceutical Use End User: Hospitals, Clinics, Home Care, Emergency Services Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intraosseous |
| Companies Covered | B. Braun Melsungen AG, CR Double Crane, Shandong Qidu Pharmaceutical Co., Ltd., Kelun Group, SSY Group, Baxter International Inc., ICU Medical, Inc., Cisen Pharmaceutical, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycerol Fructose and Sodium Chloride Injection Market Trends and Innovations
Multi-chamber bag technology and isolator-based aseptic processing are redrawing competitive boundaries between sterile specialists and commodity injectable formulators.
Closed-system transfer devices for hazardous drug compounding are bifurcating manufacturing investment profiles. European hospital systems with centralized pharmacy automation are adopting these technologies at accelerated pace. The capability gap is compressing margin structures for open-system formulators without barrier technology validation.
China's NMPA sterility and pyrogen testing protocol tightening is elevating facility qualification requirements. Domestic manufacturers face capital-intensive retrofitting demands for existing WFI-based compounding lines. German hospital procurement contracts now specify isolator-processed sourcing preferences, creating regulatory arbitrage pressure on non-compliant exporters.
Hospital pharmacy consolidation into centralized distribution models is altering purchasing authority structures. Integrated delivery networks with formulary control are displacing individual hospital procurement autonomy. The United States exhibits the most visible concentration, with IDN-level metabolic therapy bundling reshaping vendor relationship dynamics.
Glycerol Fructose and Sodium Chloride Injection Market Segmentation
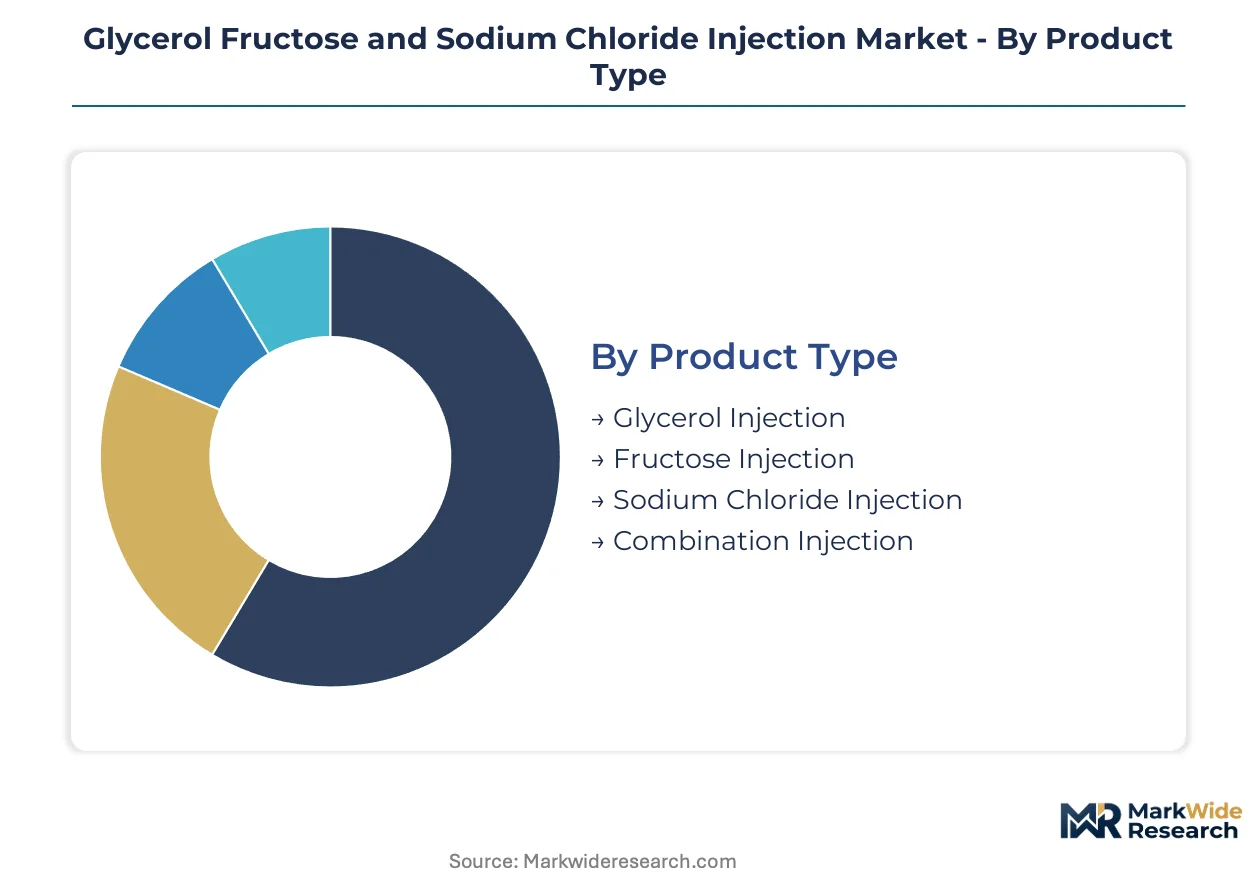
Segmentation in the Glycerol Fructose and Sodium Chloride Injection Market reveals distinct procurement patterns across clinical settings. Hospital formulary decisions and emergency medicine protocols drive divergence between premium combination products and commodity single-component alternatives.
Product Type:
Domestic production clusters around single-component formulations in China and India, while combination injections flow through European and North American import channels. Export-led segments concentrate in German and Swiss sterile manufacturing facilities.
- Combination Injection:Glycerol-fructose-NaCl co-formulation in isotonic or hypertonic ratios enables single-bag intracranial pressure management with caloric support. Tertiary hospital trauma centers in Germany and the United States specify this format for neurological emergency protocols, reducing pharmacy compounding error risk.
- Glycerol Injection:Osmotic diuretic monotherapy for acute intracranial hypertension, manufactured via WFI-based compounding with terminal sterilization constraints. Demand concentrates in Japanese and South Korean neurosurgical units where standalone osmotherapy protocols persist.
- Fructose Injection:Parenteral carbohydrate substrate for hepatic glycogen replenishment, heat-labile characteristics necessitating aseptic processing. Chinese domestic manufacturers anchor volume production for hospital nutrition departments.
- Sodium Chloride Injection:Electrolyte replacement staple with commoditized pricing, produced at massive scale across Indian and Chinese injectable facilities for cost-sensitive institutional procurement.
Combination Injection holds the largest share; momentum sits with Glycerol Injection as neurocritical care specialization expands.
Application:
Cost tier stratification separates premium perioperative metabolic bundles from basic electrolyte correction. Reimbursement coding differences between neurological and nutritional indications reshape margin structures.
- Nutritional Supplement:Perioperative caloric and electrolyte provision in surgical recovery protocols, embedded within broader parenteral nutrition procurement contracts. Tertiary hospital systems in the United States and Germany drive specification as surgical volume recovers.
- Electrolyte Replacement:Mature revenue base for sodium and volume repletion in dehydration and hypovolemia, dominated by high-volume contract manufacturing for hospital group purchasing organizations.
- Hydration Therapy:Fluid resuscitation adjunct in emergency departments and military field medicine, with intraosseous administration gaining protocol adoption where vascular access fails.
- Pharmaceutical Use:Active pharmaceutical ingredient diluent and drug delivery vehicle, specifications governed by pharmacopeial monograph compliance for injectable-grade excipients.
Electrolyte Replacement commands installed base volume; Nutritional Supplement climbs the fastest as metabolic therapy bundling penetrates surgical suites.
End User:
Customer type determines packaging format and sterility assurance requirements. Centralized pharmacy automation in integrated delivery networks displaces individual hospital procurement autonomy.
- Hospitals:Dominant procurement authority through formulary committees and metabolic therapy bundling, with German and Chinese tertiary systems specifying isolator-processed sourcing.
- Emergency Services:Pre-hospital and military protocols driving multi-chamber bag and intraosseous delivery innovation, field stability requirements shaping formulation stability specifications.
- Clinics:Outpatient infusion centers with lower sterility infrastructure investment, cost-sensitive substitution toward pharmacy-compounded alternatives.
- Home Care:Parenteral nutrition patients requiring stable, pre-mixed formulations with extended beyond-use dating, regulatory constraints limiting market penetration.
Hospitals retain procurement dominance; Emergency Services represent the steepest expansion trajectory as battlefield and disaster medicine protocols proliferate.
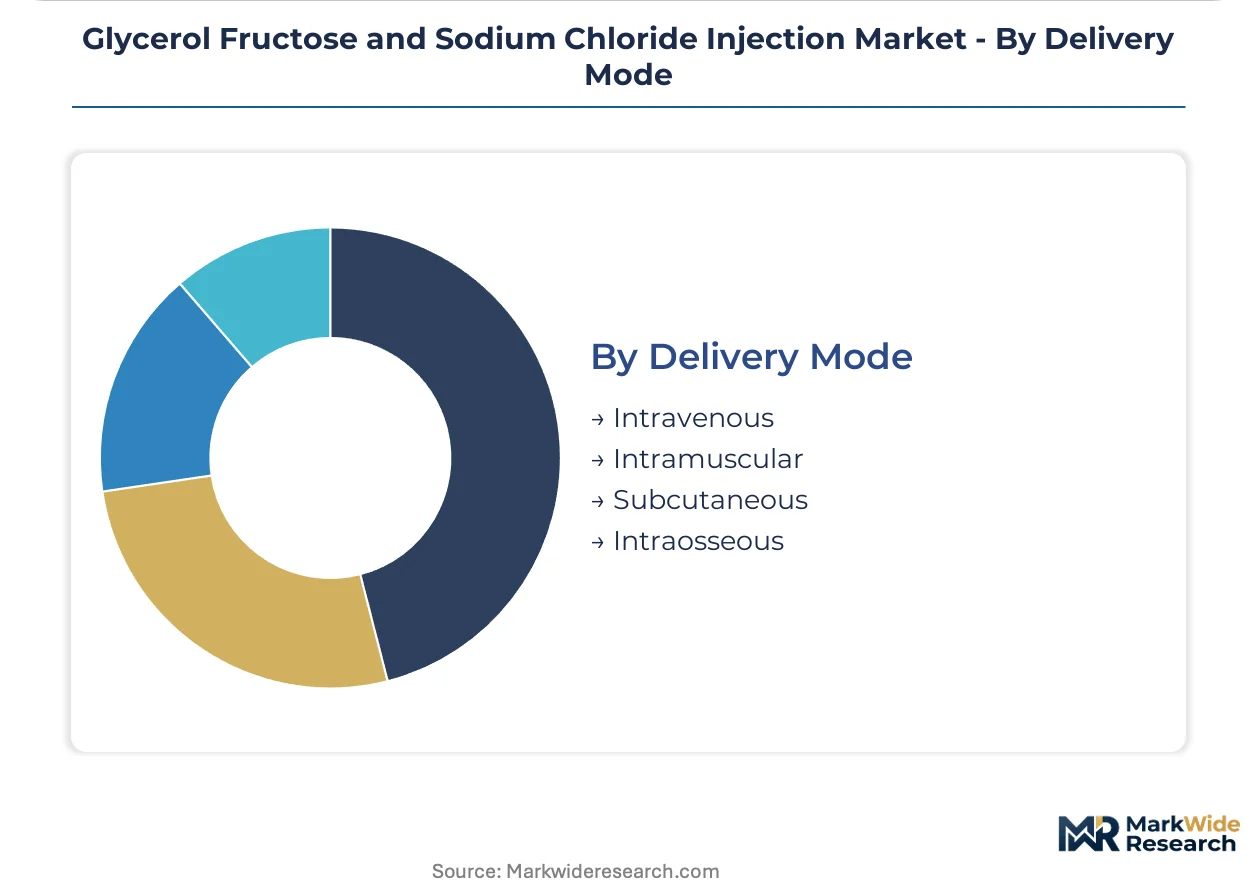
Delivery Mode:
Volume concentration in intravenous administration masks technology transition toward alternative access routes. Administration modality selection directly impacts formulation osmolarity and packaging specifications.
- Intravenous:Standard vascular access for combination injections, peripheral and central line compatibility requirements governing osmolarity limits and filtration specifications.
- Intraosseous:Emergency vascular access alternative in trauma and pediatric resuscitation, military medical services in the United States and NATO allies driving protocol standardization.
- Intramuscular:Limited applicability for hypertonic formulations, restricted to specific electrolyte replacement scenarios in resource-constrained settings.
- Subcutaneous:Hydration therapy in palliative and geriatric care, hypotonic formulation requirements constraining glycerol-fructose concentration ranges.
Intravenous delivery anchors volume; Intraosseous administration gains share fastest as emergency medicine protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in sterile parenteral solutions reveal a bifurcated trade pattern: combination injections flow predominantly from European and North American manufacturing bases toward Asian hospital systems, while API-grade glycerol and fructose concentrate in Chinese chemical production clusters serving formulators worldwide.
United States
Trauma center expansion and military medical modernization drive demand for multi-chamber bag formulations. FDA cGMP enforcement and sterility assurance requirements elevate barrier technology investment thresholds. Boston and Baltimore hospital procurement networks specify isolator-processed sourcing for neurological emergency protocols.
Germany
Tertiary hospital consolidation and metabolic therapy bundling reshape vendor contracting authority. EMA GMP Annex 1 revisions mandate isolator infrastructure, compressing the viable supplier base. Melsungen and Frankfurt-Rhine-Main industrial clusters anchor sterile manufacturing capacity for European export markets.
China
Domestic hospital infrastructure expansion and neurocritical care specialization fuel combination injection volume. NMPA sterility and pyrogen testing protocol tightening forces capital-intensive retrofitting of WFI-based compounding lines. Sichuan-Chongqing and Yangtze River Delta manufacturing bases concentrate API synthesis and aseptic filling capacity.
Japan
Neurosurgical unit specialization preserves demand for standalone glycerol osmotherapy protocols. PMDA quality standards and pharmacopeial alignment with ICH guidelines shape formulation specifications. Osaka-Kobe and Tokyo-Yokohama medical device clusters integrate parenteral solution production with surgical supply chains.
India
Tertiary care construction and emergency medicine protocol standardization create new demand vectors. CDSCO regulatory alignment with ICH standards opens pathways for advanced packaging technology introduction. Maharashtra and Gujarat pharmaceutical corridors scale injectable capacity for domestic hospital procurement and regional export.
Glycerol Fructose and Sodium Chloride Injection Market Competitive Landscape
Concentration sits with sterile manufacturing specialists possessing validated isolator infrastructure and sustained compliance capital deployment capabilities. The viable producer base compresses as multi-chamber bag technology and aseptic filling standards become baseline requirements rather than differentiators. Three archetypes dominate: vertically integrated API-to-formulation operators, clinical nutrition bundlers embedding metabolic therapy portfolios, and sterile infrastructure specialists leveraging hospital contract consolidation. Competitive moves center on M&A to secure barrier technology capabilities and capacity expansion in isolator-equipped aseptic lines.
Among European sterile infrastructure specialists, B. Braun Melsungen AG exemplifies the vertically integrated archetype with captive manufacturing footprints. Kelun Group represents the API-to-formulation integrated model anchored in Chinese chemical production clusters. Fresenius Kabi AG occupies a position within the clinical nutrition bundling tier, embedding glycerol-fructose combinations within broader parenteral therapy procurement contracts. These three entities illustrate the strategic positioning required to serve hospital systems demanding sterility assurance and metabolic therapy integration.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| CR Double Crane |
| Shandong Qidu Pharmaceutical Co., Ltd. |
| Kelun Group |
| SSY Group |
| Baxter International Inc. |
| ICU Medical, Inc. |
| Cisen Pharmaceutical |
| Fresenius Kabi AG |
| Others |
Pricing and Supply Chain Analysis
Fructose substitution for dextrose in parenteral formulations simultaneously redraws API sourcing maps toward Chinese chemical clusters and compresses margin structures for European formulators lacking backward integration into carbohydrate synthesis.
Pricing Analysis
Hospital procurement groups anchor contract-based long-term offtake structures across the Glycerol Fructose and Sodium Chloride Injection Market. Three-tier pricing structure across premium, standard, and economy levels separates isolator-processed combination injections from terminal-sterilized monotherapies and commodity electrolyte replacements. Cost compression in the economy tier intensifies because 503B compounding pharmacies threaten packaged product volume. Emergency services and military medical buyers exhibit lowest price sensitivity due to protocol rigidity and field stability requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for API shipments from Sichuan-Chongqing manufacturing bases. Supply concentrates in China for fructose and glycerol active pharmaceutical ingredients, Germany for sterile finished formulation, and India for commodity electrolyte injection. Raw material dependencies center on corn-derived fructose, palm oil-derived glycerol, and rock salt sodium chloride. Single-source vulnerability in Chinese API production clusters threatens non-integrated formulators. Distribution runs through hospital group purchasing organizations and integrated delivery network centralized pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Glycerol Fructose and Sodium Chloride Injection Market sits in surgical volume recovery phase, with perioperative metabolic support protocols driving cyclical demand normalization across tertiary hospital systems.
For Market Incumbents: Compound isolator infrastructure advantages through capacity expansion in German and Chinese manufacturing clusters before NMPA sterility mandates fully compress the viable supplier base. Secure captive fructose supply through backward integration into carbohydrate synthesis or long-term API offtake agreements with Yangtze River Delta producers. EMA GMP Annex 1 barrier technology requirements protect incumbents with validated infrastructure against commodity formulators lacking compliance capital deployment capabilities. For New Entrants and Emerging Players: Differentiate on intraosseous delivery format specialization for military and disaster medicine protocols where vascular access failure creates unmet need. Target emergency services procurement channels in NATO-aligned defense medical systems and Indian tertiary care construction projects. Penetrate through CDSCO regulatory alignment partnerships with established sterile manufacturers lacking emergency medicine market access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors sterile infrastructure specialists with validated isolator capabilities and sustained compliance capital deployment track records. Long-term viability across the analysis window hinges on regulatory arbitrage capture as multi-regional pharmacopeial divergence fragments formulation strategies. Acquisition target archetype: mid-cap API-to-formulation integrators with NMPA-certified Chinese manufacturing footprints. Signal to watch: NMPA sterility protocol enforcement timelines and hospital procurement contract specification shifts toward isolator-processed sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Infrastructure Investment | EMA GMP Annex 1 compliance protects market position against non-validated competitors in German hospital procurement. |
| API Backward Integration | Captive fructose synthesis in Sichuan-Chongqing clusters insulates margin structures from Chinese export price volatility. |
| Multi-Chamber Bag Technology | Closed-system transfer devices meet Boston and Baltimore trauma center specifications for neurological emergency protocols. |
| Clinical Nutrition Bundling | Metabolic therapy portfolio embedding secures formulary placement within United States integrated delivery network contracts. |
| Emergency Medicine Partnership | Military medical service agreements establish intraosseous delivery protocol standardization across NATO field hospital systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital pharmacy directors, sterile manufacturing plant managers, regulatory affairs leads at parenteral solution formulators, and emergency medicine procurement officers at defense medical services. Secondary validation drew from FDA cGMP inspection databases, EMA GMP Annex 1 revision documents, NMPA sterility protocol circulars, hospital group purchasing organization contract filings, and USP-EP-ChP pharmacopeial monograph comparison tables. Bottom-up volume estimates from facility-level production capacity and top-down demand triangulation from hospital admission and surgical procedure databases were reconciled.
Across the analysis window, the analytical framework modeled segmentation dimensions including product type hierarchy, application indication clustering, end-user procurement authority structures, and delivery mode technology tiers. CAGRs were derived from trend extrapolation of surgical volume recovery patterns, neurocritical care specialization rates, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs incorporated NMPA facility retrofitting timelines and German hospital consolidation trajectories.
Material uncertainties — NMPA enforcement intensity variations, pharmacopeial monograph divergence acceleration, and 503B compounding pharmacy regulatory scope expansions — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained hospital procurement consolidation and sterility assurance level maintenance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Atorvastatin API Market