
 Europe Automotive Adhesives and Sealants Market | 2026-2036
Europe Automotive Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Adhesives and Sealants Market Foresight
Direct supply relationships between adhesive formulators and vehicle assemblers is tilting toward collaborative development contracts rather than spot procurement. Henkel AG & Co. KGaA leverages its European manufacturing footprint to sustain just-in-time deliveries to German OEM paint shops. Sika AG anchors its position through specialized structural bonding systems for aluminum-intensive vehicle architectures. 3M competes via technology leadership in acrylic pressure-sensitive tapes for interior trim fixation.
Automotive adhesives and sealants comprise formulated polymer systems engineered to bond, seal, or dampen across dissimilar substrates under thermal cycling, vibration, and fluid exposure; typical specifications include shear strengths exceeding 15 MPa for structural epoxies and service temperatures from minus 40°C to 150°C for underhood silicones. Their primary industrial purpose is to enable lightweight vehicle construction, acoustic management, and corrosion protection while reducing mechanical fastener count. Polyurethane dominates exterior seam sealing and direct glazing applications where elasticity and paintability command premium positioning. Water-based technology leads interior assembly due to volatile organic compound restrictions, while UV-curable systems represent the fastest-expanding segment for electronics integration and sensor encapsulation as cure speed becomes critical.
REACH registration requirements and the EU F-Gas Regulation constrain solvent-based formulation chemistries, pushing investments toward compliant water-borne and reactive hot melt platforms. ECHA substance evaluation protocols are elevating testing burdens for imported raw materials, reshaping supplier qualification timelines across the continent. OEMs and tier-1 suppliers must monitor evolving CLH hazard classifications that could restrict existing adhesive chemistries and trigger reformulation cycles.
Market Dynamics
Electric vehicle battery pack assembly is displacing mechanical fasteners with bonded joints across European OEM engineering centers, forcing adhesive formulators to requalify products for thermal runaway containment and crashworthiness standards.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding fleet CO2 targets are accelerating aluminum-intensive vehicle architectures that require structural adhesives for dissimilar metal joining in German and French assembly plants.
- Polyurethane direct glazing penetration:Windshield bonding specifications now demand elastic, paintable seam sealants that accommodate thermal expansion coefficients across panoramic roof modules.
- Spain and Eastern Europe battery gigafactory clustering:New cell manufacturing capacity in these regions is creating localized demand for thermal interface materials and pack assembly adhesives.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with naphtha and propylene pricing, compressing margin visibility for polyurethane formulators serving exterior applications.
- ECHA substance evaluation timelines:REACH registration dossier updates for imported raw materials now extend supplier qualification cycles by 12-18 months, freezing formulation pipelines.
- Mechanical fastening residual preference:Repair shop networks and insurance assessors retain skepticism toward bonded joints, limiting aftermarket adhesive penetration for collision repair.
Strategic Opportunities
- Poland and Czech Republic tier-1 supplier densification:Underpenetrated adhesive specification influence in these manufacturing corridors offers first-mover positioning with emerging EV platform suppliers.
- UV-curable electronics encapsulation:Sensor module miniaturization and ADAS integration are creating cure-speed-critical applications where radiation-cured systems outpace thermal cure alternatives.
- CSRD supply chain disclosure requirements:Mandatory sustainability reporting is rewarding formulators with verified bio-based content and carbon footprint transparency in OEM sourcing scorecards.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in reactive hot melt and water-borne platform development is concentrating among aging technical workforces in Germany and Belgium.
- CLH hazard classification uncertainty:Pending ECHA harmonized classifications for isocyanates and specific epoxy hardeners threaten sudden reformulation mandates without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Adhesives and Sealants Market |
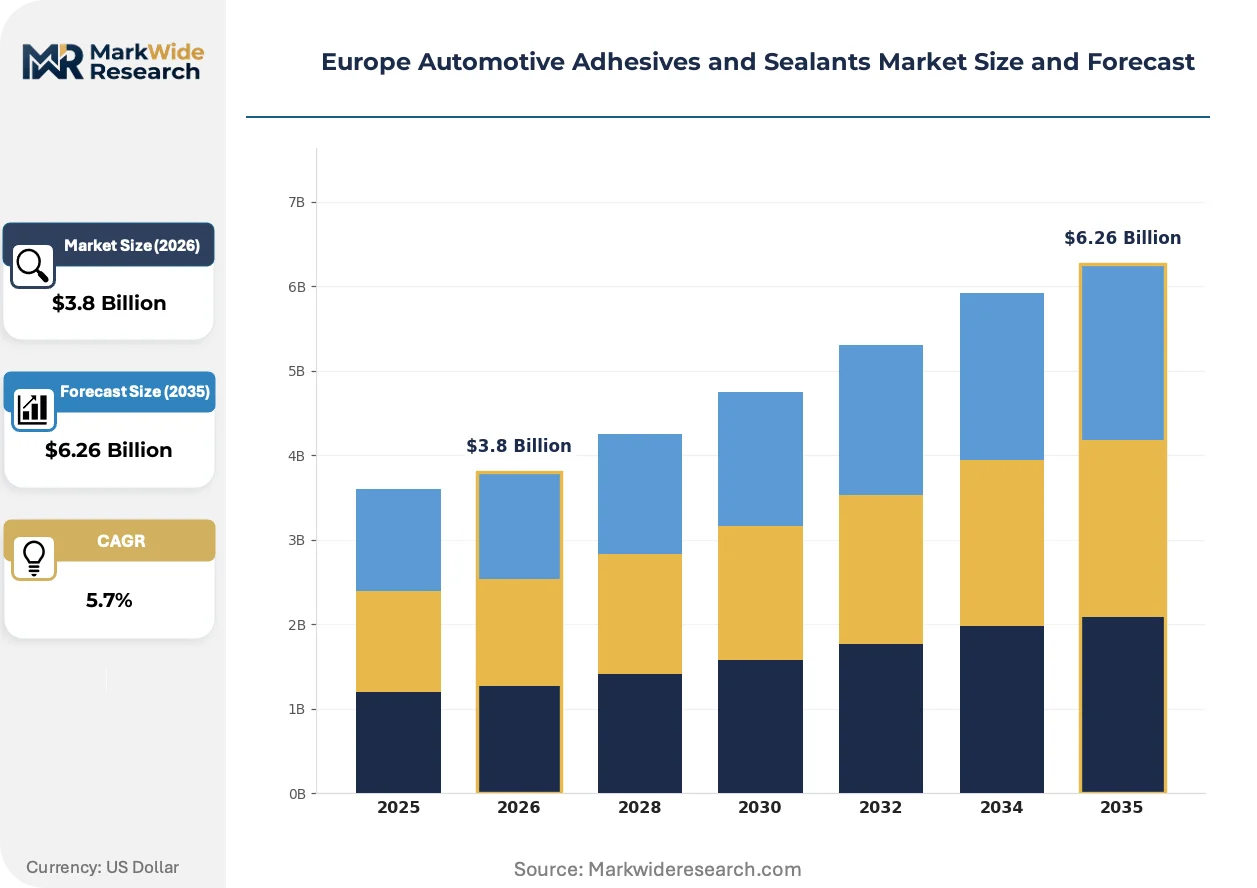
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Interior, Exterior, Structural, Assembly End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Technology: Solvent-Based, Water-Based, Hot Melt, UV-Curable |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Sika AG, H.B. Fuller Company, Huntsman International LLC, Dow, Arkema Group, Illinois Tool Works Inc, DELO Industrie Klebstoffe GmbH & Co KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Adhesives and Sealants Market Shifts & Advancements
Adhesive platforms are converging with automated dispensing robotics and in-line quality sensing, compressing the traditional boundary between material supply and assembly process control in European vehicle manufacturing.
One-component epoxy structural adhesives with snap-cure chemistry are rendering obsolete two-part mixing systems in aluminum-intensive body-in-white applications. BMW and Mercedes-Benz assembly plants in Germany and Hungary are adopting these platforms for cycle time reduction. The elimination of metering equipment and static mixers is compressing capital expenditure requirements for new model launches.
REACH authorization requirements for Substances of Very High Concern are forcing substitution of legacy bisphenol-A-based epoxy resins in structural bonding applications. ECHA's 2023-2024 candidate list updates have elevated scrutiny of specific hardener chemistries used in crash-resistant joints. Formulators are accelerating bio-based epichlorohydrin and non-BPA epoxy development programs to secure downstream supply continuity.
Specification influence is migrating from tier-1 module suppliers toward OEM central engineering teams, consolidating adhesive approval authority in Stuttgart, Munich, and Gothenburg technical centers. This concentration is displacing the traditional pattern of decentralized tier-1 formulation selection. German and Swedish OEMs now mandate direct adhesive supplier auditing for battery pack and structural bonding applications.
Europe Automotive Adhesives and Sealants Market Segmentation
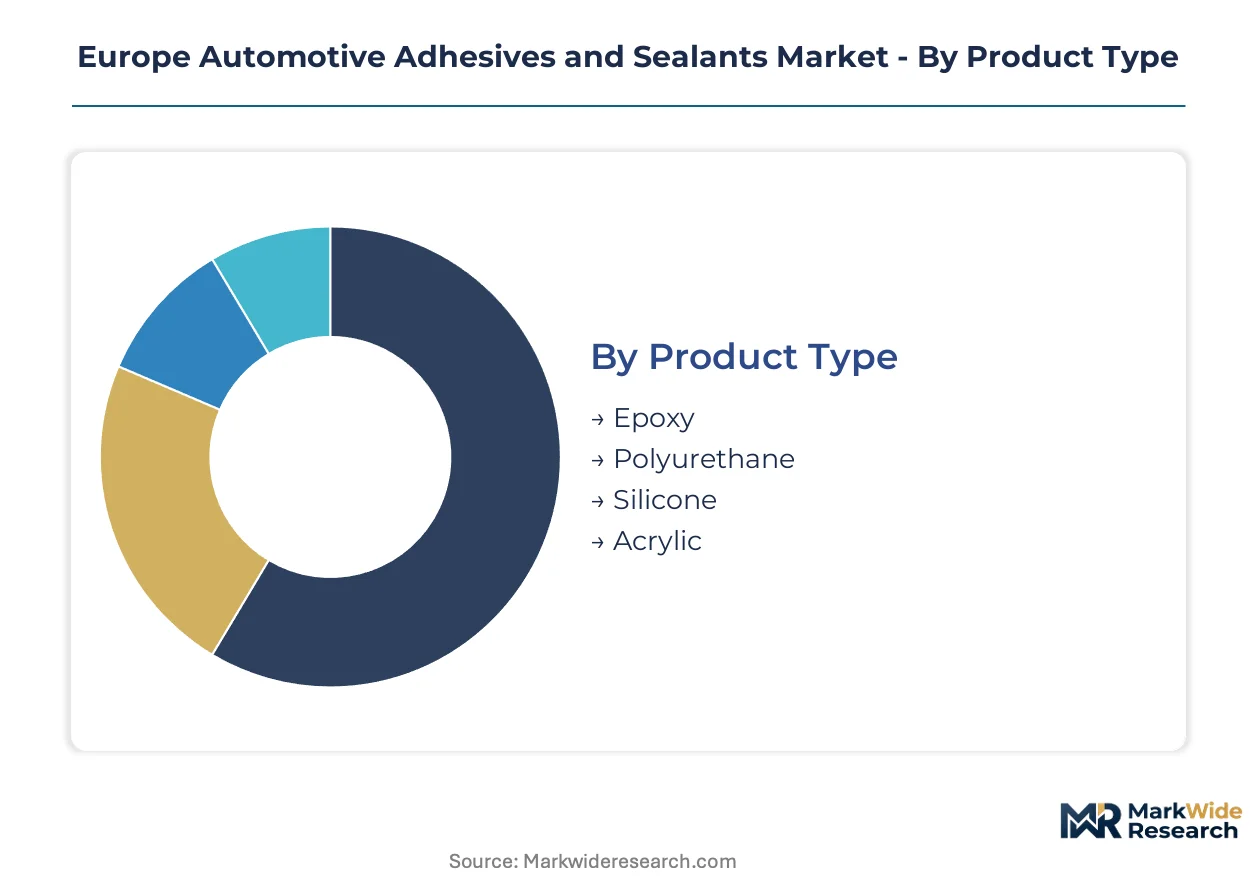
Segmentation in the Europe Automotive Adhesives and Sealants Market reveals distinct procurement rhythms across chemistries and applications. Cycle times vary dramatically from rapid-turn interior assembly specifications to multi-year structural bonding qualifications.
Product Type:
Polyurethane and epoxy formulations command the longest qualification cycles due to crashworthiness testing, while acrylic and silicone platforms turn over faster through tier-1 supplier channels.
- Polyurethane:Elastic polymer systems formulated from polyol-isocyanate reactions deliver paintable, vibration-dampening bonds for direct glazing and exterior seam sealing. Demand concentrates in German OEM paint shops where panoramic roof modules require thermal expansion accommodation across dissimilar substrates.
- Epoxy:High-modulus thermosetting resins achieve shear strengths exceeding structural thresholds for aluminum-intensive body-in-white applications. BMW and Mercedes-Benz engineering centers in Stuttgart and Munich specify one-component snap-cure epoxies to eliminate metering equipment and compress cycle times.
- Silicone:Elastomeric formulations withstand minus 40°C to 150°C service temperatures for underhood gasketing and sensor encapsulation.
- Acrylic:Pressure-sensitive and structural acrylics dominate interior trim fixation where rapid fixture and VOC compliance are prioritized.
Polyurethane anchors the volume base while UV-curable acrylic derivatives gain share at the steepest rate in electronics integration applications.
Application:
Cost tier stratification separates premium structural specifications from economy interior grades, with exterior applications commanding intermediate positioning through paint shop integration requirements.
- Structural:Load-bearing adhesive joints substitute mechanical fasteners in aluminum-steel hybrid architectures, requiring crash-resistant qualification under ECE R94 protocols. German OEM central engineering teams now mandate direct supplier auditing for these applications.
- Exterior:Direct glazing and seam sealing specifications demand elastic, paintable chemistries that accommodate thermal cycling across panoramic roof and windshield modules.
- Interior:Water-based and hot melt platforms dominate acoustic management and trim assembly where REACH VOC restrictions apply most stringently.
- Assembly:General bonding operations span battery pack construction to powertrain gasketing with formulation selection varying by thermal and fluid exposure requirements.
Structural applications extract the highest margin per kilogram while interior volumes scale most broadly across Eastern European assembly plants.
End User:
Customer type determines specification authority concentration, with OEM central engineering displacing traditional tier-1 formulation selection across high-criticality applications.
- OEMs:Central engineering teams in Stuttgart, Munich, and Gothenburg consolidated adhesive approval authority for battery pack and structural bonding applications, mandating direct formulator auditing and collaborative development contracts rather than spot procurement.
- Tier-1 Suppliers:Module integrators retain specification influence for interior and non-structural exterior applications, though their autonomy is narrowing for crash-critical joints.
- Vehicle Assemblers:Contract manufacturing and specialist assembly operations source adhesives through approved vendor lists managed by platform-owning OEMs.
- Aftermarket:Collision repair networks and independent workshops show residual preference for mechanical fastening, limiting bonded joint penetration due to insurance assessor skepticism and technician training gaps.
OEMs anchor the value chain while tier-1 suppliers in Poland and the Czech Republic represent the fastest-expanding procurement channel for emerging EV platform entrants.
Technology:
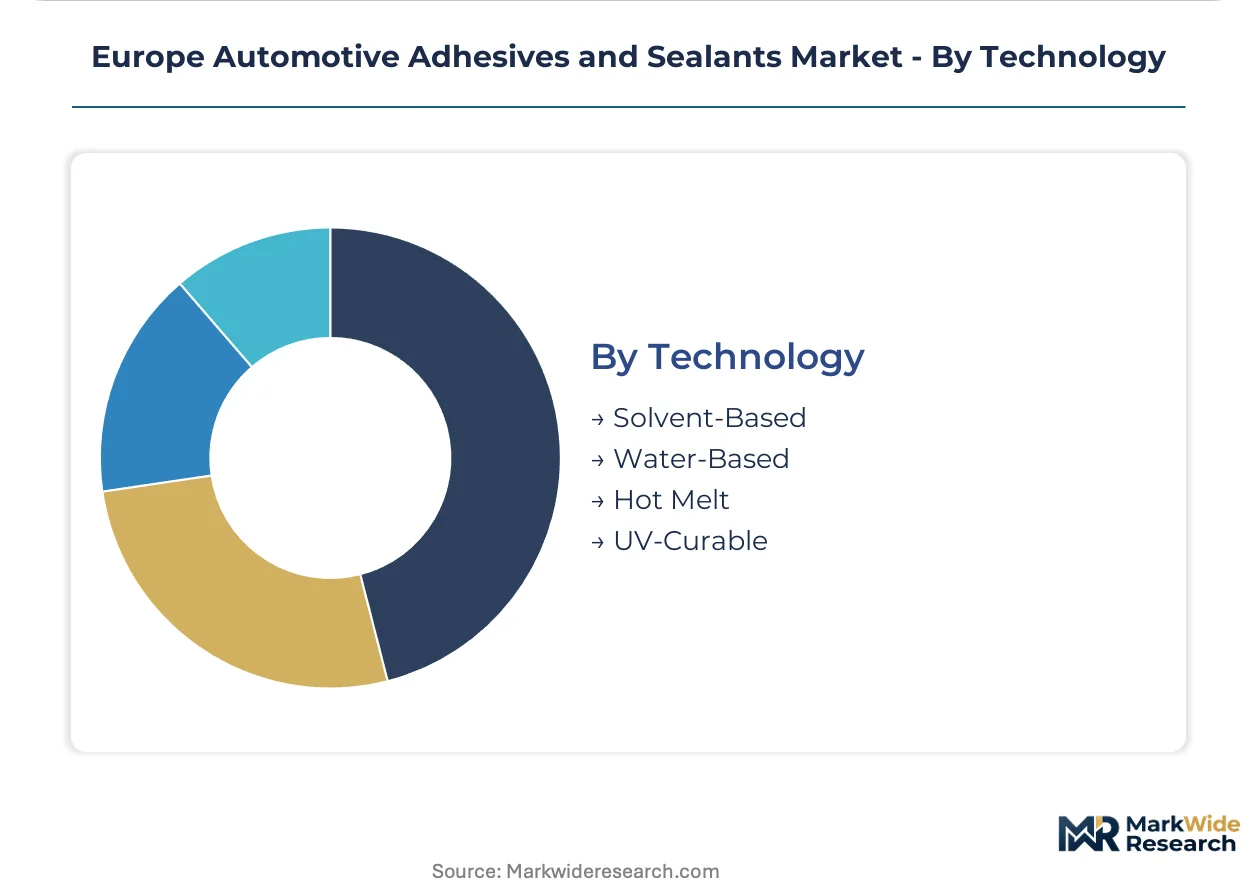
Supply concentration for compliant formulations has shifted toward water-borne and reactive hot melt platforms as ECHA substance evaluations constrain solvent-based alternatives.
- Water-Based:Acrylic and polyurethane dispersions lead interior assembly applications where REACH VOC restrictions and paint shop emissions controls are most stringent, though cure speed limitations exclude them from high-throughput structural operations.
- UV-Curable:Radiation-cured acrylate and epoxy systems achieve instant polymerization for sensor encapsulation and ADAS module integration where thermal cure alternatives cannot meet takt time requirements.
- Hot Melt:Reactive polyurethane hot melts combine rapid green strength development with durable structural performance, gaining specification in automated body-in-white applications.
- Solvent-Based:Legacy formulations face phasedown pressure under EU F-Gas Regulation and ECHA authorization requirements for Substances of Very High Concern, with remaining demand concentrated in specialty aerospace-tier automotive applications.
Water-based technology anchors the installed base while UV-curable systems expand most quickly through electronics integration and miniaturization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in automotive adhesive logistics, connecting Bavarian chemical plants to assembly clusters across the continent.
Germany
Stuttgart and Munich engineering centers consolidate specification authority for structural bonding applications. The EU Green Deal fleet CO2 mandates accelerate aluminum-intensive architectures requiring advanced adhesives. Henkel maintains just-in-time delivery networks to OEM paint shops across the Baden-Württemberg and Bavaria manufacturing belts.
France
Auvergne-Rhône-Alpes hosts specialized formulation development for PSA Group and Renault-Nissan platforms. REACH authorization timelines for Substances of Very High Concern extend supplier qualification cycles. The Lyon-Grenoble chemical corridor concentrates expertise in water-borne polyurethane platforms for interior assembly.
Spain
Battery gigafactory clustering around Valencia and Barcelona generates localized demand for thermal interface materials. The EU F-Gas Regulation constrains solvent-based formulations in exterior applications. Catalonian automotive suppliers expand procurement channels for emerging EV platform entrants.
Poland
Tier-1 supplier densification in the Silesian and Greater Poland voivodeships creates first-mover opportunities for adhesive specification influence. ECHA substance evaluation protocols elevate testing burdens for imported raw materials. The Poznań-Łódź manufacturing corridor attracts EV component investment from Western European OEMs.
Sweden
Gothenburg technical centers mandate direct adhesive supplier auditing for battery pack applications. CSRD supply chain disclosure requirements reward formulators with verified bio-based content. The Trollhättan-Western Sweden automotive cluster drives collaborative development contracts over spot procurement.
Europe Automotive Adhesives and Sealants Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified chemical conglomerates with European manufacturing footprints, specialized adhesive formulators with structural bonding expertise, and materials science multinationals with pressure-sensitive technology platforms. Competitive moves center on collaborative development contracts with OEM central engineering teams and qualification acceleration for battery pack assembly applications.
Among Germany-based chemical enterprises, Henkel AG & Co. KGaA and DELO Industrie Klebstoffe GmbH & Co KGaA exemplify the integrated formulator archetype, anchoring supply relationships through proximity to Stuttgart and Munich engineering centers. Swiss specialty chemical player Sika AG occupies a position emphasizing structural systems for aluminum-intensive architectures, representing the focused technology leadership model within the competitive set.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Sika AG |
| H.B. Fuller Company |
| Huntsman International LLC |
| Dow |
| Arkema Group |
| Illinois Tool Works Inc |
| DELO Industrie Klebstoffe GmbH & Co KGaA |
| Others |
Supply & Pricing Matrix
Undercapacity in German specialty epoxy resin production is compressing supplier margins while amplifying pricing power for compliant water-borne formulation platforms, as REACH authorization timelines force buyers toward qualified alternatives with limited sourcing options.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates crash-qualified structural epoxies from general assembly polyurethanes and commodity interior acrylics. Price differentiation hinges on ECE R94 certification status and volume scale, with German OEM direct contracts commanding premiums over tier-1 spot procurement. Cost compression in standard-grade polyurethane runs through naphtha-linked polyol input volatility. Aftermarket collision repair channels exhibit highest price sensitivity due to insurance assessor reimbursement constraints.
Supply Chain Analysis
Upstream polyol and isocyanate feedstock production centers on Belgium, the Netherlands, and Germany along the ARA chemical corridor. Raw material supply draws from naphtha crackers, propylene derivatives, and imported epoxy resin precursors. Single-source vulnerability concentrates in snap-cure hardener chemistries qualified for BMW and Mercedes-Benz body-in-white applications. Distribution runs through just-in-time pipelines to Baden-Württemberg and Bavaria paint shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle battery pack assembly is reshaping specification authority toward collaborative development contracts, with EU Green Deal fleet CO2 mandates eliminating spot procurement for structural bonding applications.
For Market Incumbents: Insulate qualified supplier status by deepening backward integration into bio-based epichlorohydrin feedstocks before ECHA hardener reclassifications trigger reformulation cycles. Accelerate capacity addition in Poland to capture tier-1 supplier densification in Silesian manufacturing corridors.
For New Entrants and Emerging Players: Establish a beachhead in UV-curable sensor encapsulation for ADAS module integration, where cure-speed requirements outpace incumbent thermal-cure platforms. Target Czech Republic battery gigafactory supply chains with localized technical service capabilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across water-borne polyurethane platforms as automated dispensing equipment standardizes. Long-term viability favors formulators with verified bio-based content transparency under CSRD disclosure requirements. The signal to watch is ECHA harmonized classification publication timelines for isocyanate substances.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures supply continuity ahead of REACH authorization deadlines for BPA-based epoxy resins. |
| Capacity Expansion in Poland | Captures tier-1 supplier procurement growth from Silesian EV component manufacturing clusters. |
| UV-Curable Platform Development | Addresses ADAS sensor miniaturization demands where thermal cure alternatives fail takt time requirements. |
| Long-Term Collaborative Development Contracts | Locks specification influence with Stuttgart and Munich OEM central engineering teams. |
| CSRD Supply Chain Disclosure Certification | Rewards carbon footprint transparency in OEM sustainability scorecards across the EU. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement leads, adhesive formulator R&D directors, and automotive aftermarket distributors and refined through secondary validation against customs trade data, Cefic chemical industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up segment sizing triangulated with top-down market reconciliation confirmed volume estimates.
Demand-supply-balance modeling across the analysis window incorporated vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers. Industry-specific forecast inputs included EU fleet CO2 mandate compliance timelines and battery gigafactory construction announcements.
Stress conditions across petrochemical feedstock volatility, ECHA substance evaluation delays, and EV platform launch timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IHS Markit vehicle registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Saudi Arabia Adhesives Market