
 Nanomaterial Supercapacitors Market | 2026-2036
Nanomaterial Supercapacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Nanomaterial Supercapacitors Market Foresight
The capital-intensity divergence between thin-film deposition specialists and module assemblers is reorganizing competitive hierarchies in nanomaterial supercapacitors. Skeleton Technologies leverages its proprietary curved graphene architecture to dominate heavy-duty transport applications. Panasonic Electronic Devices sustains manufacturing scale across consumer electronics channels in Japan and Southeast Asia. Nesscap specializes in small-format cells for industrial backup power, occupying a defensible niche against larger module competitors.
Nanomaterial supercapacitors store electrical energy through electrochemical double-layer capacitance or pseudocapacitive reactions at electrode surfaces coated with nanostructured carbon, metal oxides, or conductive polymers, achieving power densities exceeding conventional batteries by orders of magnitude while maintaining cycle stability across millions of charge events. Graphene-based electrodes command premium positioning in high-frequency pulse applications due to superior surface-area-to-volume ratios, whereas hybrid systems integrating pseudocapacitive metal oxides with carbon nanotube scaffolds represent the fastest-expanding technology segment as automotive OEMs demand higher energy density without sacrificing power response. Carbon nanotube supply chains remain concentrated among specialty chemical producers, creating margin capture opportunities for electrode manufacturers with captive nanotube synthesis capabilities.
The EU Green Deal and F-Gas Regulation constrain conventional battery chemistries in European grid storage tenders, indirectly expanding addressable market access for electrochemical double-layer devices with benign material profiles. EPA hazardous substance rules and OSHA workplace exposure limits govern U.S. manufacturing of metal oxide nanoparticles, elevating compliance costs for domestic producers relative to Asian competitors operating under MEE guidelines in China. Stakeholders must monitor evolving certification requirements for supercapacitor modules in aviation and rail applications, where emerging safety standards could preemptively disqualify electrode architectures lacking flame-retardant electrolyte formulations.
Market Dynamics
Automotive OEM procurement of graphene-based electrode architectures is compressing supplier qualification timelines and forcing electrode manufacturers to integrate captive nanotube synthesis capabilities.
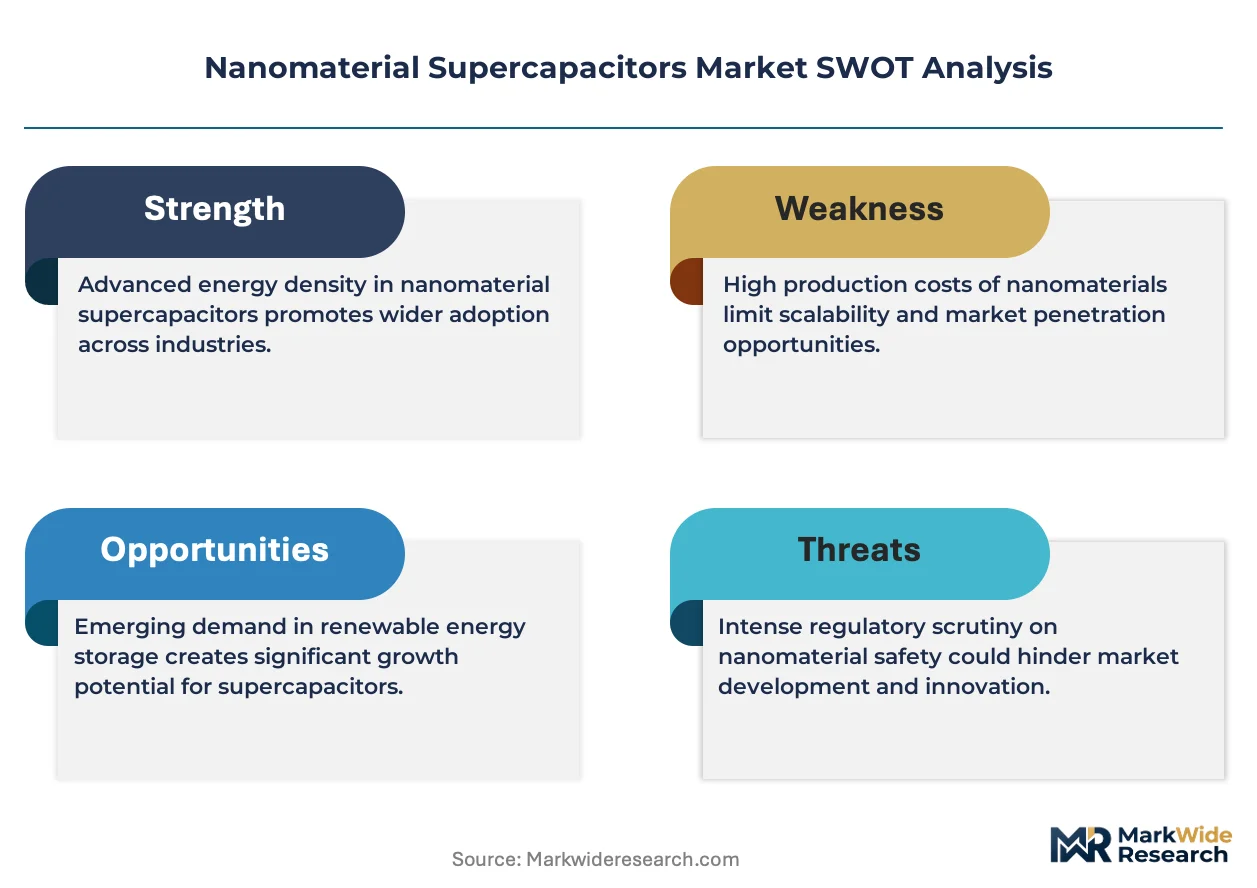
Growth Catalysts
- GB standards compliance:China's dual carbon goals and mandatory GB standards for energy storage components are accelerating domestic production of graphene electrode materials. Domestic battery integrators are securing preferential supply allocations from local producers.
- EU Green Deal procurement:The EU Green Deal and F-Gas Regulation are constraining conventional lithium-ion chemistries in European grid storage tenders, expanding addressable market access for electrochemical double-layer devices with benign material profiles.
- Aviation safety mandates:Emerging flame-retardant electrolyte certification requirements for supercapacitor modules in aviation applications are creating first-mover advantages for electrode architectures meeting preemptive safety standards.
Market Restraints
- Metal oxide nanoparticle compliance costs:EPA hazardous substance rules and OSHA workplace exposure limits elevate U.S. manufacturing costs for metal oxide nanoparticles relative to Asian competitors operating under MEE guidelines in China.
- Carbon nanotube supply concentration:Carbon nanotube supply chains remain concentrated among specialty chemical producers in East Asia, creating margin capture asymmetries and input bottlenecks for non-integrated electrode manufacturers.
- Energy density ceiling:Electrochemical double-layer capacitance mechanisms impose fundamental energy density limitations versus lithium-ion systems, restricting addressable applications in long-duration electric vehicle propulsion.
Strategic Opportunities
- Rail electrification standards:Preemptive flame-retardant electrolyte certification for rail applications creates qualification windows for compliant electrode architectures before mandatory standards crystallize.
- Hybrid pseudocapacitive convergence:Integration of pseudocapacitive metal oxides with carbon nanotube scaffolds represents white-space technology development as automotive OEMs demand higher energy density without sacrificing power response.
- South Korean battery integrator procurement:East Asian manufacturing clusters, particularly South Korean battery integrators, are consolidating procurement of high-density energy storage components, creating volume concentration opportunities for qualified suppliers.
Industry Challenges
- Thin-film deposition talent scarcity:The capital-intensity divergence between thin-film deposition specialists and module assemblers is reorganizing competitive hierarchies, with electrode manufacturers struggling to recruit process engineers with atomic-layer deposition expertise.
- Aviation certification timeline compression:Emerging safety standards for supercapacitor modules in aviation applications require multi-year qualification cycles that preemptively disqualify electrode architectures lacking flame-retardant electrolyte formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanomaterial Supercapacitors Market |
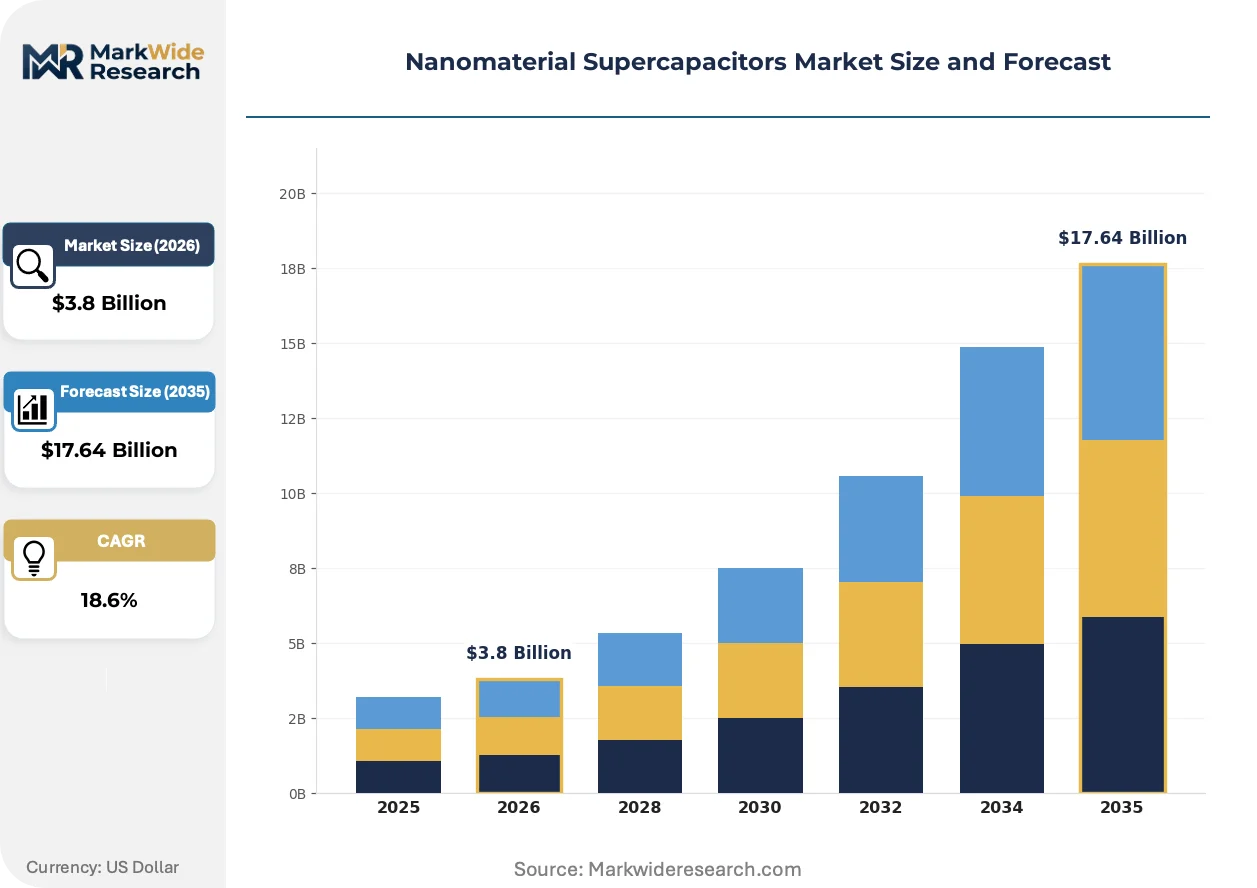
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphene-based, Carbon Nanotubes, Metal Oxide, Conductive Polymers Application: Energy Storage, Automotive, Consumer Electronics, Renewable Energy Systems End User: Manufacturers, Research Institutions, Automotive OEMs, Electronics Developers Technology: Electrochemical Double Layer, Pseudocapacitive, Hybrid Systems, Supercapacitor Modules |
| Companies Covered | Nesscap, Skeleton Technologies, Panasonic Electronic Devices, Innovasion Labs PINC, enyGy, Maxwell Technologies, Cap-XX, Nanocyl SA, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanomaterial Supercapacitors Market Shifts & Advancements
Graphene electrode architectures are compressing form-factor constraints while regulatory frameworks in major economies are rewriting procurement criteria for energy storage systems.
Curved graphene electrode structures are achieving surface-area-to-volume ratios exceeding planar configurations by an order of magnitude. Heavy-duty transport OEMs are accelerating qualification of these architectures for regenerative braking systems. The technology is miniaturizing module footprints while maintaining power density thresholds required for commercial vehicle integration.
The EU F-Gas Regulation and complementary EU Green Deal provisions are systematically disqualifying conventional battery chemistries from grid storage tenders. Electrochemical double-layer devices with benign material profiles are capturing displaced procurement volumes. European utility-scale integrators are rewriting technical specifications to favor carbon-based electrode systems.
Japanese electronics conglomerates are consolidating supercapacitor procurement through direct electrode material partnerships rather than module distributor channels. Consumer electronics channels in Japan and Southeast Asia are witnessing channel compression as buyers seek upstream cost transparency. This pattern is most visible in Osaka and Tokyo manufacturing clusters where Panasonic Electronic Devices sustains manufacturing scale.
Nanomaterial Supercapacitors Market Segmentation
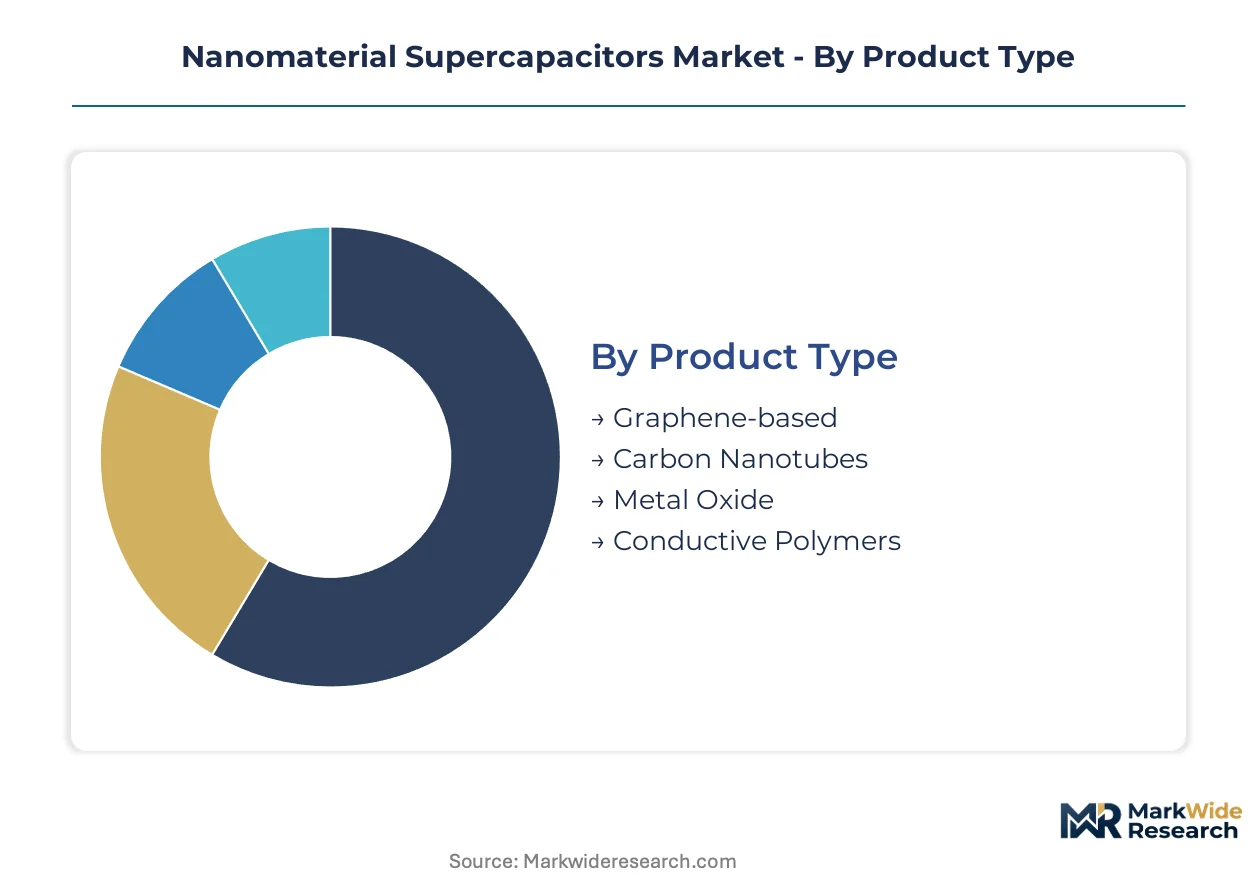
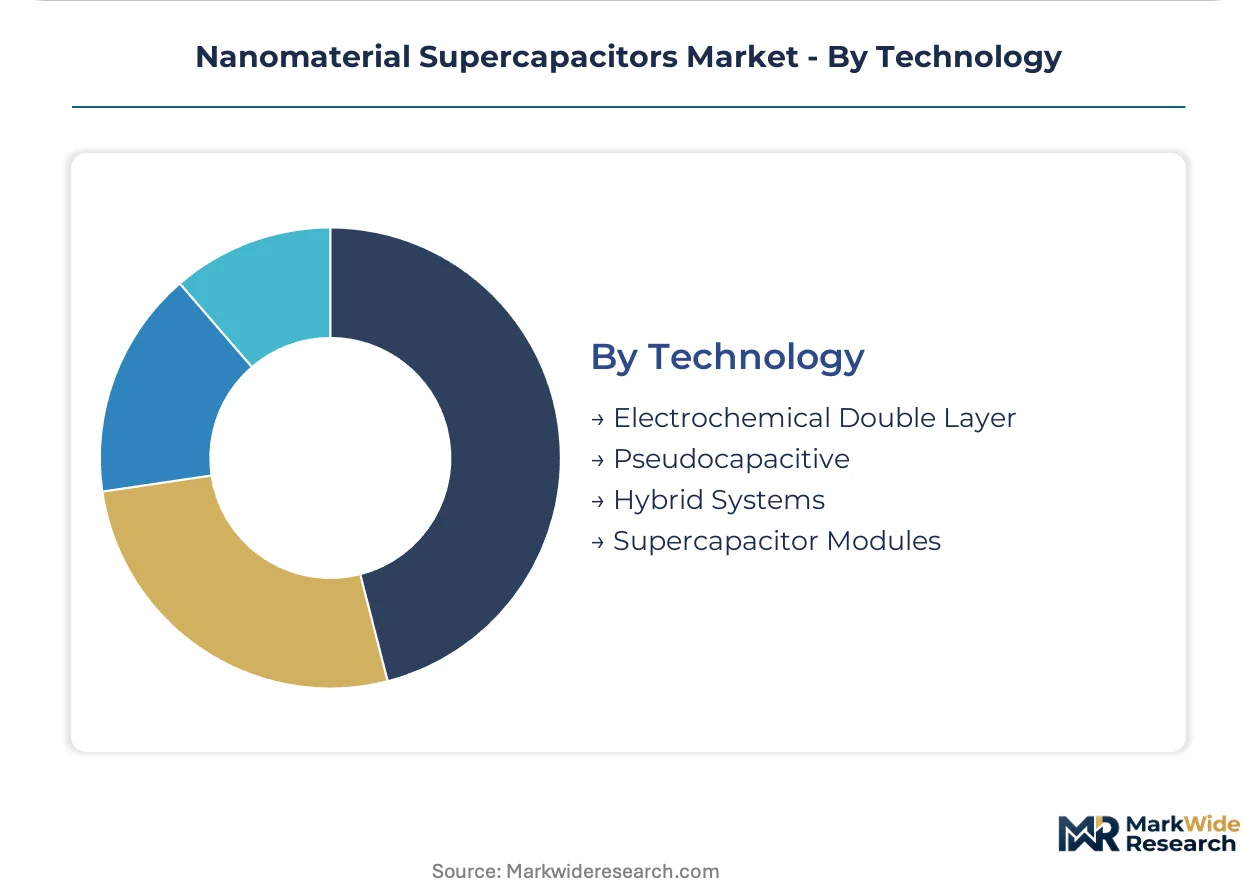
Nanomaterial supercapacitors fragment across four distinct taxonomies that determine procurement pathways and margin capture. Product type dictates electrode manufacturing complexity, while application and end-user categories shape channel access and qualification timelines for suppliers.
Product Type:
Channel distribution varies sharply by electrode chemistry, with graphene-based materials flowing through specialized distributors to automotive integrators while carbon nanotube formulations concentrate in direct manufacturer partnerships.
- Graphene-based:Electrode architectures leverage curved graphene structures achieving surface-area-to-volume ratios exceeding planar configurations. Heavy-duty transport OEMs in Germany and Japan are compressing supplier qualification timelines for regenerative braking integration.
- Carbon Nanotubes:Scaffolds constructed from single-walled and multi-walled nanotubes deliver exceptional conductivity and mechanical stability. South Korean battery integrators are consolidating procurement of nanotube-enhanced electrodes for consumer electronics modules.
- Metal Oxide:Ruthenium and manganese oxide coatings enable pseudocapacitive charge storage mechanisms.
- Conductive Polymers:Polyaniline and polypyrrole electrodes offer solution-processable manufacturing routes.
By volume, Carbon Nanotubes leads. By growth pace, Graphene-based is climbing the fastest.
Application:
Cost tier stratification separates premium automotive qualification programs from standard-grade consumer electronics procurement, with renewable energy systems occupying a mid-tier position on total cost of ownership metrics.
- Energy Storage:Grid-scale and industrial backup systems requiring cycle stability across millions of charge events. European utility-scale integrators are rewriting technical specifications under EU Green Deal procurement frameworks to favor carbon-based electrode systems.
- Automotive:Regenerative braking and fast-charge buffer applications in electric and hybrid vehicles. Chinese OEMs are securing preferential supply allocations from domestic graphene electrode producers meeting GB standards compliance.
- Consumer Electronics:Miniaturized power buffers for smartphones, wearables, and portable devices.
- Renewable Energy Systems:Smoothing intermittency in solar and wind generation installations.
By revenue concentration, Automotive leads. By expansion trajectory, Energy Storage is gaining share fastest.
End User:
Customer type determines contract structure, with automotive OEMs demanding captive synthesis capabilities and multi-year qualification cycles while research institutions prioritize technical flexibility over scale.
- Automotive OEMs:Vehicle manufacturers requiring flame-retardant electrolyte formulations and aviation-grade safety certifications. Japanese and German OEMs are accelerating direct electrode material partnerships rather than module distributor channels.
- Manufacturers:Industrial integrators assembling supercapacitor modules for diverse end-markets. Chinese domestic battery producers are capturing preferential allocations under MEE environmental guidelines.
- Research Institutions:Universities and national laboratories developing next-generation electrode architectures.
- Electronics Developers:Consumer device designers integrating small-format cells.
By procurement volume, Manufacturers lead. By contract value per unit, Automotive OEMs is expanding most quickly.
Technology:
Supply concentration among thin-film deposition specialists creates margin asymmetries, with electrochemical double-layer devices capturing utility-scale tenders while hybrid systems command automotive qualification premiums.
- Hybrid Systems:Integration of pseudocapacitive metal oxides with carbon nanotube scaffolds. Automotive OEMs are demanding this architecture to achieve higher energy density without sacrificing power response, creating white-space development opportunities.
- Electrochemical Double Layer:Pure carbon-based charge storage through electrostatic separation at electrode-electrolyte interfaces. EU F-Gas Regulation constraints on conventional battery chemistries are displacing procurement volumes toward these benign material profiles.
- Pseudocapacitive:Surface redox reactions enabling enhanced energy density through metal oxide or polymer coatings.
- Supercapacitor Modules:Packaged cells with integrated management systems for drop-in deployment.
By installed base, Electrochemical Double Layer leads. By development priority, Hybrid Systems shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with East Asian electrode manufacturers while European module assemblers absorb margin compression from regulatory compliance costs. Chinese producers leverage MEE environmental guidelines and GB standards to capture domestic procurement volumes. German automotive OEMs face elevated input costs from ECHA REACH documentation requirements for imported nanomaterials.
China
Domestic battery integrators are securing preferential graphene electrode allocations from local producers. The dual carbon goals and mandatory GB standards for energy storage components accelerate domestic manufacturing scale. Manufacturing clusters in Shenzhen and Dongguan are expanding thin-film deposition capacity for automotive qualification programs.
Germany
Heavy-duty transport OEMs in Stuttgart and Munich are compressing supplier qualification timelines for regenerative braking integration. The EU F-Gas Regulation and EU Green Deal provisions systematically disqualify conventional battery chemistries from grid storage tenders. The Rhine-Ruhr industrial corridor hosts electrode manufacturers expanding electrochemical double-layer production for utility-scale integrators.
United States
Aviation-grade supercapacitor procurement is shifting toward flame-retardant electrolyte formulations ahead of FAA safety mandates. EPA hazardous substance rules and OSHA workplace exposure limits elevate metal oxide nanoparticle manufacturing costs relative to Asian competitors. The Pacific Northwest and Greater Boston clusters concentrate research institutions developing next-generation hybrid pseudocapacitive architectures.
Japan
Electronics conglomerates in Osaka and Tokyo are consolidating procurement through direct electrode material partnerships rather than module distributor channels. METI industrial policy supports domestic carbon nanotube scaffold production for consumer electronics modules. The Kansai manufacturing belt sustains high-volume assembly operations for smartphone and wearable device integration.
South Korea
Battery integrators in Seoul and Busan are consolidating procurement of high-density energy storage components from qualified suppliers. Domestic producers leverage captive nanotube synthesis capabilities to capture margin from concentrated East Asian supply chains. The Gyeonggi-do province hosts electrode manufacturers qualifying hybrid systems for automotive OEM power response specifications.
Nanomaterial Supercapacitors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the value chain. Thin-film deposition specialists command premium positioning in automotive qualification programs while module assemblers compete on manufacturing scale and channel access. Three archetypes dominate: integrated electrode manufacturers with captive nanomaterial synthesis, specialized thin-film deposition contractors, and volume-focused module packagers. Competitive moves concentrate on backward integration into nanotube production and strategic partnerships with automotive OEMs for multi-year qualification cycles.
Among the named players, Skeleton Technologies and Panasonic Electronic Devices exemplify divergent scale-positioning strategies, while Nesscap occupies a specialist niche. Skeleton Technologies represents the integrated technology archetype with proprietary electrode architecture capabilities. Panasonic Electronic Devices anchors the volume-manufacturing tier across consumer electronics channels. Nesscap exemplifies the defensible niche strategy focused on small-format industrial applications.
| Leading Market Players |
|---|
| Nesscap |
| Skeleton Technologies |
| Panasonic Electronic Devices |
| Innovasion Labs PINC |
| enyGy |
| Maxwell Technologies |
| Cap-XX |
| Nanocyl SA |
| Murata Manufacturing |
| Others |
Supply & Pricing Matrix
Ninety-day electrode qualification timelines compress procurement cycles and concentrate pricing power with East Asian manufacturers holding captive nanotube synthesis capabilities. Automotive OEMs absorb premium configured-to-order pricing for flame-retardant electrolyte formulations while standard-grade carbon nanotube electrodes trade at compressed margins through distributor channels.
Pricing Analysis
The customization-premium spread separates automotive qualification programs from commodity procurement, with configured-to-order graphene architectures commanding substantial markups over standard carbon nanotube electrodes. Price differentiation hinges on GB standards certification tier and volume scale, with Chinese domestic battery integrators securing preferential allocations at compressed unit economics. Cost compression in standard-grade modules intensifies as South Korean battery integrators consolidate procurement volumes. Research institutions exhibit highest price sensitivity due to budget-constrained pilot programs, while aviation OEMs demonstrate lowest sensitivity given safety-critical qualification requirements.
Supply Chain Analysis
Inventory buffers for specialty metal oxide nanoparticles extend to twelve weeks as EPA hazardous substance documentation elongates customs clearance for U.S.-bound shipments. Manufacturing gravity centers on China, South Korea, and Japan, with Shenzhen and Gyeonggi-do provinces hosting thin-film deposition specialists. Electrode production draws from concentrated carbon nanotube feedstock, graphene precursor chemicals, and flame-retardant electrolyte formulations. Single-source vulnerability permeates single-walled nanotube supply where three specialty chemical producers control global output. Distribution runs through direct manufacturer partnerships for automotive OEMs and specialized industrial distributors for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where multi-year automotive qualification cycles create switching-cost barriers that entrench qualified suppliers against substitute technologies.
For Market Incumbents: Fortify captive nanotube synthesis capabilities to capture margin from supply-concentrated feedstock markets and preempt emerging thin-film deposition specialists from achieving automotive qualification. Accelerate flame-retardant electrolyte certification investments ahead of FAA safety mandate crystallization to extend qualification lead times as a competitive weapon against substitute lithium-ion buffer systems.
For New Entrants and Emerging Players: Aviation safety documentation services represent an underserved layer where incumbent electrode manufacturers lack dedicated compliance advisory capabilities. Penetrate the research institution segment through flexible small-batch configured-to-order programs with embedded technical support, leveraging lower qualification barriers versus automotive procurement channels.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because evolving aviation and rail safety standards continuously extend qualification timelines and favor incumbent technical documentation libraries. Target acquisition candidates among thin-film deposition specialists with atomic-layer deposition expertise and existing automotive OEM relationships. Monitor FAA and EASA supercapacitor safety standard development velocity as the critical inflection signal for qualification timeline expansion or compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanotube Synthesis | Captures margin from concentrated East Asian specialty chemical producers and secures supply continuity for automotive qualification programs. |
| Flame-Retardant Electrolyte Certification Investment | Preempts emerging FAA and EASA safety mandates to secure first-mover qualification windows in aviation and rail applications. |
| Direct OEM Partnership Structure | Eliminates distributor margin extraction and provides demand visibility for capacity planning in Japanese and German automotive clusters. |
| Hybrid Pseudocapacitive R&D Program | Addresses automotive OEM demand for energy density improvement without sacrificing power response characteristics. |
| GB Standards Compliance Infrastructure | Unlocks preferential supply allocations from Chinese domestic battery integrators operating under dual carbon goals procurement frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrode manufacturing executives, automotive OEM procurement directors, thin-film deposition process engineers, aviation safety certification specialists, and utility-scale energy storage integrators. Secondary validation drew from MEE environmental guideline publications, ECHA REACH documentation databases, FAA safety standard draft releases, and SEC filings of publicly traded battery component suppliers. Bottom-up volume modeling triangulated against top-down market sizing across electrode chemistry, application vertical, and geographic production cluster dimensions.
Across the analysis window, forecasts employed a segmented growth attribution framework modeling graphene-based, carbon nanotube, metal oxide, and conductive polymer electrode chemistries against automotive, energy storage, consumer electronics, and renewable energy system applications. CAGRs were derived from regression analysis of historical procurement volume trends and forward-projected OEM qualification pipeline visibility. Key inputs included GB standards implementation velocity in China, EU F-Gas Regulation enforcement intensity, and aviation safety certification timeline compression rates.
Forecasts assume regulatory continuity in EPA hazardous substance rules, EU Green Deal procurement frameworks, and MEE environmental guidelines; material policy shifts would require re-modeling. Technological substitution risk from solid-state battery buffer systems and raw material price volatility in carbon nanotube feedstock represent primary forecast revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanotechnology Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Nano Copper Oxide Market