
 Nanoparticle Titanium Dioxide (Tio2) Market | 2026-2036
Nanoparticle Titanium Dioxide (Tio2) Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoparticle Titanium Dioxide (Tio2) Market Foresight
Multi-source procurement for chloride-route feedstock is repositioning how coating manufacturers secure nano-TiO2 supply. Evonik Industries AG leverages its specialty chemicals infrastructure to dominate high-purity powder grades for cosmetics and pharmaceuticals. The Chemours Company anchors North American supply through integrated ilmenite-to-pigment operations at its Mississippi facilities. Tronox Holdings Plc competes on scale, sustaining vertical control over mineral sands in Australia and South Africa.
Nanoparticle titanium dioxide consists of crystalline TiO2 with primary particle sizes typically below 100 nanometers, existing mainly in anatase or rutile polymorphs produced via sulfate or chloride processing routes. Its industrial purpose centers on exploiting high refractive index, photocatalytic activity, and UV absorption for functional coatings, sunscreens, and environmental remediation systems. Powder formulations lead volume due to blending flexibility in paints and plastics, while liquid suspensions represent the fastest-growing format as cosmetic brands seek ready-to-disperse inputs. Photocatalysis applications command premium positioning in self-cleaning surfaces and air purification systems, though pigmentation retains the deepest margin pool across architectural and automotive coating segments.
EPA oversight under the Toxic Substances Control Act governs nano-TiO2 manufacture and import in the United States, while REACH in Europe mandates registration and hazard communication for nanoscale substances placed on the market. China's SAMR enforces GB standards for nano-material labeling and occupational exposure limits, creating divergent compliance burdens for multinational suppliers. Manufacturers must monitor regulatory divergence between jurisdictions, as divergent nano-specific thresholds threaten to fragment product formulations and testing protocols.
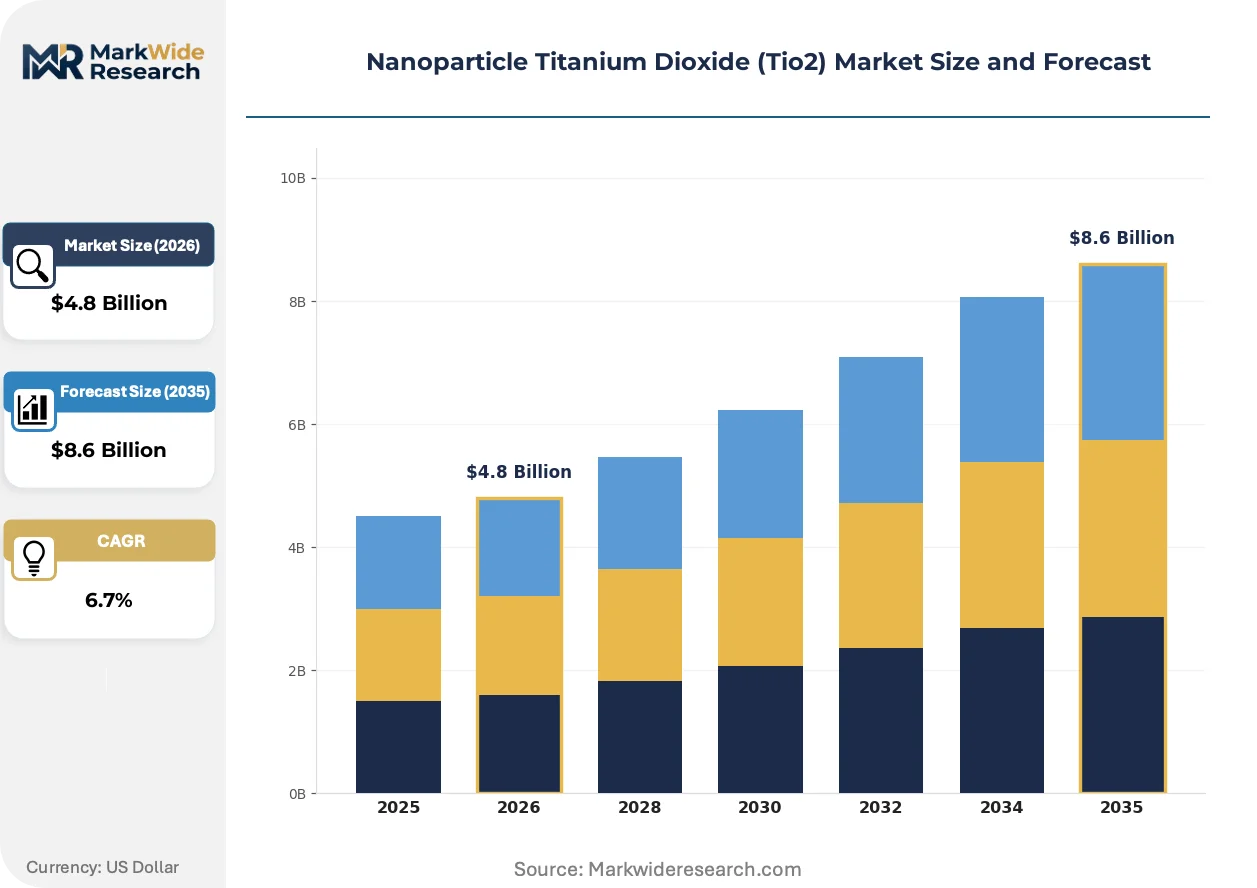
Market Dynamics
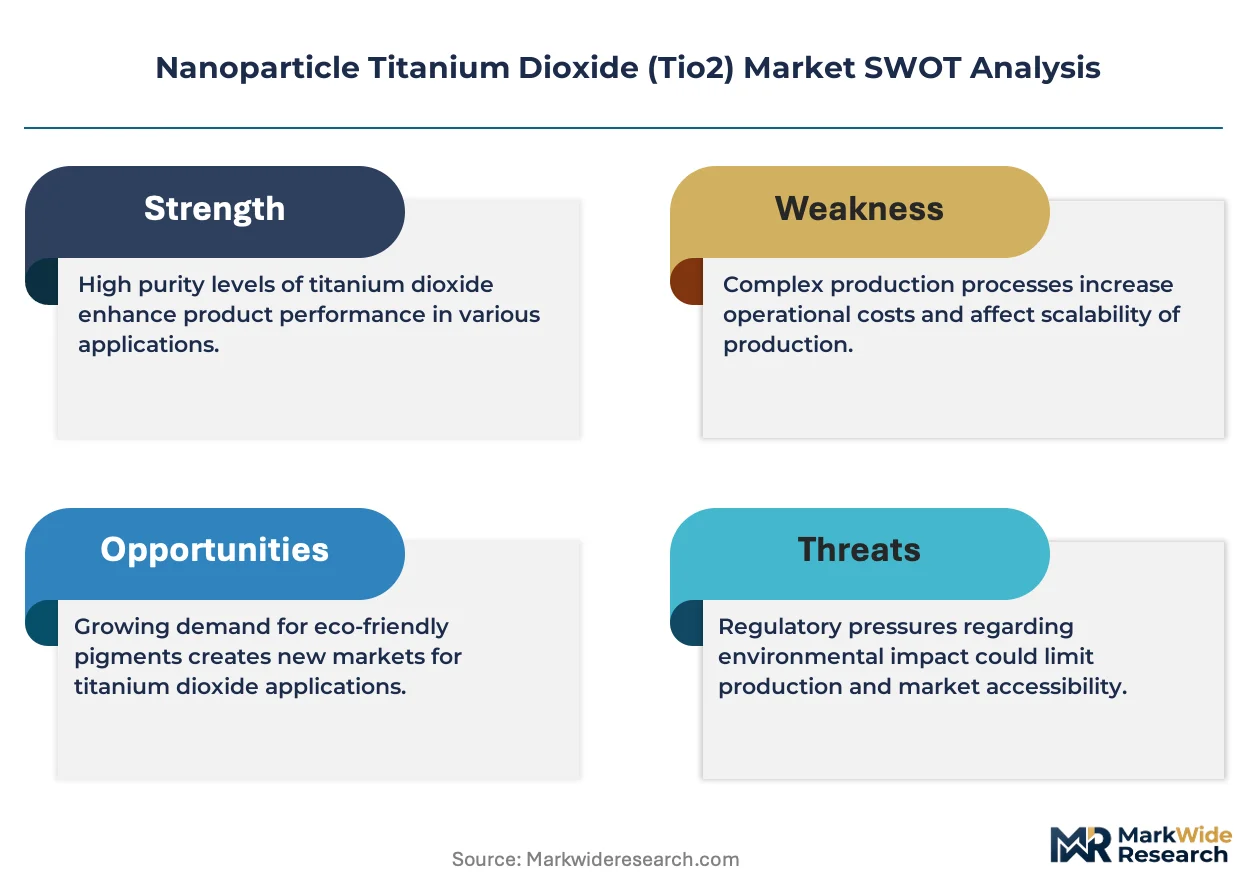
REACH registration requirements in Europe and evolving EPA guidance in the United States are tightening safety assessment protocols for nanoscale materials, forcing manufacturers to bifurcate formulations by jurisdiction and fragmenting previously standardized product lines.
Growth Catalysts
- UV protection formulations:Sunscreen and personal care manufacturers are expanding nano-TiO2 procurement for high-SPF products, driven by consumer preference for transparent mineral-based UV blockers over chemical alternatives.
- Photocatalytic coatings:Self-cleaning surfaces and air purification systems exploit TiO2's photocatalytic activity, opening premium positioning in architectural and environmental remediation segments.
- China's domestic production scale:Rapid expansion of pigment and coating manufacturing in China concentrates demand and creates pull-through for chloride-route feedstock procurement.
Market Restraints
- Ilmenite supply concentration:Vertical control over mineral sands in Australia and South Africa limits feedstock diversification and exposes coating manufacturers to concentrate pricing volatility.
- Regulatory fragmentation:Divergent nano-specific thresholds between REACH, EPA Toxic Substances Control Act oversight, and China's SAMR GB standards threaten to multiply compliance testing burdens.
- Substitution pressure from zinc oxide:Zinc oxide nanoparticles compete in UV protection applications, particularly where transparency requirements are less stringent.
Strategic Opportunities
- Ready-to-disperse liquid suspensions:Cosmetic brands seek liquid formats to reduce in-house milling infrastructure, creating white space for formulation houses with dispersion expertise.
- Environmental remediation systems:Water treatment and air purification infrastructure projects in China represent underpenetrated demand for photocatalytic TiO2 deployment.
- EU Green Deal alignment:Sustainability mandates favor photocatalytic self-cleaning surfaces that reduce maintenance chemical consumption in building operations.
Industry Challenges
- Nanotoxicology assessment capacity:Limited specialized laboratories capable of conducting OECD-compliant nanomaterial hazard characterization create bottlenecks in registration timelines.
- Process reconfiguration for sulfate-to-chloride conversion:Coating manufacturers face capital intensity in shifting feedstock acceptance criteria to match chloride-route purity specifications.
- Labeling harmonization delays:Inconsistent nano-material disclosure requirements across SAMR, EPA, and ECHA jurisdictions complicate single-SKU global distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoparticle Titanium Dioxide (Tio2) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Paste, Suspension, Liquid End Use Industry: Paints, Coatings, Plastics, Cosmetics Application: UV Protection, Pigmentation, Photocatalysis, Food Additive Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Evonik Industries AG, The Chemours Company, Tronox Holdings Plc, BASF SE, Huntsman Corporation, Kronos Worldwide Inc., Ishihara Sangyo Kaisha Ltd., Venator Materials PLC, Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoparticle Titanium Dioxide (Tio2) Market Shifts & Advancements
Surface functionalization chemistry and dispersion technology are reshaping how nano-TiO2 integrates into end-use formulations, shifting value capture from commodity powder supply toward engineered intermediate solutions.
Doped anatase nanoparticles with visible-light photocatalytic activation are overtaking standard UV-activated grades in indoor air purification applications. Building materials manufacturers in Japan and South Korea specify these modified particles for low-light environments. The technology is compressing the addressable market for conventional uncoated powders in premium architectural segments.
REACH annex revisions under ECHA nanomaterial guidance are mandating enhanced substance characterization data for nanoforms placed on the European market. Industrial coating formulators must now submit particle size distribution, surface area, and morphology specifications distinct from bulk material dossiers. Pigment suppliers serving automotive OEMs are responding by establishing dedicated nano-regulatory affairs functions.
Direct long-term supply agreements between cosmetic brand houses and chloride-route producers are displacing spot market purchasing for high-purity cosmetic grades. Specialty chemical distributors in the personal care channel face margin compression as buyers consolidate procurement volumes with integrated manufacturers. This pattern is most visible in South Korea and France, where domestic beauty conglomerates command sufficient scale to negotiate captive supply arrangements.
Nanoparticle Titanium Dioxide (Tio2) Market Segmentation
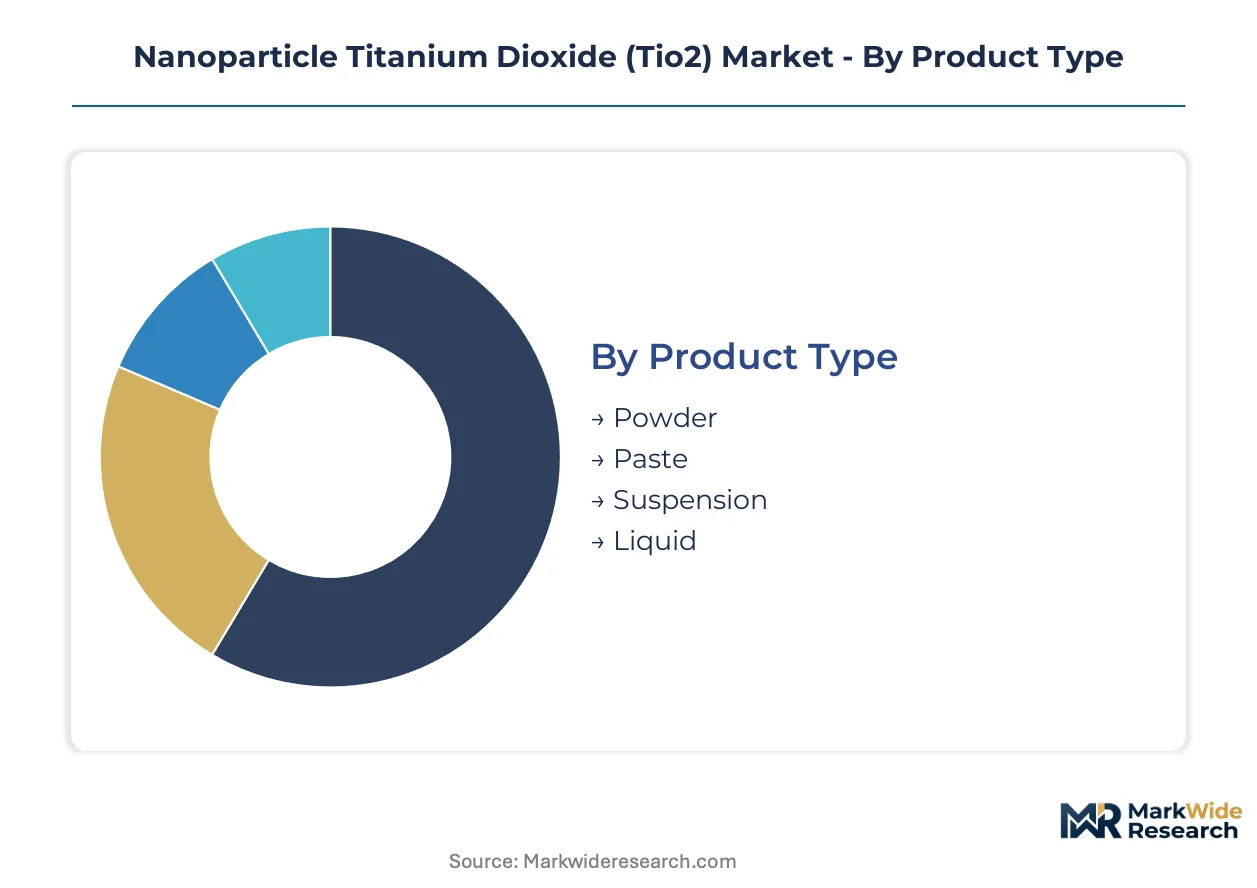
Nanoparticle TiO2 procurement patterns diverge sharply across formulation formats and end-use specifications, forcing suppliers to maintain parallel production lines for powder bulk buyers versus liquid dispersion customers. Regulatory hazard classifications further complicate segmentation, as nano-specific registration requirements in Europe and China create distinct compliance tiers within each product category.
Product Type:
Customization intensity spans from commodity powder grades requiring minimal post-processing to engineered liquid suspensions demanding surface functionalization and stabilization chemistry.
- Powder:Crystalline TiO2 in anatase or rutile polymorphs, typically surface-coated for dispersion stability in polymer matrices. Paints and plastics manufacturers in China and Germany concentrate procurement here, driven by blending flexibility and lower per-kilogram logistics costs for high-volume coating operations.
- Liquid:Ready-to-disperse aqueous or solvent-based suspensions with pre-milled particle size distribution and proprietary dispersant packages. Cosmetic formulators in France and South Korea dominate demand, seeking to eliminate in-house milling infrastructure and reduce occupational dust exposure compliance burdens.
- Paste:High-solids concentrates optimized for specific resin systems, common in automotive OEM coating lines requiring consistent batch-to-batch viscosity.
- Suspension:Lower-solids aqueous formats favored in environmental remediation systems and photocatalytic surface treatments where spray application uniformity matters.
Leading the category by volume: Powder. Expanding most quickly: Liquid.
End Use Industry:
Margin capture potential correlates inversely with formulation sophistication, as commodity pigment buyers squeeze pricing while specialty cosmetic and functional coating segments absorb premium positioning.
- Paints:Architectural and automotive coating manufacturers represent the deepest volume pool, specifying chloride-route rutile grades for exterior durability and color retention. Chinese construction activity and German automotive OEM specifications drive procurement concentration.
- Cosmetics:Mineral sunscreen and color cosmetic brands command highest purity specifications, requiring sub-50nm primary particles with tight size distribution for optical transparency. South Korean beauty conglomerates and French luxury houses are consolidating direct supply agreements with chloride-route producers.
- Coatings:Industrial protective and marine coatings leverage photocatalytic and self-cleaning functionalities, particularly in Japanese infrastructure projects.
- Plastics:Masterbatch compounders in the United States and Germany integrate nano-TiO2 for UV stabilization in outdoor polymer applications.
Deepest margin pool: Cosmetics. Steepest volume trajectory: Paints.
Application:
Functional performance requirements create distinct specification tiers, from passive optical properties to active photocatalytic chemistry demanding precise crystalline phase control.
- UV Protection:Transparent mineral UV blockers in SPF formulations exploit high refractive index and UV-B/UV-A absorption without visible whitening. Personal care procurement concentrates in France, South Korea, and the United States, where FDA and ANSM guidance on nano-material safety labeling shapes formulation choices.
- Photocatalysis:Self-cleaning surfaces and air purification systems require uncoated anatase with optimized surface area for radical generation under UV or visible-light activation. Japanese and South Korean building materials manufacturers specify doped variants for low-light indoor environments.
- Pigmentation:Opacifying and brightening applications in paints and plastics represent the foundational volume use case, with rutile grades preferred for exterior durability.
- Food Additive:E171 whitening applications face regulatory pressure from EFSA and FDA reviews, constraining nano-specific grade deployment in favor of larger particle size alternatives.
Highest premium positioning: Photocatalysis. Broadest addressable base: Pigmentation.
Distribution Channel:
Supply chain configuration reflects customer scale and technical service requirements, with direct relationships displacing intermediaries for high-volume cosmetic and automotive accounts.
- Direct Sales:Integrated manufacturers engage cosmetic brand houses and automotive OEMs through long-term supply agreements with embedded technical service and regulatory dossier support. South Korean and French beauty conglomerates increasingly bypass distributors for captive chloride-route arrangements.
- Distributors:Specialty chemical distributors retain relevance for mid-tier coating formulators and regional plastics compounders requiring smaller lot sizes and blended product portfolios.
- Online:E-procurement platforms serve research institutions, small-scale cosmetic startups, and environmental remediation contractors seeking rapid sample access and transparent pricing.
- Retail:Limited to consumer-facing photocatalytic surface treatment kits and specialty coating products in select markets.
Contract value concentrates: Direct Sales. Channel share climbing fastest: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volumes for nanoparticle TiO2 as domestic coating and pigment manufacturing scales rapidly. European REACH compliance burdens and EPA guidance evolution in the United States fragment formulation standards across major demand centers. Procurement patterns in South Korea and Japan favor high-purity cosmetic grades with direct supply arrangements.
China
Construction activity and automotive coating production drive nano-TiO2 consumption in Jiangsu and Shandong provinces. SAMR enforces GB standards for nano-material labeling and occupational exposure limits, creating compliance protocols distinct from Western jurisdictions. The Yangtze River Delta hosts integrated chloride-route pigment facilities supplying both domestic coating manufacturers and export-oriented cosmetic formulators.
United States
Personal care brands and plastics compounders anchor demand for UV-stabilization and sunscreen applications. EPA oversight under the Toxic Substances Control Act governs manufacture and import, with evolving guidance on nanoscale substance characterization. The Gulf Coast corridor sustains ilmenite-to-pigment operations serving architectural coating manufacturers and masterbatch producers.
Germany
Automotive OEM specifications and industrial coating formulations concentrate procurement in North Rhine-Westphalia and Bavaria. ECHA administers REACH annex revisions mandating enhanced nanoform characterization data distinct from bulk material dossiers. The Cologne-Düsseldorf chemical corridor hosts regulatory affairs functions established by pigment suppliers serving premium coating segments.
South Korea
Beauty conglomerates command sufficient scale to negotiate captive supply arrangements for cosmetic-grade nano-TiO2. MFDS guidance on nanomaterial safety labeling shapes formulation choices for mineral sunscreen products. Seoul Capital Area headquarters house procurement teams consolidating direct long-term agreements with chloride-route producers, displacing specialty chemical distributors.
Japan
Building materials manufacturers specify doped anatase nanoparticles for low-light photocatalytic applications in indoor air purification systems. METI standards influence visible-light activation specifications for self-cleaning surface treatments. The Kansai region around Osaka anchors demand for modified particles in premium architectural segments, compressing markets for conventional uncoated powders.
Nanoparticle Titanium Dioxide (Tio2) Market Competitive Landscape
Backward integration into mineral sands and chloride-route feedstock dominates the current landscape as manufacturers secure supply certainty against ilmenite pricing volatility. The vendor base separates into three tiers: integrated miners-to-pigment producers with captive mineral control, specialty chemical houses focusing on surface-functionalized cosmetic grades, and regional sulfate-route operators serving commodity coating demand. Strategic differentiation runs through M&A consolidation of mineral sands assets and capacity expansion in high-purity chloride-route output.
Among Germany-based specialty chemical operators, Evonik Industries AG occupies a position exemplifying the high-purity powder archetype for cosmetics and pharmaceuticals. The Chemours Company and Tronox Holdings Plc represent the integrated miner-to-pigment model, with geographic naming conventions indicating North American and British-domiciled structures respectively. These three anchors illustrate how competitive positioning stratifies between functionalization expertise and upstream resource control.
| Leading Market Players |
|---|
| Evonik Industries AG |
| The Chemours Company |
| Tronox Holdings Plc |
| BASF SE |
| Huntsman Corporation |
| Kronos Worldwide Inc. |
| Ishihara Sangyo Kaisha Ltd. |
| Venator Materials PLC |
| Cabot Corporation |
| Others |
Supply & Pricing Matrix
Ilmenite concentrate pricing benchmarks from Australian mineral sands operations cascade through chloride-route processing costs into three distinct procurement tiers for nano-TiO2 buyers. Coating manufacturers absorbing feedstock volatility face compressed margins on commodity rutile grades, while cosmetic formulators lock in long-term offtake agreements at premium fixed pricing.
Pricing Analysis
Volume-mass commodity pigment buyers squeeze per-kilogram pricing on standard rutile powders, while margin capture concentrates in cosmetic-grade nano-TiO2 where sub-50nm particle specifications command certification premiums. Three-tier pricing structure across premium cosmetic, standard industrial, and economy coating levels reflects purity gradients and REACH dossier completeness. Cost compression in standard-grade powders intensifies as Chinese chloride-route capacity expands feedstock availability. Masterbatch compounders exhibit highest price sensitivity due to polymer substitution options, whereas mineral sunscreen brands absorb premium positioning for optical transparency guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Australian and South African mineral sands corridors controlling ilmenite and rutile feedstock for chloride-route production. Downstream manufacturing draws from Chinese pigment facilities, German specialty chemical operations, and US Gulf Coast ilmenite-to-pigment complexes. Logistics chokepoints through Rotterdam and Singapore port hubs concentrate bulk powder shipments. Distribution runs through direct long-term agreements for high-volume cosmetic and automotive accounts, with specialty distributors serving regional coating formulators requiring smaller lot sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH nanoform characterization requirements create a barrier-to-entry moat favoring incumbent pigment suppliers with dedicated regulatory affairs infrastructure.
For Market Incumbents: Hedge against zinc oxide substitution in UV protection by accelerating visible-light photocatalytic doping programs for indoor air purification applications. Consolidate backward integration into mineral sands through offtake partnerships with Australian corridor operators, securing feedstock certainty against concentrate pricing volatility. Expand high-purity chloride-route capacity in China to capture cosmetic-grade demand from consolidating South Korean beauty conglomerates.
For New Entrants and Emerging Players: Capture white space in ready-to-disperse liquid suspension formats for mid-tier cosmetic brands seeking to eliminate in-house milling infrastructure. Environmental remediation contractors in China represent the most penetrable demand cluster for photocatalytic anatase deployment. Pursue formulation house partnerships with dispersion chemistry expertise as the primary go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty chemical houses with surface functionalization capabilities in European regulatory corridors. Long-term viability over the coming decade hinges on nano-regulatory compliance infrastructure rather than commodity scale. Watch ECHA guidance evolution on nanomaterial hazard classification thresholds as the critical inflection signal for portfolio repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sands | Secures ilmenite supply certainty against Australian corridor pricing volatility for chloride-route producers. |
| REACH Nanoform Dossier Investment | Establishes regulatory moat preventing commodity sulfate-route competitors from accessing European cosmetic markets. |
| Visible-Light Photocatalytic Doping | Opens Japanese and South Korean building materials demand for low-light indoor air purification applications. |
| Direct Supply Agreement Consolidation | Displaces specialty chemical distributors as South Korean and French beauty conglomerates centralize procurement. |
| Liquid Suspension Capacity Expansion | Captures cosmetic formulator preference for ready-to-disperse inputs eliminating occupational dust exposure compliance. |
Research Methodology
Independent corroboration across plant managers at chloride-route facilities, procurement leads at coating OEMs, and regulatory affairs directors at pigment suppliers underwrites the qualitative findings in this study. Primary interviews with distribution channel partners and technical R&D directors in surface functionalization chemistry were cross-referenced against customs and trade data, SEC 10-K pigment segment disclosures, and ECHA registration dossiers. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across the analysis window.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing dynamics and mix shifts toward higher-margin cosmetic grades. The analytical framework models crystalline phase, end-use industry, formulation format, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from production capacity expansion timelines correlated with downstream demand elasticity in coatings, cosmetics, and environmental remediation applications. Forecast inputs incorporate REACH annex revision implementation pace and SAMR nano-material labeling enforcement intensity.
The model holds under stable ilmenite concentrate pricing and sustained REACH compliance timelines; deviation in mineral sands supply disruptions or accelerated EFSA restrictions on food-grade nano-TiO2 would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Nanotools Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nanomaterial Supercapacitors Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Nanoparticle Contract Manufacturing Market
Nanomaterials
Global Nano Calcium Carbonate Market