
 Single-Walled Carbon Nanotube (SWCNT) Market | 2026-2036
Single-Walled Carbon Nanotube (SWCNT) Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Walled Carbon Nanotube (SWCNT) Market Analytics
Aftermarket service revenue for SWCNT dispersion optimization is narrowing as buyers shift toward vertically integrated suppliers. OCSiAl leverages captive synthesis capacity to control raw material quality from gas feedstock to purified nanotube. Thomas Swan & Co. Ltd. anchors European supply through specialized chemical vapor deposition reactors. NanoIntegris differentiates via semiconductor-grade sorting and chirality-selective separation for transistor applications.
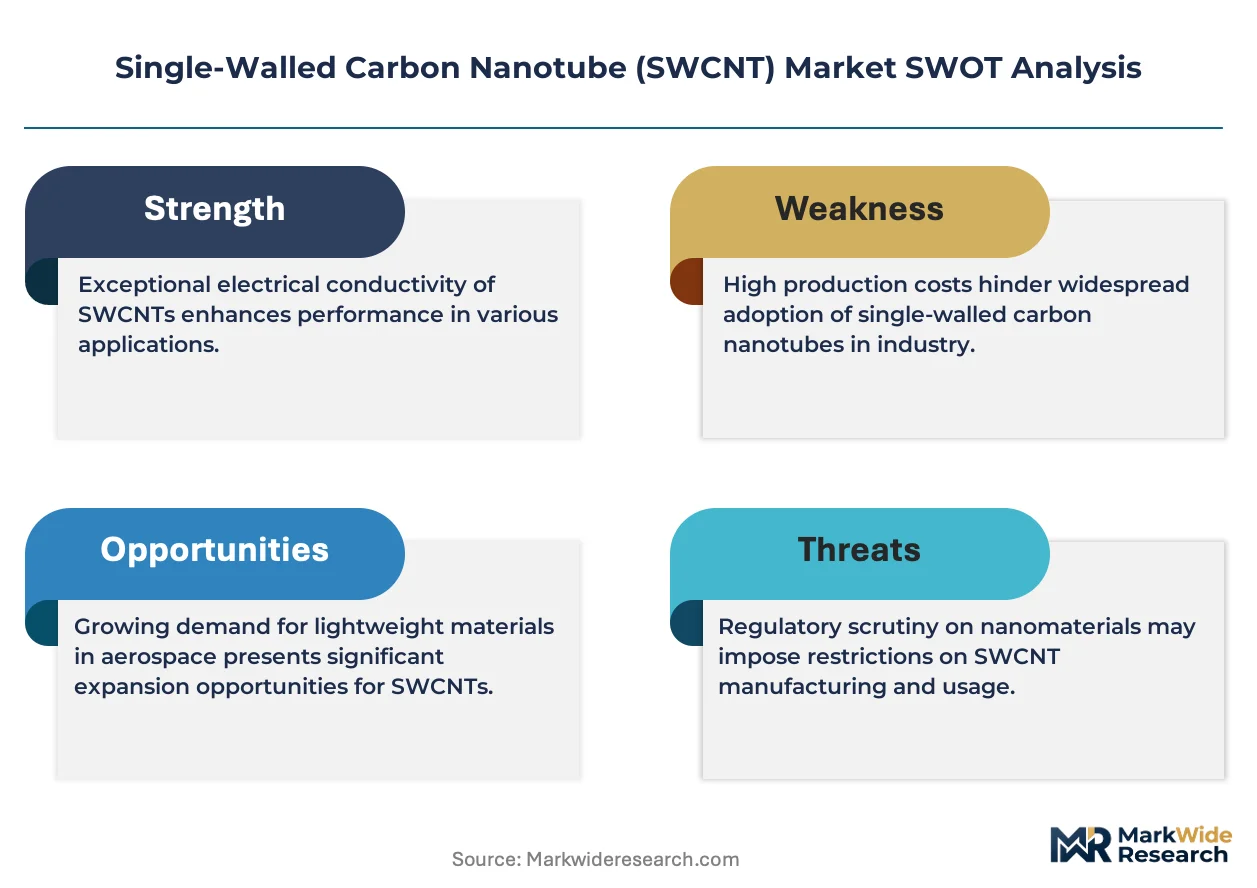
Single-walled carbon nanotubes are hollow cylindrical nanostructures composed of a single graphene sheet rolled into a seamless tube, typically one to two nanometers in diameter and several micrometers in length, produced via arc discharge, laser ablation, or catalytic chemical vapor deposition methods. Their exceptional electrical conductivity, tensile strength, and thermal stability position them as critical additives for next-generation conductors, structural composites, and targeted drug delivery vectors. Functionalized SWCNTs command premium positioning due to surface chemistry modifications that enable solvent compatibility and covalent bonding with polymer matrices. The electronics application segment sustains the largest volume commitment, while energy storage exhibits the steepest trajectory as solid-state battery developers specify SWCNTs for silicon-anode stabilization.
The US EPA oversees workplace exposure limits for engineered nanomaterials under the Toxic Substances Control Act, while REACH in Europe mandates registration and safety documentation for SWCNT imports above one ton annually. China's SAMR enforces GB standards for nanomaterial classification and labeling that affect both domestic production and export eligibility. ISO/TS 80004-3 provides terminology and measurement protocols that reduce technical friction in cross-border procurement. Stakeholders must monitor evolving classification thresholds that could resegment product tiers and redirect capital toward compliant synthesis infrastructure.
Market Dynamics
China's dual carbon goals and tightened emissions standards are forcing SWCNT manufacturers to reconfigure synthesis infrastructure around cleaner feedstock processing and closed-loop purification systems, compressing legacy capacity timelines.
Growth Catalysts
- Solid-state battery commercialization:Silicon-anode stabilization requirements from South Korean battery manufacturers are pulling high-purity SWCNT volumes into qualification programs.
- REACH registration thresholds:European mandates above one ton annually are filtering out non-compliant suppliers and consolidating import channels toward documented producers.
- Chirality-selective separation:Semiconductor-grade sorting breakthroughs are unlocking transistor applications previously blocked by metallic nanotube contamination.
Market Restraints
- Feedstock cost volatility:High-purity methane and ethylene prices fluctuate with regional natural gas markets, squeezing margin structures for non-integrated producers.
- East Asian supply concentration:Overreliance on Chinese carbon materials processing zones and South Korean battery gigafactories creates geographic vulnerability to trade policy shifts.
- Multi-walled carbon nanotube substitution:Lower-cost MWCNTs satisfy conductivity requirements in less demanding polymer composite applications.
Strategic Opportunities
- Indian PLI scheme alignment:Domestic battery cell manufacturing incentives are creating first-mover windows for localized SWCNT dispersion facilities.
- Functionalized surface chemistry:Covalent bonding modifications for solvent compatibility open pharmaceutical targeting and advanced composite matrices.
- ISO/TS 80004-3 harmonization:Standardized terminology and measurement protocols reduce technical friction in cross-border procurement for mid-tier buyers.
Industry Challenges
- Specialized reactor engineering talent:Chemical vapor deposition optimization requires rare combinations of catalysis expertise and nanomaterials handling certification.
- GB standards compliance timelines:China's SAMR labeling and classification requirements demand extended documentation cycles that delay export eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Walled Carbon Nanotube (SWCNT) Market |
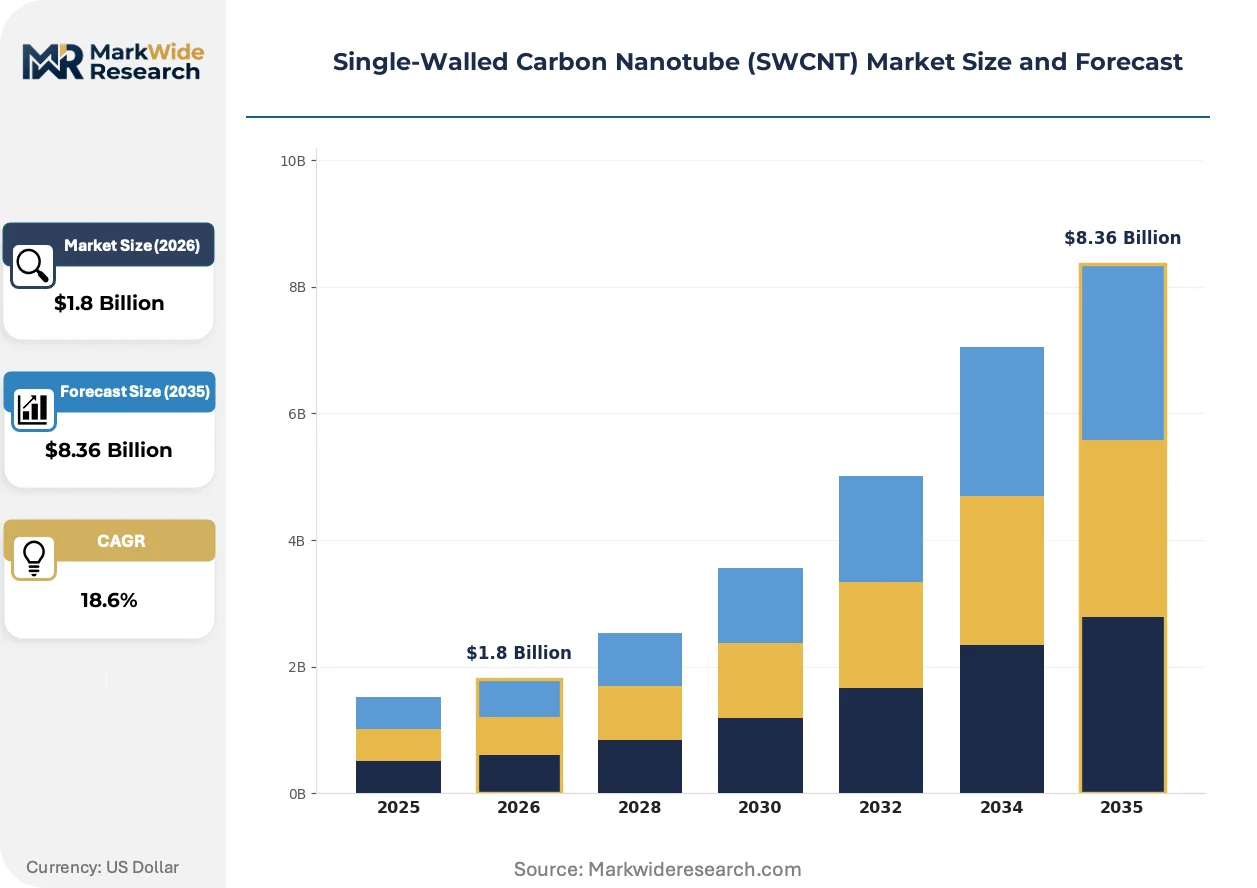
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Quality SWCNTs, Low-Quality SWCNTs, Functionalized SWCNTs, Superconducting SWCNTs Application: Electronics, Energy Storage, Composite Materials, Biomedical Delivery Mode: Suspension, Powder, Coating, Film Form End User: Aerospace, Automotive, Healthcare, Consumer Electronics |
| Companies Covered | NoPo Nanotechnologies, Klean Commodities, OCSiAl, ZEON CORPORATION, NanoIntegris, Carbon Solutions, Inc., CHASM Advanced Materials, Inc., Thomas Swan & Co. Ltd., Timesnano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Walled Carbon Nanotube (SWCNT) Market Evolving Landscape
Plasma-enhanced synthesis methods and automated chirality sorting are compressing production timelines while regulatory documentation requirements harden entry barriers for undifferentiated suppliers.
Continuous-flow plasma-enhanced chemical vapor deposition is rendering obsolete batch arc discharge methods for high-volume conductive additive production. Battery manufacturers in South Korea and China are qualifying plasma-synthesized material at 10x throughput rates. The technology is rendering obsolete capital-intensive legacy reactor footprints that cannot scale to gigafactory demand volumes.
REACH registration mandates above one ton annually are forcing importers to consolidate supplier relationships toward fully documented producers. European chemical distributors are dropping non-registered SWCNT lines from portfolios. Electronics applications with stringent traceability requirements are absorbing compliance premiums most readily.
Buyers are unbundling aftermarket dispersion optimization services from material supply contracts. Vertically integrated suppliers with captive synthesis-to-dispersion capability are capturing volume commitments previously fragmented across specialty chemical distributors. This pattern concentrates most visibly around Chinese carbon materials processing zones serving domestic battery cell manufacturers.
Single-Walled Carbon Nanotube (SWCNT) Market Segmentation
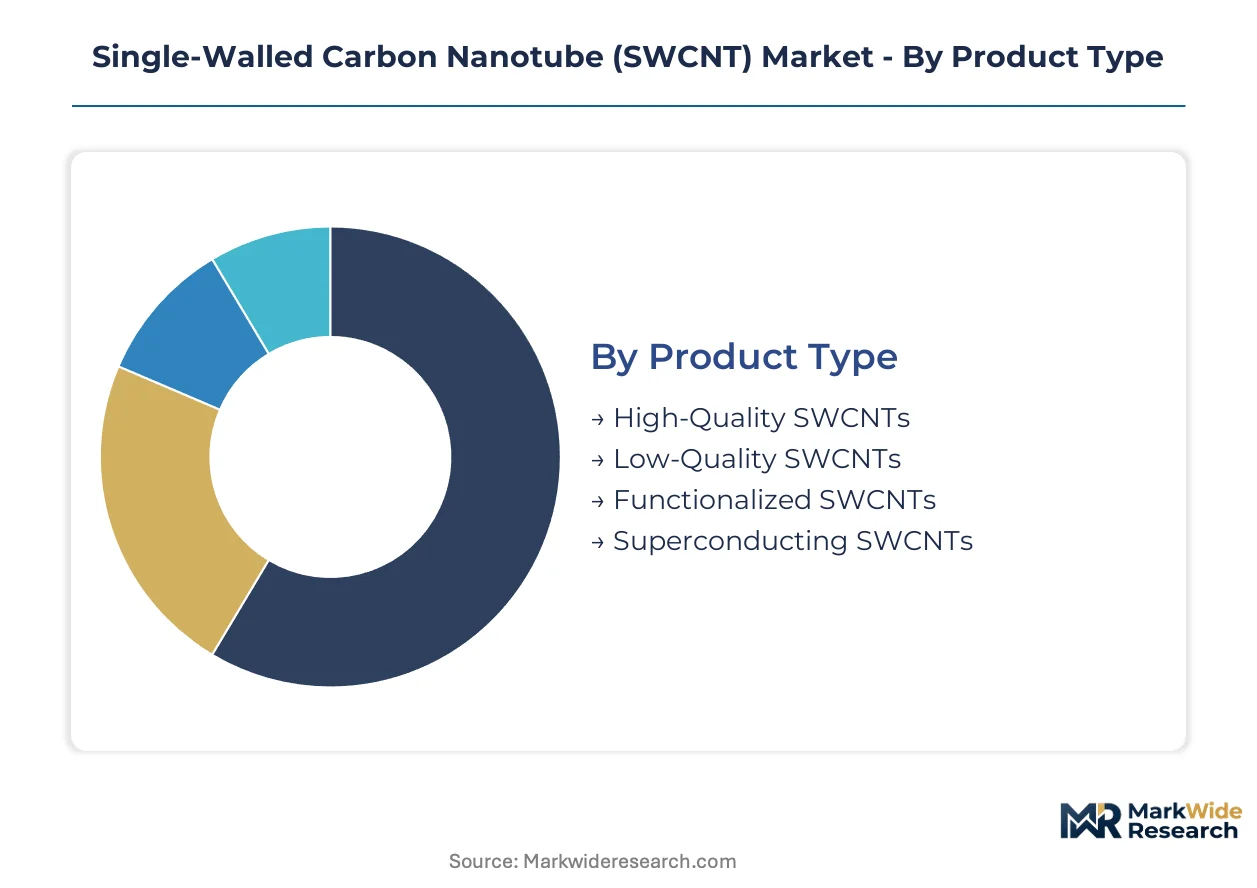
SWCNT procurement patterns diverge sharply by purity grade, functionalization state, and delivery format. Buyers in battery manufacturing and semiconductor fabrication impose distinct technical specifications that resegment supplier capabilities across value tiers.
Product Type:
High-purity grades command qualification-driven procurement cycles in semiconductor and solid-state battery applications, while functionalized variants unlock solvent compatibility for polymer integration.
- High-Quality SWCNTs:These materials exhibit metallic impurity levels below 1% and aspect ratios exceeding 1000:1, enabling percolation networks at sub-1% loading fractions. South Korean battery gigafactories specify these grades for silicon-anode conductive additives in next-generation cells. Synthesis via plasma-enhanced chemical vapor deposition dominates supply channels serving this tier.
- Functionalized SWCNTs:Surface modifications with carboxyl, hydroxyl, or amine groups transform hydrophobic nanotubes into dispersible building blocks for composite matrices. Pharmaceutical developers in Switzerland and Massachusetts utilize covalently functionalized variants for targeted drug delivery vector development. The chemistry determines solvent compatibility and interfacial bonding strength with host polymers.
- Low-Quality SWCNTs:Higher metallic content and broader diameter distributions suit cost-sensitive polymer composite applications where conductivity thresholds are modest.
- Superconducting SWCNTs:Chirality-sorted semiconducting fractions with specific (n,m) indices enable transistor channel materials and quantum device architectures.
Established volume favors High-Quality SWCNTs; emerging adoption favors Functionalized SWCNTs.
Application:
End-use requirements range from bulk conductive additives to precision electronic components, with qualification timelines spanning months to years.
- Electronics:Transistor channels, interconnects, and transparent conductors demand metallic/semiconducting separation at chirality-specific purity. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specify semiconductor-grade material for advanced node development. Metallic contamination above 0.01% degrades device on-off ratios below acceptable thresholds.
- Energy Storage:Silicon-anode stabilization in lithium-ion and solid-state configurations represents the steepest volume expansion trajectory. Chinese battery cell manufacturers and South Korean gigafactories are qualifying SWCNT conductive networks at 10x prior-year volumes. The material prevents electrode pulverization during lithiation cycles.
- Composite Materials:Structural reinforcement and electrical conductivity in aerospace-grade carbon fiber prepregs utilize dispersed SWCNT loadings of 0.1-0.5 wt%.
- Biomedical:Near-infrared imaging agents and photothermal therapy vectors exploit tunable optical absorption in functionalized nanotubes.
Electronics maintains the largest committed volume; Energy Storage climbs the fastest.
Delivery Mode:
Physical form factors determine dispersion efficiency, handling safety, and integration protocols across manufacturing environments.
- Suspension:Pre-dispersed aqueous or organic solvent formulations eliminate agglomeration risks during customer processing. German automotive suppliers and Japanese electronics assemblers prefer N-methyl-2-pyrrolidone suspensions for direct coating integration. Stability against re-agglomeration determines shelf life and shipping constraints.
- Powder:Lyophilized or spray-dried formats minimize transportation costs and enable custom dispersion protocols at point of use. Chinese carbon materials processing zones and Indian battery component startups source powder for in-house formulation development. Dust exposure controls dominate workplace safety requirements.
- Coating:Ready-to-apply conductive layers on copper or aluminum current collectors streamline electrode manufacturing for battery producers.
- Film Form:Free-standing buckypaper and transferred CVD films enable flexible electronics prototyping and sensor development.
Powder dominates raw material procurement; Suspension gains share in qualified supply chains.
End User:
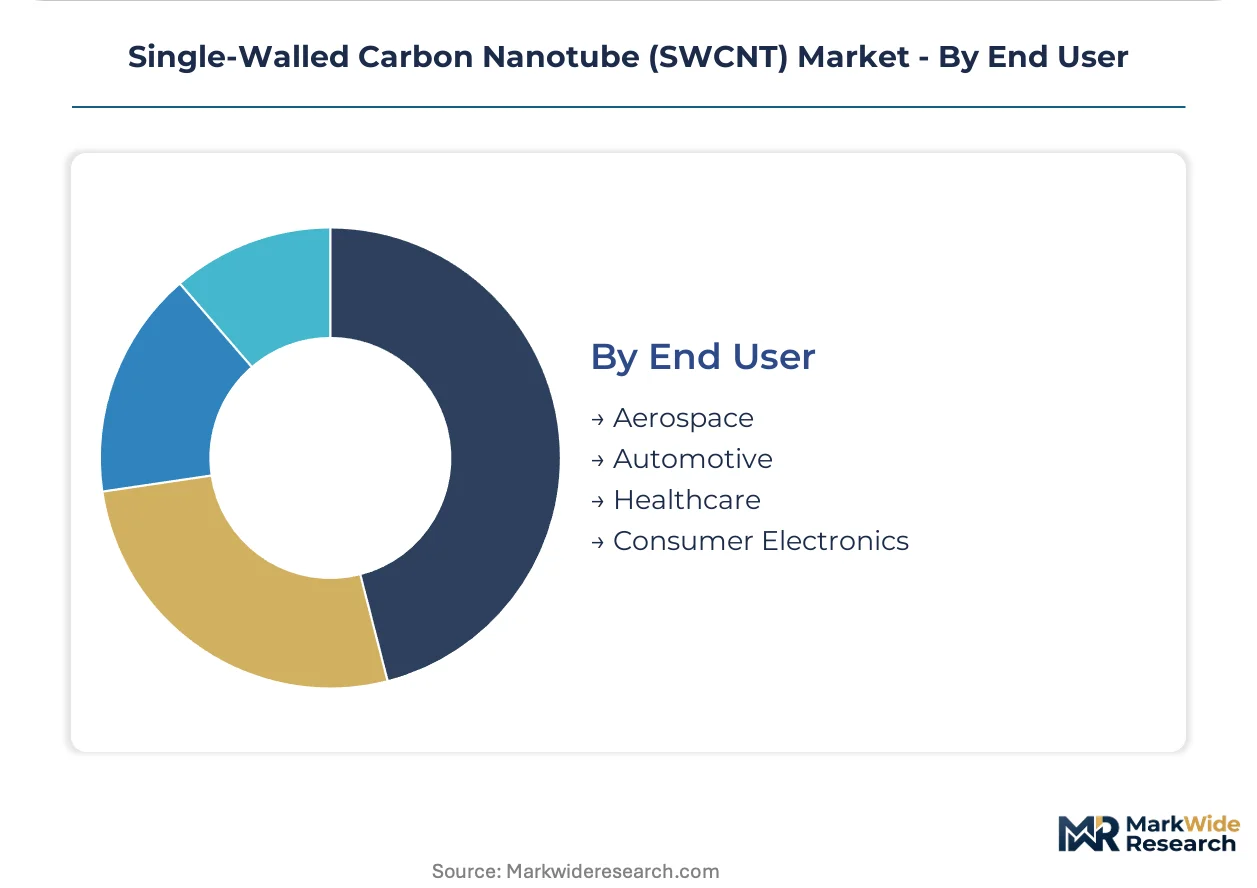
Industry-specific certification requirements and performance thresholds fragment demand across aerospace-grade, automotive-volume, and healthcare-regulated channels.
- Automotive:Electric vehicle battery packs and lightweight structural components drive specification of conductive additives and reinforced polymers. Tesla's Nevada gigafactory and BYD's Shenzhen operations qualify SWCNT suppliers against automotive-grade traceability standards. Thermal management films and EMI shielding applications expand addressable content per vehicle.
- Healthcare:FDA and EMA pathways for nanomaterial-based therapeutics impose extensive toxicology and biodistribution documentation. Boston and Basel pharmaceutical clusters pursue functionalized variants for imaging contrast and targeted delivery. Regulatory clarity remains incomplete for long-term tissue retention profiles.
- Aerospace:Lightning strike protection and structural health monitoring in Boeing and Airbus composite airframes utilize conductive network integration.
- Consumer Electronics:Flexible display interconnects and thermal interface materials in smartphone and wearable devices specify thin-film formats.
Automotive pulls the highest volume commitment; Healthcare carries the longest development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys SWCNTs primarily as battery conductive additives at massive scale, while the United States channels material toward semiconductor-grade chirality sorting and pharmaceutical functionalization. South Korea concentrates on silicon-anode stabilization for next-generation cells. Germany and Japan pursue divergent paths: precision electronics versus automotive thermal management.
China
Battery gigafactories in Shenzhen and Ningde absorb high-purity SWCNT volumes for silicon-anode conductive networks. SAMR enforces GB standards for nanomaterial classification that compress export eligibility timelines. Carbon materials processing zones in Jiangsu and Shandong provinces are reconfiguring synthesis infrastructure around closed-loop purification systems to meet dual carbon goals.
United States
Semiconductor foundries and pharmaceutical developers in Massachusetts and California specify chirality-sorted and functionalized grades. EPA oversees workplace exposure limits under the Toxic Substances Control Act. Boston and San Francisco Bay Area clusters are driving qualification programs for transistor channel materials and targeted drug delivery vectors.
South Korea
Battery manufacturers in Gyeonggi Province and Ulsan are pulling SWCNT volumes into solid-state cell qualification at 10x prior-year rates. MFDS maintains oversight of nanomaterial safety documentation for biomedical applications. The Seoul Capital Area anchors demand concentration as LG Energy Solution and Samsung SDI expand silicon-anode pilot lines.
Germany
Automotive suppliers and electronics assemblers in Bavaria and Baden-Württemberg prefer pre-dispersed suspensions for direct coating integration. REACH mandates above one ton annually filter supplier relationships toward fully documented producers. The Eindhoven-adjacent corridor and Rhine-Main region are consolidating procurement channels around compliant importers.
Japan
Electronics manufacturers in Kanto and semiconductor equipment builders in Kyushu specify metallic/semiconducting separation at sub-0.01% contamination thresholds. METI coordinates national nanomaterial strategy with JIS standards alignment. The Osaka-Kobe industrial zone is qualifying SWCNT thermal interface materials for next-generation consumer devices.
Single-Walled Carbon Nanotube (SWCNT) Market Competitive Landscape
Capability concentration sits with specialized synthesis and sorting technology holders; scale advantage sits with integrated suppliers controlling feedstock through dispersion. The vendor base organizes into three tiers: captive-integrated producers, regional synthesis specialists, and distribution-dependent importers. Dominant competitive moves include backward integration into gas feedstock processing and technology licensing for plasma-enhanced reactor deployment.
Within the captive-integrated tier, OCSiAl and Thomas Swan & Co. Ltd. occupy positions that exemplify upstream control strategies. OCSiAl represents the scale-driven archetype with synthesis-to-dispersion capability spanning gas feedstock to purified nanotube. Thomas Swan anchors European supply through specialized chemical vapor deposition reactor capacity. NanoIntegris sits within the precision-sorting specialist category, exemplifying semiconductor-grade chirality-selective separation for transistor applications.
| Leading Market Players |
|---|
| NoPo Nanotechnologies |
| Klean Commodities |
| OCSiAl |
| ZEON CORPORATION |
| NanoIntegris |
| Carbon Solutions, Inc. |
| CHASM Advanced Materials, Inc. |
| Thomas Swan & Co. Ltd. |
| Timesnano |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Busan maritime corridors carry high-purity SWCNT feedstocks at freight rates that amplify the cost advantage of integrated Chinese producers over European dispersion specialists, compressing margins for non-captive suppliers while enabling tiered pricing stratification across battery-grade and semiconductor-grade material streams.
Pricing Analysis
Long-term offtake contracts dominate procurement between South Korean battery gigafactories and plasma-enhanced CVD producers, locking in volume commitments that insulate qualified suppliers from spot methane price volatility. Price differentiation hinges on metallic impurity thresholds and SAMR export certification status, with REACH-registered European channels absorbing compliance premiums. Cost compression in standard-grade powder formats is intensifying as Chinese carbon materials processing zones expand captive synthesis capacity. Automotive battery manufacturers exhibit highest price sensitivity due to gigascale volume requirements, while semiconductor foundries prioritize chirality purity over unit economics.
Supply Chain Analysis
High-purity methane and ethylene feedstock sourcing draws from regional natural gas markets in China, the United States, and Qatar, with catalytic precursor synthesis concentrated in Jiangsu province processing zones. Chemical vapor deposition reactor components, specialized chirality-sorting equipment, and gas purification membranes constitute critical input dependencies. Single-source vulnerability sits with South Korean battery cell manufacturers relying on qualified Chinese SWCNT suppliers under shifting trade policy frameworks. Distribution runs through vertically integrated producers with captive dispersion capability, bypassing specialty chemical distributors that previously intermediated aftermarket formulation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough as solid-state battery commercialization pulls material through qualification pipelines, with silicon-anode stabilization requirements from South Korean manufacturers serving as the primary cyclical driver resetting demand baselines.
For Market Incumbents: Pre-empt multi-walled carbon nanotube substitution threats in polymer composite applications by accelerating functionalized surface chemistry development for pharmaceutical and aerospace channels. Deepen backward integration into gas feedstock processing to defend margin structures against methane price volatility, while securing SAMR pre-registration documentation to compress export eligibility timelines for Chinese carbon materials processing zones. For New Entrants and Emerging Players: Establish a beachhead in Indian PLI-aligned battery component manufacturing by deploying localized dispersion facilities serving domestic cell producers qualifying silicon-anode conductive networks. Target pharmaceutical functionalization partnerships in Boston and Basel clusters where FDA and EMA pathway expertise creates barriers to incumbent chemical suppliers lacking nanomaterial toxicology documentation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant SWCNT synthesis assets stranded by REACH registration thresholds, particularly European producers lacking captive plasma-enhanced CVD scale. Monitor qualification volume commitments from South Korean solid-state battery pilot lines as the inflection signal separating commodity-grade from semiconductor-grade supplier viability across the five-to-ten year investment window.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Enhanced Reactor Scale-Up | 10x throughput gains compress capital intensity for battery-grade material supply to LG Energy Solution and Samsung SDI. |
| REACH Registration Completion | Full ECHA documentation unlocks European electronics procurement channels previously filtered toward compliant importers. |
| Chirality-Sorting Technology Licensing | Semiconductor-grade separation capability transfers to Taiwan Semiconductor Manufacturing Company for advanced node transistor development. |
| Backward Integration into Feedstock Processing | Captive methane purification insulates OCSiAl and Thomas Swan from regional natural gas price volatility squeezing non-integrated competitors. |
| Functionalized Surface Chemistry Partnerships | Covalent bonding modifications enable Swiss pharmaceutical developers to advance targeted drug delivery vector programs. |
Research Methodology
The analysis maps high-purity SWCNTs, functionalized variants, low-quality grades, and superconducting chirality-sorted fractions, each validated through synthesis plant managers, battery cell procurement leads at South Korean gigafactories, semiconductor foundry materials engineers, and pharmaceutical formulation specialists. Primary interview intelligence triangulates against customs trade data, SEC filings from publicly traded chemical producers, SAMR nanomaterial registration databases, and IEA energy storage deployment reports. Bottom-up volume modeling from individual reactor capacity disclosures reconciles with top-down demand aggregation across electronics, energy storage, and biomedical application segments.
Assumptions around plasma-enhanced CVD adoption curves, solid-state battery commercialization timelines, and REACH enforcement stringency were held fixed while varying silicon-anode loading fractions, regional trade policy scenarios, and feedstock cost trajectories across the projection horizon. Segmentation dimensions modeled include purity grade tier, functionalization state, delivery format, end-use industry, and regional regulatory cluster. CAGRs derive from fitted adoption curves weighted by qualification pipeline visibility, with forecast inputs anchored in South Korean battery manufacturer capacity expansion disclosures and Chinese dual carbon policy implementation tracking.
Stress conditions across methane price volatility bands, trade restriction scenarios, and semiconductor-grade yield improvement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with revision triggers including SAMR classification threshold changes, MFDS nanomaterial safety documentation updates, and breakthroughs in metallic nanotube separation efficiency. Cross-checking against IEA battery supply chain assessments and ECHA registration volume disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Nanoparticle Contract Manufacturing Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market