
 Nanomaterials for Printing Market | 2026-2036
Nanomaterials for Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Nanomaterials for Printing Market Foresight
Flexible electronics demand is restructuring procurement patterns across the nanomaterials for printing value chain. BASF SE leverages its pigment synthesis heritage to dominate high-purity metal nanoparticle supply for inkjet conductors. Evonik Industries AG specializes in organosilica nanocomposites that sustain premium positioning in barrier coatings for food packaging. Novacentrix anchors North American supply of photonic-curing systems, a critical enabler for roll-to-roll printed electronics manufacturing.
Nanomaterials for printing comprise engineered particles with at least one dimension below 100 nanometers, formulated into inks, pastes, or suspensions for deposition via screen, inkjet, or gravure processes; metal nanoparticles achieve bulk conductivity at sintering temperatures below 150°C, enabling polymer substrate compatibility. Ink formulations containing silver and copper nanoparticles occupy the largest revenue pool due to entrenched use in RFID antennas and touch-screen electrodes, while quantum dot dispersions for display backlights command the fastest expansion trajectory as QD-OLED penetration deepens. Powder and suspension forms retain cost advantages in thick-film ceramic and photovoltaic metallization applications where precision deposition matters less than material throughput.
EPA oversight of volatile organic compound emissions in the United States constrains solvent selection for nano-ink carriers, pushing formulators toward water-based and UV-curable systems. REACH registration requirements in Europe mandate toxicity dossiers for nanoscale substances above one ton annual volume, raising compliance costs for imported metal oxide and carbon nanotube dispersions. Stakeholders must monitor evolving definitions of "nanomaterial" under OECD guidance, as threshold changes would trigger additional labeling and safety-testing obligations across multiple jurisdictions.
Market Dynamics
Roll-to-roll manufacturing scale-up across East Asian flexible electronics clusters is compressing sintering temperature requirements and forcing nano-ink formulators to redesign particle surface chemistries for polymer substrate compatibility.
Growth Catalysts
- REACH nanomaterial registration thresholds:ECHA's evolving dossier requirements above one-ton annual volumes are accelerating compliant water-based dispersion development for European food packaging printers.
- RFID antenna metallization:Silver nanoparticle inks sustain entrenched demand from logistics and retail asset-tracking applications requiring sub-150°C processing temperatures.
- Pearl River Delta cluster concentration:China's printed sensor manufacturing expansion is pulling conductive nano-ink procurement toward Shenzhen and Dongguan production hubs.
Market Restraints
- Silver price volatility:Precious metal cost fluctuations in conductive ink formulations constrain margin predictability for high-volume RFID and touch-electrode applications.
- Solvent carrier restrictions:EPA volatile organic compound emission limits in the United States are eliminating conventional solvent systems faster than water-based alternatives achieve equivalent dispersion stability.
- Photonic-curing equipment concentration:North American supply dominance of pulsed-light sintering systems creates geographic dependency for roll-to-roll production lines.
Strategic Opportunities
- Quantum dot display backlights:QD-OLED penetration in premium television panels is opening fastest-expansion trajectories for cadmium-free quantum dot dispersion suppliers.
- UV-curable nano-ink platforms:Regulatory pressure on solvent systems is creating white space for energy-curable formulations in North American packaging printing.
- Photovoltaic metallization:Thick-film silver pastes with engineered particle size distributions are capturing cost-sensitive solar cell manufacturing outside precision inkjet applications.
Industry Challenges
- Nanotoxicology assessment capacity:REACH-compliant toxicity dossier preparation requires scarce regulatory toxicology expertise for metal oxide and carbon nanotube submissions.
- Sintering temperature-process window mismatch:Balancing electrical conductivity targets against heat-sensitive polymer substrate limits demands iterative particle surface engineering cycles.
- ISO nanomaterial definition alignment:Evolving OECD threshold criteria for particle size distributions threaten to trigger relabeling and retesting obligations across multiple jurisdiction compliance programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanomaterials for Printing Market |
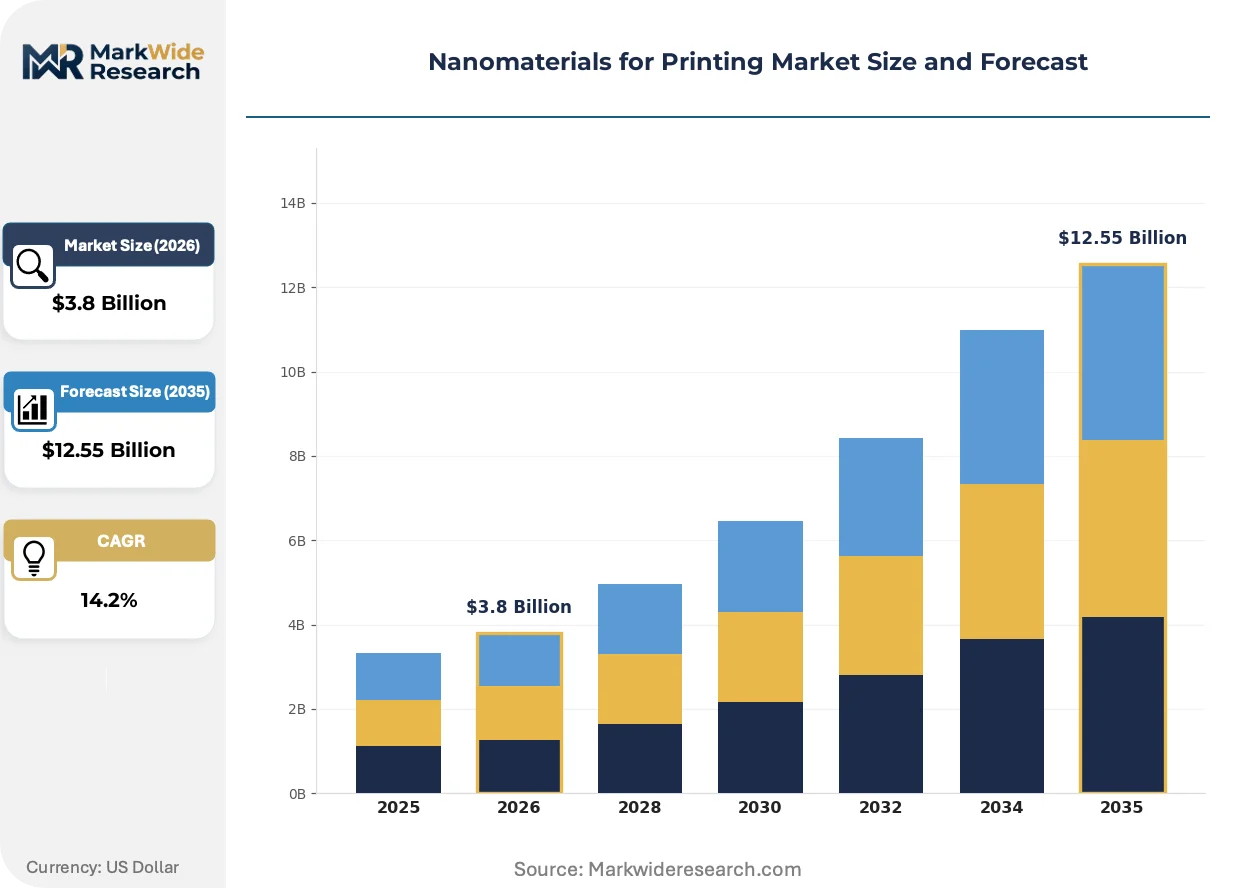
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Quantum Dots, Nanotubes, Graphene, Metal Nanoparticles Application: Electronics, Photovoltaics, Packaging, Coatings Form: Powder, Ink, Paste, Suspension End User: Manufacturing, Automotive, Healthcare, Aerospace |
| Companies Covered | BASF SE, Evonik Industries AG, Merck KGaA, Cabot Corporation, DuPont, Clariant International, American Elements, Novacentrix, Sun Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanomaterials for Printing Market Shifts & Advancements
Photonic curing systems are compressing thermal processing timelines while water-based carrier systems displace solvent platforms under regulatory pressure. These shifts are restructuring equipment procurement and formulation R&D priorities simultaneously.
Photonic sintering technology is integrating pulsed-light energy delivery to achieve metal nanoparticle densification in milliseconds without substrate thermal damage. Flexible electronics manufacturers in South Korea and Taiwan are retrofitting roll-to-roll lines with these systems to maintain PET and PEN film integrity. The technology is integrating conductive trace formation into high-speed manufacturing workflows previously constrained by oven-based thermal bottlenecks.
REACH authorization requirements for nanoscale substances are forcing imported dispersion suppliers to establish European legal entities or partner with registered importers. The industrial consequence is a compliance cost barrier that favors larger chemical conglomerates with established ECHA liaison capabilities. Specialty ink formulators serving German and French packaging printers are consolidating supplier relationships to reduce registration burden duplication.
Specification-driven procurement is consolidating nano-ink purchasing decisions at the flexible electronics OEM level rather than delegating to contract converters. Tier-one display and sensor manufacturers in Japan are imposing particle size distribution and batch consistency standards that eliminate spot-market sourcing. This concentration is most visible in the Kansai region where printed electronics supply chains have integrated backward into captive nano-dispersion blending operations.
Nanomaterials for Printing Market Segmentation
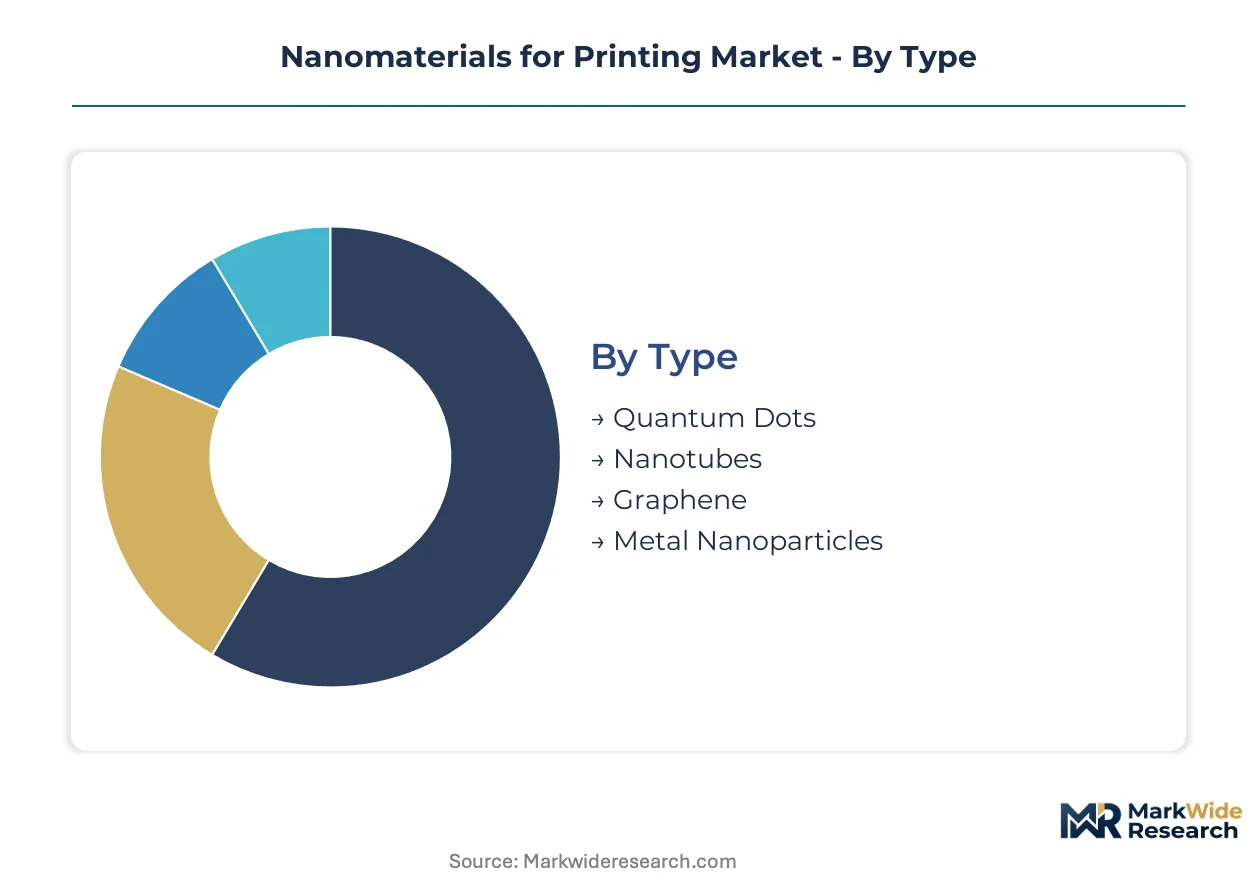
Segmentation in nanomaterials for printing reveals how material properties, application requirements, and processing constraints intersect to determine procurement priorities. Each dimension carries distinct supply chain implications for formulators and end-users navigating regulatory and performance trade-offs.
Type:
Supply concentration in metal nanoparticle production dominates current revenue pools, with specialized synthesis capabilities determining competitive positioning across material categories.
- Metal Nanoparticles:Silver and copper formulations achieve bulk conductivity below 150°C sintering thresholds, enabling polymer substrate compatibility for RFID antennas and touch-screen electrodes. Demand concentrates in China's Pearl River Delta cluster where printed sensor manufacturing has intensified, though silver price volatility constrains margin predictability for high-volume applications.
- Quantum Dots:Cadmium-free dispersions for display backlights command premium positioning as QD-OLED penetration deepens in premium television panels. South Korean and Taiwanese display manufacturers are driving fastest-expansion trajectories for this segment through specification-driven procurement that eliminates spot-market sourcing.
- Graphene:Two-dimensional carbon structures offer mechanical flexibility and thermal conductivity for emerging printed electronics applications.
- Nanotubes:Carbon nanotube dispersions face REACH registration burden duplication for European market access, favoring larger chemical conglomerates with established ECHA liaison capabilities.
Today's leader: Metal Nanoparticles. Tomorrow's challenger: Quantum Dots.
Application:
Application-driven procurement reflects divergent performance requirements across precision electronics and cost-sensitive industrial coating markets.
- Electronics:Flexible printed circuit and sensor applications demand sub-100-nanometer particle size distributions with batch consistency standards that tier-one Japanese manufacturers impose at the OEM level. Roll-to-roll manufacturing scale-up across East Asian clusters is compressing sintering temperature requirements and forcing nano-ink formulators to redesign particle surface chemistries.
- Photovoltaics:Thick-film silver pastes with engineered particle size distributions capture cost-sensitive solar cell manufacturing where precision inkjet deposition matters less than material throughput.
- Packaging:Barrier coating applications for food packaging in Europe accelerate compliant water-based dispersion development under ECHA's evolving dossier requirements.
- Coatings:Functional surface treatments for industrial substrates leverage powder and suspension cost advantages where deposition precision is secondary to coverage economics.
Electronics commands current premium positioning. Photovoltaics offers steepest volume expansion trajectory as solar manufacturing scales.
Form:
Form selection directly determines equipment compatibility and regulatory compliance pathways for deposition processes.
- Ink:Inkjet-compatible nano-dispersions require stringent viscosity and surface tension control for precision deposition in flexible electronics manufacturing. EPA volatile organic compound emission limits in the United States are pushing formulators toward water-based and UV-curable carrier systems faster than equivalent dispersion stability can be achieved.
- Paste:Screen-printable formulations with higher solids loading serve thick-film applications in photovoltaic metallization and ceramic substrates.
- Powder:Dry particulate forms retain cost advantages in high-throughput industrial coating applications where precision matters less than material economics.
- Suspension:Liquid-stable dispersions for gravure and flexographic printing face solvent carrier restrictions that favor water-based alternatives in North American packaging markets.
Ink formulations attract maximum R&D investment. Suspension platforms gain regulatory-driven momentum.
End User:
End-user verticals impose distinct certification and performance specifications that reshape supplier relationships.
- Manufacturing:Flexible electronics producers in Japan's Kansai region have integrated backward into captive nano-dispersion blending operations to enforce particle size distribution and batch consistency standards. Specification-driven procurement consolidates purchasing decisions at the OEM level rather than delegating to contract converters.
- Automotive:Printed sensor applications for vehicle electronics require thermal stability and reliability validation that extend qualification timelines.
- Healthcare:Medical device printing applications face toxicity dossier requirements for nanoscale substances above one-ton annual volumes under REACH, raising compliance costs for imported metal oxide dispersions.
- Aerospace:Lightweight conductive traces for avionics systems demand performance verification under extreme environmental conditions.
Manufacturing dominates procurement volume. Healthcare presents highest regulatory barrier to entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta cluster anchors procurement gravity for conductive nano-inks, pulling formulation suppliers toward Shenzhen and Dongguan production hubs where printed sensor manufacturing has intensified.
China
Flexible electronics OEMs in Shenzhen impose specification-driven procurement that eliminates spot-market sourcing for nano-dispersions. MIIT's evolving GB standards for nanomaterial classification threaten additional labeling obligations for imported metal oxide formulations. Dongguan's roll-to-roll manufacturing scale-up is compressing sintering temperature requirements and forcing particle surface chemistry redesigns.
United States
EPA volatile organic compound emission limits are eliminating conventional solvent systems faster than water-based alternatives achieve equivalent dispersion stability. Novacentrix anchors North American supply of photonic-curing systems for roll-to-roll printed electronics manufacturing. The Southeast's emerging flexible electronics corridor is retrofitting production lines with pulsed-light sintering technology.
Germany
REACH registration requirements mandate toxicity dossiers for nanoscale substances above one-ton annual volumes, raising compliance costs for imported carbon nanotube dispersions. ECHA's evolving dossier requirements are accelerating compliant water-based dispersion development for food packaging printers. BASF SE leverages its Ludwigshafen pigment synthesis heritage to dominate high-purity metal nanoparticle supply for inkjet conductors.
Japan
Tier-one display manufacturers in the Kansai region impose particle size distribution and batch consistency standards that have driven backward integration into captive nano-dispersion blending operations. METI's oversight of industrial chemical safety aligns with OECD threshold criteria evolution for nanomaterial definitions. Osaka's printed electronics supply chains now source internally for critical nano-ink formulations.
South Korea
QD-OLED penetration in premium television panels is opening fastest-expansion trajectories for cadmium-free quantum dot dispersion suppliers. MFDS regulates nanomaterial safety in consumer electronics applications with reference to ISO guidance. Seoul-based display manufacturers are driving specification-driven procurement that consolidates purchasing decisions at the OEM level.
Nanomaterials for Printing Market Competitive Landscape
Backward integration into captive nano-dispersion production dominates the current landscape as tier-one OEMs enforce specification-driven procurement. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with ECHA liaison capabilities, specialized nano-ink formulators serving regional packaging printers, and equipment-integrated solution providers. M&A activity concentrates among REACH-compliant dispersion suppliers seeking European legal entity status. Technology licensing partnerships between photonic-curing system developers and roll-to-roll equipment manufacturers are restructuring equipment procurement priorities.
Among German chemical conglomerates, BASF SE and Evonik Industries AG exemplify the diversified archetype with established regulatory compliance infrastructure. Novacentrix occupies a distinctive position as a North American equipment-integrated specialist. These three anchors illustrate how geographic regulatory exposure and manufacturing technology integration determine competitive positioning across formulation and equipment segments.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Merck KGaA |
| Cabot Corporation |
| DuPont |
| Clariant International |
| American Elements |
| Novacentrix |
| Sun Chemical |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty chemical producers now control significant nano-ink formulation capacity, compressing working-capital cycles and enforcing stricter volume-commitment pricing on flexible electronics OEMs across East Asian manufacturing clusters.
Pricing Analysis
Distributor margins on conductive nano-inks typically range between 15-22 percent, though direct-to-OEM procurement by tier-one Japanese display manufacturers commands 8-12 point discounts through annual volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered European formulations from spot-market Asian imports and commodity thick-film pastes. Pricing pressure stems from silver nanoparticle cost volatility, which squeezes margin predictability for RFID antenna applications. Contract converters serving logistics and retail asset-tracking segments exhibit highest price sensitivity, while specification-driven OEMs in South Korea's QD-OLED supply chain accept premium positioning for cadmium-free quantum dot dispersions.
Supply Chain Analysis
Domestic-content mandates under China's MIIT GB standards are reshaping sourcing patterns, forcing imported metal oxide dispersion suppliers to establish local blending operations or cede procurement share to indigenous competitors. Supply concentrates in China, Germany, and Japan, with raw material dependencies spanning silver bullion markets, organosilica precursors, and photoinitiator chemicals. Single-source vulnerability characterizes North American photonic-curing equipment, where Novacentrix maintains effective supply dominance for pulsed-light sintering systems. Distribution runs through authorized chemical distributors in Europe, direct mill relationships in East Asia, and integrated captive supply for Japan's Kansai-region OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nanomaterials for printing offers margin-expansion potential as water-based formulation platforms displace solvent systems, reducing regulatory compliance costs while enabling premium positioning in European food packaging applications.
For Market Incumbents: Anticipate REACH authorization threshold reductions by consolidating ECHA liaison capabilities and preemptively registering nanoscale substances above 100 kilogram annual volumes. BASF SE and Evonik Industries AG demonstrate how Ludwigshafen-based pigment synthesis heritage translates into defensive positioning against emerging Asian competitors. Capacity addition in China's Pearl River Delta, rather than European expansion, captures procurement gravity as Dongguan roll-to-roll manufacturing scales. For New Entrants and Emerging Players: The 40-60 percent price-point gap between premium REACH-compliant European formulations and economy-tier Chinese imports creates white-space opportunity for mid-tier UV-curable nano-ink platforms. North American packaging printers facing EPA volatile organic compound limits represent the most penetrable buyer segment, with regulatory-compliant water-based dispersions as the specific go-to-market angle. Photovoltaic metallization applications outside precision inkjet deposition offer volume traction without tier-one OEM qualification barriers. For Investors and Strategic Acquirers: Chemical conglomerates with established ECHA compliance infrastructure are the most active acquirer in this space, targeting REACH-registered dispersion suppliers to secure European legal entity status. Long-term viability hinges on quantum dot display backlight penetration and printed sensor manufacturing expansion in East Asian clusters. The signal to watch is specification-driven procurement consolidation at flexible electronics OEMs, which eliminates spot-market sourcing and favors integrated formulation-equipment solution providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nano-Dispersion Production | Captive supply secures particle size distribution control for tier-one Japanese OEMs in Kansai. |
| REACH-Compliant Water-Based Formulation Development | ECHA dossier alignment opens European food packaging procurement for compliant suppliers. |
| Photonic-Curing Equipment Retrofit Programs | Pulsed-light sintering integration enables PET substrate compatibility in South Korean roll-to-roll lines. |
| Cadmium-Free Quantum Dot Dispersion Scale-Up | MFDS-aligned cadmium-free platforms capture QD-OLED specification requirements from Seoul-based manufacturers. |
| Regional Legal Entity Establishment | MIIT GB standard compliance requires Chinese legal presence for imported metal oxide formulations. |
Research Methodology
Multiple input streams — technical interviews with nano-ink formulators and photonic-curing equipment developers, procurement discussions with flexible electronics OEMs, and regulatory filings with ECHA and EPA — were reconciled against trade flow data and chemical industry association reports. Primary engagement spanned R&D directors at German chemical conglomerates, plant managers at Shenzhen-based roll-to-roll facilities, and regulatory affairs leads navigating REACH nanomaterial thresholds. Secondary validation drew from SEC 10-K filings, Cefic specialty chemicals reports, and customs documentation of silver nanoparticle trade flows. Bottom-up volume modeling across formulation types was cross-checked against top-down market sizing from equipment installation records.
Historical capacity utilization patterns were cross-referenced against expert panel input on sintering temperature reduction timelines and quantum dot display penetration assumptions across the analysis window. Segmentation modeling incorporated material type, application end-use, formulation form, and regional regulatory cluster dimensions. CAGRs were derived from iterative reconciliation of equipment procurement forecasts, OEM production ramp schedules, and nano-ink consumption intensity metrics per square meter of printed electronics output.
Caveats apply where ECHA nanomaterial definition revisions or EPA volatile organic compound threshold adjustments could materially shift the outlook for solvent-based formulation viability. Forecasts embed assumptions regarding silver price stability, photonic-curing equipment deployment rates, and specification-driven procurement consolidation trajectories. A small set of triggers — REACH authorization scope expansion, MIIT GB standard enforcement timing, and QD-OLED manufacturing yield improvements — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Single-Walled Carbon Nanotube (SWCNT) Market
Nanomaterials
Nanotools Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Nanomaterial Supercapacitors Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Nanomaterials Market