
 Nano Healthcare Technology for Medical Equipment Market | 2026-2036
Nano Healthcare Technology for Medical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Healthcare Technology for Medical Equipment Market Foresight
Market Context with Strategic Players
The capital-intensity divergence between integrated device manufacturers and component specialists is reorganizing competitive tiers in nano-enabled medical equipment. Medtronic leverages captive nanomaterial sourcing and in-house cleanroom fabrication to sustain premium positioning across cardiac and neurological implant lines. Stryker anchors its orthobiologics portfolio through controlled hydroxyapatite nanoparticle synthesis, while Smith & Nephew PLC competes via surface-modified antimicrobial coatings for wound closure and arthroscopy applications.
Technical Definition and Structural Segments
Nano healthcare technology for medical equipment encompasses engineered structures with at least one dimension between one and one hundred nanometers, deployed in devices that exploit quantum-scale surface-area effects for enhanced sensitivity, targeted bioavailability, or improved biocompatibility. Drug Delivery Systems command the deepest margin pools as liposomal and polymeric nanoparticle platforms require specialized formulation expertise and extended regulatory validation, while Nano Sensors expand fastest in point-of-care glucose and cardiac biomarker monitoring where miniaturization directly reduces reagent volumes and test turnaround. Diagnostic Tools occupy a mature revenue position in centralized hospital laboratories, though Imaging Devices incorporating quantum dots and gold nanorods are displacing conventional contrast agents in oncology and interventional radiology workflows.
Regulatory Frame and Forward-Looking Close
The FDA's 510(k) and PMA pathways, the EU MDR's classification rules for nanomaterial-containing devices, and ISO 10993 biocompatibility standards collectively shape product development timelines and market access costs for manufacturers targeting transatlantic distribution. EMA's nanomedicine reflection papers and the FDA's emerging technology program create divergent evidentiary requirements that favor firms with dedicated regulatory affairs capacity across both jurisdictions. Stakeholders must monitor how evolving characterization standards for nanoscale impurities influence batch-release protocols and supplier qualification criteria.
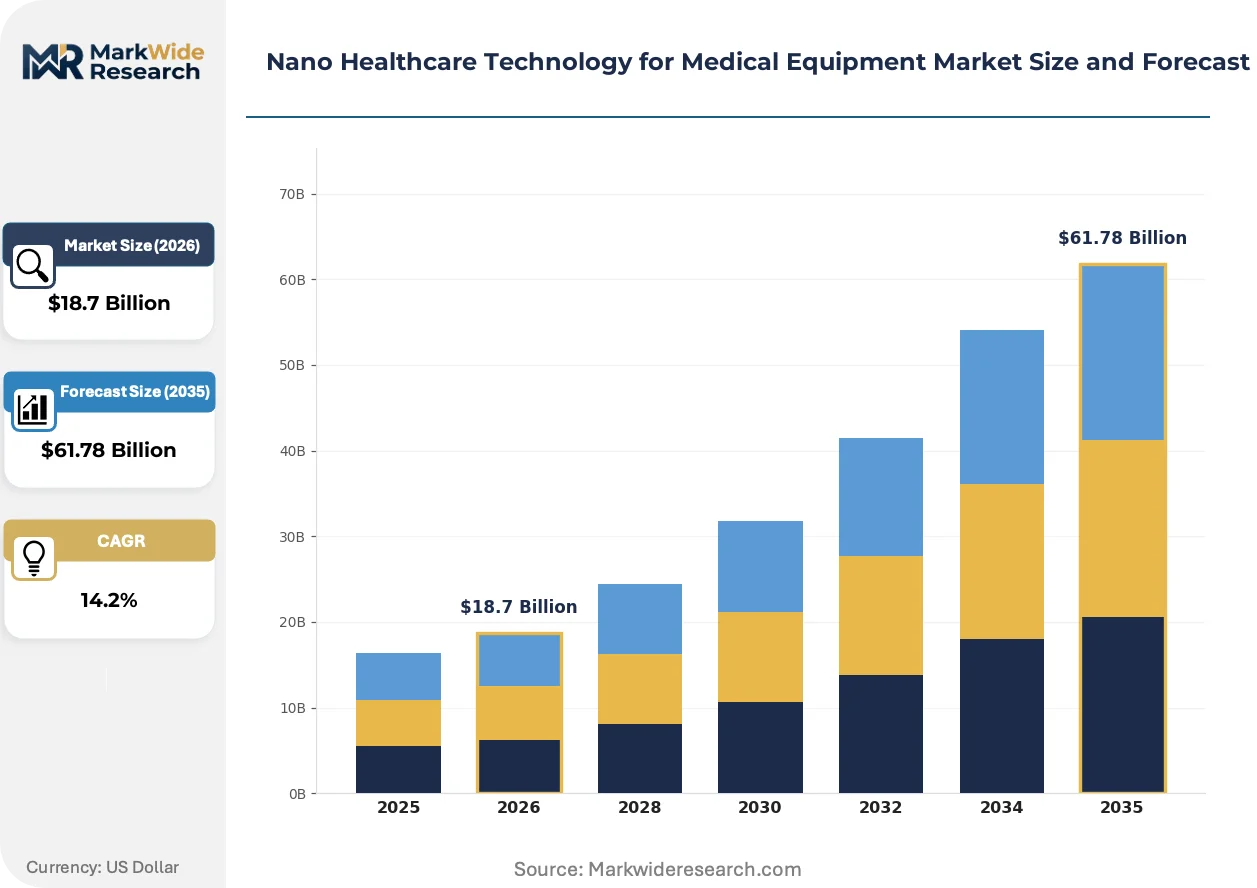
Market Dynamics
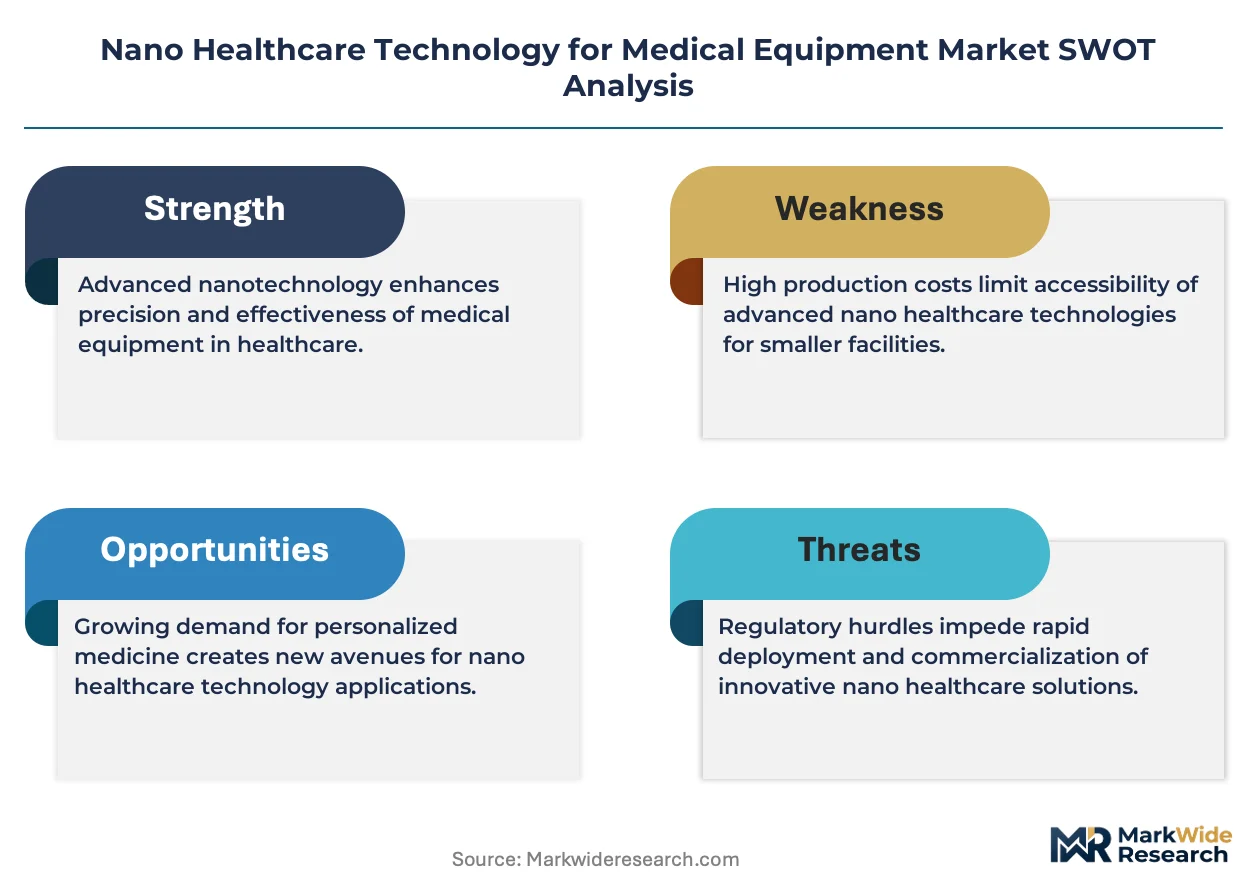
The FDA's 510(k) clearance pathway and the EU Medical Device Regulation are compressing product development timelines while simultaneously elevating compliance investments, forcing manufacturers to restructure R&D budgets around dual-jurisdiction validation requirements.
Growth Catalysts
- NIH-funded consortia:Academic medical centers in the United States channel federal research dollars into nanoscale imaging and targeted drug delivery platforms, accelerating clinical translation of laboratory discoveries.
- ISO 10993 biocompatibility standards:Harmonized international testing protocols reduce redundant safety evaluations, enabling faster regulatory submissions across multiple jurisdictions.
- Hydroxyapatite nanoparticle synthesis:Controlled manufacturing of bone-integrative nanomaterials expands addressable indications in spinal fusion and joint reconstruction procedures.
Market Restraints
- Cleanroom fabrication capex:Nanoscale device manufacturing requires ISO Class 5-7 environments with continuous particle monitoring, creating capital barriers for mid-scale entrants.
- EMA nanomedicine reflection papers:Evidentiary requirements for nanomaterial characterization extend premarket approval timelines and increase pharmacokinetic study costs.
- Conventional contrast agents:Iodine-based and gadolinium-based imaging agents retain formulary preference in cost-sensitive hospital systems, slowing nanorod adoption.
Strategic Opportunities
- German university hospitals:Procurement expansion in Baden-Württemberg and Bavaria creates early-adopter channels for quantum dot-enabled surgical navigation systems.
- Point-of-care glucose monitoring:Miniaturized nano sensor platforms reduce reagent volumes and test turnaround in ambulatory settings outside traditional laboratory infrastructure.
- EU MDR classification rules:Nanomaterial-containing device categories trigger specialized conformity assessment pathways that reward firms with dedicated regulatory affairs capacity.
Industry Challenges
- Formulation expertise scarcity:Liposomal and polymeric nanoparticle development requires cross-functional teams combining materials science, pharmacology, and regulatory knowledge that compete for limited talent pools.
- Batch-release protocol complexity:Evolving characterization standards for nanoscale impurities necessitate supplier requalification and extended analytical method validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Healthcare Technology for Medical Equipment Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nano Sensors, Drug Delivery Systems, Diagnostic Tools, Imaging Devices End User: Hospitals, Clinics, Research Laboratories, Home Care Technology: Nanotechnology, Microscopy, Surface Modification, Biocompatible Materials Application: Diagnostics, Treatment, Monitoring, Research & Development |
| Companies Covered | 3M, Zimmer Biomet, Medtronic, Starkey Laboratories, Boston Scientific Corporation, Stryker, Smith & Nephew PLC, Dentsply Sirona, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Healthcare Technology for Medical Equipment Market Shifts & Advancements
Quantum dots, gold nanorods, and surface-modified antimicrobial coatings are restructuring diagnostic and therapeutic workflows by displacing legacy contrast agents and infection-control methodologies.
Quantum dots are decomposing the centralized radiology model by enabling real-time fluorescence-guided surgery with tunable emission spectra. Academic medical centers in the United States integrate these semiconductor nanocrystals into oncology and interventional radiology workflows. The technology is decomposing conventional imaging department hierarchies by shifting diagnostic capability directly into surgical suites.
EMA nanomedicine reflection papers and FDA emerging technology program divergence creates parallel evidentiary tracks that favor established multinationals with dedicated regulatory affairs capacity across both jurisdictions. Manufacturers must maintain separate pharmacokinetic study designs and nanomaterial characterization protocols. Drug delivery system developers face the steepest compliance cost escalation as liposomal platforms trigger enhanced safety monitoring requirements.
Hospital procurement departments in France and Germany consolidate vendor relationships around integrated device manufacturers offering captive nanomaterial sourcing and in-house cleanroom fabrication. Multi-year supply agreements replace transactional purchasing for nano-enabled cardiac and neurological implant lines. This concentration pattern is most visible in Baden-Württemberg university hospital networks where procurement committees prioritize vertical integration guarantees over component-specialist pricing.
Nano Healthcare Technology for Medical Equipment Market Segmentation
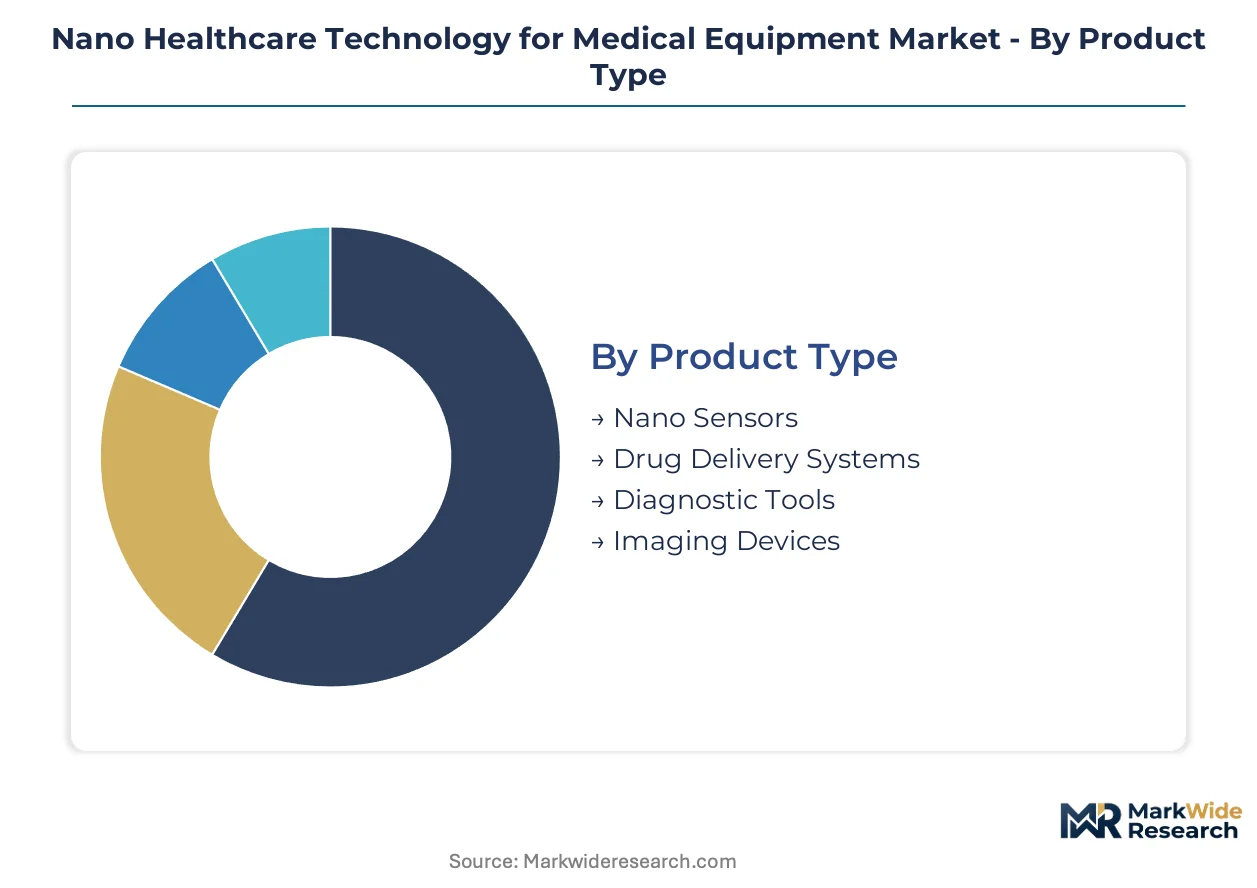
Segmentation in nano-enabled medical equipment reveals divergent margin profiles and regulatory burdens across product architectures. Manufacturers calibrate R&D allocation based on which segments face imminent displacement from conventional alternatives versus those commanding protected premium positions.
Product Type:
Substitution pressure concentrates in imaging and sensing segments where legacy contrast agents and electrochemical sensors retain formulary footholds through entrenched reimbursement codes.
- Drug Delivery Systems:Liposomal and polymeric nanoparticle platforms encapsulate therapeutic payloads for targeted bioavailability. NIH-funded academic medical centers in the United States drive early adoption in oncology and neurology departments. Extended regulatory validation timelines protect margin pools for specialized formulation houses.
- Nano Sensors:Electrochemical and optical transducers exploit quantum-scale surface-area effects for biomarker detection. Point-of-care glucose monitoring in ambulatory settings outside traditional laboratory infrastructure propels volume expansion. Miniaturization directly reduces reagent consumption per test.
- Diagnostic Tools:Centralized laboratory instruments incorporating nanoscale reagents for enhanced sensitivity.
- Imaging Devices:Quantum dots and gold nanorods displacing iodine-based contrast in interventional radiology workflows.
Drug Delivery Systems anchors the volume base while Nano Sensors gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital procurement from price-sensitive home care deployment, with reimbursement pathways determining viable technology configurations.
- Hospitals:Academic medical centers and university hospitals in Germany, France, and the United States consolidate procurement around integrated device manufacturers. Multi-year supply agreements prioritize vertical integration guarantees for cardiac and neurological implant lines.
- Research Laboratories:NIH-funded consortia and European Framework Programme beneficiaries channel federal research dollars into preclinical nanoscale imaging platforms. Early-stage validation creates technology spillover into commercial segments.
- Clinics:Outpatient facilities adopting miniaturized diagnostic platforms for rapid turnaround.
- Home Care:Patient-operated monitoring devices with simplified nano sensor interfaces for chronic disease management.
Hospitals command the revenue concentration while Research Laboratories expand most quickly as translational funding accelerates.
Technology:
Supply concentration in cleanroom fabrication capacity favors established players controlling nanomaterial synthesis and surface engineering competencies.
- Nanotechnology:Engineered structures with at least one dimension between one and one hundred nanometers. Controlled hydroxyapatite nanoparticle synthesis for orthobiologics applications anchors Stryker's spinal fusion portfolio.
- Surface Modification:Antimicrobial coatings and biofunctionalization protocols enhancing device biocompatibility. Smith & Nephew PLC deploys surface-modified layers for wound closure and arthroscopy applications.
- Microscopy:Super-resolution imaging systems exploiting near-field optical effects.
- Biocompatible Materials:ISO 10993-compliant substrates for implantable device integration.
Nanotechnology captures the deepest value pools while Surface Modification climbs the fastest as infection-control protocols tighten.
Application:
Maturity gradients separate established diagnostic revenue streams from emerging therapeutic modalities facing evidentiary hurdles.
- Diagnostics:Centralized laboratory and point-of-care platforms leveraging nano sensor sensitivity for early disease detection. Quantum dot-enabled fluorescence-guided surgery is decomposing conventional radiology department hierarchies in United States academic centers.
- Treatment:Targeted drug delivery and localized therapeutic action through nanoparticle carriers. EMA nanomedicine reflection papers and FDA emerging technology program divergence creates parallel evidentiary tracks favoring multinationals with dedicated regulatory affairs capacity.
- Monitoring:Continuous biomarker tracking through wearable and implantable nano sensor arrays.
- Research & Development:Preclinical characterization tools and nanomaterial prototyping services.
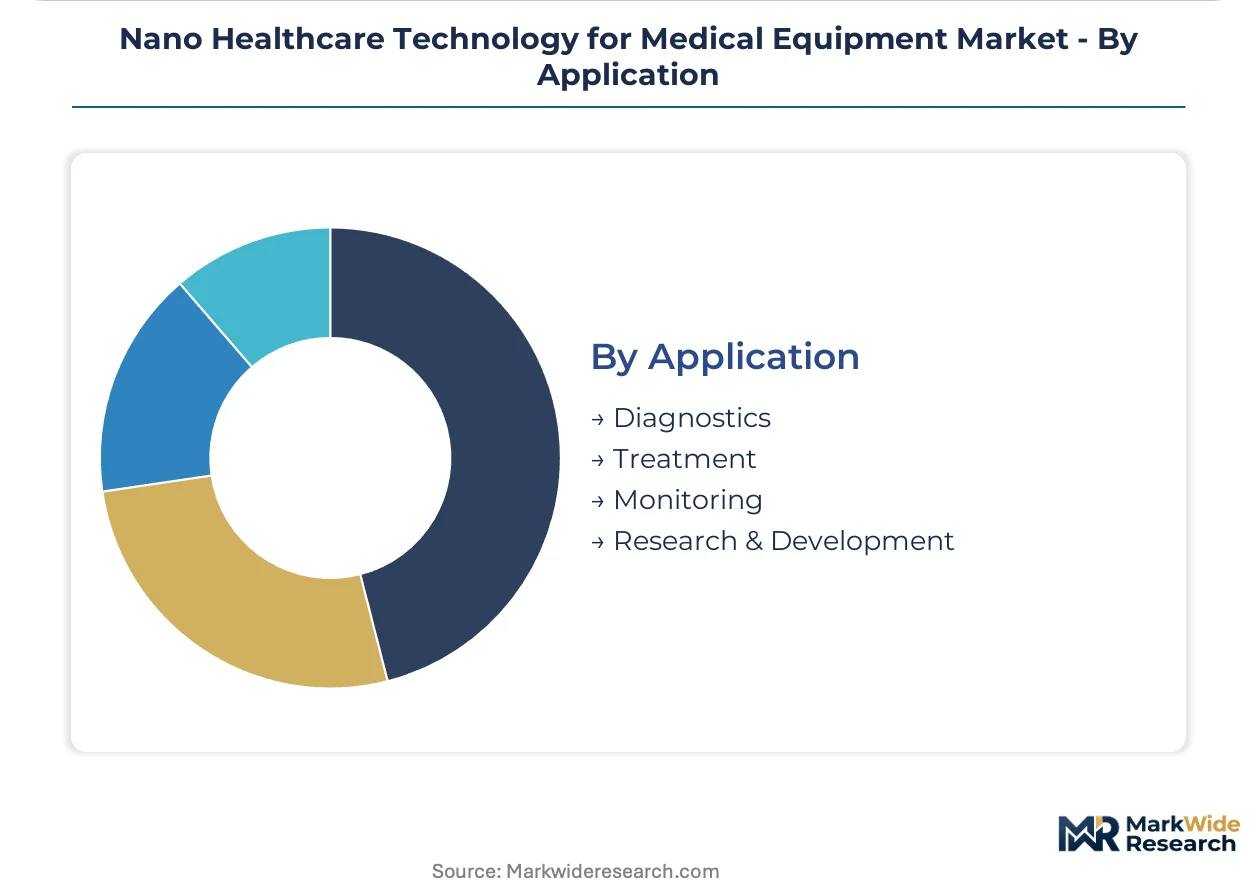
Diagnostics retains the revenue base while Treatment shows the steepest expansion trajectory as regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets prioritizing translational research infrastructure and those emphasizing procurement consolidation around vertically integrated suppliers. Academic medical centers in the United States channel federal research dollars into preclinical nanoscale platforms, while German hospital networks concentrate purchasing power through multi-year supply agreements.
United States
NIH-funded consortia and academic medical centers in Boston, Baltimore, and San Francisco drive early adoption of quantum dot-enabled surgical navigation and targeted drug delivery systems. FDA's emerging technology program accelerates premarket review for nanomaterial-containing devices. The Greater Boston cluster anchors translational research partnerships between Massachusetts General Hospital and MIT-affiliated fabrication facilities.
Germany
University hospital networks in Baden-Württemberg and Bavaria consolidate procurement around integrated device manufacturers offering captive nanomaterial sourcing. EU Medical Device Regulation classification rules for nanomaterial-containing devices trigger specialized conformity assessment pathways. The Stuttgart-Tübingen corridor concentrates orthobiologics manufacturing and cleanroom fabrication capacity.
France
Hospital procurement departments in Île-de-France and Auvergne-Rhône-Alpes prioritize multi-year supply agreements for nano-enabled cardiac and neurological implants over component-specialist pricing. ANSM oversight of nanomedicine characterization standards extends batch-release protocol requirements. The Lyon-Grenoble cluster hosts surface modification research facilities serving arthroscopy and wound closure applications.
United Kingdom
NHS England's specialized commissioning frameworks create demand concentration for point-of-care nano sensor platforms in diabetes and cardiovascular monitoring. MHRA alignment with ISO 10993 biocompatibility standards streamlines regulatory submissions for implantable devices. The Cambridge-Oxford arc anchors super-resolution microscopy development for diagnostic imaging applications.
Japan
PMDA's structured consultation pathways for nanomedicine products attract foreign manufacturers seeking parallel regulatory validation with FDA submissions. METI funding for regenerative medicine infrastructure expands addressable indications for hydroxyapatite nanoparticle synthesis in spinal fusion. The Kansai region concentrates biocompatible materials testing facilities serving implantable device developers.
Nano Healthcare Technology for Medical Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in nano-enabled medical equipment. Captive nanomaterial sourcing and in-house cleanroom fabrication distinguish the upper tier from component specialists dependent on external supply chains. Three archetypes populate the competitive map: diversified multinationals with captive fabrication, orthobiologics-focused manufacturers controlling nanoparticle synthesis, and surface engineering specialists deploying antimicrobial coatings. Capacity expansion and strategic partnerships dominate competitive moves as firms seek to secure ISO Class 5-7 fabrication environments and dual-jurisdiction regulatory capacity.
Among diversified multinationals, Medtronic and Stryker exemplify the integrated leader archetype through captive supply chain control. Smith & Nephew PLC occupies a position within the surface modification specialist tier. These three entities represent distinct strategic postures: the first two anchor premium positioning through backward integration into nanomaterial production, while the third exemplifies focused expertise in biofunctionalization protocols for specific surgical applications.
| Leading Market Players |
|---|
| 3M |
| Zimmer Biomet |
| Medtronic |
| Starkey Laboratories |
| Boston Scientific Corporation |
| Stryker |
| Smith & Nephew PLC |
| Dentsply Sirona |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
FDA 510(k) and EU MDR classification regimes for nanomaterial-containing devices simultaneously gate supplier qualification tiers and stratify price bands across cardiac implant and diagnostic platform categories. Manufacturers bearing dual-jurisdiction compliance costs command premium positioning against component specialists lacking dedicated regulatory affairs capacity.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement for nano-enabled cardiac and neurological implants, while spot purchasing persists for consumable nano sensor reagents. Three-tier pricing structure across premium, standard, and economy levels separates integrated device manufacturers with captive nanomaterial sourcing from component specialists dependent on external supply chains. Cost compression in point-of-care glucose monitoring intensifies as miniaturized platforms commoditize reagent volumes. Academic medical centers exhibit lowest price sensitivity given NIH-funded budget insulation, while outpatient clinics face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of hydroxyapatite nanoparticles and quantum dot precursors characterizes orthobiologics and imaging device manufacturing, contrasting with just-in-time inventory for standardized nano sensor substrates. Supply concentration centers on Germany, the United States, and Japan for ISO Class 5-7 cleanroom fabrication capacity. Raw material dependencies include rare earth elements for quantum dot synthesis, high-purity solvents for liposomal formulation, and specialized polymers for surface modification coatings. Single-source vulnerability in hydroxyapatite nanoparticle synthesis threatens spinal fusion device timelines. Distribution runs through GPO contracts and direct hospital system partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as point-of-care diagnostic decentralization and surgical navigation miniaturization create specialty niches outside integrated multinational portfolios.
For Market Incumbents: Shield premium positioning in cardiac and neurological implant lines by deepening backward integration into nanomaterial synthesis and expanding ISO Class 5-7 cleanroom footprint in Baden-Württemberg. Surface engineering specialists threaten margin pools in wound closure applications. Dual-jurisdiction regulatory capacity serves as the primary defensive lever against emerging entrants lacking EMA-FDA parallel submission expertise. For New Entrants and Emerging Players: Lead with point-of-care glucose monitoring platforms in NHS England specialized commissioning frameworks, where reimbursement pathways favor ambulatory nano sensor deployment over centralized laboratory infrastructure. Home care chronic disease management represents the most penetrable end-user segment given simplified interface requirements and patient-operated device protocols. Partner with German university hospital networks for early-adopter validation of quantum dot-enabled surgical navigation. For Investors and Strategic Acquirers: EU MDR nanomaterial classification rules reshape the acquisition landscape by elevating regulatory affairs capacity to primary valuation consideration alongside fabrication assets. Long-term viability centers on targets controlling hydroxyapatite nanoparticle synthesis or surface modification IP with proven ISO 10993 compliance histories. Watch EMA nanomedicine reflection paper revisions as inflection signal for pharmacokinetic study cost escalation and premarket timeline extension.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Regulatory Capacity Buildout | EMA-FDA parallel submission expertise accelerates nanomaterial-containing device market access timelines. |
| Captive Nanomaterial Sourcing Integration | In-house hydroxyapatite and quantum dot production insulates margin pools from supplier qualification volatility. |
| University Hospital Partnership Network | Baden-Württemberg and Bavaria procurement committees prioritize vertical integration guarantees in multi-year agreements. |
| Point-of-Care Platform Miniaturization | Reduced reagent consumption per test expands addressable ambulatory settings outside traditional laboratory infrastructure. |
| Surface Modification IP Portfolio Expansion | Antimicrobial coating patents protect arthroscopy and wound closure positioning against generic coating commoditization. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors; and secondary validation against FDA 510(k) filings, EMA nanomedicine reflection papers, hospital procurement databases, and ISO 10993 biocompatibility standard revisions. Bottom-up triangulation cross-checked manufacturer capacity disclosures with top-down demand modeling from NIH funding allocations and EU Framework Programme beneficiaries.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, end-user cost tier, cleanroom fabrication technology, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation with macro healthcare expenditure patterns. Forecast inputs incorporated nanoscale imaging platform adoption curves in academic medical centers and orthobiologics procedure volume elasticity.
Forecasts assume regulatory continuity in FDA emerging technology program and EU MDR classification regimes; material policy shifts would require re-modeling. Revision becomes warranted when EMA nanomedicine characterization standards or ISO 10993 batch-release protocols cross implementation thresholds affecting premarket approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Prostate Biopsy Devices Market
Medical Devices
Digital Impression System Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Medical Coatings Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Global Hernia Repair Devices Market