
 Australia Abrasives Market | 2026-2036
Australia Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Abrasives Market Intelligence
Australian abrasive manufacturing capacity is realigning toward high-performance bonded and super abrasive grades for precision engineering. Saint-Gobain Abrasives Pty Ltd. leverages its global technology base to dominate premium ceramic grain supply for metalworking clients. 3M Australia Pty Limited anchors the coated abrasive segment through deep distribution into automotive refinishing and construction trades. PFERD Australia Pty Ltd. specializes in application-specific finishing tools for localized mining maintenance workflows.
Abrasives are hard minerals or synthetic grains bonded into tools that remove material through cutting, grinding, or polishing action, with specifications including grit size, bond type, and hardness grade determining removal rate and surface finish quality. These materials serve primary industrial purposes across metal fabrication, surface preparation, and precision component manufacturing. Coated abrasives lead volume in automotive refinishing and construction sanding applications where flexibility and conformability matter. Super abrasives, specifically diamond and CBN variants, capture premium margin pools in aerospace component grinding and advanced electronics machining. Bonded abrasives sustain foundational demand from metalworking and infrastructure sectors requiring aggressive stock removal on hardened steels.
WorkSafe Australia enforces respirable crystalline silica exposure standards that compel manufacturers toward engineered abrasives with reduced friability and dust generation. TGA oversight on imported abrasive products ensures compliance with Australian labeling and material safety requirements, while AS/NZS standards govern performance benchmarking for bonded wheel integrity. State-level environmental regulations in Victoria and Queensland restrict waste disposal from abrasive blasting operations, redirecting demand toward recyclable garnet and waterjet alternatives. Stakeholders must monitor evolving silica threshold reductions and state procurement preferences for low-emission surface preparation technologies.
Market Dynamics
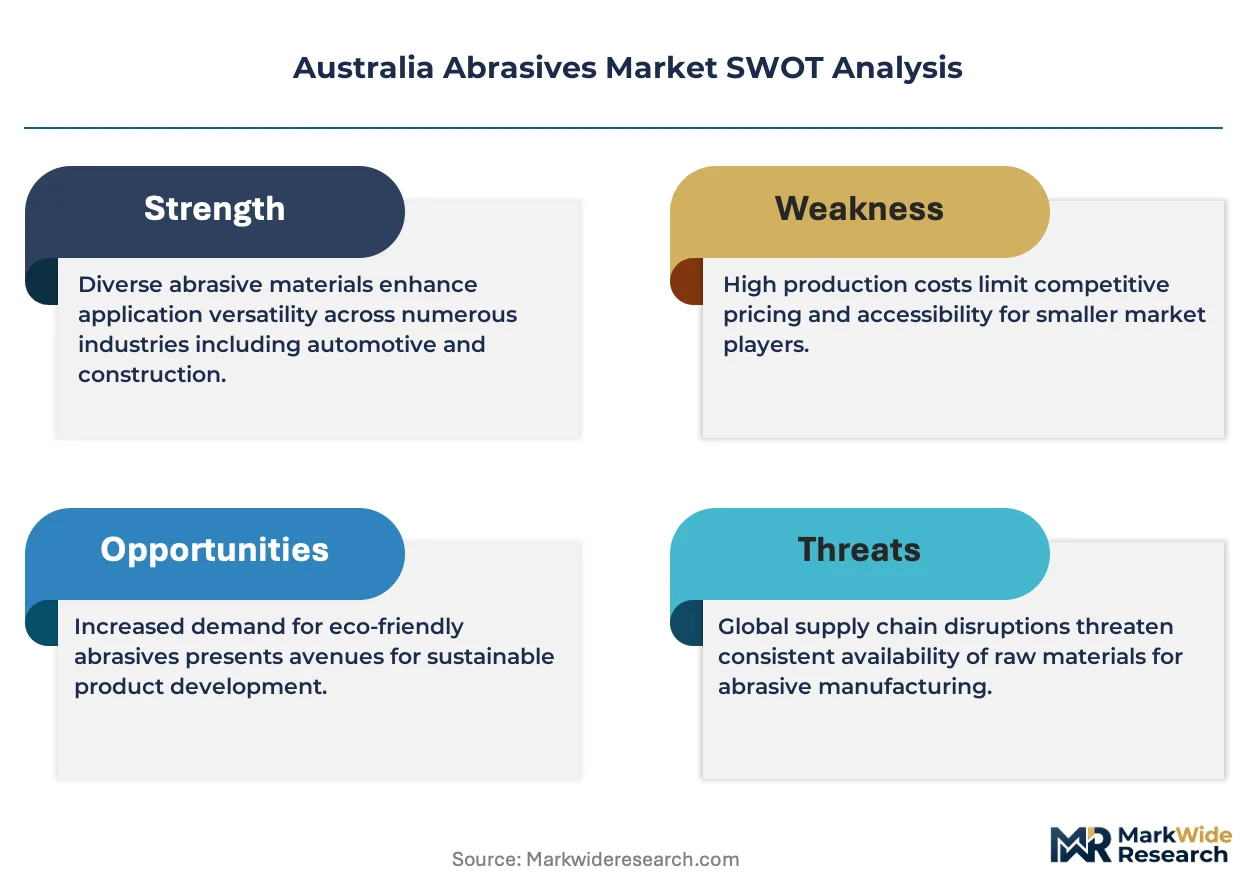
WorkSafe Australia's progressive tightening of respirable crystalline silica exposure limits is forcing abrasive manufacturers to reformulate bonded products and accelerate investment in engineered ceramic grains that minimize dust generation during grinding operations.
Growth Catalysts
- Western Australian Mining Equipment Refurbishment:Cyclical replacement of haul truck buckets and excavator teeth generates sustained demand for heavy-duty bonded grinding wheels in Kalgoorlie and Pilbara maintenance facilities.
- Queensland Infrastructure Pipeline:State government transport and energy projects require abrasive consumption for steel fabrication, surface preparation, and welding finishing across Brisbane-Gladstone manufacturing corridors.
- AS/NZS 1788 Wheel Integrity Standards:Mandatory testing protocols for bonded abrasive wheels elevate product replacement rates and disqualify low-cost imports from non-compliant suppliers.
Market Restraints
- Fused Alumina Import Dependence:Australian manufacturers source over eighty percent of brown and white fused alumina feedstock from Chinese smelters, exposing margins to shipping cost volatility and tariff uncertainty.
- Super Abrasive Equipment Capex Barriers:Precision grinding centers utilizing diamond and CBN wheels require capital investment exceeding two million dollars per installation, limiting adoption among mid-tier metalworking shops.
- Silica Substitution Technical Limits:Engineered grains reduce respirable dust but cannot yet match silicon carbide's stock removal efficiency on cast iron and non-ferrous alloys in heavy foundry applications.
Strategic Opportunities
- Tasmanian Precision Manufacturing Corridor:Underdeveloped relative to mainland states, Hobart and Launceston aerospace component suppliers present white space for super abrasive technical sales and application engineering support.
- Waterjet Cutting Convergence:Integration of garnet abrasive recycling systems with waterjet platforms creates bundled service opportunities in Victorian and New South Wales stone and composite fabrication.
- Victorian Circular Economy Procurement Mandates:State government preference for recyclable blasting media in infrastructure contracts redirects demand toward garnet recovery and reprocessing business models.
Industry Challenges
- Ceramic Grain Application Engineering Talent:Shortage of metallurgists and process engineers capable of specifying seeded-gel and sol-gel alumina formulations for precision grinding operations limits premium product penetration.
- TGA Product Registration Timelines:Imported abrasive products face twelve-to-eighteen month approval cycles for compliance with Australian labeling and material safety documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Abrasives Market |
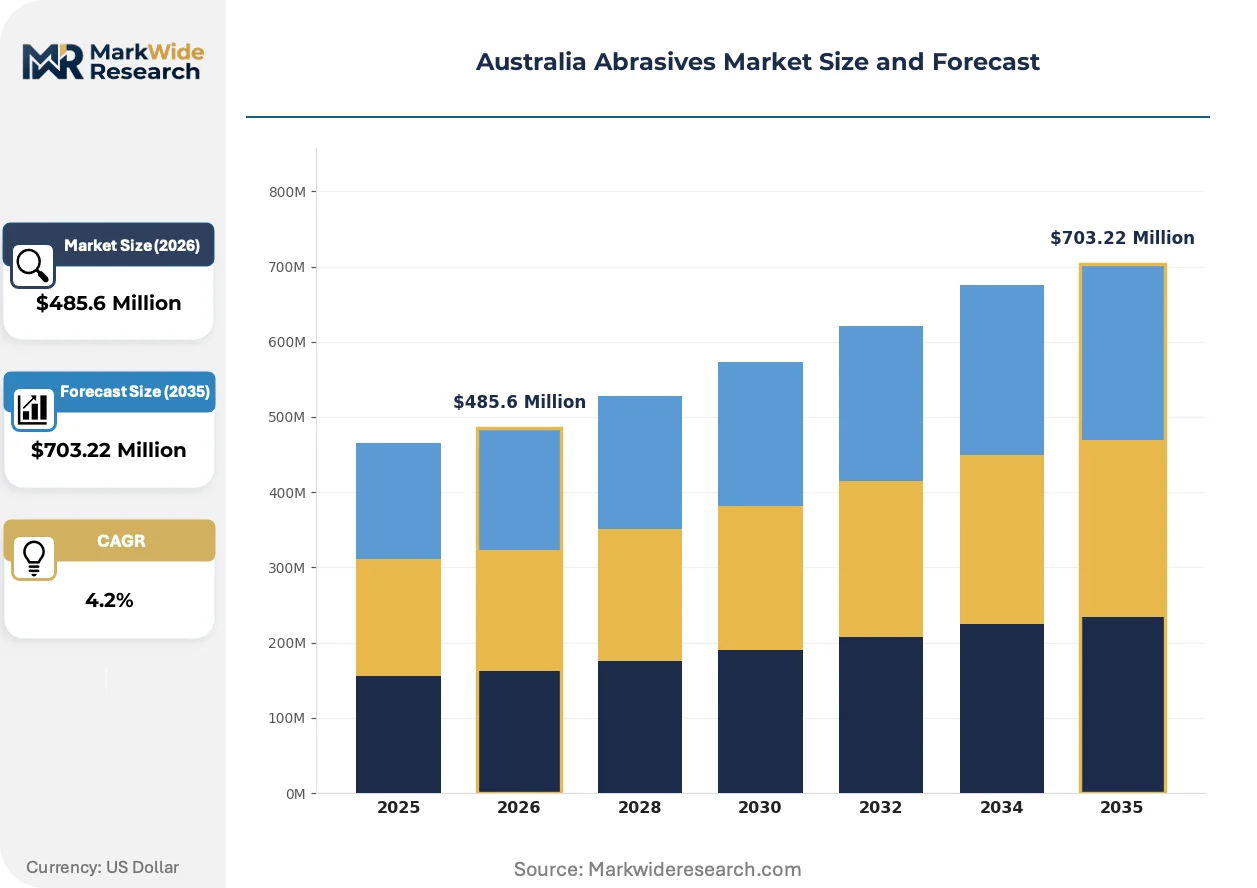
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $703.22 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Abrasives, Coated Abrasives, Super Abrasives, Loose Abrasives Material: Alumina, Silicon Carbide, Diamond, CBN Industry Vertical: Construction, Automotive, Metalworking, Electronics Application: Grinding, Cutting, Polishing, Finishing |
| Companies Covered | PFERD Australia Pty Ltd., Hermes Abrasives Australia Pty Ltd., Saint-Gobain Abrasives Pty Ltd., Klingspor Australia Pty Ltd., 111 Abrasives Australia Pty Ltd., 3M Australia Pty Limited, Tyrolit Australia Pty Ltd., CUMI Australia, GMA Garnet Pty Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Abrasives Market Strategic Shifts & Innovations
Reformulation chemistry and digital process control are compressing the performance gap between commodity abrasives and precision-engineered grades. Manufacturers now compete on application-specific technical service rather than grit specification alone.
Ceramic seeded-gel abrasive grain technology is unifying stock removal speed and surface finish quality in single-pass grinding operations. Tier-one automotive component suppliers in Adelaide and Melbourne are retrofitting centerless grinding lines with these grains to eliminate secondary honing steps. The technology is unifying what previously required separate roughing and finishing wheel sets, reducing changeover downtime and inventory complexity for high-volume manufacturers.
WorkSafe Australia's 2024 respirable crystalline silica exposure standard reduction to 0.025 milligrams per cubic meter is eliminating conventional silicon carbide products from approved procurement lists. Abrasive distributors must now maintain dual inventory of compliant engineered grains and legacy stock while educating trades on proper extraction system pairing. Metal fabrication shops in New South Wales and Queensland are responding fastest, driven by state-level workplace safety audit intensity and insurance premium linkage to compliance certification.
Application-engineered abrasive subscription programs are displacing transactional spot purchasing among multi-site mining maintenance contractors. These contracts bundle technical specification, on-site inventory management, and consumption analytics in exchange for volume commitments. The model is most visible in Western Australia's Pilbara region, where Rio Tinto and BHP maintenance divisions prioritize supply security and standardization across remote fly-in-fly-out operations over unit cost minimization.
Australia Abrasives Market Segmentation
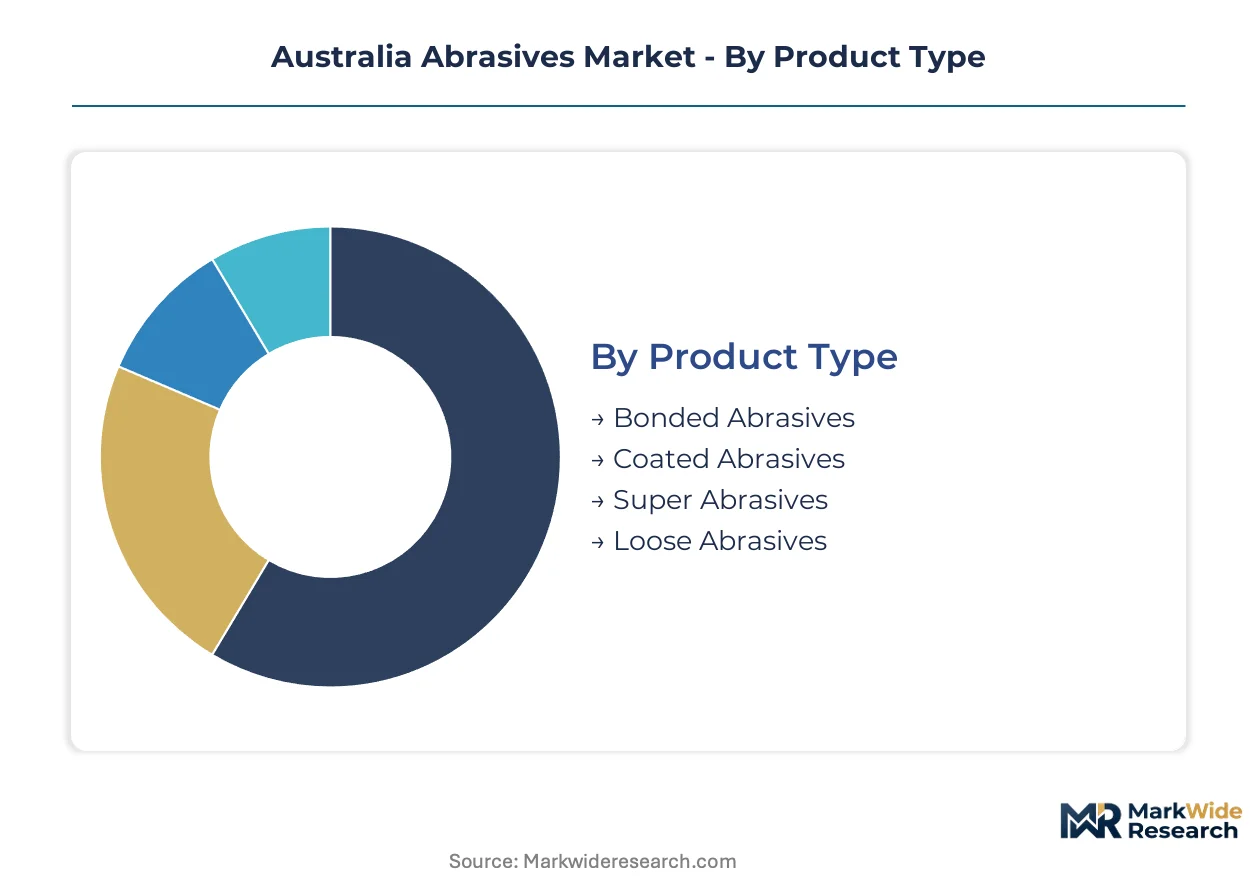
Segmentation in the Australia abrasives market reveals distinct procurement patterns across product grades, material chemistries, and end-use applications. Mining maintenance workflows in Western Australia, infrastructure steel fabrication in Queensland, and precision component machining in Victoria each drive divergent specification requirements and margin structures.
Product Type:
Volume concentration sits with commodity bonded and coated formats serving construction and mining maintenance, while premium capture concentrates in super abrasive grades for precision engineering applications.
- Bonded Abrasives:Grinding wheels, segments, and mounted points formed by vitrified, resinoid, or rubber bonds that fix abrasive grains into rigid shapes for aggressive stock removal. Demand concentrates in Western Australia's Pilbara and Kalgoorlie mining equipment refurbishment facilities, driven by cyclical replacement of haul truck buckets and excavator teeth requiring heavy-duty grinding operations.
- Coated Abrasives:Flexible backing materials—paper, cloth, or fiber—impregnated with abrasive grains in open or closed coat configurations for sanding and finishing. Queensland's Brisbane-Gladstone infrastructure manufacturing corridor consumes the majority of volume for steel surface preparation and welding seam finishing on transport and energy projects.
- Super Abrasives:Diamond and cubic boron nitride (CBN) grains bonded into precision grinding wheels for hardened materials and tight tolerances.
- Loose Abrasives:Free-flowing grains deployed in blasting, mass finishing, and lapping operations without fixed bond structures.
Mature deployment sits with bonded abrasives in mining maintenance. Newer deployment is concentrated in super abrasive precision grinding for aerospace and automotive component manufacturing.
Material:
Feedstock selection determines removal rate, thermal stability, and compliance with WorkSafe Australia respirable crystalline silica exposure standards.
- Alumina:Brown fused alumina for heavy stock removal and white fused alumina for precision finishing, with seeded-gel and sol-gel ceramic variants gaining traction for reduced dust generation. Australian manufacturers source over eighty percent from Chinese smelters, exposing margins to shipping cost volatility.
- Silicon Carbide:Hard, sharp grains prized for cast iron and non-ferrous alloy grinding in heavy foundry applications.
- Diamond:Synthetic and natural monocrystalline and polycrystalline grains for grinding carbides, ceramics, and glass in aerospace and electronics machining.
- CBN:Cubic boron nitride grains second only to diamond in hardness, optimized for ferrous material precision grinding without carbon dissolution issues.
Alumina variants dominate volume across all industry verticals. Diamond and CBN are expanding most quickly in Tasmanian aerospace component suppliers and Melbourne precision manufacturing clusters.
Industry Vertical:
End-use concentration shapes specification complexity, with infrastructure and mining favoring standardized heavy-duty formats while automotive and electronics demand application-engineered precision grades.
- Construction:Surface preparation, concrete grinding, and masonry cutting applications consuming bonded wheels and coated abrasive sheets. New South Wales and Victorian government infrastructure procurement mandates increasingly specify recyclable blasting media and low-emission surface preparation technologies.
- Automotive:OEM component grinding, refinishing, and aftermarket repair operations requiring consistent surface finish quality.
- Metalworking:Foundry, fabrication, and precision machining operations spanning commodity roughing to micron-tolerance finishing.
- Electronics:Semiconductor wafer dicing, substrate polishing, and printed circuit board depaneling requiring contamination-controlled super abrasive processing.
Construction and metalworking anchor volume demand. Electronics represents the steepest expansion trajectory as advanced manufacturing reshoring accelerates precision component production.
Application:
Functional use case determines wheel specification, with aggressive material removal contrasting against cosmetic and dimensional finishing requirements.
- Grinding:Dimensional accuracy and surface integrity operations using bonded wheels in cylindrical, centerless, and surface configurations. Adelaide and Melbourne automotive suppliers are retrofitting centerless grinding lines with ceramic seeded-gel grains to eliminate secondary honing steps.
- Cutting:Severing operations using reinforced bonded wheels or abrasive saws on metal, stone, and composite materials.
- Polishing:Fine abrasive action producing specular surface finishes through progressively finer grit sequences.
- Finishing:Final surface treatment operations including deburring, blending, and aesthetic preparation.
Grinding commands the largest equipment-installed base. Polishing is gaining share fastest in premium automotive and electronics manufacturing as surface quality specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite deposits in Queensland and Western Australia anchor feedstock security for domestic fused alumina production, though smelting capacity remains concentrated in Chinese industrial zones. State-level procurement mandates and mining maintenance cycles reshape regional demand patterns across Australia's eastern and western seaboards.
Western Australia
Pilbara iron ore operations and Kalgoorlie gold mining drive cyclical demand for heavy-duty bonded grinding wheels in haul truck bucket refurbishment. WorkSafe Western Australia enforces respirable crystalline silica exposure limits that accelerate ceramic grain substitution in maintenance contracts. Perth-based distributors maintain bonded abrasive inventory for fly-in-fly-out mining contractors prioritizing supply security over unit cost.
Queensland
Brisbane-Gladstone infrastructure manufacturing corridors consume coated abrasives for steel surface preparation on transport and energy projects. State procurement policies increasingly specify recyclable blasting media for government contracts. Gladstone metal fabrication clusters source bonded wheels for welding seam finishing on structural steel components.
New South Wales
Sydney infrastructure pipeline and regional highway construction sustain construction-grade abrasive consumption for concrete grinding and masonry cutting. NSW Environment Protection Authority restrictions on waste disposal from abrasive blasting redirect demand toward garnet recovery systems. Wollongong steel fabrication facilities represent concentrated demand for coated abrasive sheets in shipbuilding and heavy engineering.
Victoria
Melbourne automotive component suppliers and aerospace precision manufacturers anchor super abrasive adoption for hardened material grinding. Victorian circular economy procurement mandates favor recyclable blasting media in state infrastructure contracts. Geelong manufacturing clusters retrofit centerless grinding lines with ceramic seeded-gel grains to eliminate secondary finishing steps.
South Australia
Adelaide automotive OEM component grinding operations require consistent surface finish quality from engineered abrasive specifications. Defence industry procurement from Osborne naval shipbuilding generates specialized abrasive demand for alloy fabrication. TGA product registration timelines for imported abrasives create inventory planning complexity for distributors serving South Australian manufacturers.
Australia Abrasives Market Key Industry Players
Global majors compete with regional champions across technology licensing and distribution depth, producing a tiered structure where premium ceramic grain supply concentrates among multinational technology holders while mid-market bonded and coated formats fragment across regional distributors. Three archetypes dominate: technology-integrated multinationals leveraging global R&D platforms, application-specialized regional distributors with deep mining maintenance relationships, and commodity-focused import distributors competing on price and availability. Capacity expansion and strategic technical service partnerships represent the dominant competitive vectors as manufacturers seek to differentiate beyond grit specification.
Among German-origin precision tool specialists, PFERD Australia Pty Ltd. and Hermes Abrasives Australia Pty Ltd. occupy positions emphasizing application-engineered finishing tools for localized industrial workflows. Saint-Gobain Abrasives Pty Ltd. anchors the premium technology tier through its global ceramic grain capabilities. These three exemplify how European-headquartered multinationals structure Australian market presence through technology transfer and technical sales engineering rather than commodity volume competition.
| Leading Market Players |
|---|
| PFERD Australia Pty Ltd. |
| Hermes Abrasives Australia Pty Ltd. |
| Saint-Gobain Abrasives Pty Ltd. |
| Klingspor Australia Pty Ltd. |
| 111 Abrasives Australia Pty Ltd. |
| 3M Australia Pty Limited |
| Tyrolit Australia Pty Ltd. |
| CUMI Australia |
| GMA Garnet Pty Ltd. |
| Others |
Cost & Logistics Intelligence
Captive sourcing of brown and white fused alumina from Chinese smelters anchors Australian manufacturers' cost position while constraining their pricing autonomy against engineered ceramic grain competitors. This upstream dependency locks margin structures to shipping rate volatility and tariff exposure, forcing domestic distributors to absorb cost swings or cede share to technology-integrated multinationals with global grain supply networks.
Pricing Analysis
Warranty-backed technical service bundling separates premium ceramic grain suppliers from commodity importers competing on spot price alone. Three-tier pricing structure across premium, standard, and economy levels reflects grit specification, bond integrity certification, and application engineering support inclusion. Cost compression in economy bonded wheels is intensifying because import distributors flood the market with non-AS/NZS compliant inventory. Mining maintenance contractors in Western Australia show lowest price sensitivity due to fly-in-fly-out supply security priorities, while construction trades in New South Wales exhibit highest sensitivity to per-unit abrasive cost.
Supply Chain Analysis
Victorian and Queensland government procurement mandates for recyclable blasting media are reshaping sourcing patterns toward garnet recovery and reprocessing networks. Australian manufacturers draw from Chinese smelters for fused alumina, German and Austrian suppliers for precision grinding wheel bonds, and domestic garnet miners for waterjet feedstock. Single-source vulnerability concentrates in the China-origin alumina stream where shipping cost spikes transmit directly into landed cost. Distribution runs through Perth-based mining supply houses, Brisbane-Gladstone industrial distributors, and Melbourne precision manufacturing technical sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around technology-integrated multinationals as WorkSafe Australia's silica exposure standard enforcement disqualifies low-cost import suppliers lacking reformulation capabilities.
For Market Incumbents: Deploy application engineering subscription contracts to lock multi-site mining maintenance relationships before commodity distributors adapt. Saint-Gobain and 3M should extend ceramic grain technical service teams into Tasmanian aerospace corridors where super abrasive penetration remains underdeveloped. Backward integration into garnet recovery systems captures Victorian circular economy procurement preference and creates defensive moats against import price competition. For New Entrants and Emerging Players: TGA product registration timelines in Australia open a window for specialized super abrasive distributors willing to absorb twelve-to-eighteen month approval cycles for CBN precision grinding wheels. Target Hobart and Launceston aerospace component suppliers with application-specific technical sales support, bypassing saturated Melbourne automotive grinding markets. Waterjet garnet recycling service bundling represents the most penetrable entry vector given state infrastructure procurement mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by global technology holders seeking Australian mining maintenance distribution depth. Five-to-ten year viability favors regional distributors with captive relationships to Pilbara fly-in-fly-out contractors and approved vendor status under BHP and Rio Tinto procurement systems. Watch for inflection in Victorian government infrastructure contract awards specifying recyclable blasting media compliance tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Grain Application Engineering Investment | Seeded-gel and sol-gel formulation expertise commands premium pricing in precision grinding segments. |
| Garnet Recovery System Integration | Victorian circular economy procurement mandates redirect infrastructure abrasive demand toward recyclable media. |
| TGA Product Registration Acceleration | Twelve-to-eighteen month approval timelines create inventory barriers for import distributors lacking compliance infrastructure. |
| Western Australian Mining Maintenance Subscription Contracts | Fly-in-fly-out supply security priorities enable volume commitment extraction from BHP and Rio Tinto divisions. |
| Tasmanian Aerospace Technical Sales Expansion | Underdeveloped super abrasive penetration in Hobart and Launceston precision manufacturing clusters offers white-space capture. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant engineers at Western Australian mining maintenance facilities, procurement leads at Queensland infrastructure fabricators, and technical sales directors at Melbourne precision grinding operations. WorkSafe Australia exposure standard documentation, TGA product registration databases, and AS/NZS 1788 testing protocol records provided regulatory constraint parameters. Bottom-up consumption modeling across bonded, coated, and super abrasive categories triangulated against top-down import value flows from Australian Bureau of Statistics trade data.
Data-stream reconciliation across product type, material chemistry, industry vertical, and application use case generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, grain specification, end-use industry, and regional demand cluster throughout the forecast period. CAGRs derived from historical consumption elasticity to mining capital expenditure cycles, infrastructure project pipelines, and precision manufacturing reshoring trends. Forecast inputs incorporated WorkSafe Australia silica threshold reduction implementation timelines and state procurement mandate adoption rates.
Caveats apply where shipping cost volatility, Chinese smelter supply disruptions, or accelerated silica exposure standard enforcement could materially shift the outlook. Forecasts reflect documented assumptions regarding mining maintenance cycle timing and infrastructure project award pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Boron Carbide Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Glass Abrasives Market
Abrasives
Abrasive Base Paper Market
Abrasives
Synthetic Abrasives Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Polishing Chemicals Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Calcined Shale Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market
Abrasives
Europe Abrasives Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Metal Abrasives Market
Abrasives
Super Abrasives Market
Abrasives
Polishing Powder Market