
 Global Graphene Based Supercapacitors Market | 2026-2036
Global Graphene Based Supercapacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graphene Based Supercapacitors Market Analysis
The graphene supercapacitor supply base is rebalancing as premium electrochemical cells with verified cycle life separate from commodity pseudocapacitor assemblies where price competition erodes margin. Skeleton Technologies leverages its Estonian-German manufacturing footprint to sustain long-term supply contracts with European tram and bus builders. Nanotech Energy anchors North American demand through its graphene nanocomposite electrode production in California. CRRC dominates rail-sector deployments, controlling procurement channels for China's expanding electric locomotive fleet.
Graphene based supercapacitors store electrical energy through electrochemical double-layer capacitance at electrode-electrolyte interfaces, achieving power densities exceeding 10 kW per kilogram and cycle stability surpassing one million charge-discharge events. Their primary commercial purpose is to deliver burst power and bridge energy gaps where batteries face thermal or rate limitations. Electrochemical product types lead current revenue pools due to proven manufacturing repeatability, while supercapattery variants represent the fastest-expanding segment as hybrid architectures capture electric vehicle regenerative braking applications. Energy Storage applications concentrate margin pools through utility-scale frequency regulation contracts, whereas Mobile Devices remains a volume-driven, lower-margin category.
The EU Green Deal and F-Gas Regulation shape product standards by mandating fluorinated-gas-free thermal management in grid-connected storage, pushing developers toward graphene aerogel thermal interfaces. China's MIIT enforces GB standards for energy density and safety testing, creating market access barriers for uncertified imports. India's BIS certification requirements under the PLI scheme for advanced chemistry cell manufacturing are redirecting capital toward domestic electrode production. Stakeholders must monitor how regulatory divergence between Brussels and Beijing on carbon footprint disclosure reshapes supply chain routing and capital allocation for new electrode fabrication capacity.
Market Dynamics
Automotive OEM procurement contracts for regenerative braking systems are compressing supplier qualification timelines and forcing electrode manufacturers to co-locate near vehicle assembly clusters in Germany and China.
Growth Catalysts
- EU Green Deal F-Gas mandates:Grid-scale storage developers must eliminate fluorinated-gas thermal management, accelerating adoption of graphene aerogel interfaces in utility frequency regulation installations.
- Electric locomotive fleet electrification:China's rail sector procurement channels are absorbing electrochemical double-layer modules for regenerative energy capture across expanding high-speed networks.
- California nanocomposite electrode production:North American anode manufacturing capacity is scaling to serve fast-charge bus fleet operators demanding verified million-cycle stability.
Market Restraints
- High-purity graphene flake supply concentration:Electrode fabrication depends on limited feedstock sources, creating input cost volatility when mining or chemical vapor deposition capacity tightens.
- GB standard certification barriers:China's MIIT energy density and safety testing requirements block uncertified imports, fragmenting supply chain routing for non-domestic producers.
- Lithium-ion cost-performance parity:Battery energy density improvements above 300 Wh per kilogram threaten supercapacitor positioning in longer-duration electric vehicle applications.
Strategic Opportunities
- India PLI scheme electrode localization:BIS certification requirements under advanced chemistry cell manufacturing incentives are redirecting capital toward domestic anode production capacity.
- Supercapattery hybrid architectures:Convergence of battery energy density with supercapacitor power density is opening regenerative braking applications previously locked to pure electrochemical cells.
- Utility-scale frequency regulation contracts:Grid operators in Germany and California are tendering burst-power services that reward sub-second response times inaccessible to conventional storage.
Industry Challenges
- Electrochemist talent scarcity:Qualified electrode formulation specialists command premium compensation, constraining R&D velocity at mid-scale manufacturers.
- Multi-jurisdiction carbon footprint disclosure:Divergent Brussels and Beijing reporting requirements complicate supply chain documentation for electrode fabricators serving both markets.
- Legacy thermal management system integration:Grid-connected storage retrofits face mechanical incompatibility when replacing fluorinated-gas cooling with graphene aerogel interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graphene Based Supercapacitors Market |
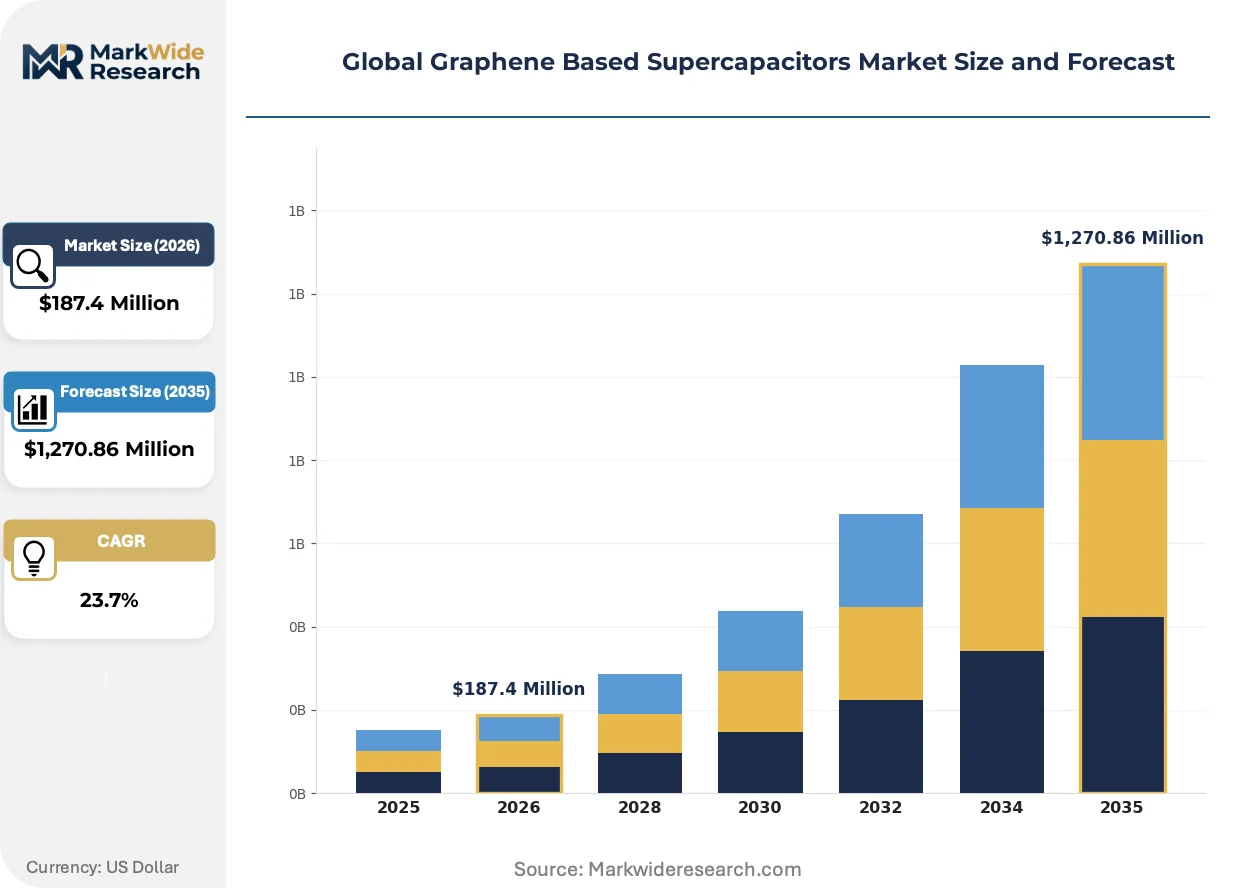
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Hybrid, Pseudocapacitor, Supercapattery End User: Consumer Electronics, Automotive, Renewable Energy, Industrial Technology: Graphene Nanocomposite, Aerogel, Conductive Polymer, Metallic Application: Energy Storage, Power Backup, Electric Vehicles, Mobile Devices |
| Companies Covered | Skeleton Technologies, Nanotech Energy, Huawei Technologies, Global Graphene Group, Graphenea, CRRC, Sunvault Energy, XG Sciences, Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graphene Based Supercapacitors Market Emerging Trajectories
Graphene supercapacitor electrode engineering is advancing through three concurrent pathways: nanocomposite formulation, thermal interface materials, and procurement model restructuring. Each pathway carries distinct competitive implications for module assemblers and raw material suppliers.
Graphene aerogel thermal interfaces are rewriting grid-scale storage design conventions. These materials conduct heat across electrode stacks without fluorinated-gas coolants, enabling compact module geometries. German utility EPCs are specifying aerogel-compliant designs for frequency regulation installations. This thermal architecture is compressing cooling system footprints by half while satisfying EU F-Gas phase-out deadlines.
REACH substance authorization and EU Green Deal carbon border adjustments are tightening material provenance documentation. Electrode manufacturers must now trace graphene flake origin through chemical vapor deposition or mining sources. Supply chain visibility investments are diverting working capital from capacity expansion. German automotive OEMs are demanding batch-level carbon intensity certificates before qualifying new supercapacitor vendors.
Long-term supply contracting is displacing spot purchasing in automotive procurement. Bus and tram builders in Estonia and Germany are signing five-year electrode supply agreements with fixed volume corridors. This commitment structure locks in manufacturing capacity at qualified suppliers while transferring price volatility risk to module assemblers. Skeleton Technologies has anchored this model through captive production clusters serving continental OEMs.
Global Graphene Based Supercapacitors Market Segmentation
Graphene supercapacitor architectures fragment across electrochemical mechanisms, thermal integration depths, and customer procurement specifications. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape competitive positioning.
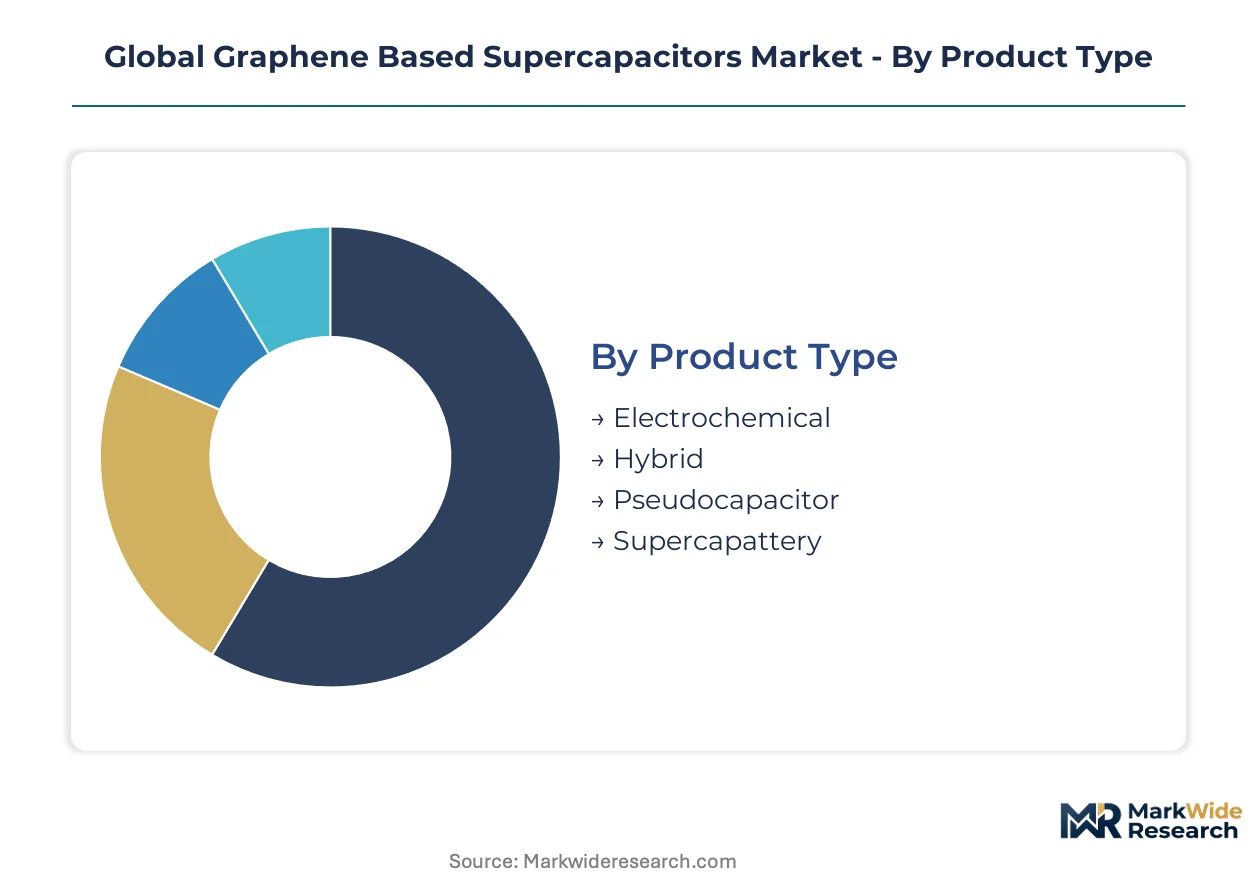
Product Type:
Standalone electrochemical cells dominate utility-scale frequency regulation, while hybrid and supercapattery variants embed into electric vehicle powertrains where space constraints demand multi-functional energy storage.
- Electrochemical:Double-layer capacitance at electrode-electrolyte interfaces delivers power densities exceeding 10 kW per kilogram with cycle stability surpassing one million events. German tram manufacturers specify these modules for regenerative braking where verified longevity outweighs upfront cost premiums.
- Supercapattery:Hybrid architectures converge battery energy density with supercapacitor power density, opening electric vehicle applications previously locked to pure electrochemical cells. China's rail sector procurement channels absorb these modules for regenerative energy capture across expanding high-speed networks.
- Hybrid:Intermediate formulations balance cost and performance for industrial uninterruptible power supply systems.
- Pseudocapacitor:Faradaic charge transfer mechanisms serve niche burst-power applications in precision manufacturing equipment.
Volume placements concentrate in Electrochemical; the faster expansion belongs to Supercapattery.
End User:
Cost tiers separate premium automotive qualification pathways from volume-driven consumer electronics procurement, with renewable energy and industrial segments occupying intermediate pricing bands.
- Automotive:OEM procurement contracts compress supplier qualification timelines and force electrode manufacturers to co-locate near vehicle assembly clusters. Skeleton Technologies anchors Estonian-German production clusters serving continental bus and tram builders with five-year fixed-volume supply agreements.
- Renewable Energy:Grid-scale frequency regulation contracts reward sub-second response times inaccessible to conventional storage. California and German utility EPCs tender burst-power services that specify graphene aerogel thermal interfaces compliant with EU F-Gas phase-out deadlines.
- Consumer Electronics:Lower-margin volume category driven by mobile device manufacturers seeking bridge power for peak load smoothing.
- Industrial:Manufacturing automation and uninterruptible power supply systems demand proven cycle life under harsh thermal cycling conditions.
Revenue margins peak in Automotive; Renewable Energy climbs the fastest as utility procurement scales.
Technology:
Application specificity determines technology selection, with nanocomposite electrodes serving high-cycle automotive demands and aerogel architectures addressing thermal management constraints in grid-connected installations.
- Graphene Nanocomposite:Electrode formulations integrate graphene flakes with activated carbon or conductive polymers to optimize surface area and conductivity trade-offs. Nanotech Energy anchors North American demand through California-based production serving fast-charge bus fleet operators.
- Aerogel:Ultra-light thermal interfaces conduct heat across electrode stacks without fluorinated-gas coolants, compressing cooling system footprints by half. German utility specifications mandate aerogel-compliant designs for frequency regulation installations facing EU F-Gas Regulation deadlines.
- Conductive Polymer:Flexible electrode substrates enable conformable supercapacitor geometries for wearable electronics applications.
- Metallic:High-conductivity current collectors support extreme power density requirements in heavy-duty industrial equipment.
Commercial maturity centers on Nanocomposite; Aerogel gains share fastest as thermal regulations tighten.
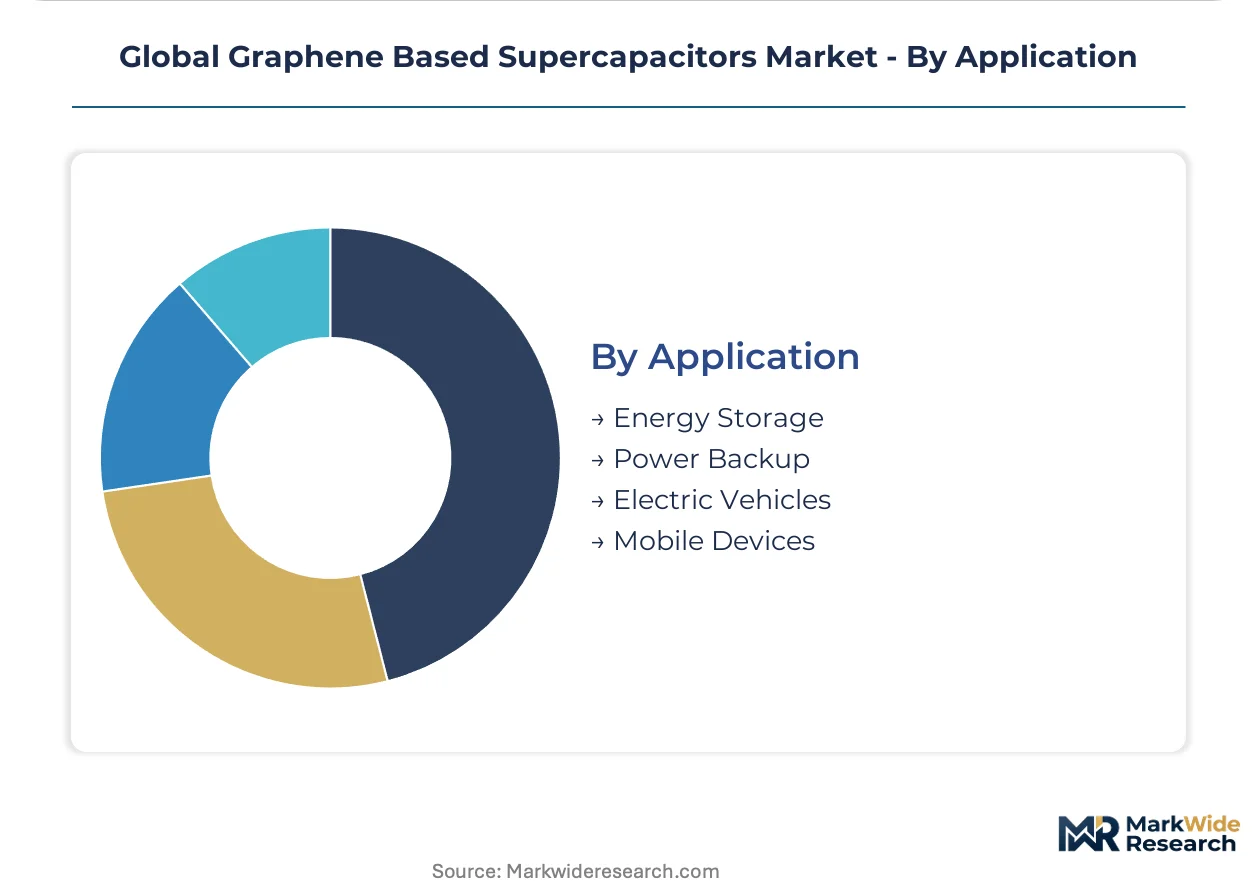
Application:
Customer type separates enterprise procurement with multi-year contracting horizons from consumer markets characterized by spot purchasing and rapid product obsolescence.
- Energy Storage:Utility-scale frequency regulation concentrates margin pools through long-term service contracts. Grid operators in Germany and California specify sub-second response capabilities that exclude lithium-ion alternatives from burst-power tenders.
- Electric Vehicles:Regenerative braking systems demand modules with verified million-cycle stability under dynamic charge-discharge profiles. CRRC dominates rail-sector deployments, controlling procurement channels for China's expanding electric locomotive fleet.
- Power Backup:Industrial uninterruptible power supply systems prioritize reliability metrics over energy density optimization.
- Mobile Devices:Bridge power applications for peak load smoothing operate on compressed qualification timelines and price-sensitive procurement.
Contract value concentrates in Energy Storage; Electric Vehicles show the steepest expansion trajectory as fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dresden anchors European graphene supercapacitor manufacturing through Skeleton Technologies' production cluster serving automotive OEMs across the continent.
Germany
Automotive OEM procurement contracts compress supplier qualification timelines for regenerative braking modules. EU F-Gas Regulation mandates fluorinated-gas-free thermal management in grid-connected storage. The Dresden production corridor concentrates electrode fabrication capacity serving continental tram and bus builders.
China
Rail-sector procurement channels absorb electrochemical double-layer modules for regenerative energy capture across expanding high-speed networks. MIIT enforces GB standards for energy density and safety testing that block uncertified imports. CRRC dominates electric locomotive deployments through controlled procurement channels.
United States
California nanocomposite electrode production scales to serve fast-charge bus fleet operators demanding verified million-cycle stability. FERC market rules reward sub-second frequency regulation response times inaccessible to conventional storage. Nanotech Energy anchors North American demand through its California-based graphene nanocomposite operations.
India
BIS certification requirements under the PLI scheme for advanced chemistry cell manufacturing redirect capital toward domestic electrode production. The national regulator enforces standards that favor localized anode fabrication capacity. Industrial corridors in Gujarat and Tamil Nadu attract electrode manufacturing investments.
Estonia
Five-year fixed-volume supply agreements lock in manufacturing capacity for qualified suppliers serving continental OEMs. The country's manufacturing footprint sustains long-term contracts with European tram and bus builders. Tallinn anchors production clusters integrated with German automotive supply chains.
Global Graphene Based Supercapacitors Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and cycle-life verification tiers. The supply base separates into electrochemical cell specialists with proven manufacturing repeatability and pseudocapacitor assemblers facing price competition. Three archetypes dominate: integrated electrode-to-module fabricators, nanocomposite formulation specialists, and rail-sector system integrators. Capacity co-location near vehicle assembly clusters and captive graphene flake supply represent the dominant competitive moves.
Within the integrated fabrication tier, Skeleton Technologies and CRRC exemplify divergent geographic anchoring strategies. Nanotech Energy occupies a position among nanocomposite specialists serving fast-charge transportation applications. These three entities represent distinct competitive positions without overlapping segment focus.
| Leading Market Players |
|---|
| Skeleton Technologies |
| Nanotech Energy |
| Huawei Technologies |
| Global Graphene Group |
| Graphenea |
| CRRC |
| Sunvault Energy |
| XG Sciences |
| Cabot Corporation |
| Others |
Supply Flow & Price Mechanics
Electrochemist talent scarcity in Germany and Estonia widens labor-cost differentials that stratify pricing tiers across electrochemical cell grades. Premium electrode formulations command substantial markups where qualified formulation specialists validate million-cycle stability, while commodity pseudocapacitor assemblies face margin compression from price competition.
Pricing Analysis
Verified cycle-life outcomes anchor value-based pricing for automotive OEM procurement contracts, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation stems from GB standard compliance tier and captive graphene flake supply integration. Cost compression in commodity pseudocapacitor tiers intensifies as mining-dependent feedstock volatility transfers downstream. Consumer electronics manufacturers exhibit highest price sensitivity; utility frequency regulation contractors accept premium positioning for sub-second response guarantees.
Supply Chain Analysis
India's PLI scheme domestic-content mandates and China's MIIT localization requirements are redirecting electrode fabrication capacity toward certified domestic producers. Supply concentrates in Germany, China, and Estonia for qualified module assembly, with high-purity graphene flake feedstock drawing from chemical vapor deposition facilities and mining operations. Single-source vulnerability in high-purity flake supply creates input cost volatility when capacity tightens. Distribution runs through long-term fixed-volume agreements locking in manufacturing corridors near vehicle assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrode fabrication capacity bottlenecks in certified supply corridors prop pricing power for qualified producers. Limited electrochemist availability constrains R&D velocity, extending supplier qualification timelines for automotive OEMs.
For Market Incumbents: Hedge against lithium-ion energy density improvements above 300 Wh per kilogram by deepening backward integration into graphene flake supply and securing captive chemical vapor deposition capacity. Reinforce certification moats through GB standard and REACH substance authorization investments that block uncertified imports. For New Entrants and Emerging Players: Launch via utility-scale frequency regulation service contracts in California and Germany where FERC and EU Green Deal regulations reward sub-second response capabilities. Target India's PLI scheme electrode localization corridor as the most penetrable geography, leveraging BIS certification pathways to capture domestic anode production incentives. For Investors and Strategic Acquirers: The window for entry favors integrated electrode-to-module fabricators with captive supply chains and established OEM qualification relationships. Long-term viability centers on five-to-ten-year contracting structures that lock in volume corridors and transfer price volatility risk downstream. Watch for divergence between Brussels and Beijing carbon footprint disclosure requirements as the signal indicating supply chain documentation cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphene Flake Supply | Captive chemical vapor deposition capacity insulates electrode fabricators from mining-source volatility. |
| GB Standard Certification Investment | MIIT compliance unlocks procurement channels for China's expanding electric locomotive fleet deployments. |
| Long-term Supply Agreement Structuring | Five-year fixed-volume contracts with German tram builders lock in manufacturing capacity corridors. |
| Aerogel Thermal Interface Development | EU F-Gas Regulation compliance enables frequency regulation tender participation by German utility EPCs. |
| Electrode Production Cluster Co-location | Proximity to Dresden vehicle assembly compresses logistics costs for continental OEM qualification timelines. |
Methodological Framework
Document review covered SEC filings from energy storage developers, EU F-Gas Regulation implementation guidance, and MIIT GB standard documentation, complemented by interviews with electrode fabrication plant managers, automotive OEM procurement leads, utility EPC planning officers, and graphene flake supply specialists. Secondary validation drew from customs trade data, FERC market rule filings, and IEA grid storage deployment databases. Bottom-up module shipment estimates triangulated against top-down energy storage investment flows across the analysis window.
Historical capacity expansion patterns cross-referenced against panel input from electrode formulation specialists and rail-sector system integrators shaped the analytical framework. Segmentation modeling spanned product type, end-user vertical, thermal integration technology, and regional regulatory cluster dimensions. CAGRs derived from slope analysis of procurement contract volumes and utility tender awards throughout the forecast period, with electrochemist labor availability and certification timeline data serving as industry-specific forecast inputs.
Feedstock supply disruptions, regulatory divergence between Brussels and Beijing on carbon disclosure, and lithium-ion cost-performance parity advances are the dominant revision risks that could compress supercapacitor positioning in longer-duration applications. Forecasts reflect documented assumptions on OEM qualification velocity and utility procurement scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Nanoclay Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Single-Walled Carbon Nanotube (SWCNT) Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market