
 Titanium Dioxide Nanomaterials Market | 2026-2036
Titanium Dioxide Nanomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Dioxide Nanomaterials Market Intelligence
Asset-light toll manufacturing and third-party nano-milling partnerships are reconfiguring competitive entry barriers for mid-scale producers. American Elements leverages vertical integration from metal sponge to nanopowder, sustaining cost control across the supply chain. Xuancheng Jingrui New Material Co. Ltd. dominates regional nano-TiO2 output through captive ilmenite processing in Anhui province.
Titanium dioxide nanomaterials are crystalline or amorphous particles sized between 1 and 100 nanometers, typically synthesized via sol-gel, hydrothermal, or flame pyrolysis routes, valued for their high refractive index, photocatalytic activity, and UV absorption. The primary commercial purpose centers on functional surface coatings and light-scattering applications where bulk TiO2 performance proves insufficient. Coatings and pigments together anchor the product landscape, with UV protection and whitening agent applications commanding premium pricing due to stringent photostability requirements. Powder form leads volume shipments, though aqueous dispersions are gaining share in cosmetics formulation.
REACH registration and the EU Cosmetics Regulation govern nano-TiO2 placement in European personal care products, while the FDA monitors sunscreen active ingredient safety through ongoing monograph revisions. China's GB standards and NMPA cosmetic ingredient filings add compliance layers for import-dependent brands. Stakeholders must track regulatory divergence between photostability testing protocols and nano-specific labeling mandates to anticipate reformulation costs and market access timelines.
Market Dynamics
REACH compliance deadlines and FDA monograph revisions are compressing reformulation cycles while China and Japan maintain upstream nano-powder concentration, creating asymmetric access to high-purity feedstock for Western formulators.
Growth Catalysts
- Photocatalytic coatings:Self-cleaning building facades and antimicrobial surfaces in healthcare infrastructure are absorbing nano-TiO2 at elevated volumes, particularly in GCC states deploying smart city mandates.
- EU Cosmetics Regulation:Permitted nano-TiO2 use in sunscreens under specific labeling and safety conditions sustains premium personal care demand despite broader ingredient scrutiny.
- Flame pyrolysis advancement:Continuous production methods with tighter particle size distribution are reducing batch-to-batch variability for electronics-grade applications.
Market Restraints
- Ilmenite supply concentration:Captive processing in Anhui province and select Australian deposits limits independent feedstock access for European and North American nano-milling operations.
- ECHA nano-specific dossier requirements:Extended toxicological testing timelines and data gap closures add 18-36 months to new product registrations in the European Economic Area.
- Zinc oxide substitution:Mineral UV filter alternatives with comparable transparency profiles are capturing reformulation budgets in natural-positioned cosmetics lines.
Strategic Opportunities
- Saudi Arabia construction surge:NEOM and Red Sea Project concrete specifications incorporating photocatalytic air-purifying additives represent uncontracted volume for specification-grade nano-TiO2.
- India PLI scheme for advanced materials:Domestic nano-powder production incentives could localize supply for subcontinent coatings and personal care manufacturing expansion.
- Sol-gel aqueous dispersion convergence:Direct cosmetic formulation compatibility eliminates downstream milling steps and opens toll manufacturing partnerships with mid-scale beauty brands.
Industry Challenges
- Particle metrology expertise scarcity:Accurate DLS and BET characterization for regulatory submissions requires specialized analytical chemists concentrated in legacy industrial centers.
- Photostability certification timelines:ISO 24443 and COLIPA method validation for nano-TiO2 sunscreen efficacy extends product development cycles by 12-18 months.
- Legacy pigment integration:Reformulating established coating lines for nano-enhanced performance without process line reconfiguration creates technical service bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Dioxide Nanomaterials Market |
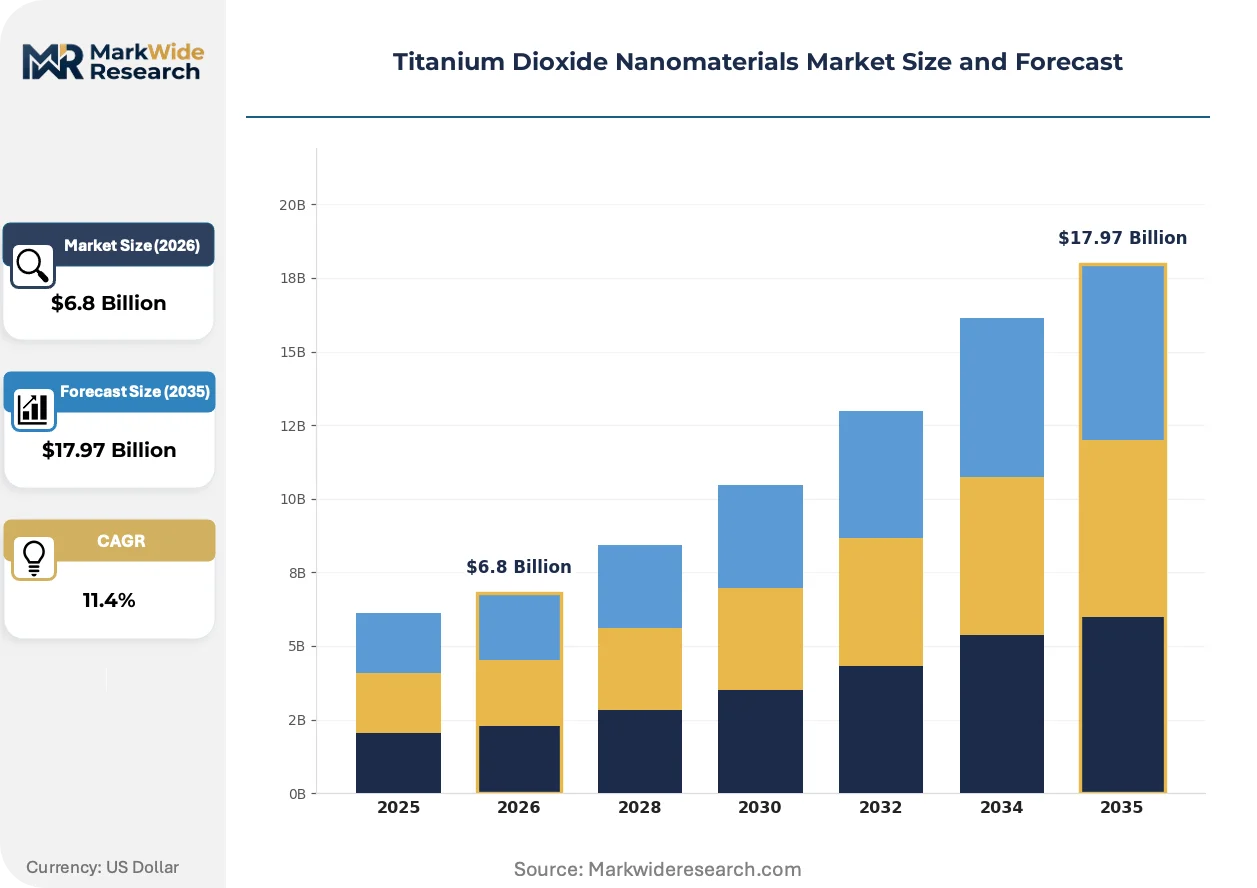
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Pigments, Additives, Inks End Use Industry: Cosmetics, Paints, Plastics, Food Form: Powder, Suspension, Dispersion, Granules Application: UV Protection, Whitening Agent, Catalysis, Antibacterial |
| Companies Covered | ACS Material LLC, Altair Nanotechnologies Inc., US Research Nanomaterials Inc., Skyspring Nanomaterials Inc., Sigma-Aldrich Corporation, American Elements, MK Nano, Shanghai Xiaoxiang Chemicals Co., Xuancheng Jingrui New Material Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Dioxide Nanomaterials Market Strategic Shifts & Innovations
Surface functionalization chemistry and dispersion stability engineering are displacing commodity nano-powder sales, with value capture migrating toward formulation-ready intermediates and application-specific grades.
Hydrophobic silane-treated nano-TiO2 is migrating from specialty sunscreens toward mass-market daily wear cosmetics as Korean and Japanese beauty houses accelerate SPF-in-moisturizer launches. The shift compresses raw material differentiation toward surface chemistry IP rather than core particle synthesis.
REACH annex revisions and impending nano-specific hazard classification updates are forcing inventory segregation and dual-labeling investments across EU distribution networks. Personal care contract manufacturers with multi-brand portfolios face the steepest compliance cost escalation.
Direct procurement from Chinese nano-powder specialists via Alibaba and vertical B2B platforms is fragmenting traditional distributor relationships in North American coatings sectors. Small-batch cosmetic formulators in California and New York now source dispersed grades without regional intermediary markup.
Titanium Dioxide Nanomaterials Market Segmentation
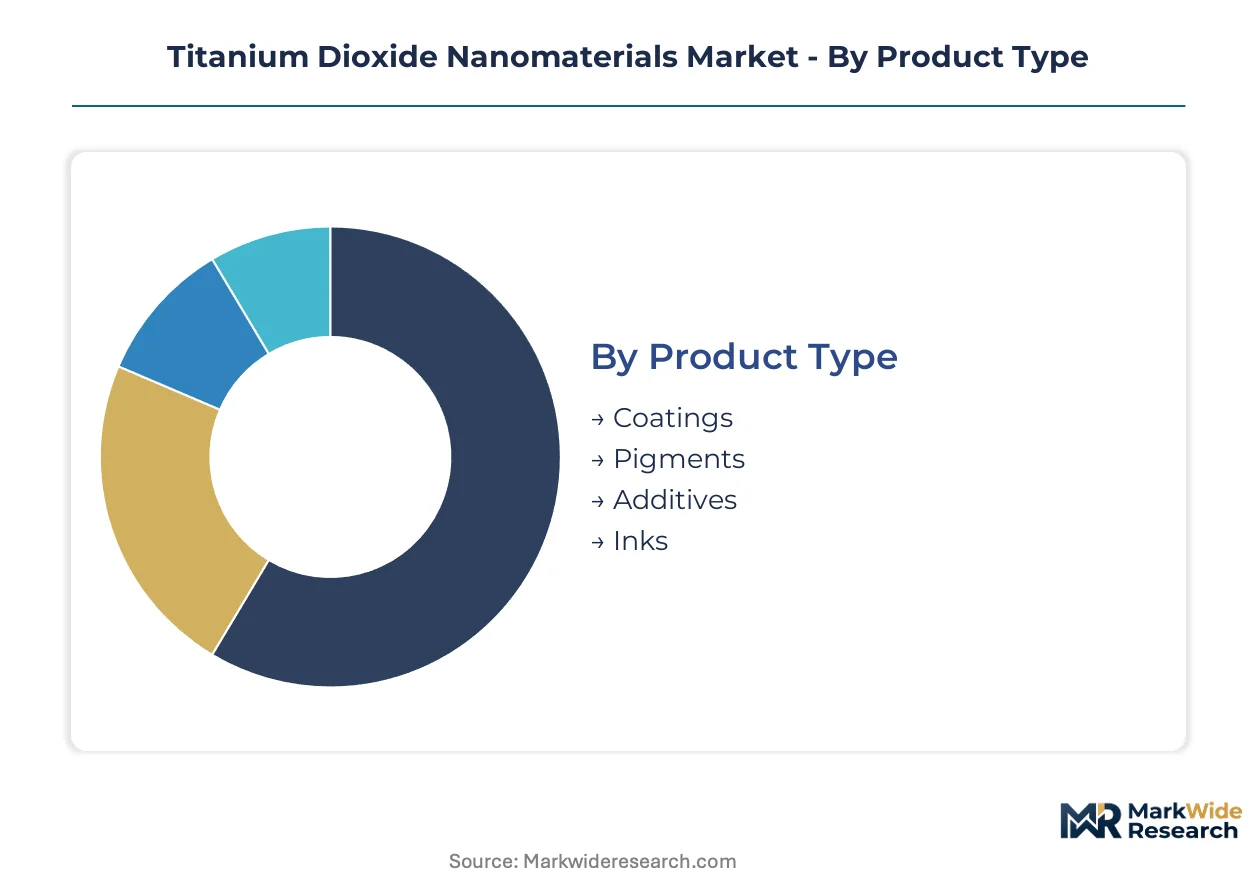
Segmentation in titanium dioxide nanomaterials reveals how technical specifications diverge across regulatory environments and end-use performance thresholds. Formulators select grades based on photostability certification requirements, particle size distribution tolerances, and regional compliance frameworks rather than commodity pricing alone.
Product Type:
Use-case spectrum spans architectural self-cleaning surfaces requiring photocatalytic activation to food-grade whitening where purity thresholds exclude surface-treated variants.
- Coatings:Photocatalytic and UV-blocking formulations dominate specification-grade demand, with NEOM project concrete additives in Saudi Arabia absorbing volumes for air-purifying facade applications. Technical service requirements for substrate compatibility extend sales cycles but lock in multi-year supply agreements.
- Pigments:High-refractive-index grades for premium cosmetics and electronics packaging command margin premiums through tight particle size control below 50 nanometers. Korean beauty houses drive formulation innovation toward SPF-integrated daily wear products.
- Additives:Functional fillers for polymer masterbatches enhance mechanical properties and weather resistance in automotive and construction plastics.
- Inks:Specialized dispersions for security printing and high-resolution digital applications leverage nano-TiO2 opacity at reduced film thickness.
The dominant share belongs to Coatings, while Pigments is closing the gap fastest.
End Use Industry:
Cost tier stratification separates pharmaceutical-grade cosmetic applications from industrial coating volumes, with certification burden determining margin structure.
- Cosmetics:Sunscreen and daily wear formulations under EU Cosmetics Regulation and FDA monograph oversight require ISO 24443 photostability validation. REACH nano-specific labeling mandates in Europe add compliance costs that fragment contract manufacturing relationships.
- Paints:Architectural and industrial coating lines integrate nano-TiO2 for durability and self-cleaning functionality, particularly in GCC smart city deployments.
- Plastics:Polymer stabilization and UV protection in packaging and automotive components leverage masterbatch dispersion compatibility.
- Food:EFSA-approved grades for whitening and opacity face strict purity limits that exclude surface-functionalized variants common in cosmetic applications.
Cosmetics commands premium pricing tiers, though Paints demonstrates the steepest volume expansion trajectory in emerging market infrastructure.
Form:
Supply concentration in Anhui province powder production shapes downstream dispersion economics for Western formulators lacking captive nano-milling capacity.
- Powder:Unprocessed nano-TiO2 from Chinese specialists via Alibaba and vertical B2B platforms fragments traditional distributor relationships, enabling direct procurement by small-batch California and New York cosmetic formulators.
- Suspension:Aqueous systems for coating line integration reduce dust handling requirements and accelerate production throughput in continuous manufacturing environments.
- Dispersion:Pre-milled cosmetic-grade products eliminate downstream processing steps, opening toll manufacturing partnerships with mid-scale beauty brands seeking formulation-ready intermediates.
- Granules:Compacted forms for polymer masterbatch feeding address dust containment and handling efficiency in high-volume plastics operations.
Powder retains volume leadership, yet Dispersion is expanding most quickly through cosmetics toll manufacturing partnerships.
Application:
Maturity differentiation separates established UV protection markets from emerging catalytic deployment in healthcare and environmental remediation.
- UV Protection:Mineral sunscreen actives face zinc oxide substitution pressure in natural-positioned cosmetics lines, though nano-TiO2 maintains transparency advantages at high SPF ratings.
- Whitening Agent:Toothpaste and personal care applications require specialized surface treatments to prevent photocatalytic degradation of organic ingredients in formulation.
- Catalysis:Self-cleaning building materials and water treatment systems exploit photocatalytic oxidation, with Japanese and Korean infrastructure projects specifying performance-tested grades.
- Antibacterial:Healthcare surface coatings and textile treatments leverage reactive oxygen species generation under UV activation for pathogen reduction.
UV Protection holds established revenue concentration, while Catalysis is gaining share fastest through GCC infrastructure mandates and Asian smart city investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances define regional positioning. Chinese nano-powder specialists supply dispersed grades directly to Western formulators, compressing traditional distributor margins. European and North American producers face feedstock access constraints against concentrated upstream capacity in East Asia.
China
NEOM project concrete additives and photocatalytic coating demand in GCC states absorb specification-grade volumes from Anhui province operations. NMPA cosmetic ingredient filings and GB standards govern nano-TiO2 placement in personal care products. Xuancheng Jingrui New Material Co. Ltd. maintains captive ilmenite processing capacity that limits independent feedstock access for competing operations.
United States
California and New York cosmetic formulators source dispersed grades via Alibaba and vertical B2B platforms without regional intermediary markup. FDA sunscreen monograph revisions compress reformulation cycles for mineral UV filter applications. Small-batch beauty brands in Los Angeles and Brooklyn accelerate toll manufacturing partnerships for SPF-integrated daily wear products.
Germany
REACH compliance deadlines and ECHA nano-specific dossier requirements extend toxicological testing timelines for new product registrations. Photostability certification under ISO 24443 and COLIPA methods validates sunscreen efficacy for export-oriented cosmetics manufacturers. Industrial coating lines in North Rhine-Westphalia integrate nano-TiO2 for durability specifications in automotive and construction applications.
Japan
Korean and Japanese beauty houses drive formulation innovation toward SPF-in-moisturizer launches, compressing raw material differentiation toward surface chemistry IP. METI standards and JIS specifications govern electronics-grade nano-powder production for high-resolution digital applications. Infrastructure projects in Kansai and Chubu regions specify performance-tested photocatalytic grades for self-cleaning building materials.
Saudi Arabia
NEOM and Red Sea Project concrete specifications incorporate photocatalytic air-purifying additives, representing uncontracted volume for specification-grade nano-TiO2. SFDA cosmetic regulations align with GCC standardization frameworks for mineral sunscreen ingredient approvals. Construction surge in Riyadh and the Western Region absorbs elevated volumes of antimicrobial surface coatings for healthcare infrastructure.
Titanium Dioxide Nanomaterials Market Key Industry Players
On the supply side, the industry is consolidating around upstream control over ilmenite processing and captive nano-milling capacity. Strategic archetypes span vertically integrated metal-to-nanopowder operators, regional nano-powder specialists with captive mineral processing, and toll manufacturing partners offering formulation-ready dispersions. Dominant competitive moves include backward integration into ilmenite supply and direct-to-formulator platform sales that disintermediate traditional distribution.
Among US-based material suppliers, American Elements exemplifies vertical integration from metal sponge through nanopowder synthesis. Chinese specialists occupy critical positions in upstream nano-powder production, with Xuancheng Jingrui New Material Co. Ltd. representing regional concentration through captive Anhui province operations. Sigma-Aldrich Corporation sits within the research-grade and laboratory supply tier, serving formulation development rather than commodity volume markets.
| Leading Market Players |
|---|
| ACS Material LLC |
| Altair Nanotechnologies Inc. |
| US Research Nanomaterials Inc. |
| Skyspring Nanomaterials Inc. |
| Sigma-Aldrich Corporation |
| American Elements |
| MK Nano |
| Shanghai Xiaoxiang Chemicals Co. |
| Xuancheng Jingrui New Material Co. Ltd. |
| Others |
Cost & Logistics Intelligence
REACH annex revisions and nano-specific hazard classification updates create dual-labeling inventory segregation costs that simultaneously widen premium-economy pricing spreads and force contract manufacturers toward captive dispersion capacity or third-party toll partnerships.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with photostability certification under ISO 24443 and COLIPA methods separating specification-grade cosmetic inputs from commodity coating powders. Price differentiation rests on surface functionalization chemistry and particle size distribution control below 50 nanometers. Cost compression in standard-tier powders is intensifying because direct Alibaba procurement by small-batch formulators fragments traditional distributor markups. Contract cosmetic manufacturers exhibit the highest price sensitivity due to multi-brand compliance cost escalation, while electronics-grade buyers absorb premiums for tighter batch-to-batch variability.
Supply Chain Analysis
Toll manufacturing partners with aqueous dispersion capability in Anhui province, California, and North Rhine-Westphalia hold critical formulation-ready capacity. Raw material dependencies draw from captive ilmenite processing in Anhui, Australian mineral sands, and Japanese METI-certified electronics-grade feedstock. Single-source vulnerability concentrates in Xuancheng Jingrui's captive ilmenite operations, limiting independent feedstock access for European nano-milling operations. Distribution runs through direct B2B platform sales disintermediating regional distributors, with Alibaba and vertical portals fragmenting traditional channel relationships in North American coatings sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as regulatory divergence between REACH, FDA monograph revisions, and China's NMPA filings forces multi-jurisdictional formulators toward specialized compliance service providers and regional dispersion specialists.
For Market Incumbents: Entrench specification-grade positioning through backward integration into ilmenite supply or captive nano-milling partnerships that lock in feedstock security against Anhui province concentration. American Elements' metal-sponge-to-nanopowder model demonstrates margin defense through upstream control. Invest in ISO 24443 photostability certification capacity to capture reformulation cycles compressing under FDA monograph timelines. For New Entrants and Emerging Players: Establish a beachhead in sol-gel aqueous dispersion toll manufacturing for mid-scale Korean and Japanese beauty brands accelerating SPF-in-moisturizer launches. The uncontracted NEOM and Red Sea Project volume in Saudi Arabia represents the most penetrable infrastructure segment for specification-grade photocatalytic grades. Pursue direct platform sales via Alibaba and vertical B2B channels to bypass traditional distributor relationships and capture small-batch California and New York cosmetic formulators. For Investors and Strategic Acquirers: Regional nano-powder specialists with captive mineral processing and NMPA-compliant dispersion capacity offer the strongest acquisition profile for long-term viability across the 5-10 year window. Watch for India's PLI scheme for advanced materials triggering domestic nano-powder production incentives that could localize supply and reshape subcontinent manufacturing economics. The signal to monitor is ECHA nano-specific dossier requirement enforcement intensity, which extends toxicological testing timelines and creates captive capacity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ilmenite Supply | Captive mineral processing in Anhui or Australian deposits secures feedstock independence against upstream concentration. |
| Photostability Certification Investment | ISO 24443 and COLIPA method validation captures reformulation cycles under FDA monograph compression. |
| Toll Manufacturing Partnership Expansion | Aqueous dispersion capacity opens mid-scale beauty brand relationships seeking formulation-ready intermediates. |
| Direct Platform Sales Channel Development | Alibaba and vertical B2B presence fragments traditional distributor margins in North American coatings. |
| Regional Compliance Service Capability | Multi-jurisdictional REACH, FDA, and NMPA expertise captures regulatory divergence cost escalation. |
Research Approach
A spread of perspectives from nano-powder plant managers, cosmetics formulation R&D directors, coatings procurement leads at industrial OEMs, and regulatory affairs specialists at contract manufacturers converged on the working assumptions. Primary fieldwork combined with secondary validation from ECHA registration databases, FDA sunscreen monograph dockets, China's NMPA cosmetic ingredient filings, and SEC 10-K disclosures from listed material suppliers. Bottom-up volume modeling triangulated against top-down market sizing across grade tier, end-use industry, and regional regulatory cluster dimensions.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with capacity utilization at Anhui province operations and NEOM project concrete specifications serving as industry-specific forecast inputs. Segmentation dimensions modeled included product type, end-use industry, form, and application, with CAGRs derived from regression analysis against historical volume trajectories and capacity expansion announcements. Price elasticity assumptions incorporated direct procurement platform penetration and toll manufacturing partnership growth rates.
Sensitivities concentrate around REACH annex revision timing, FDA monograph finalization schedules, and ilmenite supply disruptions from Australian mineral sands operations. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure project award timelines. Quarterly review of ECHA nano-specific dossier submission rates, NMPA cosmetic ingredient filing volumes, and GCC smart city mandate implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Nanoparticle Contract Manufacturing Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Nano Copper Oxide Market