
 Myanmar Residential Real Estate Market | 2026-2036
Myanmar Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Residential Real Estate Market Foresight
Market Context
First-time buyers from Yangon's emerging middle class is collapsing the historical dominance of speculative investors in Myanmar's residential property landscape. Dagon Group leverages its integrated construction-to-sales pipeline across multiple Yangon townships. FMI Garden Development anchors its position through exclusive garden-style compound developments targeting family segments. Shwe Taung Group competes via diversified exposure across infrastructure-adjacent residential zones.
Technical and Structural Dimensions
Myanmar residential real estate encompasses purpose-built dwellings including condominiums, villas, townhouses, and serviced land plots designed for human habitation, typically constructed with reinforced concrete frames, brick infill, and aluminum glazing systems suited to tropical monsoon climates. Condominiums dominate transaction volume in Yangon and Mandalay as urban land scarcity intensifies vertical development patterns. Mid-range properties capture the fastest buyer growth as mortgage accessibility expands through Myanmar's banking sector reforms. Luxury and high-end segments concentrate margin pools around diplomatic zones and golf course peripheries where foreign buyer quotas apply.
Regulatory Environment
Myanmar's Directorate of Investment and Company Administration, the Myanmar Investment Commission, and municipal development affairs committees collectively shape residential market access through foreign ownership ceilings, construction permitting timelines, and land use conversion protocols. The condominium law framework restricts foreign freehold to 40 percent of units per building, directly channeling developer product mix toward domestically absorbable unit sizes and price points. Stakeholders must monitor pending urban planning code revisions and infrastructure corridor announcements to anticipate demand migration patterns before competing capital positions.
Market Dynamics
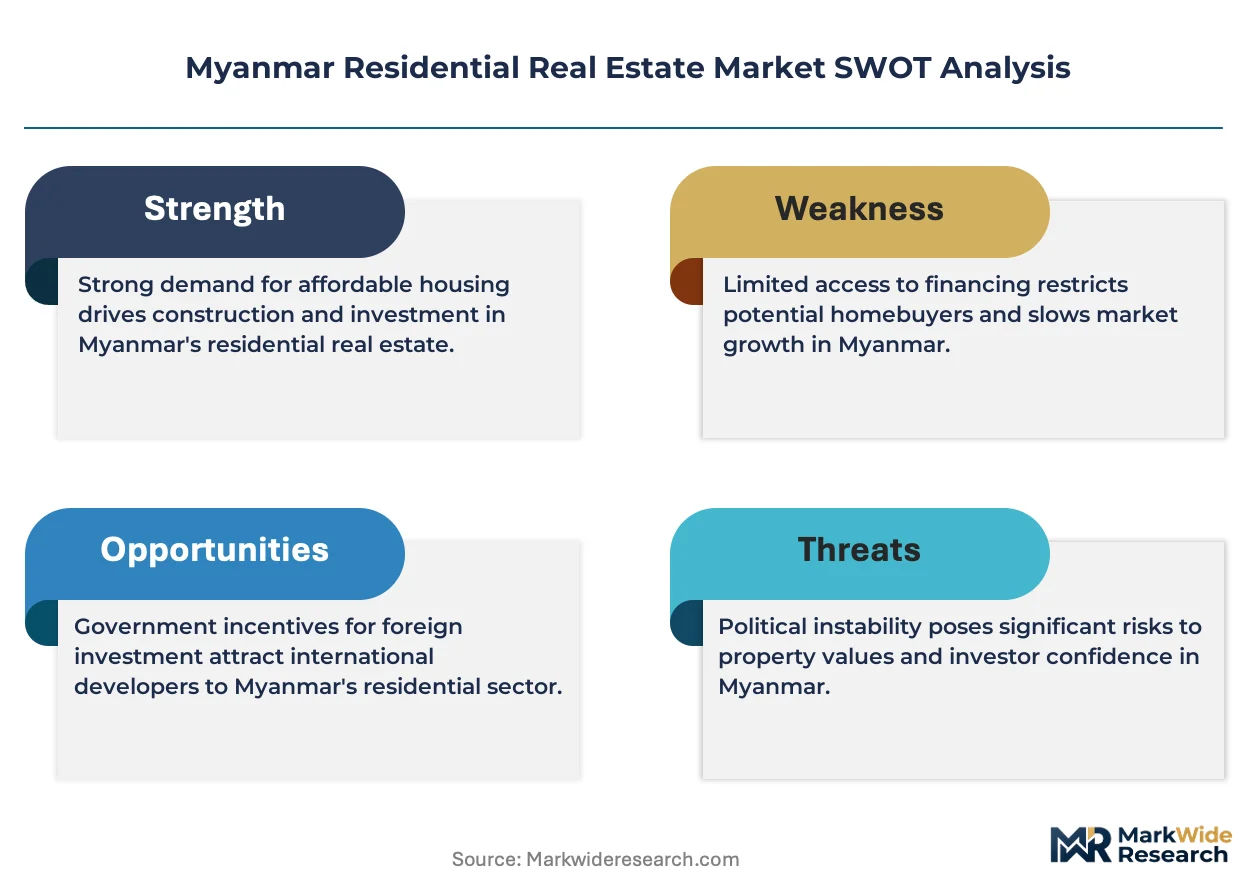
Yangon's emerging middle class is displacing speculative investors as the dominant transaction force, while the Myanmar Investment Commission's revised condominium ownership rules for foreigners are compressing developer product strategies toward domestically absorbable unit configurations.
Growth Catalysts
- Myanmar Investment Commission Condominium Revisions:The 40 percent foreign ownership ceiling is channeling developer capital toward mid-range unit sizes that domestic first-time buyers can absorb through expanding mortgage accessibility.
- Thanlyin Infrastructure Corridor Expansion:Road and bridge connectivity improvements are unlocking satellite township absorption capacity where land costs remain below central Yangon levels.
- Banking Sector Mortgage Reforms:Domestic financial institutions are extending longer-tenor home loans to formal-sector employees, collapsing cash-only transaction dominance in the mid-market segment.
Market Restraints
- Reinforced Concrete Input Volatility:Import dependency for cement and steel reinforcement creates construction cost instability that developers cannot fully pass through to price-sensitive domestic buyers.
- Land Use Conversion Protocols:Municipal development affairs committees impose extended permitting timelines for agricultural-to-residential conversions, stretching project gestation periods in peripheral townships.
- Foreign Buyer Quota Saturation:Diplomatic zone and golf course periphery projects face demand ceilings where luxury unit supply exceeds eligible foreign purchaser pools.
Strategic Opportunities
- Dagon Seikkan Satellite Corridor:Industrial zone adjacency and port connectivity are creating absorption potential for workforce housing that current supply has not captured.
- Green Building Material Convergence:Cross-laminated timber and low-carbon concrete technologies are opening differentiation pathways for developers targeting environmentally conscious Yangon households.
- Digital Transaction Platforms:Property technology channels are compressing search-to-close timelines for domestic buyers unfamiliar with traditional broker-dependent processes.
Industry Challenges
- Construction Skilled Labor Scarcity:Reinforced concrete frame and aluminum glazing system installation expertise concentrates in Yangon, constraining quality execution in Mandalay and secondary city expansions.
- Condominium Law Compliance Complexity:Foreign ownership tracking and strata title management systems require legal function investments that smaller developers lack capital to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Residential Real Estate Market |
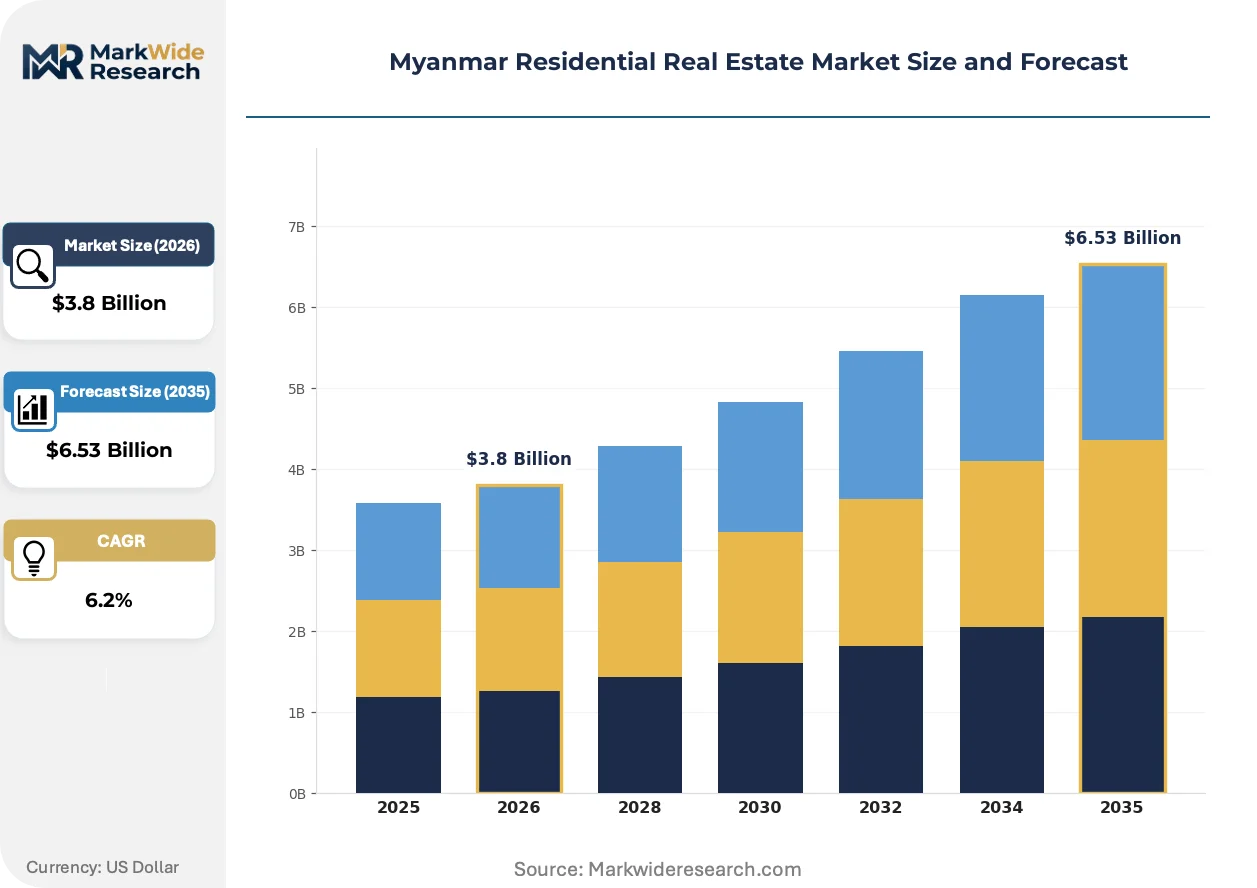
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominiums, Villas, Townhouses, Land Plots Price Range: Affordable, Mid-range, Luxury, High-end Investment Purpose: Rental Income, Resale, Personal Use, Commercial Use Buyer Type: Local Investors, Foreign Investors, First-time Buyers, Real Estate Developers |
| Companies Covered | Dagon Group, FMI Garden Development, Shwe Taung Group, Shwe Than Lwin Co., Capital Development Ltd., Yoma Strategic Holdings, Eden Group, Myanmar Seilone, Marga Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Residential Real Estate Market Shifts & Advancements
Technology adoption and buyer behavior evolution are compressing traditional transaction structures while regulatory frameworks force product configuration adaptations. Three forces are actively restructuring competitive positioning.
Smart home automation systems incorporating remote climate control and security monitoring are penetrating Yangon condominium developments. Young professional households in Thanlyin and Dagon Seikkan are specifying these features at accelerating rates. Developer differentiation is fragmenting across technology-enabled versus basic specification tiers, compressing margin pools for undifferentiated mid-range supply.
The Myanmar Investment Commission's condominium ownership framework is tightening enforcement mechanisms for foreign purchaser eligibility verification. Developers must now maintain dedicated compliance functions to track 40 percent unit quotas across buildings. Luxury and high-end segments in diplomatic zones are responding by embedding legal advisory services into sales processes, extending transaction timelines but reducing regulatory rejection risk.
First-time buyer preference is rotating away from speculative investment-grade units toward owner-occupied functional configurations. Family segments are prioritizing garden-style compounds and proximity to emerging school clusters over central Yangon appreciation potential. This behavioral pivot is most visible in Thanlyin, where infrastructure corridor announcements are preceding speculative capital flows that previously led physical development.
Myanmar Residential Real Estate Market Segmentation
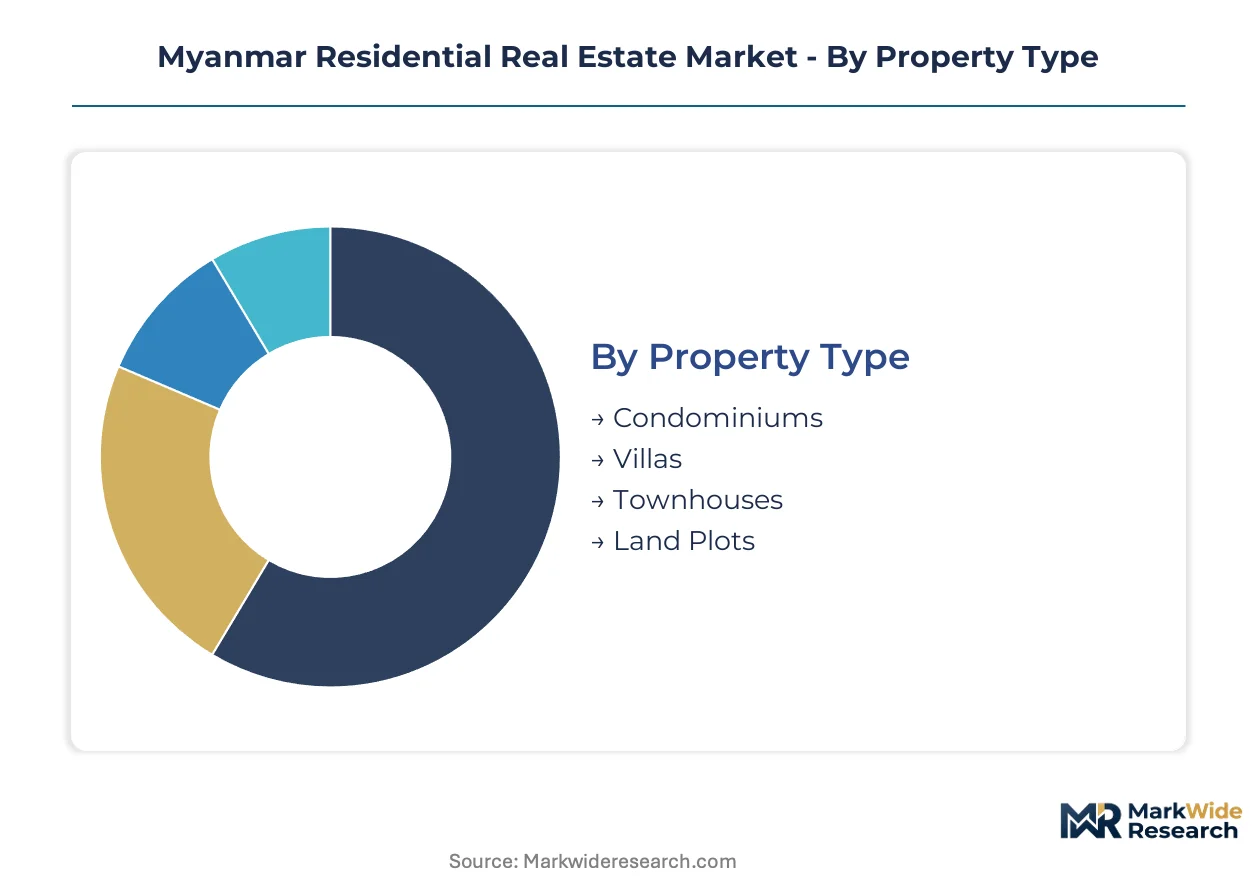
Segmentation in Myanmar's residential real estate market reveals how regulatory constraints and buyer behavior shifts are fragmenting demand across distinct product tiers. Understanding these divisions exposes where developer capital allocation faces the highest substitution risk from adjacent property classes.
Property Type:
Condominiums face intensifying substitution pressure from townhouses in Yangon's satellite corridors where land costs still permit horizontal development.
- Condominiums:Vertical dwellings constructed with reinforced concrete frames and aluminum glazing systems dominate transaction volume in central Yangon and Mandalay. Demand concentrates among first-time buyers in Thanlyin and Dagon Seikkan where the Myanmar Investment Commission's foreign ownership ceiling channels supply toward domestically absorbable unit sizes. Banking sector mortgage reforms are collapsing cash-only transaction dominance in this segment.
- Townhouses:Multi-story attached dwellings with private ground-level access are gaining preference among family segments prioritizing functional space over speculative appreciation. Demand clusters in Dagon Seikkan's industrial zone periphery where workforce housing supply remains underdeveloped relative to port connectivity improvements.
- Villas:Detached single-family residences with garden compounds anchor luxury positioning in diplomatic zones and golf course peripheries where foreign buyer quotas apply.
- Land Plots:Serviced residential land for custom construction attracts self-build investors navigating municipal development affairs committees' extended agricultural-to-residential conversion timelines.
Condominiums anchor the volume base while townhouses gain share at the steepest rate.
Price Range:
Cost tier stratification reflects the banking sector's expanding mortgage accessibility and its compression of cash-only market dominance.
- Mid-range:Properties priced for formal-sector employees accessing longer-tenor home loans represent the fastest buyer growth trajectory. Yangon's emerging middle class is displacing speculative investors as the dominant transaction force in this tier.
- Affordable:Entry-level units targeting income-constrained households face construction cost instability from cement and steel reinforcement import dependency that developers cannot fully pass through.
- Luxury:Premium specifications in infrastructure-adjacent zones concentrate margin pools where foreign ownership tracking systems require dedicated legal compliance functions.
- High-end:Ultra-premium developments in diplomatic corridors face demand ceilings where supply exceeds eligible foreign purchaser pools under the 40 percent ownership ceiling.
Mid-range properties capture the steepest demand expansion while affordable supply confronts input cost volatility constraints.
Investment Purpose:
Application-based segmentation tracks the behavioral pivot from speculative capital rotation toward owner-occupied functional configurations.
- Personal Use:Owner-occupier demand is collapsing historical speculative investor dominance as first-time buyers prioritize garden-style compounds and school cluster proximity over central Yangon appreciation potential.
- Rental Income:Yield-focused acquisitions concentrate in Thanlyin where infrastructure corridor announcements are preceding capital flows that previously led physical development.
- Resale:Speculative appreciation plays retreat to luxury and high-end segments where foreign buyer quotas create artificial scarcity premiums.
- Commercial Use:Mixed-use residential configurations with ground-floor retail face permitting complexity from municipal development affairs committees' land use protocols.
Personal use anchors transaction volume while rental income strategies expand most quickly in satellite corridor markets.
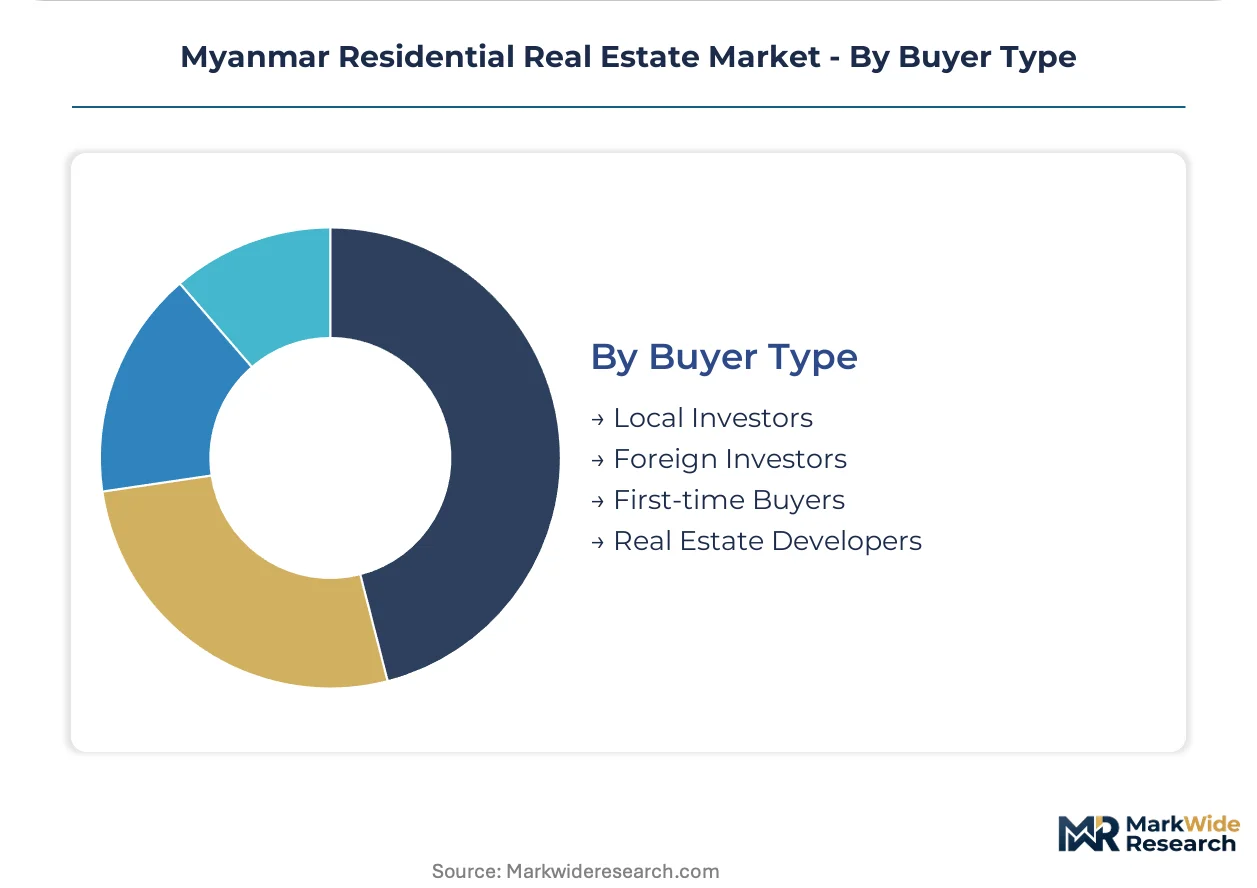
Buyer Type:
Customer-type segmentation exposes how the Myanmar Investment Commission's condominium revisions are compressing developer product strategies toward domestically absorbable configurations.
- First-time Buyers:Yangon's emerging middle class is displacing speculative investors as the dominant market force. This segment drives demand for mid-range condominiums and townhouses in Thanlyin and Dagon Seikkan where mortgage accessibility is expanding.
- Local Investors:Domestic capital rotation shifts from speculative resale plays toward rental income generation in infrastructure-adjacent satellite townships.
- Foreign Investors:Eligible purchasers under the 40 percent ownership ceiling concentrate in diplomatic zones and golf course peripheries where luxury unit supply faces quota saturation.
- Real Estate Developers:Integrated construction-to-sales pipeline operators navigate condominium law compliance complexity and foreign ownership tracking system investments that smaller competitors cannot staff.
First-time buyers anchor the volume base while local investors rotate strategies at the fastest rate toward rental yield models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyers from Yangon's emerging middle class are concentrating transaction volume in satellite corridors where infrastructure expansion precedes speculative capital flows. Domestic mortgage accessibility is displacing cash-only dominance across Myanmar's primary residential absorption zones.
Yangon Metropolitan Core
Thanlyin and Dagon Seikkan corridors are capturing the steepest demand growth as bridge and road connectivity unlock workforce housing absorption. The Myanmar Investment Commission's 40 percent foreign ownership ceiling channels developer supply toward domestically absorbable unit configurations. Central Yangon townships see speculative investor retreat as first-time buyer preferences rotate toward functional owner-occupied specifications.
Mandalay Urban Zone
Secondary city expansion confronts skilled labor scarcity for reinforced concrete frame and aluminum glazing system execution. Municipal development affairs committees impose extended permitting timelines for agricultural-to-residential land use conversions. Industrial zone adjacency in peripheral townships creates unmet workforce housing demand that current supply has not captured.
Naypyitaw Administrative Capital
Civil servant housing clusters and diplomatic zone adjacency sustain localized luxury segment absorption. The condominium law framework restricts foreign freehold eligibility verification to designated building quotas. Golf course periphery developments face demand saturation where eligible foreign purchaser pools fall below luxury unit supply.
Bago Satellite Corridor
Highway connectivity improvements are compressing commute timelines to Yangon employment centers for cost-sensitive household segments. Banking sector mortgage reforms extend longer-tenor home loan access to formal-sector employees in this corridor. Land cost differentials versus central Yangon are attracting developer capital toward mid-range horizontal development configurations.
Pathein Delta Region
Port connectivity and agricultural processing zone expansion are creating nascent rental income demand from transient professional households. Import dependency for cement and steel reinforcement generates construction cost volatility that developers cannot fully pass through to price-constrained buyers. Localized supply remains underdeveloped relative to infrastructure corridor announcements.
Myanmar Residential Real Estate Market Competitive Landscape
Player mix skews toward integrated construction-to-sales pipeline operators with municipal land bank relationships. Market structure concentrates around developers with dedicated legal compliance functions for condominium law foreign ownership tracking. Three archetypes dominate: integrated township developers with infrastructure adjacency exposure, garden-style compound specialists targeting family segments, and diversified conglomerates with construction material captive supply. Competitive moves center on satellite corridor land banking ahead of infrastructure announcements and compliance function investments that smaller competitors cannot staff.
Within the integrated pipeline tier, Dagon Group exemplifies multi-township construction-to-sales operations across Yangon. FMI Garden Development occupies a position among garden-style compound specialists targeting family buyer preferences. Shwe Taung Group anchors the diversified infrastructure-adjacent exposure archetype with port and industrial zone proximity strategies.
| Leading Market Players |
|---|
| Dagon Group |
| FMI Garden Development |
| Shwe Taung Group |
| Shwe Than Lwin Co. |
| Capital Development Ltd. |
| Yoma Strategic Holdings |
| Eden Group |
| Myanmar Seilone |
| Marga Group |
| Others |
Supply & Pricing Matrix
Cross-laminated timber substitution for reinforced concrete frames is simultaneously redrawing procurement geography toward Southeast Asian engineered-wood suppliers and compressing per-square-meter construction economics for Yangon developers targeting environmentally conscious households. This materials pivot interacts with import-dependent cement and steel reinforcement volatility to fragment pricing power across vertical development tiers.
Pricing Analysis
Technology-generation pricing gaps separate smart-home-enabled condominiums from basic-specification units from legacy cash-transaction stock. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade for foreign ownership eligibility and proximity to infrastructure corridor announcements. Cost compression in the affordable tier is intensifying because cement and steel reinforcement import dependency prevents full cost pass-through to price-constrained buyers. First-time buyers from Yangon's emerging middle class exhibit highest price sensitivity, while foreign purchasers in diplomatic zones show lowest elasticity due to quota-scarcity positioning.
Supply Chain Analysis
Port congestion at Thilawa and container availability constraints on the Singapore-Yangon trade lane are elevating inbound logistics costs for aluminum glazing systems and elevator components. Manufacturing concentration rests on China for construction equipment, Thailand for ceramic tiles and sanitary ware, and Singapore for building automation systems. Reinforced concrete frames draw from Myanmar's domestic cement plants supplemented by Thai and Vietnamese clinker imports. Single-source vulnerability concentrates in high-rise elevator and fire-safety system suppliers. Distribution runs through developer-integrated construction-to-sales pipelines with direct municipal land bank relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar's residential real estate market sits at a platform-economics inflection where digital transaction platforms and mortgage accessibility expansion are collapsing traditional broker-dependent search-to-close timelines, creating interoperability between banking sector reform and property technology channel convergence.
For Market Incumbents: Compound defensive positioning through backward integration into captive cement supply and dedicated legal compliance functions for condominium law foreign ownership tracking. Threat substitution from cross-laminated timber specialists and property technology platforms demands certification investment in green building materials and smart home automation integration.
For New Entrants and Emerging Players: Myanmar Investment Commission compliance certification fast-track enables penetration of the mid-range condominium segment where first-time buyer mortgage accessibility is collapsing cash-only dominance. White-space targets include Dagon Seikkan workforce housing and Thanlyin rental income generation. Go-to-market angle centers on digital-native transaction platforms compressing search-to-close timelines for domestic buyers unfamiliar with traditional broker processes.
For Investors and Strategic Acquirers: The market sits at a banking-sector-reform acceleration phase that favors integrated construction-to-sales pipeline operators with municipal land bank relationships. Long-term viability hinges on infrastructure corridor announcement timing and foreign ownership ceiling enforcement consistency. Acquisition target archetype: developers with established compliance functions and satellite corridor land positions. Signal to watch: Myanmar Investment Commission urban planning code revisions indicating demand migration patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Material Certification | Cross-laminated timber and low-carbon concrete differentiation opens premium positioning for Yangon environmentally conscious households. |
| Digital Transaction Platform Integration | Property technology channels compress search-to-close timelines for domestic first-time buyers unfamiliar with broker-dependent processes. |
| Condominium Compliance Function Investment | Dedicated legal staffing for foreign ownership tracking reduces regulatory rejection risk under Myanmar Investment Commission enforcement tightening. |
| Satellite Corridor Land Banking | Thanlyin and Dagon Seikkan positions ahead of infrastructure announcements capture workforce housing absorption before speculative capital flows. |
| Banking Sector Mortgage Partnership | Longer-tenor home loan channel partnerships with domestic financial institutions collapse cash-only transaction dominance in mid-market segment. |
Research Methodology
A standing panel of condominium development executives, municipal planning officers, mortgage product managers at domestic banks, and property technology platform operators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from Myanmar Investment Commission regulatory filings, Directorate of Investment and Company Administration construction permitting databases, and municipal development affairs committee land use conversion records. Bottom-up unit absorption estimates triangulated against top-down construction pipeline assessments.
Consistency checks validated volume and value outputs against infrastructure corridor announcement timelines and foreign ownership transaction tracking systems. The analytical framework modeled segmentation across property type, price range, investment purpose, and buyer type throughout the forecast period. CAGRs derived from trend extrapolation of mortgage accessibility expansion rates and construction cost input indices. Industry-specific forecast inputs included cement and steel reinforcement import dependency ratios and satellite township connectivity improvement schedules.
Underlying assumptions cover banking sector reform continuation, foreign ownership ceiling enforcement stability, and infrastructure corridor completion timelines, with deviation risk concentrated in construction input cost volatility and regulatory permitting delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market