
 India Manufactured Homes Market | 2026-2036
India Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
India Manufactured Homes Market Foresight
PLI scheme extensions for construction material manufacturing is repositioning the cost-of-entry calculus for prefabricated housing entrants. Epack Prefab leverages backward integration into steel framing to sustain margin control across western India. Loom Crafts anchors its competitive stance through artisanal wood-composite specialization that differentiates it from commodity panel producers. Karmod Prefabricated Technologies dominates institutional procurement channels for emergency housing deployments.
Manufactured homes are factory-built residential structures assembled from prefabricated modules or panels, typically constructed to BIS SP 7 or equivalent structural codes with specified wind-load and seismic resistance ratings, then transported to sites for installation. Their primary purpose is to deliver cost-efficient, scalable housing solutions faster than conventional brick-and-mortar construction. Modular homes occupy the largest volume share given their suitability for multi-story urban infill projects, while tiny homes represent the fastest-expanding niche among millennial first-time buyers seeking compact ownership models. Steel-based building materials command preference in industrial zone applications due to fire-safety compliance advantages over timber alternatives.
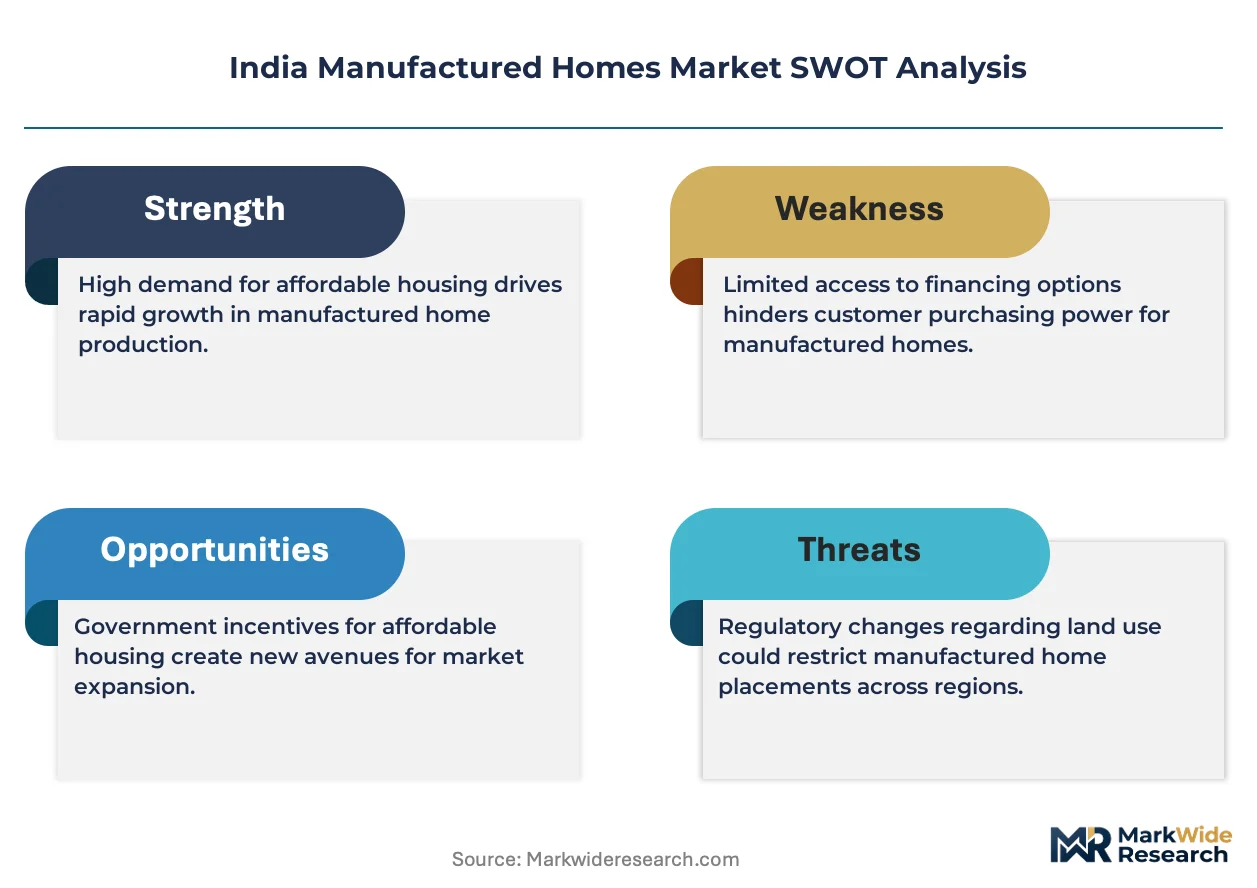
BIS mandates on structural integrity testing, combined with CEA electrical safety standards and state-level RERA registration requirements, collectively elevate compliance costs but simultaneously filter out informal assemblers. RBI housing finance guidelines extending priority-sector lending to prefabricated units are unlocking mortgage access previously restricted to conventional construction. Stakeholders must monitor how state urban development authorities reconcile building bye-laws with factory-built certification pathways.
Market Dynamics
PLI scheme extensions for construction material manufacturing are compressing cost structures for prefabricated housing entrants while BIS certification mandates filter informal assemblers from Maharashtra's industrial corridors and Gujarat's special economic zones.
Growth Catalysts
- PLI scheme for construction materials:Central government production-linked incentives reduce input costs for steel framing and panel manufacturing, enabling price competitiveness against conventional brick-and-mortar construction in urban corridors.
- RBI priority-sector lending extension:Housing finance guidelines now classify prefabricated units as eligible for mortgage access, unlocking institutional capital flows previously restricted to traditional construction formats.
- Maharashtra-Gujarat industrial clustering:Demand concentrates in these states due to special economic zone expansions and port-proximate logistics infrastructure that reduces module transport costs.
Market Restraints
- BIS SP 7 compliance costs:Mandatory structural integrity testing and wind-load certification elevate fixed costs for smaller fabricators, consolidating market share toward scaled producers.
- Steel price volatility:Input cost fluctuations for cold-rolled steel framing compress margins for producers lacking backward integration into metal forming operations.
- Timber fire-safety substitution ceiling:Industrial zone applications face regulatory barriers to wood-composite adoption, limiting material diversification in high-volume segments.
Strategic Opportunities
- Kerala-Tamil Nadu coastal belt penetration:Underdeveloped manufactured housing adoption in southern states offers first-mover positioning for cyclone-resistant modular formats.
- CEA electrical safety convergence:Pre-certified electrical systems integration creates turnkey value propositions for institutional buyers seeking rapid deployment timelines.
- Millennial tiny home ownership models:Compact single-module formats targeting first-time buyers in Bengaluru and Hyderabad tech corridors represent unaddressed demographic demand.
Industry Challenges
- RERA state-level registration fragmentation:Factory-built certification pathways remain inconsistently reconciled with state urban development authority building bye-laws, creating approval timeline uncertainty.
- Seismic engineering talent scarcity:Specialized structural design capabilities for multi-story modular construction outpace current vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Manufactured Homes Market |
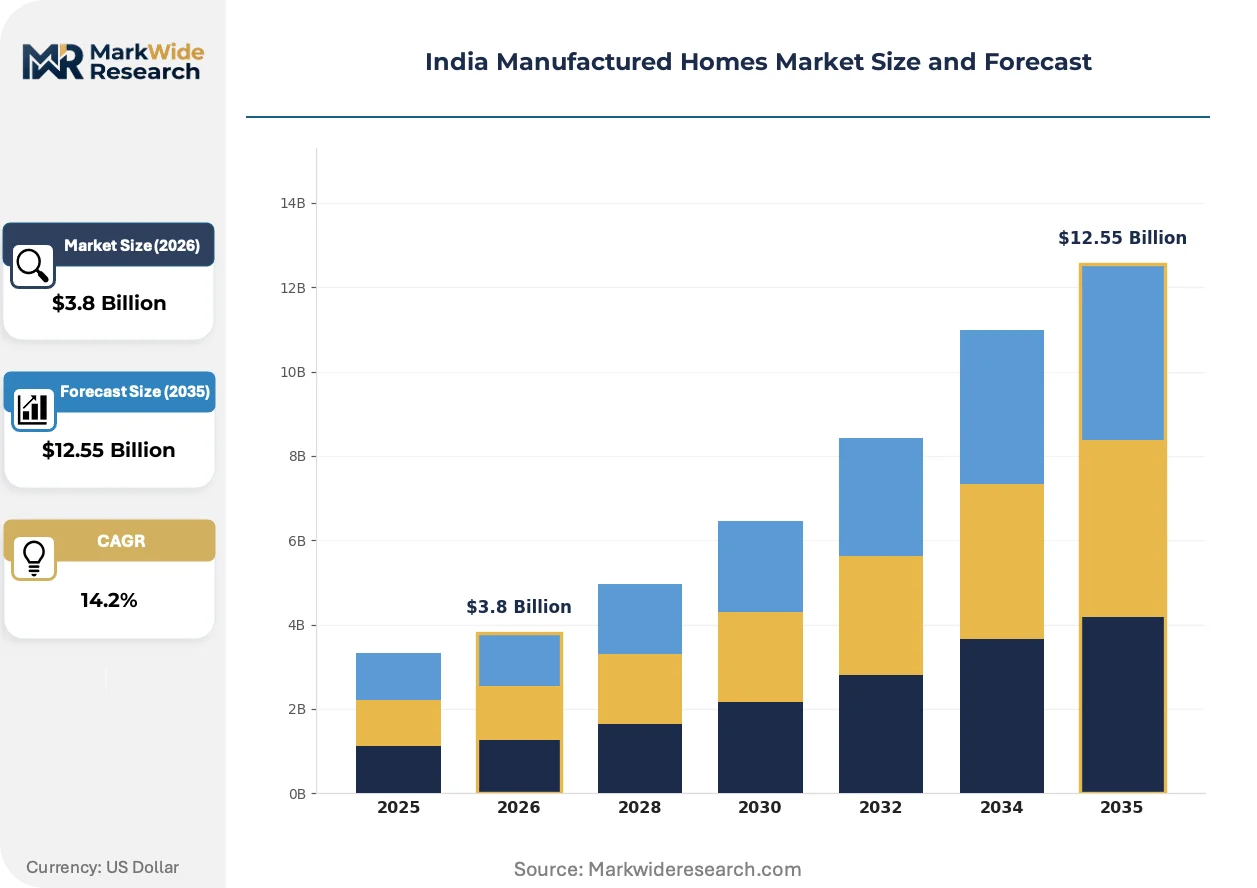
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Prefabricated Homes, Tiny Homes, Panelized Homes Building Material: Wood, Steel, Concrete, Composite Application: Residential, Commercial, Recreational, Emergency Housing Distribution Channel: Direct Sales, Online, Retail, Dealers |
| Companies Covered | Windoors International Ltd., Loom Crafts, Epack Prefab, Multi Decor India Pvt. Ltd, Pressmach Infrastructure Private Limited, Shadecrafts India, Karmod Prefabricated Technologies, Satec Envir Engineering, Magic Structures, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Manufactured Homes Market Shifts & Advancements
Factory-level digitalization is compressing design-to-delivery timelines while regulatory convergence between BIS standards and state RERA frameworks redefines compliance architecture for prefabricated housing.
Robotic welding systems for steel frame assembly are automating joint fabrication precision that previously required manual fitter labor. Tier-one producers in Gujarat's industrial zones deploy these systems for multi-story module production. This automation is compressing defect rates and enabling overnight shift operations that double effective factory throughput.
BIS mandates on structural integrity testing are tightening quality benchmarks for wind-load and seismic resistance ratings across all prefabricated formats. State urban development authorities must now reconcile these national standards with localized building bye-laws. Maharashtra's municipal corporations are responding with expedited approval tracks for pre-certified modular designs.
Institutional procurement is consolidating toward turnkey contractors capable of delivering design-permit-construction packages under single-contract accountability. Real estate developers in Pune and Ahmedabad industrial suburbs are displacing fragmented subcontractor models with integrated module suppliers. This concentration is most visible in affordable housing projects where timeline certainty outweighs unit cost minimization.
India Manufactured Homes Market Segmentation
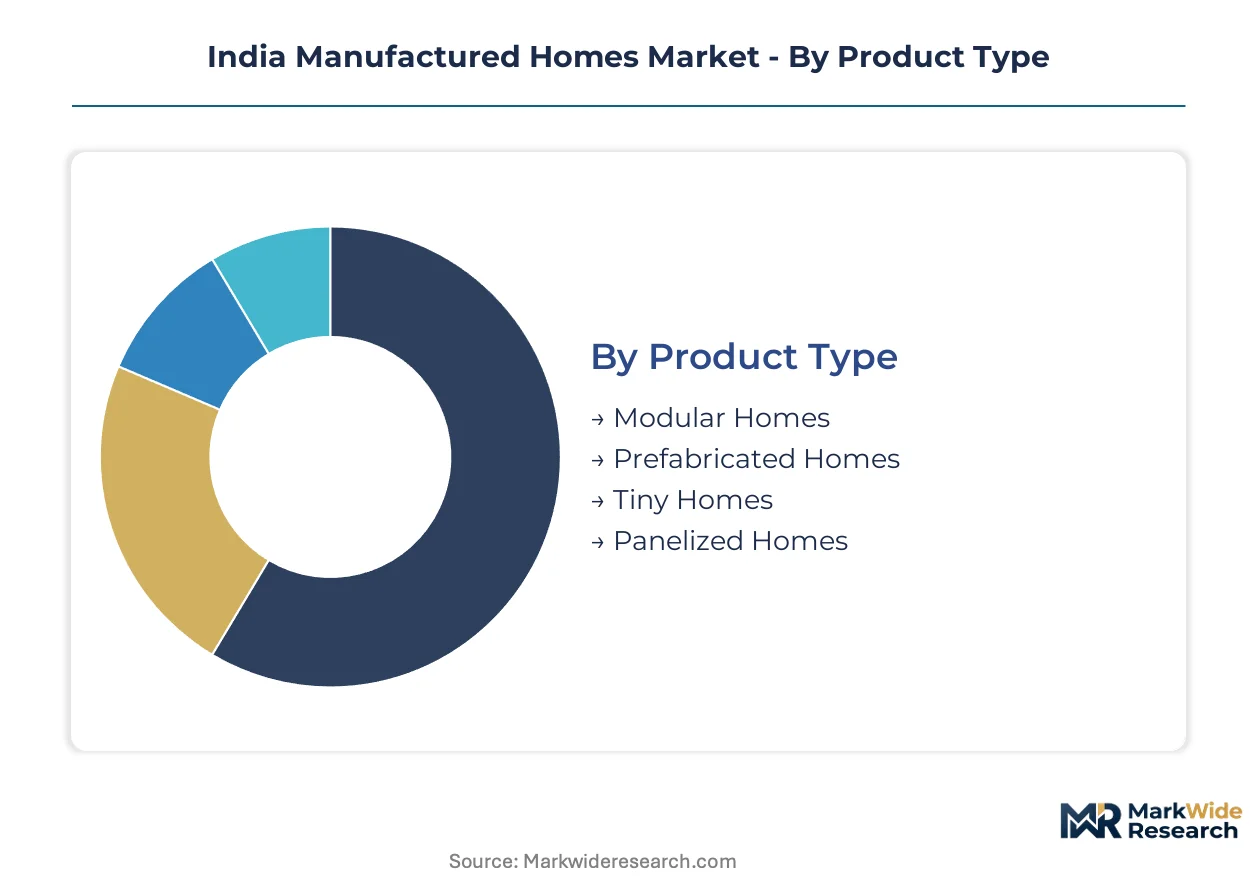
Segmentation reveals how supply-side capabilities align with distinct buyer requirements across India's manufactured housing landscape. Material choices and distribution pathways determine which fabricators capture volume in Maharashtra's industrial corridors versus Gujarat's special economic zones.
Product Type:
Supply concentration in western India favors formats that maximize factory throughput and minimize site assembly complexity.
- Modular Homes:Factory-built volumetric units constructed to BIS SP 7 structural codes with integrated MEP systems, transported as complete modules. Demand concentrates in Pune and Ahmedabad industrial suburbs where multi-story urban infill projects require rapid deployment timelines and single-contract accountability.
- Prefabricated Homes:Panel-based systems assembled from wall, floor, and roof components manufactured off-site. Maharashtra's municipal corporations are driving adoption through expedited approval tracks for pre-certified designs in affordable housing initiatives.
- Tiny Homes:Compact single-module formats targeting millennial first-time buyers in Bengaluru and Hyderabad tech corridors.
- Panelized Homes:Flat-packed wall and roof panels requiring on-site assembly, suited to remote locations with limited crane access.
Today's leader: Modular Homes. Tomorrow's challenger: Tiny Homes.
Building Material:
Cost tier differentiation separates premium structural performance from economy-grade alternatives.
- Steel:Cold-rolled framing systems dominate industrial zone applications due to fire-safety compliance advantages and seismic resistance ratings specified under BIS standards. Gujarat's producers leverage backward integration into metal forming to control margin compression from input price volatility.
- Wood:Timber-composite panels serve recreational and residential segments where aesthetic differentiation commands premium positioning. Kerala's artisanal fabricators specialize in cyclone-resistant engineered wood formats for coastal belt penetration.
- Concrete:Precast concrete systems deliver thermal mass and acoustic insulation for multi-story residential projects.
- Composite:Hybrid material formulations combining fiber reinforcement with polymer matrices for lightweight structural applications.
Steel commands institutional procurement. Composite materials are climbing the fastest as weight-reduction priorities reshape transport economics.
Application:
Volume concentration tracks government procurement cycles and private development pipelines.
- Residential:Affordable housing projects constitute the core demand base, with RBI priority-sector lending extension unlocking mortgage access for prefabricated units previously restricted to conventional construction.
- Emergency Housing:Disaster relief and temporary shelter deployments dominate institutional procurement channels, requiring rapid manufacturing turnaround and turnkey logistics.
- Commercial:Site offices, retail kiosks, and hospitality pods in special economic zones.
- Recreational:Resort cabins and vacation homes targeting secondary ownership markets.
Residential absorbs the greatest unit volume. Emergency Housing offers the steepest expansion trajectory as climate resilience budgets expand.
Distribution Channel:
Customer type determines whether transactions flow through project-specific contracting or standardized retail pathways.
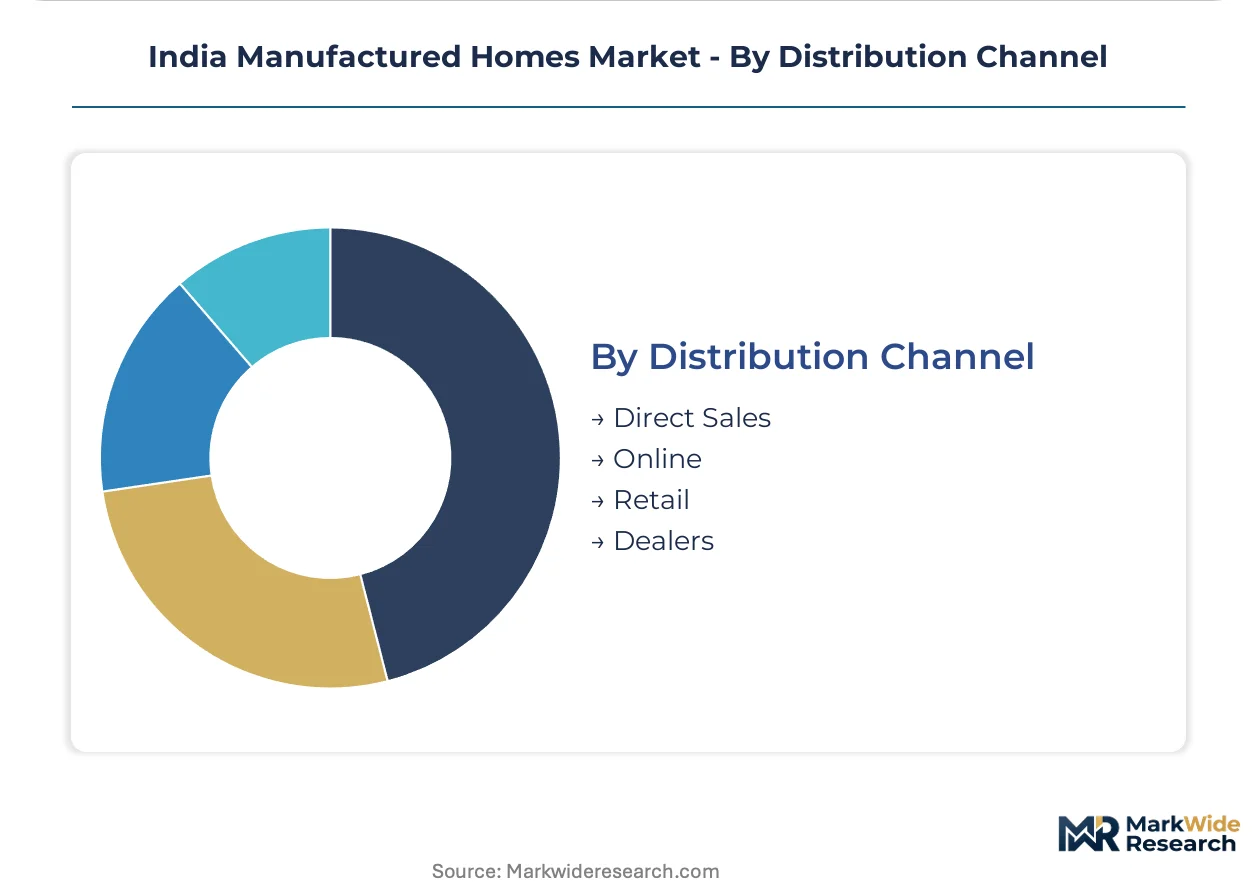
- Direct Sales:Large-volume contracts with real estate developers and government agencies, delivering design-permit-construction packages under single-point accountability. This channel captures the majority of affordable housing and institutional procurement volume.
- Dealers:Regional distributor networks providing local site coordination and after-sales service for individual buyers and small developers.
- Online:Digital configurators and quotation platforms targeting tech-savvy millennial buyers in metropolitan markets.
- Retail:Physical showrooms displaying model units for consumer inspection, concentrated in urban centers with established housing finance ecosystems.
Direct Sales anchors current revenue. Online channels are gaining share fastest as digital-native buyers enter first-time ownership markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory-built housing first scaled in western India during the 1990s SEZ construction wave, establishing Maharashtra and Gujarat as the industry's historical anchor points before southern states emerged as expansion frontiers.
Maharashtra
Pune's industrial suburbs and Mumbai's peripheral corridors drive modular demand through affordable housing mandates and IT park expansions. The state's urban development authorities operate expedited approval tracks for BIS SP 7 pre-certified designs. MMRDA's transit-oriented development zones concentrate multi-story module deployment along metro extensions.
Gujarat
Port-proximate logistics infrastructure at Mundra and Hazira reduces module transport costs for export-oriented fabricators. The state's special economic zone expansions trigger institutional procurement for site offices and worker housing. GIDC industrial estates cluster steel-framing producers with captive metal forming operations.
Karnataka
Bengaluru's tech corridor generates millennial demand for compact ownership formats and rapid-deployment rental units. The state's housing department integrates manufactured units into urban mission targets. Electronic City and Whitefield sub-markets attract panelized home distributors targeting IT workforce mobility.
Tamil Nadu
Chennai's automotive belt and Sriperumbudur industrial zone sustain commercial prefabricated demand for plant ancillary structures. Coastal cyclone exposure positions the state for cyclone-resistant modular penetration. State disaster management authorities stockpile emergency housing modules at Nagapattinam and Cuddalore depots.
Telangana
Hyderabad's pharmaceutical and IT corridor expansion creates hybrid demand for workforce housing and cleanroom-adjacent modular facilities. The state's building permission automation reduces factory-built certification friction. Genome Valley and Fab City sub-regions concentrate turnkey contractor activity for rapid facility deployment.
India Manufactured Homes Market Competitive Landscape
The competitive structure tilts toward integrated fabricators with captive steel supply and institutional procurement relationships. Market concentration remains moderate, with tier-one producers commanding affordable housing and emergency deployment channels while regional specialists occupy aesthetic-differentiated residential niches. Two archetypes dominate: backward-integrated metal formers controlling input cost volatility, and artisanal wood-composite specialists serving premium coastal markets. Capacity expansion and BIS certification acquisition constitute the primary competitive moves, filtering informal assemblers from formal procurement channels.
Among western India-based integrated producers, Epack Prefab and Karmod Prefabricated Technologies exemplify the scale-driven archetype through metal-forming integration and institutional channel dominance. Loom Crafts occupies a differentiated position within the artisanal tier, representing wood-composite specialization that commands premium positioning outside commodity panel markets. These three anchors illustrate how material focus and distribution channel selection partition competitive terrain across India's manufactured housing landscape.
| Leading Market Players |
|---|
| Windoors International Ltd. |
| Loom Crafts |
| Epack Prefab |
| Multi Decor India Pvt. Ltd |
| Pressmach Infrastructure Private Limited |
| Shadecrafts India |
| Karmod Prefabricated Technologies |
| Satec Envir Engineering |
| Magic Structures |
| Others |
Supply & Pricing Matrix
BIS SP 7 structural certification gates qualified supply and premium-tier pricing access, filtering informal assemblers from Maharashtra's industrial corridors while elevating compliance costs that stratify fabricators across economy and certified-grade tiers. This regulatory architecture concentrates margin capture among scaled producers with captive testing infrastructure and backward-integrated steel supply.
Pricing Analysis
Project-based contract pricing dominates institutional procurement, with BIS certification grade and volume scale as the primary differentiation drivers. Cost compression in economy-tier panel systems is intensifying because cold-rolled steel input volatility squeezes fabricators lacking metal-forming integration. Government agency buyers exhibit the highest price sensitivity due to tender-based procurement, while premium residential buyers prioritize timeline certainty over unit cost minimization.
Supply Chain Analysis
BIS SP 7 qualification requirements concentrate qualified supply in India, with secondary component sourcing from China and South Korea for specialized MEP systems. The supply chain draws from cold-rolled steel framing, cement-bonded particleboard, and pre-certified electrical assemblies as core inputs. Single-source vulnerability runs through specialized seismic engineering talent for multi-story modular design. Distribution runs through direct sales contracts with real estate developers and government agencies, supplemented by regional dealer networks for individual buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's manufactured homes market offers margin expansion through PLI scheme-enabled cost compression in steel framing inputs and premium-tier shift toward turnkey design-permit-construction packages. Fabricators capturing backward integration benefits and BIS certification early will consolidate pricing power as compliance filters intensify.
For Market Incumbents: Lock in institutional procurement relationships through expedited RERA registration assistance and pre-certified modular design libraries. Threat from artisanal wood-composite specialists in Kerala-Tamil Nadu coastal markets demands counter-positioning via fire-safety certified steel formats. Priority lever rests on captive metal-forming capacity expansion in Gujarat's GIDC industrial estates to neutralize input price volatility.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium turnkey contractors and economy panel assemblers creates white-space for standardized small-developer packages. Bengaluru and Hyderabad tech corridors offer the most penetrable geography for millennial tiny home formats targeting first-time ownership. Go-to-market angle should emphasize online configurators with integrated housing finance pre-qualification.
For Investors and Strategic Acquirers: Roll-up economics work for regional steel-framing fabricators because BIS certification acquisition costs and RERA registration complexity create barriers that favor scaled platforms over fragmented local operators. Long-term viability hinges on positioning for institutional affordable housing procurement cycles and climate resilience budget expansion. Signal to watch is state urban development authority adoption of factory-built certification pathways that accelerate approval timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Framing | Captive cold-rolled steel production insulates margins from commodity volatility in Gujarat's industrial zones. |
| BIS SP 7 Certification Acquisition | Pre-certified structural designs unlock expedited RERA registration tracks in Maharashtra's municipal corporations. |
| Turnkey Design-Permit-Construction Packaging | Single-contract accountability displaces fragmented subcontractor models in Pune and Ahmedabad affordable housing. |
| Kerala-Tamil Nadu Coastal Belt Expansion | Cyclone-resistant modular formats address underpenetrated southern markets with state disaster management procurement. |
| Digital Configurator Platform Launch | Online quotation systems with RBI priority-sector lending integration target millennial first-time buyers in tech corridors. |
Research Methodology
Multiple input streams — primary interviews with prefabricated housing fabricators, real estate developers, and state urban development authority officials; secondary validation through BIS certification registries, RBI housing finance circulars, and state RERA filings; and customs data on steel framing imports — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included factory operations directors, institutional procurement managers at affordable housing developers, municipal corporation building permission officers, and steel input procurement leads.
Historical volume trajectories were cross-referenced against panel-based demand projections across product type, building material, application, and distribution channel dimensions over the analysis window. CAGRs were derived from segmented growth rate modeling incorporating PLI scheme uptake curves, state-level affordable housing mission targets, and industrial zone expansion pipelines as industry-specific forecast inputs.
Caveats apply where BIS standard revisions, state RERA framework divergence, or steel price volatility spikes could materially shift the outlook. A model refresh is warranted upon material change in central government PLI scheme extension decisions or Maharashtra-Gujarat industrial corridor policy priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
United Arab Emirates Residential Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
Spain Residential Real Estate Market