
 Latin America Residential Real Estate Market | 2026-2036
Latin America Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Residential Real Estate Market Insights
Multi-source contractor engagement is realigning how developers manage land assembly and vertical construction across Latin America. MRV Engenharia leverages prefabricated component sourcing to compress delivery schedules in Brazilian affordable housing. Cyrela Brazil Realty anchors premium positioning through direct architectural control in São Paulo and Rio de Janeiro. QuintoAndar competes by digitizing rental transaction flows, reducing broker dependency in fragmented secondary markets.
Latin America residential real estate encompasses permanent dwelling structures designed for individual or family occupancy, typically constructed with reinforced concrete frames, ceramic block infill, and regionally adapted thermal insulation meeting local seismic codes. The primary commercial purpose centers on shelter provision as a consumable service and wealth-storage asset within inflation-prone economies. Condominiums command dominant share in dense Brazilian and Mexican urban cores where land scarcity elevates per-unit values. First-time buyers represent the fastest-expanding customer type as mortgage securitization deepens and government guarantee programs broaden credit access. Sales transactions still occupy the largest value pool, though rental platforms are capturing recurring-revenue margin pools previously fragmented among informal landlords.
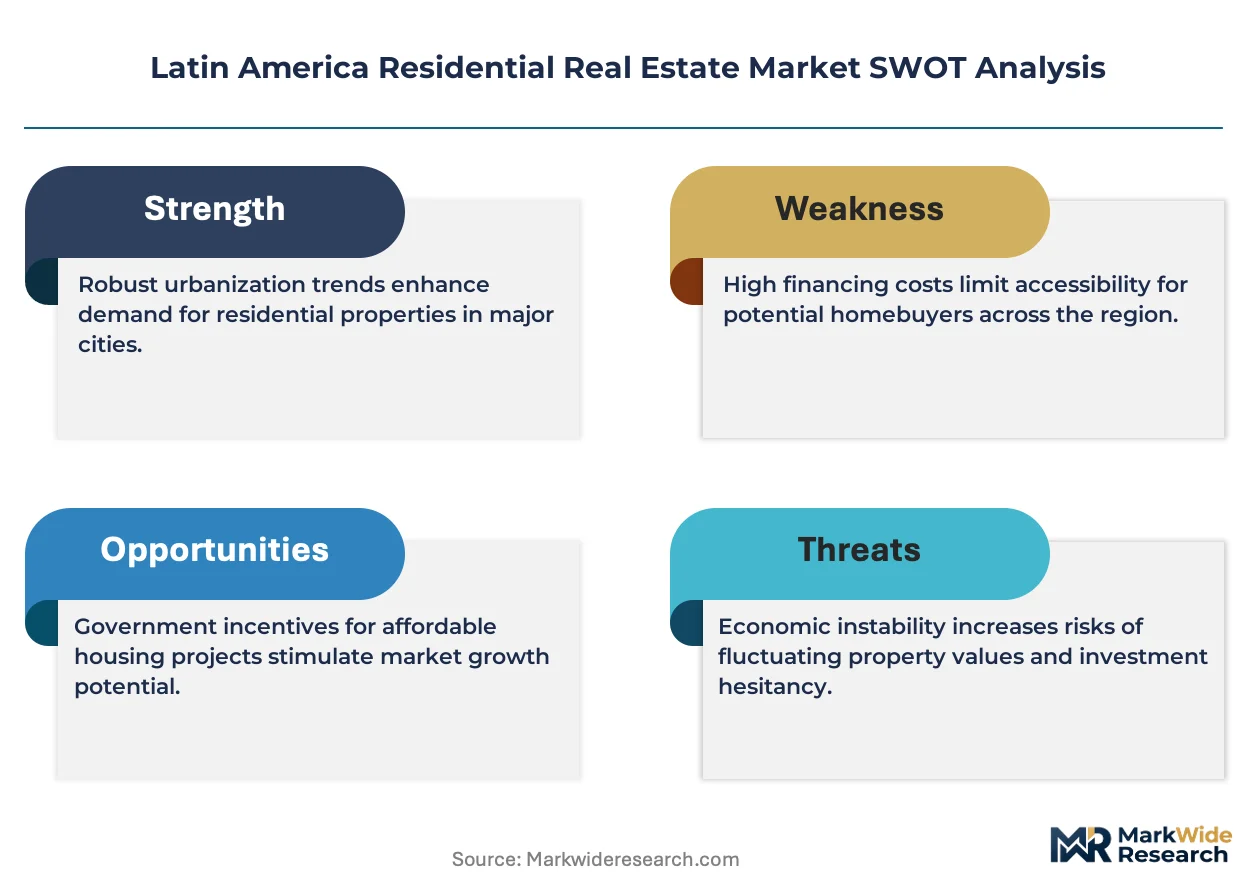
Brazil's Casa Verde e Amarela program, Mexico's INFONAVIT worker housing fund, and Colombia's VIS affordable housing certification each shape product specifications, subsidy eligibility, and developer pricing power. These frameworks mandate minimum unit sizes, construction timelines, and buyer income ceilings that directly filter project feasibility and location choice. Stakeholders must monitor how digital title registries and distributed ledger pilots in Chile and Mexico reshape transaction transparency and collateral valuation standards.
Market Dynamics
Mortgage securitization and fintech-enabled credit scoring are restructuring how working-class households in São Paulo and Mexico City access formal financing for first-time purchases.
Growth Catalysts
- Brazil's Casa Verde e Amarela program:Federal subsidy thresholds and income-linked financing terms are pulling lower-middle-income households into formal homeownership in southeastern metropolitan corridors.
- Digital title registries:Blockchain pilots in Chile and Mexico are compressing collateral verification timelines and expanding mortgage lender confidence in informal settlements.
- Prefabricated construction systems:Component standardization is reducing vertical delivery schedules for affordable housing developments across Brazil's urban peripheries.
Market Restraints
- Cement price volatility:Input cost swings in Brazilian and Mexican construction materials squeeze developer margins on fixed-price affordable housing contracts.
- Land titling fragmentation:Informal ownership records in peri-urban Colombia and Peru block institutional financing for self-built housing upgrades.
- Substitution to rental platforms:QuintoAndar-style digital intermediation is capturing households who would otherwise pursue purchase, particularly mobile professionals in São Paulo.
Strategic Opportunities
- Colombia's VIS certification pipeline:Subsidized interest-rate eligibility for value-based housing creates developer pricing power in Bogotá and Medellín peripheral zones.
- Mortgage securitization depth:Fiduciary certificate markets in Mexico are enabling longer-duration lending to informal-sector workers previously excluded from INFONAVIT.
- Convergence of IoT sensors and property management:Smart condominium systems are opening recurring-revenue streams for developers retaining operational stakes in Brazilian luxury towers.
Industry Challenges
- Construction labor scarcity:Skilled ceramic block masons and reinforced concrete specialists command wage premiums that distort project cost models in Mexican central plateau clusters.
- Seismic code compliance timelines:Updated structural engineering certifications in Chilean and Colombian high-risk zones extend pre-construction permitting by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Residential Real Estate Market |
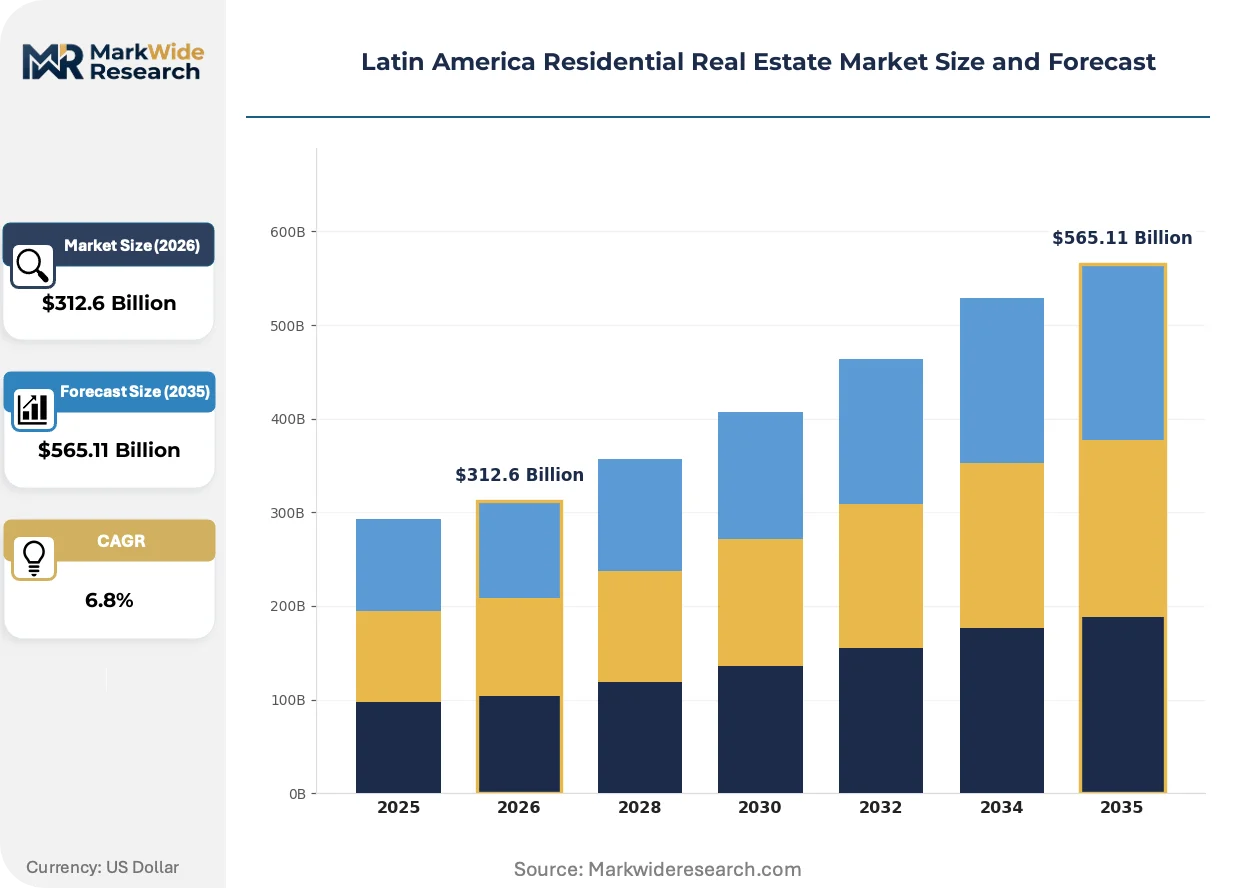
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Multi-Family Residences Customer Type: First-Time Buyers, Investors, Retirees, Expats Transaction Type: Sales, Rentals, Lease Options, Foreclosures Financing Options: Conventional Loans, Government Programs, Private Financing, Cash Transactions |
| Companies Covered | MRV Engenharia e Participações S.A., Cyrela Brazil Realty S.A., Gafisa S.A., Tenda S.A., Direcional Engenharia S.A., Even Construtora e Incorporadora S.A., QuintoAndar, La Haus, Habi, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Residential Real Estate Market Trends and Innovations
Digital transaction infrastructure and modular construction methods are compressing delivery timelines while reshaping how developers capture value across the ownership lifecycle.
Cross-laminated timber and light-gauge steel framing systems are overtaking traditional reinforced concrete in mid-rise residential towers targeting sustainability-certified buyers in São Paulo and Santiago. Green building rating adopters in premium segments specify these materials to meet carbon disclosure requirements. Developer procurement teams are consolidating supplier relationships to secure volume pricing on imported engineered wood products.
Mexico's INFONAVIT worker housing fund has tightened energy efficiency mandates for subsidized unit eligibility, forcing developers to incorporate solar water heating and LED infrastructure as baseline specifications. Projects failing thermal envelope standards lose access to below-market financing pools. Builders in Querétaro and Guadalajara are responding by partnering with equipment lessors to spread capital costs across construction phases.
First-time buyer segments are bypassing traditional broker networks in favor of algorithmic property-matching platforms that compress search-to-offer cycles from weeks to days. These channels aggregate fragmented secondary inventory previously invisible to mortgage-qualified households. Adoption concentrates among university-educated professionals in Mexico City and Buenos Aires who prioritize transaction transparency over negotiated discounts.
Latin America Residential Real Estate Market Segmentation
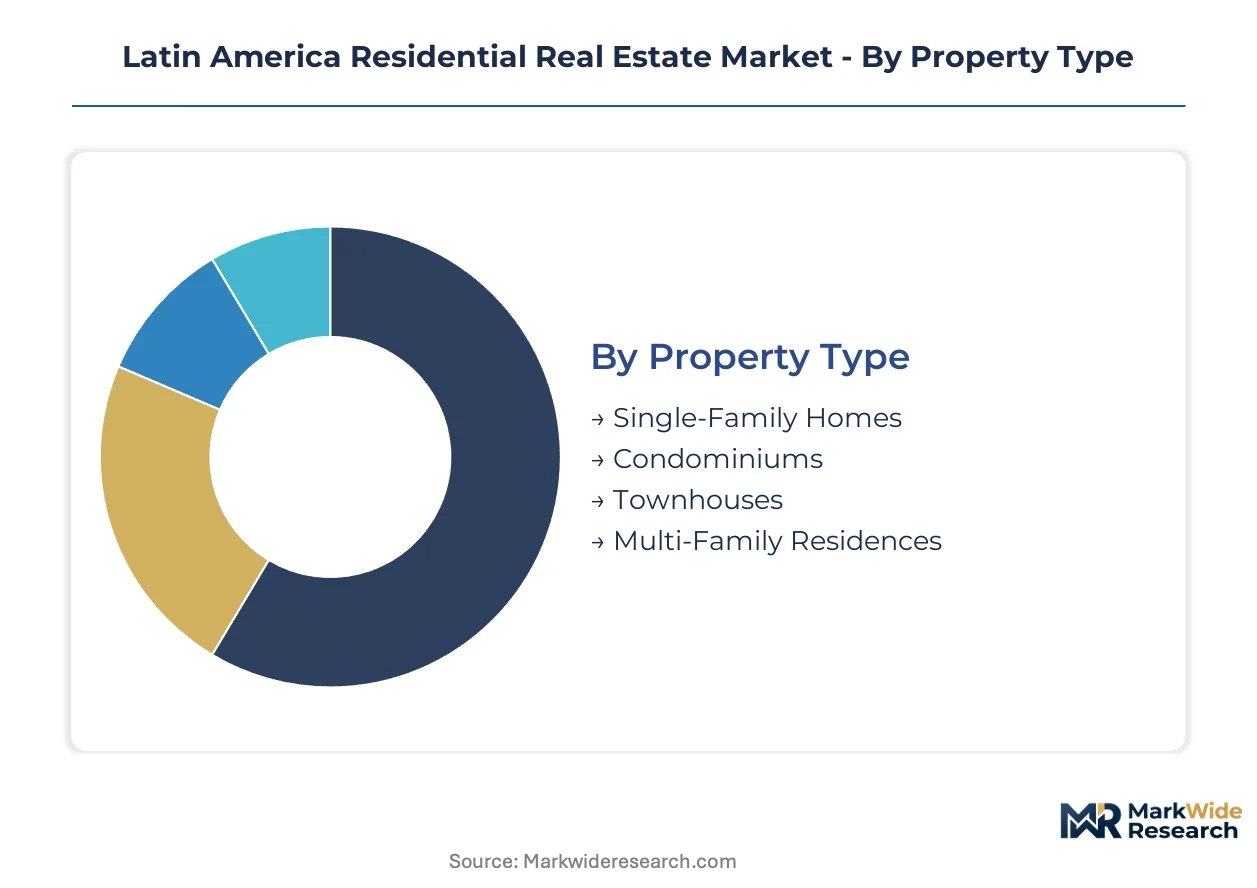
Segmentation reveals how housing demand fragments across property configurations, buyer profiles, and capital sources in Latin America's inflation-prone economies. Each dimension carries distinct regulatory exposure and margin structures that reshape developer positioning.
Property Type:
Upgrade cycles differ sharply across structural forms, with density constraints and land scarcity driving replacement demand in core metropolitan corridors.
- Single-Family Homes:Detached structures on individual land parcels dominate peripheral zones of São Paulo and Mexico City where horizontal expansion remains feasible. INFONAVIT and Casa Verde e Amarela subsidies concentrate here for first-time buyers seeking space.
- Condominiums:Vertical multi-unit buildings with shared common areas command premium pricing in land-scarce Brazilian and Mexican urban cores. Seismic codes in Santiago and Bogotá elevate structural engineering costs for mid-rise and high-rise formats.
- Townhouses:Attached dwellings with private entrances and limited common space fill density gaps in Medellín and Guadalajara peripheral zones. Developers favor this format where zoning permits moderate density without full condominium infrastructure.
- Multi-Family Residences:Purpose-built rental apartment blocks attract institutional capital in Buenos Aires and Lima as inflation hedges. QuintoAndar-style platforms accelerate tenant turnover and reduce vacancy risk for yield-focused investors.
Condominiums sit at the top of the volume ranking, with multi-family residences climbing the fastest as rental platforms professionalize yield capture.
Customer Type:
Buyer composition shifts with mortgage market depth, as formal credit expansion pulls new demographic cohorts into ownership.
- First-Time Buyers:Young professionals and working-class households entering formal ownership through government-backed financing programs. Brazil's Casa Verde e Amarela income thresholds and Mexico's INFONAVIT points system filter eligibility by employment sector and savings history.
- Investors:Yield-focused purchasers targeting rental income in high-demand urban corridors. Colombian VIS-certified units in Bogotá peripheral zones attract this segment through subsidized interest rates and capital appreciation potential.
- Retirees:Downsizing households liquidating larger family homes for lower-maintenance units. Demand concentrates in temperate climate zones of Mexico's central plateau and Colombia's coffee region.
- Expats:Foreign nationals seeking secondary residences or remote-work bases in Latin American urban centers. Mexico City and Buenos Aires draw North American and European buyers leveraging currency arbitrage.
First-time buyers anchor volume leadership, while expats are gaining share fastest as remote-work normalization extends cross-border mobility.
Transaction Type:
Deal structure determines revenue timing and developer risk exposure, with digital infrastructure compressing friction in secondary market exchanges.
- Sales:Permanent ownership transfers generating upfront developer revenue and buyer equity accumulation. Blockchain title pilots in Chile and Mexico reduce notarial delays and expand mortgage lender confidence.
- Rentals:Recurring revenue contracts capturing professional-class mobility in São Paulo and Mexico City. Platform intermediation displaces informal broker networks and standardizes lease terms.
- Lease Options:Rent-to-own structures bridging credit-constrained households toward eventual ownership. Brazilian fintechs embed these products with automated savings mechanisms and credit-score building.
- Foreclosures:Distressed asset dispositions by financial institutions recovering non-performing mortgage exposure. Volume fluctuates with macroeconomic cycles and employment shocks in Argentina and Brazil.
Sales transactions hold volume dominance, with rentals expanding most quickly as platform economics professionalize recurring-revenue capture.
Financing Options:
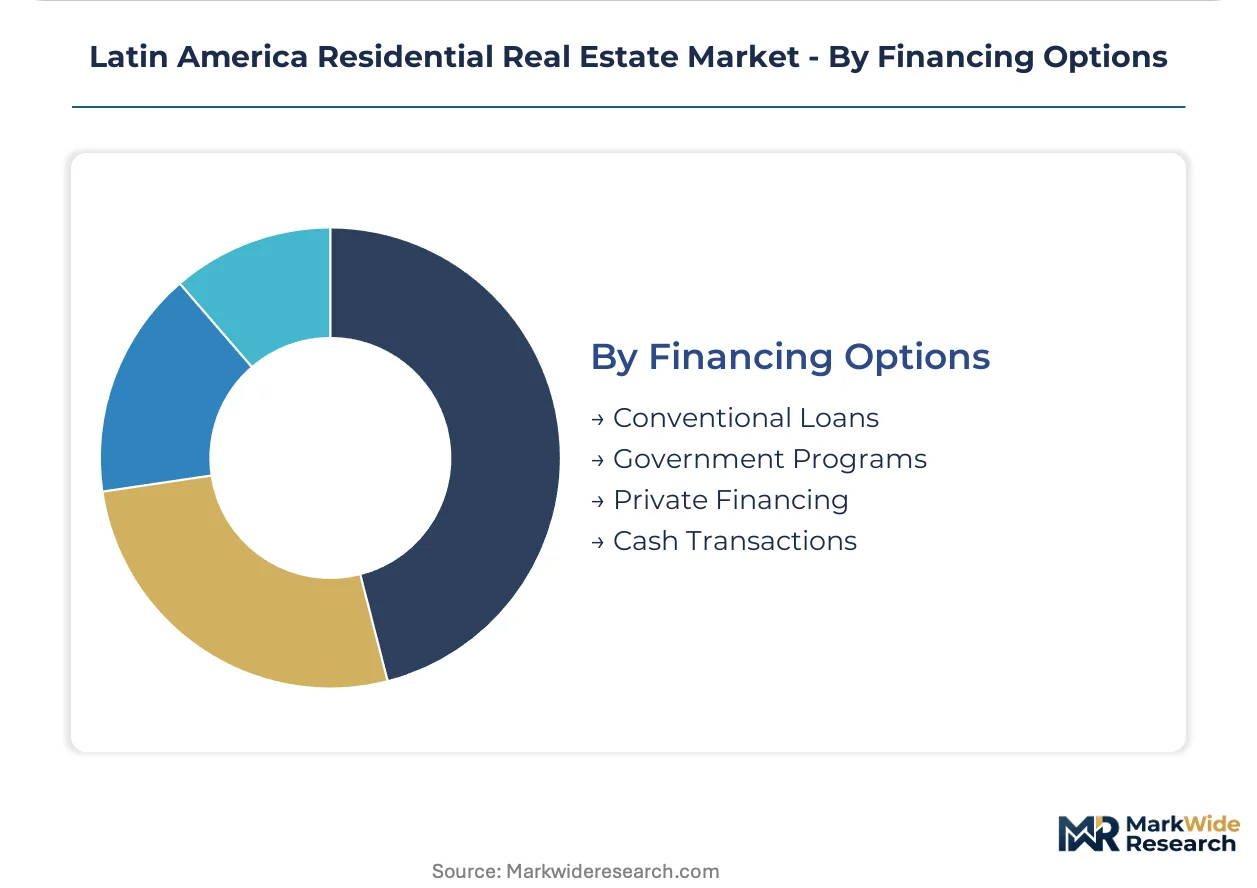
Capital source diversity shapes buyer accessibility and developer pricing power, with government programs filtering project specifications.
- Conventional Loans:Private bank mortgages with market-rate pricing and standard underwriting criteria. Mexican fiduciary certificate markets extend duration and reduce funding cost for prime borrowers.
- Government Programs:Subsidized-rate financing through Brazil's Casa Verde e Amarela, Mexico's INFONAVIT, and Colombia's VIS certification. Eligibility mandates minimum unit sizes, construction timelines, and buyer income ceilings.
- Private Financing:Non-bank lending from construction-linked lenders, employer housing funds, and informal credit circles. Interest rate premiums reflect collateral risk and limited regulatory oversight.
- Cash Transactions:Full upfront payment avoiding mortgage origination friction and interest burden. Concentrated among high-net-worth buyers and inflation-hedge investors in dollarized or currency-volatile economies.
Government programs lead volume, with conventional loans climbing fastest as securitization deepens and fintech credit scoring expands formal bank reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Latin American residential construction volume through its southeastern metropolitan corridor. Brazil's urban peripheries absorb government-subsidized demand while Mexico's central plateau clusters professionalize rental platforms. Chilean seismic codes and Colombian VIS certification reshape developer specifications across Andean markets.
Brazil
Southeastern metropolitan corridors concentrate Casa Verde e Amarela program deployment for lower-middle-income households. ANVISA-adjacent construction quality standards filter material specifications for affordable housing verticals. MRV Engenharia compresses delivery schedules through prefabricated component sourcing in São Paulo and Rio de Janeiro peripheral zones.
Mexico
INFONAVIT worker housing fund mandates tighten energy efficiency thresholds for subsidized unit eligibility. The central bank's fiduciary certificate markets extend mortgage duration for informal-sector workers previously excluded from formal credit. Querétaro and Guadalajara developers partner with equipment lessors to spread solar water heating capital costs across construction phases.
Colombia
VIS affordable housing certification creates subsidized interest-rate eligibility that attracts yield-focused investors to Bogotá peripheral zones. The national planning department's minimum unit size mandates filter project feasibility in Medellín density corridors. Antioquia and Cundinamarca construction clusters adapt to seismic code updates extending pre-construction permitting timelines.
Chile
Blockchain title registry pilots compress collateral verification timelines for mortgage lenders operating in informal settlements. Updated structural engineering certifications from the national building code commission extend permitting duration in Santiago high-risk seismic zones. Biobío and Valparaíso metropolitan areas concentrate mid-rise tower development targeting sustainability-certified buyers.
Argentina
Currency volatility propels dollar-denominated cash transactions among high-net-worth buyers seeking inflation hedges. The central bank's mortgage liquidity restrictions constrain formal credit expansion for first-time buyers in Buenos Aires. Córdoba and Rosario secondary markets attract platform-intermediated rental demand from mobile professionals.
Latin America Residential Real Estate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital transaction infrastructure and prefabricated construction systems. Brazilian developers concentrate vertically through in-house production of ceramic block and reinforced concrete components while Mexican platforms displace informal broker networks. Three archetypes dominate: vertically integrated construction conglomerates controlling land-to-delivery pipelines, fintech-enabled rental intermediaries capturing recurring-revenue pools, and modular system specialists compressing project timelines. Competitive moves center on strategic partnerships with equipment lessors for energy infrastructure and geographic expansion into peripheral zones eligible for government subsidy programs.
Among Brazilian publicly traded developers, MRV Engenharia e Participações S.A. and Cyrela Brazil Realty S.A. exemplify contrasting tier positioning—one representing volume-driven affordable housing delivery, the other anchoring premium architectural control in dense urban cores. QuintoAndar occupies a distinct archetype as a digital-native rental platform reducing broker dependency through algorithmic property matching. These three entities collectively illustrate how Latin American residential real estate fragments across construction execution, asset ownership, and transaction intermediation vectors.
| Leading Market Players |
|---|
| MRV Engenharia e Participações S.A. |
| Cyrela Brazil Realty S.A. |
| Gafisa S.A. |
| Tenda S.A. |
| Direcional Engenharia S.A. |
| Even Construtora e Incorporadora S.A. |
| QuintoAndar |
| La Haus |
| Habi |
| Others |
Pricing and Supply Chain Analysis
Prefabricated component standardization is compressing construction timelines in Brazilian affordable housing while simultaneously concentrating procurement power among engineered wood and light-gauge steel suppliers. This production-method transition reshapes cost economics by reducing on-site labor exposure and enabling volume pricing leverage, yet it tethers developer margins to imported material cost volatility and foreign exchange swings.
Pricing Analysis
Input-cost pass-through from cement and steel price volatility dominates pricing dynamics across fixed-price affordable housing contracts in Brazil and Mexico. Three-tier pricing structure across premium, standard, and economy levels separates Cyrela's architect-controlled São Paulo towers from MRV's volume-driven peripheral developments and informal self-built housing. Pricing pressure stems from ANVISA-adjacent construction quality standards that elevate material specifications without corresponding subsidy adjustments. First-time buyers under Casa Verde e Amarela income thresholds exhibit highest price sensitivity, while expat dollar-denominated purchasers in Buenos Aires show least elasticity.
Supply Chain Analysis
Dual-sourcing requirements from major Brazilian developers mandate multi-supplier qualification for ceramic block, reinforced concrete, and prefabricated structural components. Supply concentrates in Brazil, Mexico, and China for engineered wood products, with domestic construction clusters in São Paulo and Rio de Janeiro anchoring regional cement and steel production. Raw material dependencies on Portland cement, structural steel rebar, and imported cross-laminated timber create exposure to commodity price swings and logistics chokepoints at Santos port. Distribution runs through vertically integrated developer procurement divisions and third-party construction material distributors serving smaller regional builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Latin American residential real estate rests on prefabrication-driven cost compression in affordable housing and premium-tier architectural differentiation capturing inflation-hedge demand from high-net-worth buyers.
For Market Incumbents: Acquire land bank positions in southeastern Brazilian metropolitan corridors and Mexico's central plateau urban clusters before subsidy program eligibility maps crystallize. Consolidate ceramic block and reinforced concrete production capacity to defend against QuintoAndar-style platform disintermediation in rental transaction flows. Deepen relationships with INFONAVIT and Casa Verde e Amarela program administrators to secure preferential developer status as income thresholds tighten. For New Entrants and Emerging Players: Digital rental transaction infrastructure offers the lowest barrier to entry in São Paulo and Mexico City secondary markets where informal broker networks still dominate. Target lease-option and rent-to-own structures for credit-constrained households in Bogotá peripheral zones eligible for VIS certification subsidies. Deploy algorithmic property-matching platforms with embedded credit-score building to bypass traditional mortgage origination friction. For Investors and Strategic Acquirers: Roll-up economics work for fintech-enabled rental platforms because fragmented landlord ownership in Buenos Aires and Lima prevents institutional yield capture at scale. Long-term viability over the coming decade hinges on regulatory acceptance of blockchain title registries expanding mortgage lender confidence. Watch Chile's national building code commission seismic certification timelines as the signal indicating permitting velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Construction Scale-Up | MRV Engenharia's component sourcing model compresses delivery schedules in São Paulo affordable housing verticals. |
| Digital Title Registry Pilot Expansion | Blockchain collateral verification in Chile and Mexico reduces mortgage lender risk exposure in informal settlements. |
| Energy Infrastructure Partnership | Querétaro developers leasing solar water heating equipment spread capital costs across construction phases. |
| Platform Integration with Mortgage Securitization | QuintoAndar's algorithmic matching connects INFONAVIT-qualified buyers to previously invisible secondary inventory. |
| Geographic Expansion into VIS-Eligible Zones | Bogotá peripheral development captures subsidized interest-rate demand from yield-focused investors. |
Research Methodology
Bottom-up housing unit modeling reconciled against top-down construction permit tracking forms the analytical core of this study. Primary interviews with real estate development executives, mortgage securitization specialists, government housing fund administrators, and prefabricated component suppliers were validated against secondary sources including ANVISA construction quality filings, INFONAVIT beneficiary databases, Brazilian federal subsidy program disclosures, and Chilean national building code commission regulatory updates. Cross-referencing of fiduciary certificate market issuance data with fintech credit-scoring platform transaction records enabled triangulation of informal-sector lending expansion.
Input-output matrix framing connects demographic cohort projections to housing unit absorption rates across property type, customer segment, and financing option dimensions. The analytical framework models demand evolution over the projection horizon through segmentation by structural form, buyer income tier, transaction mechanism, and capital source. CAGRs derive from regression analysis of historical construction volume against mortgage origination depth, subsidy program enrollment, and urban land price appreciation. Forecast inputs incorporate seismic code compliance timeline scenarios and digital title registry adoption curves.
Cement price volatility, land titling fragmentation in peri-urban Colombia and Peru, and fintech platform substitution effects are the dominant revision risks to the outlook. Deviation in government subsidy program funding continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
United Arab Emirates Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market