
 UK Real Estate Market | 2026-2036
UK Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
UK Real Estate Market Insights
The gap between premium-grade logistics assets and secondary commercial stock is expanding as institutional capital chases yield security. SEGRO leverages its dominant position in big-box warehousing around London Heathrow to sustain occupancy premiums. Barratt Developments anchors its pipeline in energy-efficient homes to navigate tightening building regulations. Taylor Wimpey differentiates through regional land banking that controls development costs outside overheated southern markets.
UK real estate encompasses land and permanent structures used for residential habitation, commercial activity, industrial operations, or agricultural production, with assets valued on location quality, lease duration, tenant covenant strength, and energy performance certificate ratings. Residential property absorbs the largest capital allocation as mortgage affordability constraints push demand toward affordable housing and build-to-rent schemes. Industrial logistics commands the fastest rent growth as e-commerce fulfillment requirements reshape last-mile specifications. Student accommodation and luxury properties concentrate margin pools through operational intensity and scarcity premiums respectively.
The UK's Building Safety Act, enforced by the Building Safety Regulator, imposes gateway compliance duties on developers that extend project timelines and elevate capital requirements. MHCLG planning reforms and the Future Homes Standard mandate net-zero-ready construction that filters development feasibility toward scale operators. Stakeholders must monitor how interest rate trajectories and evolving ESG disclosure rules under the UK Green Taxonomy reshape asset pricing and portfolio allocation decisions.
Market Dynamics
The UK's Building Safety Act imposes gateway compliance duties that extend development timelines and elevate capital requirements, filtering project feasibility toward scale operators with regulatory expertise and balance sheet depth.
Growth Catalysts
- Build-to-Rent Capital Flows:Institutional investors seeking yield stability channel funds into professionally managed residential assets, expanding the investable universe beyond traditional owner-occupied housing.
- MHCLG Planning Reforms:Streamlined consent processes for brownfield regeneration accelerate project delivery in Greater Manchester and Birmingham's urban cores.
- E-Commerce Logistics Specifications:Last-mile fulfillment requirements from retail tenants drive demand for high-bay warehousing with EV charging infrastructure around London Heathrow.
Market Restraints
- Construction Input Volatility:Steel and timber price fluctuations compress development margins on mid-market residential schemes outside London's prime zones.
- Land Supply Concentration:Strategic land banking by major housebuilders limits site availability for regional developers in southern England's overheated corridors.
- Interest Rate Sensitivity:Mortgage affordability constraints tighten first-time buyer access, dampening transaction velocity in price-sensitive segments.
Strategic Opportunities
- Future Homes Standard Alignment:Net-zero-ready construction mandates create first-mover advantage for developers mastering heat pump integration and fabric efficiency.
- Student Accommodation Operational Intensity:Purpose-built PBSA assets in university towns like Nottingham and Leeds capture premium rents through amenity-rich service models.
- Life Sciences Conversion:Obsolete office stock in Cambridge and Oxford's innovation clusters repurposes for laboratory and R&D facilities.
Industry Challenges
- Building Safety Regulator Compliance:Gateway 2 and Gateway 3 sign-off requirements demand specialized fire engineering expertise that outstrips current consultant capacity.
- Retrofit Capex Burden:Existing stock EPC upgrades to minimum C ratings by 2035 require capital deployment that strains legacy portfolio returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Real Estate Market |
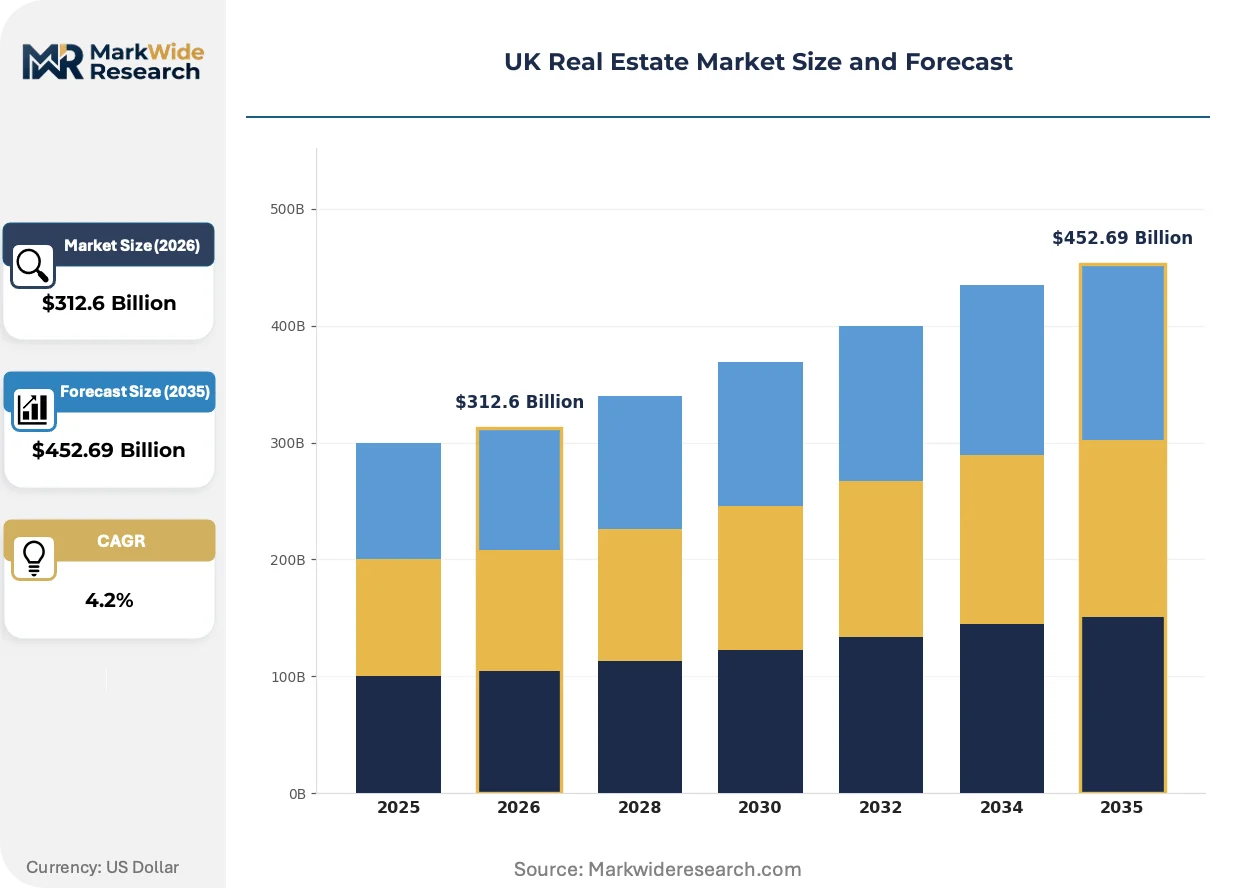
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $452.69 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Agricultural Customer Type: First-Time Buyers, Investors, Renters, Property Developers Financing Model: Fixed-Rate Mortgage, Buy-to-Let, Equity Release, Cash Purchase Market Segment: Luxury Properties, Affordable Housing, Student Accommodation, Foreclosed Properties |
| Companies Covered | SEGRO, Barratt Developments, Taylor Wimpey, Persimmon, Bellway, Land Securities Group, Grainger, Savills, Knight Frank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Real Estate Market Trends and Innovations
Digital construction methods and tightening environmental mandates are compressing traditional development cycles while elevating performance standards across asset classes.
Modular offsite manufacturing is rewriting delivery economics for residential schemes. Housebuilders deploying volumetric construction in Scotland and northern England compress programme durations by 30-50% against traditional methods. Factory-controlled quality reduces snagging costs and accelerates cash conversion, though transport radius constraints limit deployment density.
The UK's Future Homes Standard mandates fossil-fuel-free heating in new dwellings from 2025. Developers in Bristol and Cardiff pilot heat pump-ready fabric specifications that exceed current building regulations. Compliance cost premiums of 15-25% filter development viability toward scale operators with procurement leverage over M&E contractors.
Tenant sustainability screening now precedes lease commitment decisions in prime logistics and office assets. Corporate occupiers in London's South Bank and Manchester's Spinningfields district require BREEAM Excellent or EPC A ratings as non-negotiable criteria. Landlords without certified stock face extended void periods or rental discounts against compliant competing supply.
UK Real Estate Market Segmentation

UK real estate segmentation reveals how capital allocation, regulatory exposure, and tenant demand diverge across asset classes and transaction structures. Understanding these fault lines enables stakeholders to match risk appetite with appropriate entry points.
Property Type:
Upgrade cycles vary dramatically across physical asset categories, with functional obsolescence driving replacement demand in some segments while locational permanence protects others.
- Residential:Comprises single-family dwellings, apartments, and build-to-rent schemes with EPC ratings increasingly governing mortgage eligibility. Demand concentrates in Greater Manchester's urban cores and London's outer boroughs where Help-to-Buy legacy stock requires energy retrofitting.
- Industrial:Encompasses logistics warehousing, manufacturing facilities, and distribution centers with specifications evolving toward higher bay heights and EV charging capacity. Last-mile fulfillment requirements around London Heathrow and the Midlands Golden Triangle command rent premiums as e-commerce tenants prioritize speed-to-consumer.
- Commercial:Office and retail assets facing accelerated obsolescence as hybrid work patterns and experiential retail reshape space requirements. Secondary stock in regional city centers confronts extended void periods without substantial capital reinvestment.
- Agricultural:Farmland and rural estates valued on soil quality, subsidy entitlements, and development optionality under MHCLG planning reforms. Institutional investors target strategic land with residential conversion potential in southern England's growth corridors.
Residential sits at the top of the volume ranking, with Industrial climbing the fastest.
Customer Type:
Buyer motivation and holding-period expectations create distinct behavioral segments with divergent sensitivity to interest rate trajectories and policy shifts.
- First-Time Buyers:Households entering ownership through government schemes or family assistance, constrained by deposit requirements and mortgage affordability tests. Lender criteria tightening around debt-to-income ratios filters access toward dual-income households in stable employment sectors.
- Investors:Individuals and institutions acquiring income-generating assets, with buy-to-let landlords navigating Section 24 tax changes and selective licensing expansion. Professionalization of the sector favors portfolio operators over accidental landlords.
- Renters:Households priced out of ownership or prioritizing flexibility, increasingly channeled toward build-to-rent providers with professional management and amenity packages. Demand concentrates among young professionals in Bristol, Leeds, and Birmingham's regenerated districts.
- Property Developers:Entities controlling land positions and construction pipelines, with scale operators leveraging balance sheet depth to absorb Building Safety Act compliance costs that strain smaller competitors.
Investors account for the largest transaction value aggregate, with Renters expanding most quickly as tenure patterns shift.
Financing Model:
Capital structure choices determine exposure to monetary policy transmission and regulatory intervention across the property cycle.
- Fixed-Rate Mortgage:Long-term rate locks protecting borrowers from Bank of England base rate volatility, with two and five-year products dominating origination volumes. Lender pricing reflects funding cost pressures and risk-weighted capital requirements.
- Buy-to-Let:Specialist lending to investor purchasers with stress-testing criteria incorporating interest coverage ratios and portfolio leverage limits. Regulatory scrutiny of landlord taxation and tenant protection measures elevates compliance burdens.
- Equity Release:Lifetime mortgages and home reversion plans enabling older homeowners to access housing wealth without displacement, with product innovation addressing inheritance planning objectives.
- Cash Purchase:Unlevered acquisitions by domestic and international capital, prevalent in prime central London and trophy asset categories where currency diversification or wealth preservation motivates deployment.
Fixed-Rate Mortgage dominates origination volumes, with Equity Release gaining share fastest among demographic tailwinds.
Market Segment:
Price positioning and operational intensity create tiered margin profiles with varying capital efficiency characteristics.
- Luxury Properties:Prime central London and country estate assets trading on scarcity, architectural significance, and privacy amenities. International purchaser participation fluctuates with currency movements and geopolitical capital flight patterns.
- Affordable Housing:Subsidized tenure products and sub-market rental stock delivered through Section 106 planning obligations and registered provider pipelines. Grant funding constraints and development cost inflation strain delivery targets.
- Student Accommodation:Purpose-built PBSA assets in university towns with operational intensity capturing premium rents through service packaging and community programming. Nottingham, Leeds, and Manchester clusters attract institutional capital seeking yield stability.
- Foreclosed Properties:Distressed assets entering market through lender enforcement or insolvency processes, requiring rehabilitation capital and legal clearance before reintroduction to conventional sale channels.
Affordable Housing represents the largest policy-addressable segment, with Student Accommodation posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's concentration of planning consultants and fire engineering specialists anchors the nation's development expertise. Regional talent pools in Manchester and Birmingham sustain build-to-rent execution capacity outside the capital. Scotland's land reform expertise and Wales's community housing models diversify the UK's property development skill base.
London and the Southeast
Institutional capital seeking yield stability concentrates in Heathrow-adjacent logistics corridors and Thames Valley distribution nodes. The Building Safety Regulator's gateway compliance duties extend timelines for high-rise residential schemes across the capital. Canary Wharf and South Bank office clusters face accelerated obsolescence as hybrid work patterns reshape tenant requirements.
Greater Manchester
Build-to-rent developers channel funds into Salford Quays and Ancoats regeneration zones where young professionals cluster. MHCLG planning reforms streamline brownfield consent processes for former industrial sites. The Trafford logistics hub captures e-commerce fulfillment demand with EV-ready warehousing specifications.
West Midlands
Birmingham's Big City Plan attracts residential investment toward Digbeth and Eastside regeneration corridors. The West Midlands Combined Authority coordinates strategic land release for housing delivery. Solihull's proximity to the Midlands Golden Triangle positions logistics assets for last-mile distribution optimization.
Scotland
Edinburgh's constrained greenbelt policy elevates land values for brownfield residential intensification. The Scottish Government's Heat in Buildings Strategy mandates zero-emission heating retrofits by 2045. Glasgow's Clyde waterfront regeneration attracts institutional capital to purpose-built student accommodation clusters.
Wales
Cardiff's central enterprise zone delivers office and residential stock through development corporation frameworks. Welsh Government planning policy prioritizes affordable housing quotas in major urban extensions. Swansea Bay's tidal lagoon adjacency shapes speculative land banking for future energy infrastructure corridors.
UK Real Estate Market Competitive Landscape
Capital-heavy land banks compete with asset-light development managers for project execution margins. The market structure concentrates around five national housebuilders controlling strategic land positions across southern England. Three strategic archetypes dominate: scale-integrated volume builders, specialist rental landlords, and logistics REITs with captive development pipelines. Competitive moves center on land option accumulation and modular construction partnerships that compress programme durations.
Among London-listed REITs, SEGRO exemplifies the logistics-focused archetype with Heathrow corridor dominance. Barratt Developments and Taylor Wimpey represent the volume housebuilder tier, each navigating Building Safety Act compliance through standardized design protocols. These three entities anchor the competitive spectrum from income-generating assets to development-led growth models.
| Leading Market Players |
|---|
| SEGRO |
| Barratt Developments |
| Taylor Wimpey |
| Persimmon |
| Bellway |
| Land Securities Group |
| Grainger |
| Savills |
| Knight Frank |
| Others |
Pricing and Supply Chain Analysis
Fire engineering specialists concentrated in London command premium fees that widen pricing spreads between compliant and non-compliant residential schemes. Labor-cost differentials between the capital's consultant pool and regional capacity constrain developers' ability to absorb Building Safety Act compliance premiums outside the Southeast.
Pricing Analysis
Bundled turnkey development contracts dominate prime logistics and build-to-rent segments, while unbundled land-plus-construction arrangements persist in speculative residential. Three-tier pricing structure across premium, standard, and economy levels reflects EPC rating bands and gateway compliance status. Pricing pressure stems from steel and timber input volatility compressing margins on mid-market housing. First-time buyers exhibit acute price sensitivity, whereas institutional investors in income-generating assets prioritize yield stability over absolute cost.
Supply Chain Analysis
Reverse-logistics flows for modular housing components create refurbishment and redeployment opportunities as developers reclaim volumetric units from completed schemes. Manufacturing draws from factory facilities in Scotland, northern England, and the Midlands, with transport radius constraints limiting deployment density. Timber, steel, and heat pump systems constitute critical input dependencies. Single-source vulnerability concentrates in fire engineering consultant capacity for Gateway 2 and 3 sign-offs. Distribution runs through regional housebuilder procurement networks and direct developer-contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Greater Manchester's streamlined brownfield consent processes and London's extended Building Safety Regulator timelines, with compliance-cost differentials favoring northern development pipelines.
For Market Incumbents: Cement regulatory expertise advantages by acquiring fire engineering consultancies strained by Gateway capacity constraints. Scale operators should consolidate strategic land positions in the West Midlands Combined Authority corridors before MHCLG planning reforms accelerate competition. Building Safety Act compliance costs filter viability toward balance-sheet depth.
For New Entrants and Emerging Players: Proptech-enabled direct-to-tenant platforms offer low-capital entry into build-to-rent management services. Purpose-built student accommodation in Nottingham and Leeds clusters presents the most penetrable institutional segment. Partner with modular manufacturers for offsite construction capabilities that compress programme durations against traditional methods.
For Investors and Strategic Acquirers: Logistics REITs with captive development pipelines are the most active acquirer in this space, targeting Heathrow-adjacent warehousing assets. Long-term viability hinges on portfolio EPC trajectories toward net-zero-ready specifications. Monitor interest rate trajectories and tenant sustainability screening intensity as inflection indicators for asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Construction Partnership | Factory-controlled quality reduces snagging costs and accelerates cash conversion for residential schemes. |
| Fire Engineering Consultancy Acquisition | Captures scarce Gateway 2 and 3 sign-off capacity required by Building Safety Act mandates. |
| Strategic Land Banking | Controls development costs in Greater Manchester and Birmingham urban cores ahead of planning reform. |
| Heat Pump-Ready Fabric Investment | Positions developments ahead of Future Homes Standard fossil-fuel-free heating mandates from 2025. |
| EV-Ready Warehousing Specification | Captures last-mile logistics premiums around London Heathrow and the Midlands Golden Triangle. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged land directors at national housebuilders, fire engineering consultants, planning officers at MHCLG, institutional asset managers, and modular manufacturing executives. Secondary validation drew from MHCLG planning statistics, Building Safety Regulator gateway data, HM Land Registry transaction records, and REIT regulatory filings. Bottom-up project pipeline enumeration and top-down capital flow analysis were triangulated against sector-level aggregates.
Segment-weighting approaches allocated value and volume across property type, customer type, financing model, and market segment dimensions. CAGRs were derived from trend extrapolation moderated by regulatory timeline assumptions and interest rate scenario inputs. Modeling incorporated Building Safety Act compliance cost curves, Future Homes Standard construction premiums, and e-commerce logistics specification evolution across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for heat pump integration and modular manufacturing scale-up would alter the outlook. Forecasts reflect assumptions about regulatory enforcement intensity and institutional capital allocation preferences. Practitioners should monitor Bank of England policy trajectories and ESG disclosure rule evolution under the UK Green Taxonomy for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
Egypt Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market