
 Spain Manufactured Homes Market | 2026-2036
Spain Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Manufactured Homes Market Analytics
The gap between premium manufactured homes and commodity-grade units is expanding. ALUCASA Mobile Homes leverages its vertical integration to control material costs and delivery timelines. COFITOR Prefabricated Houses anchors its position through specialized designs for coastal tourism zones. Sismo Building Technology differentiates via seismic-resistant structural systems that command higher pricing.
Spain manufactured homes are factory-built residential structures constructed offsite and transported to permanent or semi-permanent foundations, typically featuring steel or timber frames with insulated wall panels and integrated utility channels designed for rapid assembly. Single-section units dominate volume sales among retirement communities seeking compact, manageable footprints, while custom homes capture the widest margin pools as investors commission architecturally distinctive vacation rental properties. Modular installation methods lead growth trajectories due to shorter on-site construction windows and reduced labor dependency.
Spain's Technical Building Code (CTE) and the Ministry of Transport and Housing enforce thermal efficiency and structural safety standards that elevate compliance costs for smaller producers. The European Union's Energy Performance of Buildings Directive pushes manufacturers toward near-zero energy specifications, reshaping material procurement and design workflows. Stakeholders must monitor how regional urban planning reforms in Catalonia and the Balearic Islands alter zoning permissions for temporary versus permanent installations.
Market Dynamics
Spain's manufactured homes sector is undergoing a structural recalibration as the Technical Building Code (CTE) tightens thermal performance mandates while coastal tourism investors demand architecturally distinctive vacation rental units that command premium nightly rates.
Growth Catalysts
- CTE Thermal Efficiency Mandates:Spain's updated Technical Building Code requires near-zero energy specifications for new residential construction, pushing developers toward factory-built solutions with integrated insulation and controlled assembly environments.
- Retirement Community Concentration:Andalusia and the Valencian Community host expanding retirement demographics seeking compact, single-section units with manageable footprints and reduced maintenance obligations.
- Modular Installation Methods:Shorter on-site construction windows and reduced labor dependency make modular approaches attractive for tourism zone developments where seasonal construction windows are narrow.
Market Restraints
- Steel and Timber Input Volatility:Frame material costs fluctuate with European construction commodity cycles, squeezing margin predictability for producers without captive supply arrangements.
- Compliance Cost Burden:Spain's Ministry of Transport and Housing enforcement of structural safety standards elevates fixed costs disproportionately for smaller producers lacking scale economies in certification workflows.
- Site-Built Substitution:Traditional masonry construction retains preference among domestic buyers in inland provinces where land costs are lower and aesthetic familiarity dominates purchase decisions.
Strategic Opportunities
- Balearic Islands Zoning Reform:Pending urban planning revisions may expand permissions for permanent manufactured installations currently restricted to temporary tourism accommodations.
- EU Energy Performance of Buildings Directive:Near-zero energy specifications create procurement pull for manufacturers with pre-certified envelope systems and integrated renewable-ready utility channels.
- Cross-Laminated Timber Convergence:Hybrid steel-timber structural systems combining seismic performance with biogenic material appeal open positioning for coastal luxury segments.
Industry Challenges
- Seismic Certification Timelines:Sismo-resistant structural system approvals require extended testing protocols that delay product launches and tie up engineering resources.
- Installation Labor Specialization:Rapid assembly methods demand crews trained in precision foundation alignment and utility channel integration, skills scarce in Spain's fragmented construction workforce.
- Utility Integration Complexity:Factory-built utility channels must interface with heterogeneous regional grid standards across Catalonia, Andalusia, and the Valencian Community.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Manufactured Homes Market |
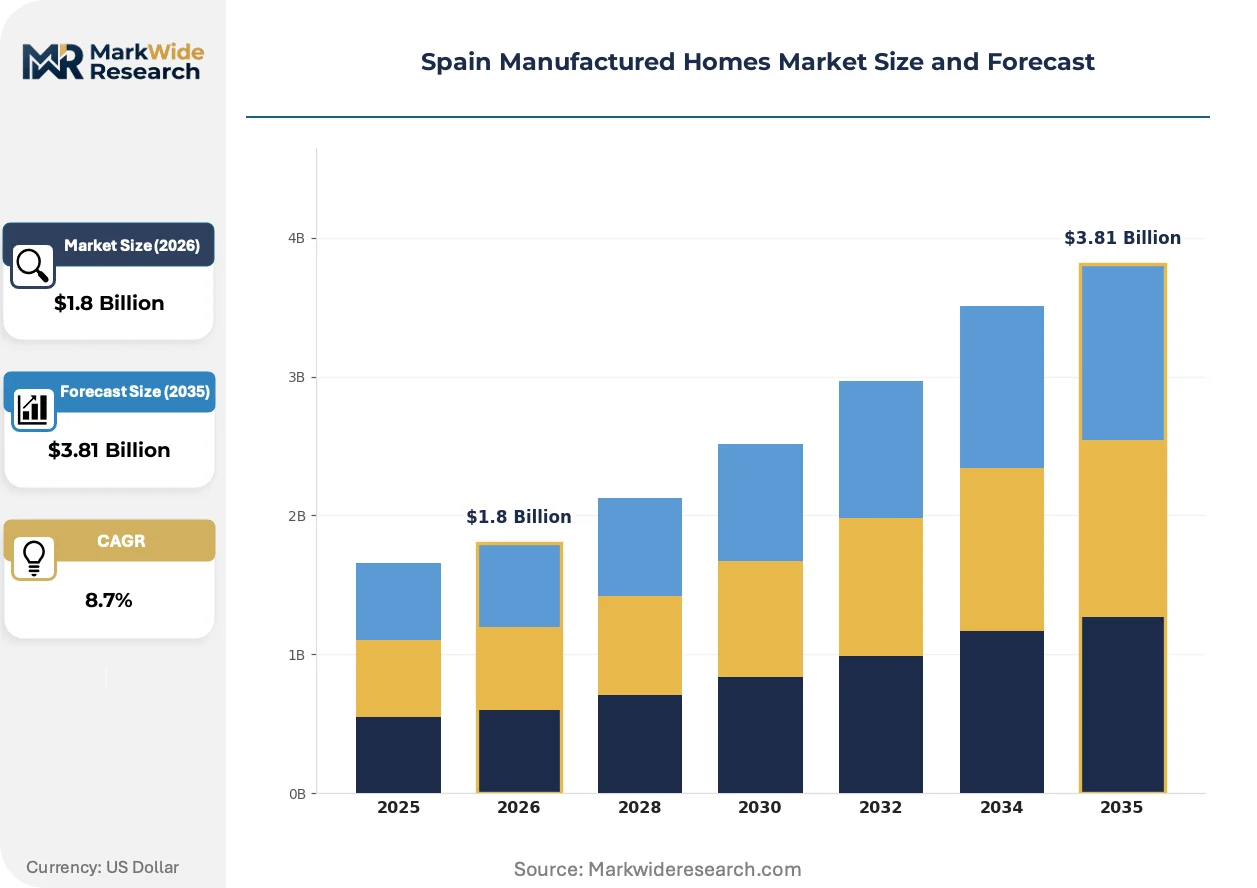
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Double-Section, Triple-Section, Custom Homes Installation Type: Permanent, Temporary, Modular, Offsite End User: Families, Investors, Retirement Communities, Vacation Rentals Utility Connection: Electricity, Water, Sewage, Internet |
| Companies Covered | ALUCASA Mobile Homes, COFITOR Prefabricated Houses, Sismo Building Technology, Custom Home - Casas Modulares Huércal, Construcciones Modulares CUNI, Modular Homes España, HabiTera, Casa Modular, Baufritz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Manufactured Homes Market Evolving Landscape
Factory fabrication workflows are absorbing digital design tools and material science advances that compress delivery timelines while elevating architectural differentiation. Three developments are restructuring competitive positioning.
Cross-laminated timber panels are absorbing moisture-regulation and fire-retardant treatments that expand their deployment beyond interior finishes to primary structural envelopes. Coastal tourism investors in the Balearic Islands and Costa del Sol are specifying these systems for vacation rental properties where biogenic material narratives support premium positioning. The technology is absorbing market share from conventional steel-frame alternatives in segments where aesthetic distinction commands rate premiums.
Spain's Technical Building Code updates align with the European Union's Energy Performance of Buildings Directive to mandate near-zero energy specifications for new residential units. Manufacturers must reconfigure procurement workflows to source high-performance insulation, triple-glazed envelope components, and heat-recovery ventilation systems. Producers with pre-certified building envelope platforms gain timeline advantages in Andalusia and the Valencian Community where permit review cycles are compressing.
Tourism zone developers are consolidating procurement authority through direct manufacturer relationships that disintermediate traditional construction intermediaries. Channel concentration is visible in coastal Andalusia where vacation rental investors commission architecturally distinctive custom units for short-term rental portfolios. Developers with captive installation crews and repeat-order volume are extracting price concessions and priority production slots from fabricators.
Spain Manufactured Homes Market Segmentation
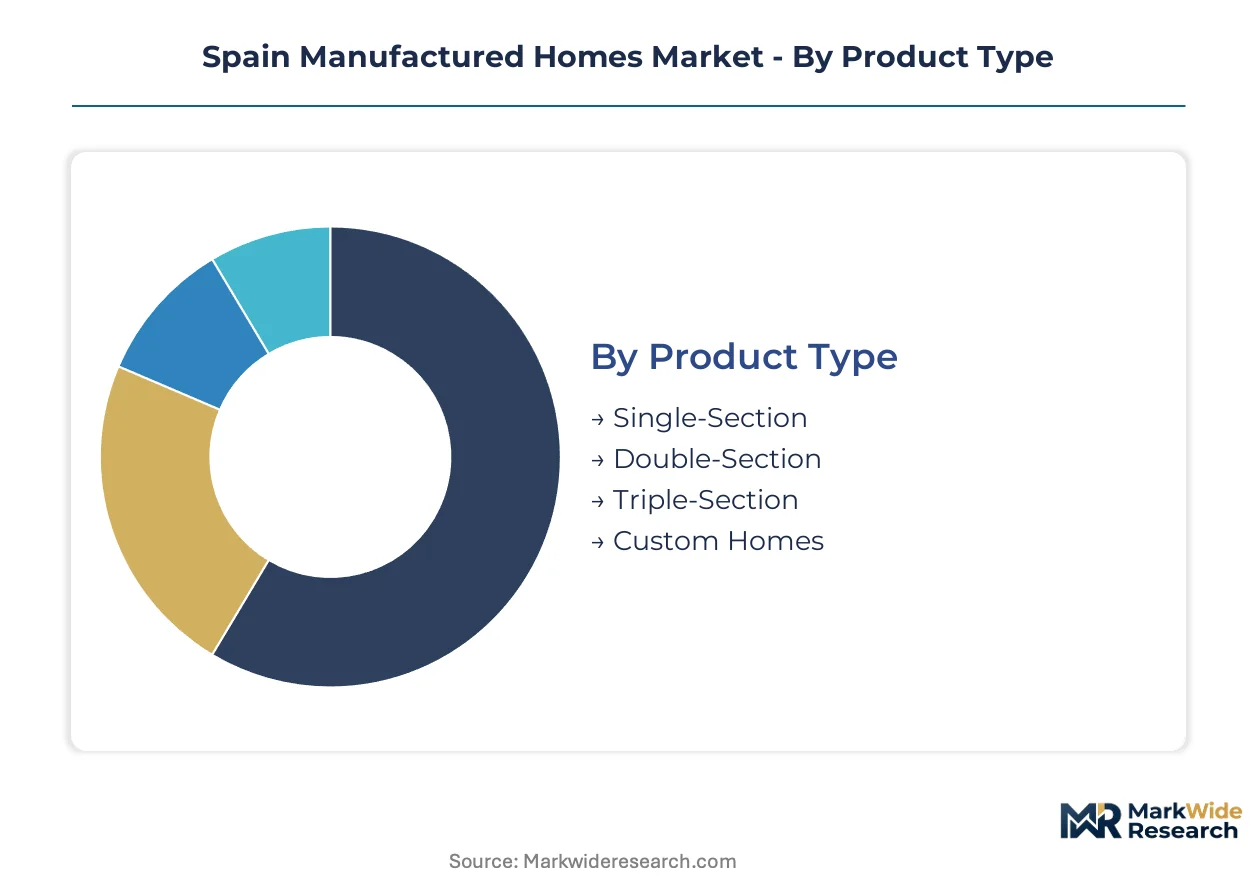
Manufactured homes in Spain fragment across structural, regulatory, and usage dimensions that determine fabrication workflows and margin profiles. Understanding these divides reveals where procurement authority concentrates and which specifications command premium positioning.
Product Type:
Supply concentration tilts toward compact, standardized units that minimize engineering overhead and permit turnaround.
- Single-Section:Compact steel or timber-frame units with integrated utility channels and minimal foundation requirements. Retirement communities in Andalusia and the Valencian Community specify these for manageable footprints and reduced maintenance obligations.
- Custom Homes:Architecturally distinctive units commissioned with non-standard envelope specifications and premium finishes. Coastal tourism investors in the Balearic Islands and Costa del Sol drive demand for vacation rental portfolios commanding premium nightly rates.
- Double-Section:Dual-module configurations offering expanded living space through parallel transport and on-site joining.
- Triple-Section:Three-module assemblies for larger residential footprints requiring complex foundation alignment and extended installation windows.
Single-Section absorbs the bulk of installed capacity; Custom Homes is expanding most quickly.
Installation Type:
Cost tier differentiation separates capital-intensive permanent foundations from lower-commitment temporary deployments.
- Modular:Factory-fabricated volumetric units with pre-installed utilities and controlled-assembly quality. Tourism zone developers in coastal Andalusia favor these for narrow seasonal construction windows and reduced on-site labor dependency.
- Permanent:Fixed-foundation installations subject to full Technical Building Code compliance and municipal occupancy permits. Families in inland provinces prefer these for long-term residential security and financing accessibility.
- Temporary:Semi-permanent foundations with simplified permitting for seasonal or provisional occupancy.
- Offsite:Panelized or component-based systems requiring substantial on-site assembly and finishing labor.
Permanent foundations anchor the revenue base; Modular approaches are gaining share fastest.
End User:
Customer type determines specification intensity, with institutional buyers extracting volume concessions unavailable to individual purchasers.
- Retirement Communities:Age-restricted developments specifying single-section units with accessibility features and low-maintenance envelopes. Concentrated demand in Andalusia and the Valencian Community drives repeat-order procurement patterns.
- Investors:Portfolio operators commissioning architecturally distinctive units for short-term rental yield optimization. Direct manufacturer relationships in coastal zones disintermediate traditional construction intermediaries.
- Families:Owner-occupant purchasers prioritizing cost predictability and financing accessibility over customization.
- Vacation Rentals:Tourism accommodation operators seeking rapid deployment for seasonal occupancy peaks.
Retirement Communities absorb the bulk of installed capacity; Investors is climbing the fastest.
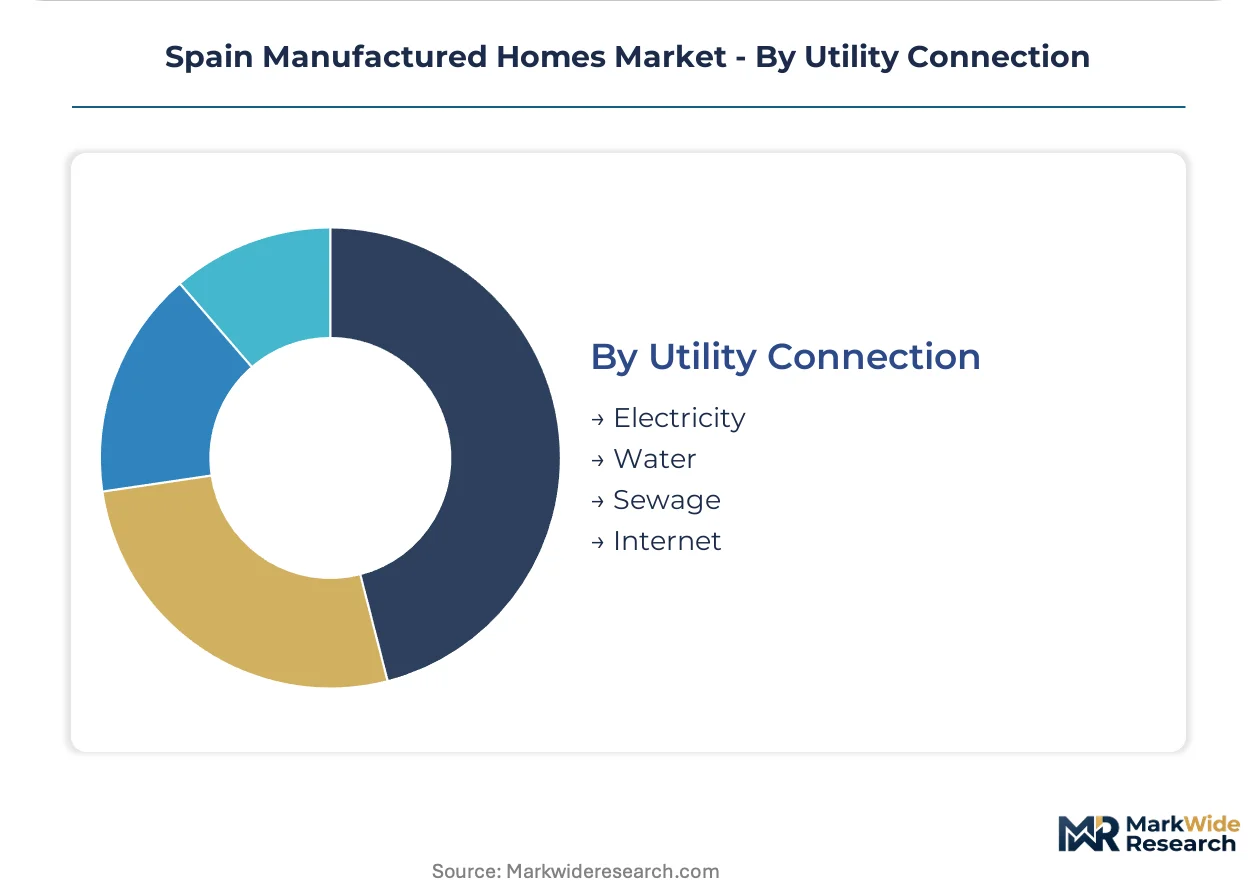
Utility Connection:
Application focus varies from basic habitation requirements to connectivity-dependent remote work accommodations.
- Electricity:Grid-tied or solar-ready power distribution systems with pre-wired panels and inverter accommodation. All end-user segments require this as baseline infrastructure.
- Internet:Fiber-optic or satellite-ready conduit pre-installation for remote work and entertainment streaming. Vacation rental investors in the Balearic Islands specify this as competitive necessity.
- Water:Municipal connection or rainwater harvesting integration with pressure-regulated distribution.
- Sewage:Gravity or pump-based wastewater systems with regional treatment compliance.
Electricity absorbs the bulk of installed capacity; Internet is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valencia anchors Spain's manufactured homes production corridor, with coastal tourism investors and retirement community developers clustering along the Mediterranean basin from Catalonia through Andalusia.
Catalonia
Barcelona's metropolitan periphery hosts engineering-intensive fabricators serving cross-border French demand and domestic coastal projects. The Generalitat de Catalunya enforces stringent seismic standards under regional building codes that exceed national CTE baselines. Girona province concentrates vacation rental developers commissioning architecturally distinctive modular units for Costa Brava tourism zones.
Valencia
Alicante and Castellón provinces generate the densest retirement community installations, with British and German expatriates driving single-section unit specifications. The Valencian regional government maintains simplified permitting pathways for temporary tourism accommodations that manufacturers exploit for rapid deployment. Benidorm's surrounding municipalities host the highest concentration of repeat-order procurement from institutional investors.
Andalusia
Costa del Sol municipalities from Málaga to Cádiz absorb premium custom home volumes for short-term rental portfolios targeting international tourists. The Junta de Andalucía's coastal urban planning reforms are expanding permanent foundation permissions beyond previous temporary-only restrictions. Seville's inland corridor shows emerging family demand as land costs pressure conventional masonry construction.
Madrid
The capital's periphery serves as a distribution and logistics hub rather than primary manufacturing concentration, with units trucked southward to coastal demand centers. Madrid's municipal building department enforces full CTE compliance for permanent installations, elevating certification costs relative to temporary-permit zones. The Corredor del Henares industrial corridor hosts component suppliers serving Valencia and Andalusia fabricators.
Basque Country
Bilbao and San Sebastián anchor northern Spain's limited manufactured homes penetration, with cooler maritime climates reducing tourism accommodation demand relative to Mediterranean zones. The Eusko Jaurlaritza promotes industrialized construction through regional innovation grants that favor timber-frame systems. Gipuzkoa province hosts specialized engineering consultancies serving seismic-resistant structural design for export markets.
Spain Manufactured Homes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across architectural customization and regulatory certification dimensions, with the vendor base stratifying between volume-driven standard unit producers and design-intensive custom fabricators. Three archetypes dominate: vertically integrated material controllers capturing cost predictability, coastal tourism specialists commanding rate premiums through distinctive aesthetics, and seismic engineering licensors extracting technology fees. Consolidation pressure is accelerating through direct developer-manufacturer relationships that disintermediate traditional construction intermediaries, while regional permit complexity is forcing smaller producers toward specialty niches or exit.
Among Spain-based fabricators, ALUCASA Mobile Homes, COFITOR Prefabricated Houses, and Sismo Building Technology occupy distinct positioning vectors. ALUCASA exemplifies the material-control archetype through captive supply arrangements that compress delivery timelines. COFITOR represents coastal tourism specialization with properties concentrated in Mediterranean demand zones. Sismo Building Technology anchors the engineering-licensing tier, with seismic-resistant systems commanding premium positioning in structurally regulated markets. Custom Home - Casas Modulares Huércal and Construcciones Modulares CUNI sit within mid-scale regional fabrication, while Modular Homes España and HabiTera occupy emerging positions in the standard-unit volume segment.
| Leading Market Players |
|---|
| ALUCASA Mobile Homes |
| COFITOR Prefabricated Houses |
| Sismo Building Technology |
| Custom Home - Casas Modulares Huércal |
| Construcciones Modulares CUNI |
| Modular Homes España |
| HabiTera |
| Casa Modular |
| Baufritz |
| Others |
Value Network & Pricing Analysis
Captive supply of cross-laminated timber and steel framing anchors both production continuity and margin defense for Spain's manufactured homes fabricators. ALUCASA's backward integration into aluminum extrusion and panel fabrication compresses delivery timelines while insulating unit economics from European commodity cycles.
Pricing Analysis
Value-based pricing anchored to rental yield outcomes dominates coastal tourism segments where vacation rental investors commission architecturally distinctive units. Certification grade under the Technical Building Code and volume scale separate premium custom homes from standardized single-section retirement units. Cost compression in commodity-grade segments is intensifying as smaller producers absorb disproportionate compliance burdens. Retirement communities exhibit highest price sensitivity while tourism investors prioritize nightly rate premiums over upfront unit costs.
Supply Chain Analysis
Dual-sourcing qualification mandates from institutional developers in Andalusia and the Valencian Community push fabricators toward qualified secondary suppliers for insulation and glazing components. Steel draws from mills in Spain and Germany; timber feeds from Nordic and Baltic producers; utility systems source from regional Spanish electromechanical specialists. Single-source vulnerability concentrates in seismic certification testing capacity where Sismo Building Technology's protocols face limited qualified alternatives. Distribution runs through manufacturer-direct relationships that disintermediate traditional construction intermediaries in coastal tourism zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
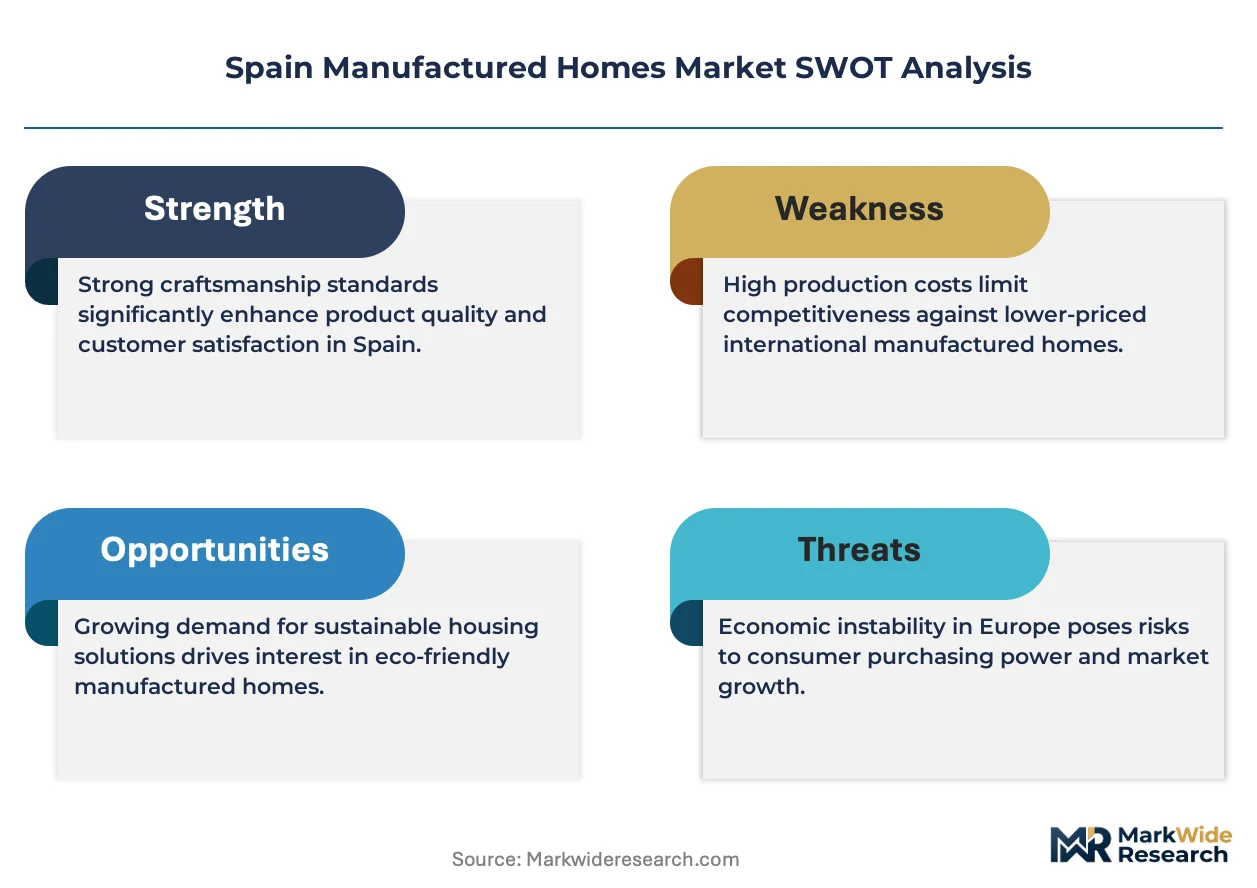
Spain's manufactured homes sector operates as a cost-of-compliance story where Technical Building Code enforcement creates barrier-to-entry moats favoring scaled producers with pre-certified envelope platforms.
For Market Incumbents: Anticipate margin pressure from steel-timber hybrid systems displacing conventional steel-frame alternatives in coastal luxury segments. Defensive consolidation should prioritize captive installation crew capacity in the Balearic Islands and Costa del Sol where seasonal construction windows compress project timelines. Certification investment in near-zero energy envelope systems anchors pricing power as EU Energy Performance of Buildings Directive mandates tighten. For New Entrants and Emerging Players: The mid-tier price-point gap between premium custom homes and economy single-section units offers white-space positioning for standardized modular units with CTE pre-certification. Andalusia's inland corridor around Seville shows lowest competitive density among family-oriented permanent installations. A direct-to-developer go-to-market angle bypasses fragmented traditional construction intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by European modular construction platforms seeking Mediterranean production footholds. Long-term viability favors fabricators with vertically integrated material control and repeat-order relationships with institutional tourism developers. The signal to watch is Balearic Islands zoning reform progress on permanent foundation permissions.| Strategic Initiative | Industry Significance |
|---|---|
| CTE Pre-Certification Investment | Accelerates municipal permitting in Andalusia and Valencian Community where review cycles compress. |
| Captive Installation Crew Development | Secures priority production slots from fabricators during narrow seasonal construction windows. |
| Cross-Laminated Timber Backward Integration | Locks biogenic material supply for coastal tourism investors commanding premium nightly rates. |
| Seismic Engineering Licensing | Extracts technology fees from fabricators serving Catalonia's stringent regional building codes. |
| Tourism Developer Direct Relationship | Disintermediates traditional construction channels consolidating procurement authority in coastal zones. |
Research Methodology
Document review covered Spanish Ministry of Transport and Housing regulatory filings, EU Energy Performance of Buildings Directive implementation guidance, and regional urban planning reforms in Catalonia and the Balearic Islands, complemented by interviews with manufactured homes fabricators, retirement community developers, coastal tourism investors, and municipal permitting officers. Secondary validation drew from CTE technical specifications, industry association production statistics, and customs data on steel and timber imports. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across the analysis window.
Historical capacity utilization and permit issuance patterns were cross-referenced against panel input from fabricators and institutional buyers to anchor growth trajectories. Segmentation dimensions modeled include product type, installation method, end-user category, and utility configuration. CAGRs were derived from slope analysis of normalized shipment data and validated against stakeholder capacity expansion plans. Near-zero energy specification compliance timelines and seismic certification testing bottlenecks served as industry-specific forecast inputs.
Inputs from regional permitting databases and fabricator production records were available through the study window; gaps in informal temporary installation tracking introduce uncertainty bands around tourism accommodation estimates. Deviation in Balearic Islands zoning reform timing or CTE enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Indonesia Residential Real Estate Market