
 United States Rental Rate for Residential Real Estate Market | 2026-2036
United States Rental Rate for Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Rental Rate for Residential Real Estate Market Insights
The Inflation Reduction Act is expanding capital deployment into energy-efficient residential retrofits across the United States rental housing stock. Equity Residential leverages its coastal urban portfolio to capture premium rents from transit-oriented developments. Invitation Homes anchors its strategy in single-family build-to-rent communities across suburban Sun Belt corridors. AvalonBay Communities dominates high-amenity multifamily construction in supply-constrained gateway metros.
The United States rental rate for residential real estate represents the periodic payment exchanged for temporary occupancy rights in dwelling units, typically structured as monthly lease obligations tied to square footage, location quality, and amenity packages. Pricing mechanisms incorporate operating expense pass-throughs, concession amortization, and market-comparable adjustments calibrated to neighborhood submarket velocity. Apartments command the deepest institutional liquidity pools due to standardized underwriting and scale economies in property management. Single-family rentals represent the fastest-expanding segment as institutional operators professionalize fragmented mom-and-pop ownership structures. Luxury tiers concentrate margin pools in gateway cities while affordable segments face structural supply deficits relative to qualifying household formation.
The Department of Housing and Urban Development shapes demand through Section 8 voucher administration and fair housing enforcement standards that affect landlord participation decisions. State-level rent control frameworks in California, New York, and Oregon constrain pricing flexibility and alter development feasibility calculations for new supply. Fannie Mae and Freddie Mac multifamily lending caps influence capital availability and underwriting terms across the income spectrum. Stakeholders must monitor evolving local inclusionary zoning mandates and their interaction with federal tax credit programs that finance below-market units.
Market Dynamics
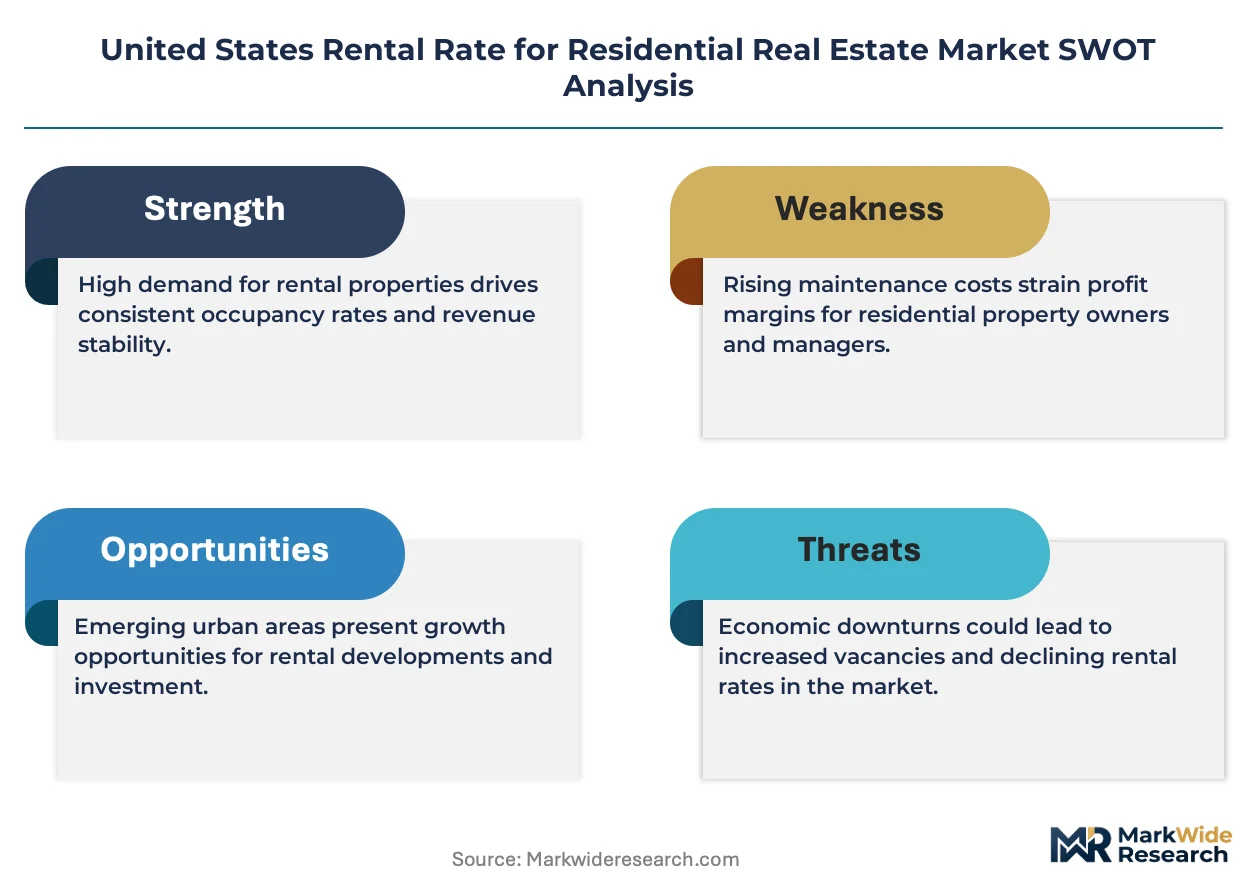
The Inflation Reduction Act is redirecting institutional capital toward energy-efficient retrofits across Class B and C multifamily assets, compressing operating expense spreads and reshaping underwriting assumptions for value-add strategies. Remote work permanence continues redistributing tenant demand toward Sun Belt metros, forcing coastal operators to defend occupancy through amenity densification.
Growth Catalysts
- Green building incentives:The IRA's tax credits for electrification and solar retrofits are accelerating capital deployment into aging housing stock. Operators capture utility savings while qualifying for favorable Fannie Mae and Freddie Mac green bond pricing.
- Single-family rental professionalization:Build-to-rent communities are consolidating fragmented suburban ownership. Institutional operators deploy centralized property management platforms across scattered-site portfolios.
- Population migration patterns:Texas, Florida, and Arizona submarkets absorb inbound households faster than construction pipelines can respond. Rent growth outpaces national averages in these corridors.
Market Restraints
- Construction cost volatility:Lumber, steel, and concrete input prices fluctuate with trade policy uncertainty. Development pro formas carry wider contingency reserves, compressing projected yields.
- Rent control frameworks:California, New York, and Oregon statutes constrain annual lease escalation. Investors demand higher going-in cap rates to compensate for pricing rigidity.
- Interest rate sensitivity:Floating-rate construction debt and fixed-rate permanent financing spreads have widened. Refinancing risk concentrates in 2025-2027 maturity windows.
Strategic Opportunities
- Adaptive reuse of obsolete office:Downtown conversion pipelines in Chicago, Cleveland, and St. Louis are unlocking supply in supply-constrained urban cores. Municipal zoning overlays expedite entitlement timelines.
- Workforce housing tax credits:Low-Income Housing Tax Credit allocations from state housing finance agencies are financing below-market units at higher leverage than conventional structures.
- Smart home technology convergence:IoT sensors and automated access control are reducing on-site staffing requirements. Operators bundle connectivity packages into base rent.
Industry Challenges
- Maintenance technician scarcity:HVAC and appliance repair skill gaps lengthen work-order resolution times. Third-party vendor contracts absorb margin compression.
- Utility pass-through reconciliation:RUBS allocation disputes and submetering installation costs generate tenant friction. Regulatory scrutiny of billing practices is intensifying.
- Insurance availability constraints:Climate-exposed Gulf Coast and wildfire-prone California markets face carrier withdrawals. Captive insurance structures require capital reserves that compete with acquisition capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Rental Rate for Residential Real Estate Market |
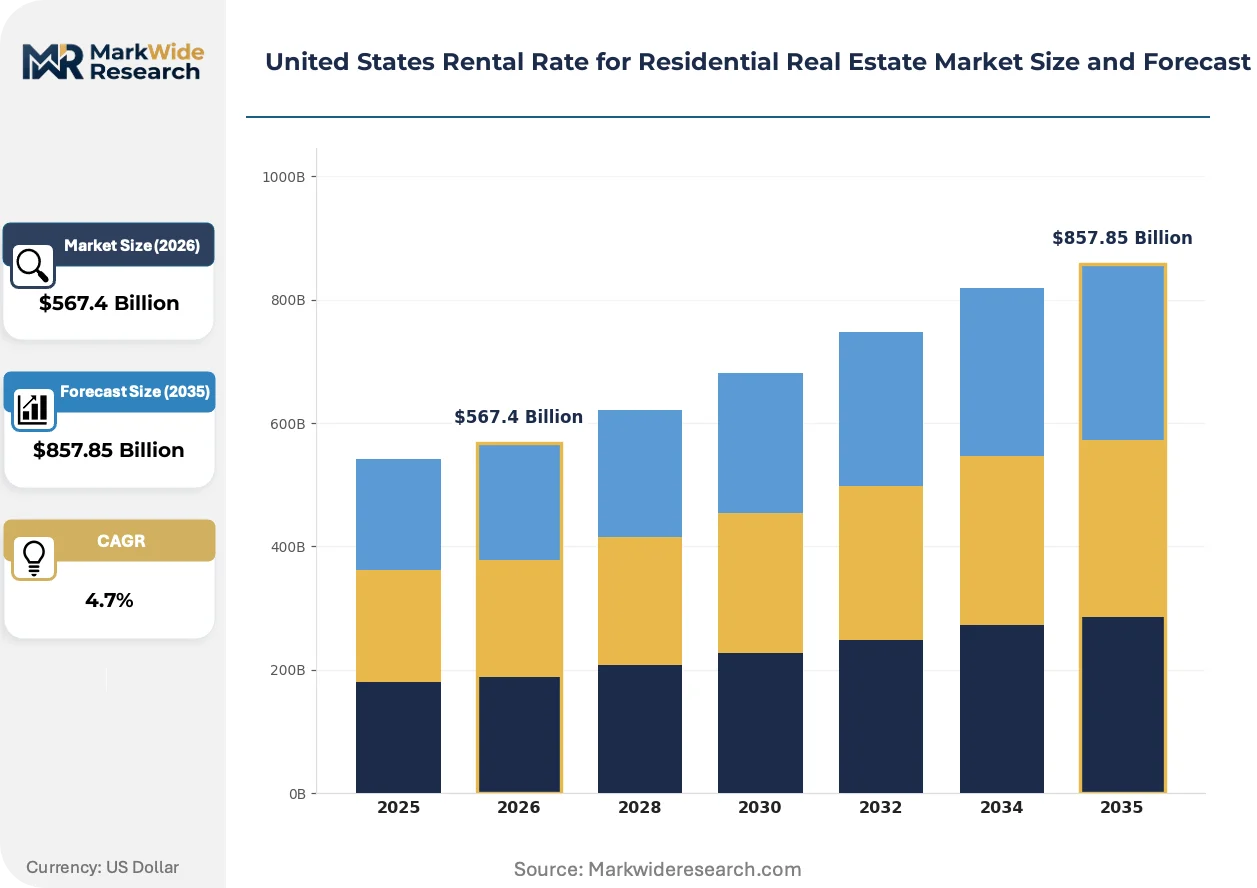
| Market Size in 2026 | $567.4 Billion |
| Market Size in 2035 | $857.85 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Apartments Rental Price Tier: Luxury, Mid-Range, Affordable, Budget Lease Duration: Short-Term, Long-Term, Month-to-Month, Seasonal Management Structure: Self-Managed, Property Management Firms, Real Estate Agents, Corporate Housing |
| Companies Covered | AvalonBay Communities, Equity Residential, Invitation Homes, American Homes 4 Rent, Essex Property Trust, Mid-America Apartment Communities, UDR, Camden Property Trust, Tricon Residential, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Rental Rate for Residential Real Estate Market Trends and Innovations
Property technology is compressing operating expense ratios while regulatory pressure on carbon intensity forces asset-level capital deployment decisions. Three converging shifts are restructuring competitive positioning across income tiers and geographies.
Integrated building automation platforms are unifying HVAC, lighting, and access control into single-pane-of-glass interfaces. Mid-market multifamily operators in Phoenix and Dallas are deploying these systems at 40% of new construction starts. The technology is compressing on-site staffing models from one employee per 100 units toward one per 150 units.
The Department of Housing and Urban Development is tightening fair housing algorithmic screening standards for tenant selection software. Third-party screening vendors must document disparate impact testing or risk liability exposure. Large institutional landlords in Atlanta and Denver are bringing screening logic in-house to maintain audit trails.
Tenant preferences are rotating toward lease flexibility and furnished short-term options. Corporate relocation channels and travel nurse housing are displacing traditional twelve-month structures in Austin and Nashville submarkets. Operators are unbundling furniture packages from base rent to capture ancillary revenue streams.
United States Rental Rate for Residential Real Estate Market Segmentation
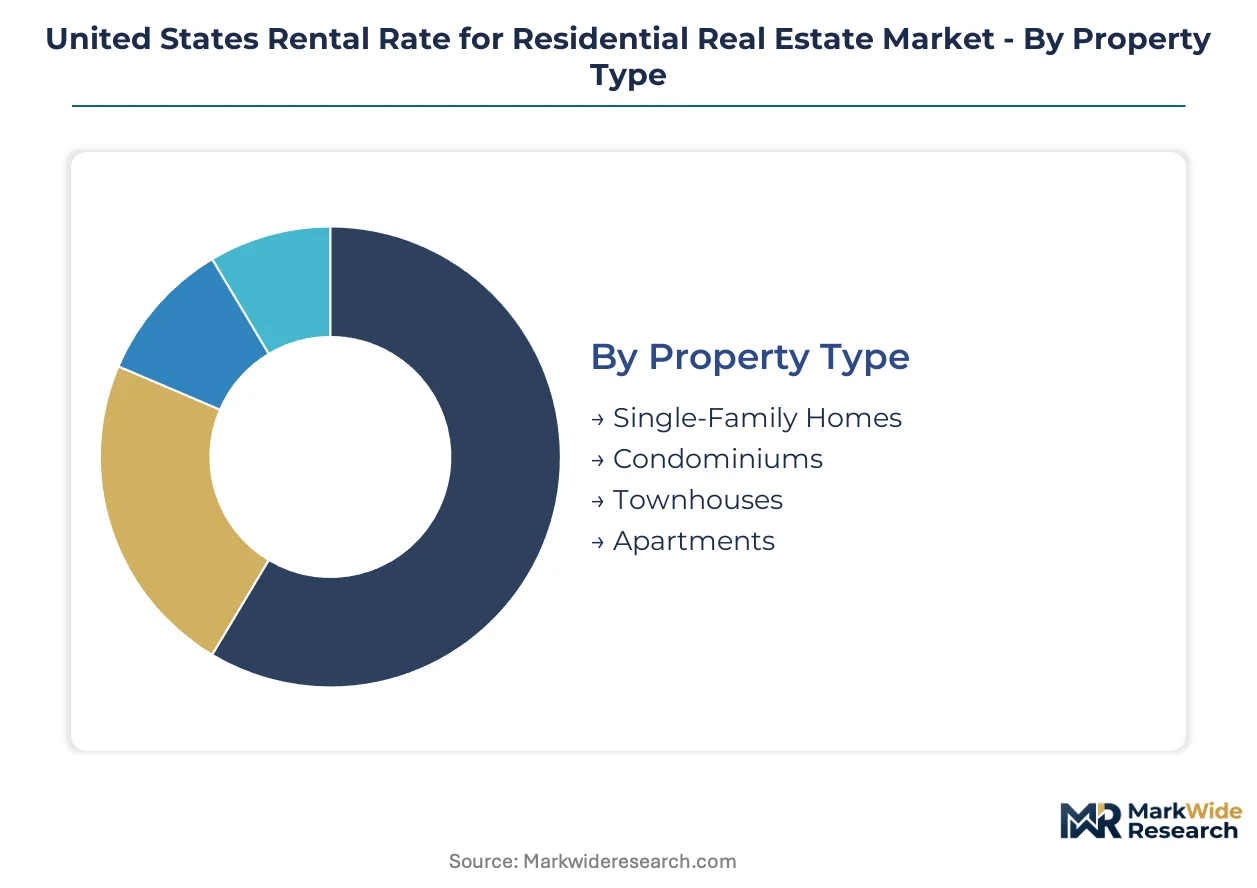
Segmentation in the United States rental rate for residential real estate market exposes how pricing mechanisms, lease structures, and operational models diverge across asset classes. Investors and operators calibrate underwriting assumptions, management platforms, and capital deployment strategies differently for each segment cluster.
Property Type:
HUD fair housing enforcement standards and local zoning ordinances impose distinct compliance burdens across physical dwelling configurations, shaping operator participation decisions and development feasibility.
- Single-Family Homes:Detached structures on individual parcels with dedicated utility infrastructure and yard maintenance obligations. Institutional build-to-rent operators in Phoenix and Dallas suburbs deploy centralized property management platforms across scattered-site portfolios to capture professionalization premiums.
- Apartments:Multifamily structures with shared mechanical systems and common amenity spaces, commanding the deepest institutional liquidity pools due to standardized underwriting and scale economies in property management. Coastal gateway metros concentrate Class A supply while Sun Belt markets absorb development pipeline expansion.
- Condominiums:Individually owned units subject to homeowners association governance and special assessment risks that complicate landlord cash flow forecasting. Miami and Los Angeles submarkets exhibit elevated investor concentration in rental-restricted condo regimes.
- Townhouses:Attached single-family configurations with fractional common element ownership and hybrid maintenance responsibilities. Suburban Atlanta and Charlotte corridors attract workforce housing demand seeking space-efficiency tradeoffs.
Leading the category by volume: Apartments. Growing fastest: Single-Family Homes.
Rental Price Tier:
Cost stratification determines capital stack composition, with luxury segments accessing institutional equity and affordable tiers relying on tax credit syndication.
- Luxury:Top-quartile rent positioning with high-amenity packages, concierge services, and premium finishes. Gateway city operators in Manhattan and San Francisco defend occupancy through amenity densification as remote work redistributes demand.
- Affordable:Rent-restricted units serving households below area median income, financed through Low-Income Housing Tax Credit allocations from state housing finance agencies. LIHTC structures enable higher leverage than conventional financing.
- Mid-Range:Market-rate product targeting median-income households without subsidy dependency or premium positioning. Austin and Nashville submarkets exhibit compressed rent growth in this tier as supply pipelines mature.
- Budget:Minimal-amenity product with functional obsolescence risk and elevated tenant turnover. Class C assets in legacy Rust Belt metros face capital needs assessments that challenge operating expense pass-through viability.
Leading the category by volume: Mid-Range. Expanding most quickly: Affordable.
Lease Duration:
Tenant mobility preferences and operator revenue stability tradeoffs segment the market into distinct cash flow predictability profiles.
- Long-Term:Twelve-month or greater lease obligations with fixed rent schedules and renewal optionality. Institutional multifamily operators prefer this structure for debt service coverage reliability.
- Short-Term:Furnished accommodations with flexible termination provisions, capturing corporate relocation channels and travel nurse housing demand in Austin and Nashville submarkets.
- Month-to-Month:At-will tenancy with thirty-day termination notice requirements, common in rent-controlled jurisdictions where annual escalation caps incentivize pricing flexibility.
- Seasonal:Term-certain leases aligned with academic calendars or tourism cycles, concentrated in Florida and Arizona snowbird markets with pronounced occupancy seasonality.
Leading the category by volume: Long-Term. Climbing the fastest: Short-Term.
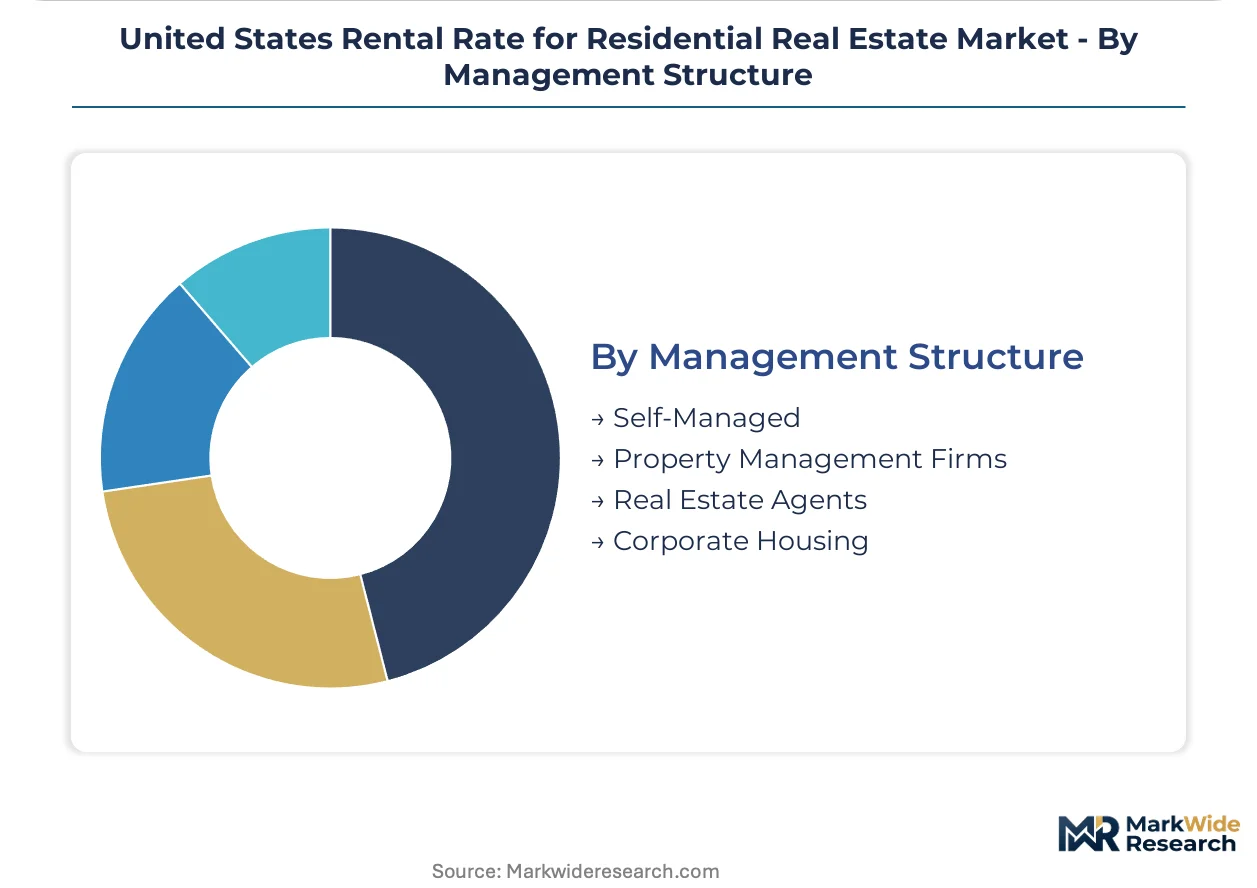
Management Structure:
Operational control configurations determine expense ratio profiles and tenant service level commitments across ownership models.
- Property Management Firms:Third-party operators executing leasing, maintenance, and accounting functions for fee-based compensation. Institutional single-family rental platforms deploy technology stacks that compress on-site staffing ratios.
- Self-Managed:Direct landlord oversight with minimal overhead, prevalent in fragmented mom-and-pop ownership structures that institutional operators consolidate. HVAC and appliance repair skill gaps lengthen work-order resolution times.
- Real Estate Agents:Transaction-focused intermediaries handling tenant placement without ongoing operational responsibility, common in high-turnover luxury submarkets.
- Corporate Housing:Full-service providers bundling furniture, utilities, and concierge support for executive relocation accounts. Chicago and Denver downtown cores concentrate this supply.
Leading the category by volume: Property Management Firms. Gaining share fastest: Self-Managed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity in residential rental housing concentrates in Sun Belt metros where population inflows outpace construction pipelines, while consumption demand redistributes away from coastal gateway cities toward suburban corridors in Texas, Florida, and Arizona.
Texas
Dallas-Fort Worth and Houston absorb inbound households faster than developers can deliver supply. The Texas Department of Housing and Community Affairs administers Low-Income Housing Tax Credit allocations that finance workforce units at higher leverage. Austin's build-to-rent pipeline expands fastest as institutional operators consolidate suburban single-family parcels.
Florida
Miami and Tampa submarkets exhibit pronounced seasonality as snowbird demand converges with permanent relocation. The Florida Housing Finance Corporation channels state tax credits toward affordable preservation deals. Orlando's institutional single-family rental concentration deepens as Invitation Homes and Tricon Residential scale scattered-site portfolios.
Arizona
Phoenix rent growth outpaces national averages as California out-migration accelerates household formation. The Arizona Department of Housing coordinates federal HOME funds with state residual receipts programs. Tucson's Class B multifamily retrofit activity concentrates IRA green building incentives into aging 1980s garden-style assets.
California
Los Angeles and San Francisco operators defend occupancy through amenity densification as remote work drains tenant demand. State rent control statutes constrain annual lease escalation and alter development feasibility calculations. San Diego's adaptive reuse pipeline converts obsolete downtown office into residential units under municipal zoning overlays.
Georgia
Atlanta's suburban sprawl accommodates build-to-rent community expansion across exurban Cherokee and Forsyth counties. The Georgia Department of Community Affairs allocates federal tax credits through qualified allocation plans. Midtown's high-amenity multifamily construction targets corporate relocation channels with furnished short-term lease structures.
United States Rental Rate for Residential Real Estate Market Competitive Landscape
The competitive structure tilts toward institutional multifamily REITs with scale advantages in capital formation and property management technology deployment. Publicly traded apartment operators command premium valuations through portfolio diversification across gateway and Sun Belt metros. Three archetypes dominate: coastal urban specialists, Sun Belt diversifiers, and single-family rental consolidators. Dominant competitive moves include portfolio recycling through suburban asset acquisitions and technology platform licensing to third-party managers.
Among coastal urban specialists, AvalonBay Communities and Essex Property Trust exemplify high-amenity construction in supply-constrained gateway metros. Equity Residential anchors the transit-oriented development vector with concentrated exposure to rail-served submarkets. Invitation Homes and American Homes 4 Rent occupy positions within the single-family rental consolidation tier, deploying centralized property management platforms across scattered-site suburban portfolios. Tricon Residential represents the cross-border institutional model with Canadian capital backing U.S. Sun Belt expansion.
| Leading Market Players |
|---|
| AvalonBay Communities |
| Equity Residential |
| Invitation Homes |
| American Homes 4 Rent |
| Essex Property Trust |
| Mid-America Apartment Communities |
| UDR |
| Camden Property Trust |
| Tricon Residential |
| Others |
Pricing and Supply Chain Analysis
Lumber futures and concrete price indices cascade through development pro formas into lease rate stratification across Class A, B, and C multifamily assets. Input cost volatility compresses projected yields on new construction while retrofit economics improve under IRA green building incentives.
Pricing Analysis
Location-based pricing anchors rent schedules to transit accessibility scores, school district ratings, and employment density metrics rather than pure construction cost recovery. Three-tier pricing structure across luxury, workforce, and affordable levels reflects amenity density, unit finish grade, and operating expense pass-through mechanisms. Pricing pressure stems from interest rate sensitivity on floating-rate construction debt and refinancing risk in near-term maturity windows. Workforce housing segments exhibit highest price sensitivity as qualifying household income growth lags rent escalation, while luxury tiers absorb premium positioning through corporate relocation channels.
Supply Chain Analysis
HUD fair housing certification and local zoning compliance gate material supplier and contractor qualification for federally financed projects. Construction inputs draw from Mexico, Canada, and domestic manufacturing bases for lumber, steel, and HVAC equipment. Supply chain risk concentrates in tariff exposure on Canadian softwood lumber and Chinese steel imports. Distribution runs through regional building material distributors serving metropolitan construction corridors, with just-in-time delivery models vulnerable to logistics chokepoints at port and rail terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where construction pipeline velocity caps out below household formation rates in Texas, Florida, and Arizona corridors. Development entitlement timelines and skilled labor scarcity prop pricing power for existing stabilized assets.
For Market Incumbents: Cement portfolio positioning through accelerated Class B and C retrofit deployment under IRA green building incentives before tax credit sunset provisions. Consolidate suburban Sun Belt scattered-site portfolios to capture professionalization premiums as Invitation Homes and Tricon Residential have demonstrated. Channel control through direct contractor relationships mitigates construction cost volatility and secures capacity in supply-constrained markets.
For New Entrants and Emerging Players: Integrated building automation platforms offer technology-first wedge into mid-market multifamily operations where legacy operators lag IoT sensor deployment and automated access control adoption. Target adaptive reuse of obsolete office in downtown Chicago, Cleveland, and St. Louis where municipal zoning overlays expedite entitlement timelines. Go-to-market angle centers on turnkey conversion partnerships with municipal economic development authorities seeking housing supply without greenfield land costs.
For Investors and Strategic Acquirers: The window for entry favors build-to-rent single-family specialists with scalable property management technology stacks and concentrated Sun Belt geographic exposure. Long-term viability hinges on operational platform licensing revenue streams and third-party management fee generation beyond owned-asset cash flows. Watch Fannie Mae and Freddie Mac multifamily lending cap adjustments as the signal for institutional capital availability inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Retrofit Acceleration | IRA tax credits compress operating expense spreads while qualifying assets for favorable GSE green bond pricing. |
| Build-to-Rent Community Expansion | Institutional operators consolidate fragmented suburban ownership through centralized property management platforms. |
| Adaptive Reuse Pipeline Development | Municipal zoning overlays in legacy downtown cores unlock supply without greenfield land competition. |
| Smart Home Technology Convergence | IoT sensor deployment reduces on-site staffing ratios from one per 100 units toward one per 150 units. |
| Workforce Housing Tax Credit Syndication | LIHTC allocations from state housing finance agencies enable higher leverage than conventional financing structures. |
Research Methodology
Independent corroboration across property management executives, multifamily REIT portfolio managers, state housing finance agency directors, and construction lending officers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from HUD program data, Fannie Mae and Freddie Mac disclosure filings, state qualified allocation plans, and municipal zoning ordinance databases anchored segment-level demand assessments. Bottom-up lease rate surveys across metropolitan statistical areas triangulate against top-down institutional investment flow analysis.
Comparable-period anchoring to historical rent growth velocity, occupancy rate trajectories, and construction permit issuance patterns established the forecast baseline. The analytical framework models property type, rental price tier, lease duration, and management structure dimensions across the projection horizon. CAGRs derive from regression analysis against population migration flows, employment growth differentials, and housing starts permit data. Forecast inputs incorporate remote work permanence assumptions and IRA incentive program utilization rates.
Several conditions sit outside the modeled scope, including abrupt interest rate regime shifts, federal tax credit program modifications, and natural catastrophe frequency changes affecting insurance availability. Forecasts reflect documented assumptions about household formation rates and construction cost input trajectories. A model refresh is warranted upon material change in GSE lending cap policy or state-level rent control framework expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
Malaysia Residential Real Estate Market