
 Mexico Residential Real Estate Market | 2026-2036
Mexico Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Residential Real Estate Market Insights
Market Context
Skilled construction labor availability is reorganizing development timelines across central Mexico, compressing project delivery windows for active builders. Ruba Residencial leverages its vertically integrated model to control costs amid wage pressures in the skilled trades. Vinte Viviendas Integrals sustains volume through standardized designs that reduce on-site labor intensity. Grupo Jomer anchors its position in Monterrey through direct employment of specialized masonry crews rather than subcontractor reliance.
Technical Definition and Segment Structure
Mexico residential real estate encompasses privately owned dwelling units ranging from single-family detached structures to multi-story condominium buildings, typically constructed with reinforced concrete frames, clay brick infill, and ceramic tile roofing adapted to seismic codes and tropical climate zones. The primary purpose is to provide shelter, wealth accumulation, and rental income streams within a market where homeownership rates exceed sixty percent nationally. Single-family homes dominate transaction volume in secondary cities, though condominiums capture disproportionate margin pools in Mexico City and Guadalajara where land scarcity elevates per-unit pricing. The affordable tier absorbs the largest buyer volume through INFONAVIT-subsidized financing, while luxury segments concentrate in Polanco, Santa Fe, and Valle Poniente where international buyers and domestic executives sustain premium absorption.
Regulatory Framework and Outlook
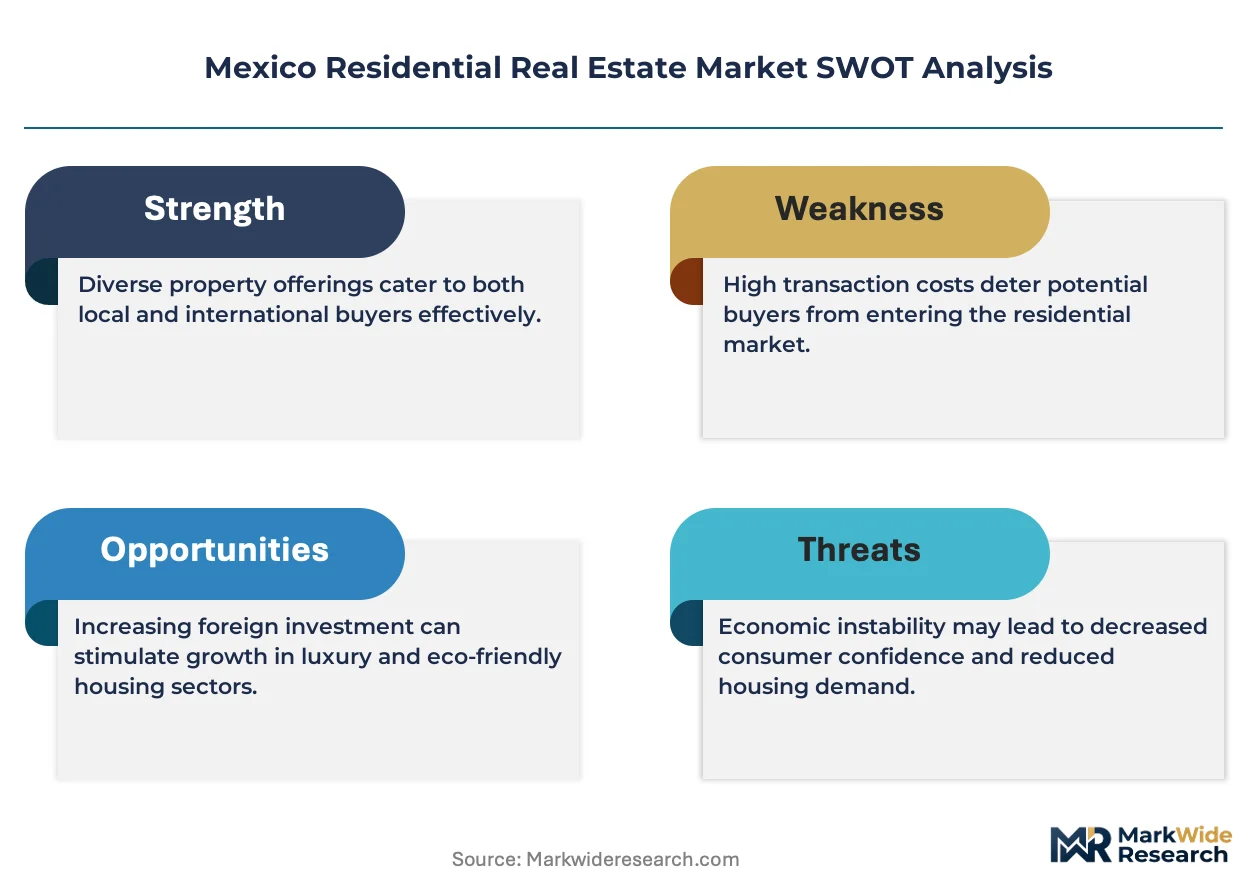
INFONAVIT, SHCP, and local municipal zoning authorities collectively shape market access through credit allocation, fiscal incentives, and land-use permissions that determine buildable density. Mexico's federal mortgage guarantee programs and state-level environmental impact assessments for large developments filter project feasibility and buyer qualification thresholds. Stakeholders must monitor whether proposed constitutional reforms to restrict foreign ownership near coastlines and borders reshape investment flows into permitted interior markets.
Market Dynamics
INFONAVIT credit system reforms are expanding mortgage access to informal workers, fundamentally reshaping buyer qualification pools and developer project targeting across Mexico's affordable housing segment.
Growth Catalysts
- INFONAVIT Subsidy Expansion:Federal mortgage guarantee programs now extend credit to workers without formal payroll documentation, unlocking demand from Mexico's substantial informal economy workforce.
- Bajío Manufacturing Corridors:Industrial job creation in Guanajuato and Querétaro sustains household formation rates and housing absorption velocity in secondary markets.
- Remote Work Normalization:Young professional households in Mexico City and Guadalajara are driving condominium demand as location flexibility reduces commute constraints.
Market Restraints
- Skilled Masonry Labor Scarcity:Specialized construction trades face acute shortages in central Mexico, compressing project delivery timelines and elevating wage costs for active developers.
- Municipal Zoning Fragmentation:Local land-use permissions vary dramatically across 32 state jurisdictions, creating regulatory friction that filters project feasibility and buildable density calculations.
- Coastal Foreign Ownership Restrictions:Proposed constitutional reforms to limit foreign property rights near borders and coastlines threaten investment flows into traditional vacation home markets.
Strategic Opportunities
- Guadalajara Metro Expansion:Light rail extensions into peripheral municipalities create transit-oriented development zones with underpriced land relative to Mexico City comparable corridors.
- Green Building Certification Incentives:State-level environmental impact assessment streamlining for LEED-equivalent projects offers regulatory tailwinds for sustainable construction differentiation.
- Digital Mortgage Origination:Fintech platforms are converging with traditional INFONAVIT channels to reduce documentation friction and accelerate closing timelines for qualified buyers.
Industry Challenges
- Seismic Engineering Certification Bottlenecks:Qualified structural review capacity lags project submission volumes in high-growth zones, extending pre-construction approval timelines.
- Reinforced Concrete Supply Volatility:Cement and rebar input cost swings force developers to absorb margin compression or delay project launches during price spikes.
Report Scope
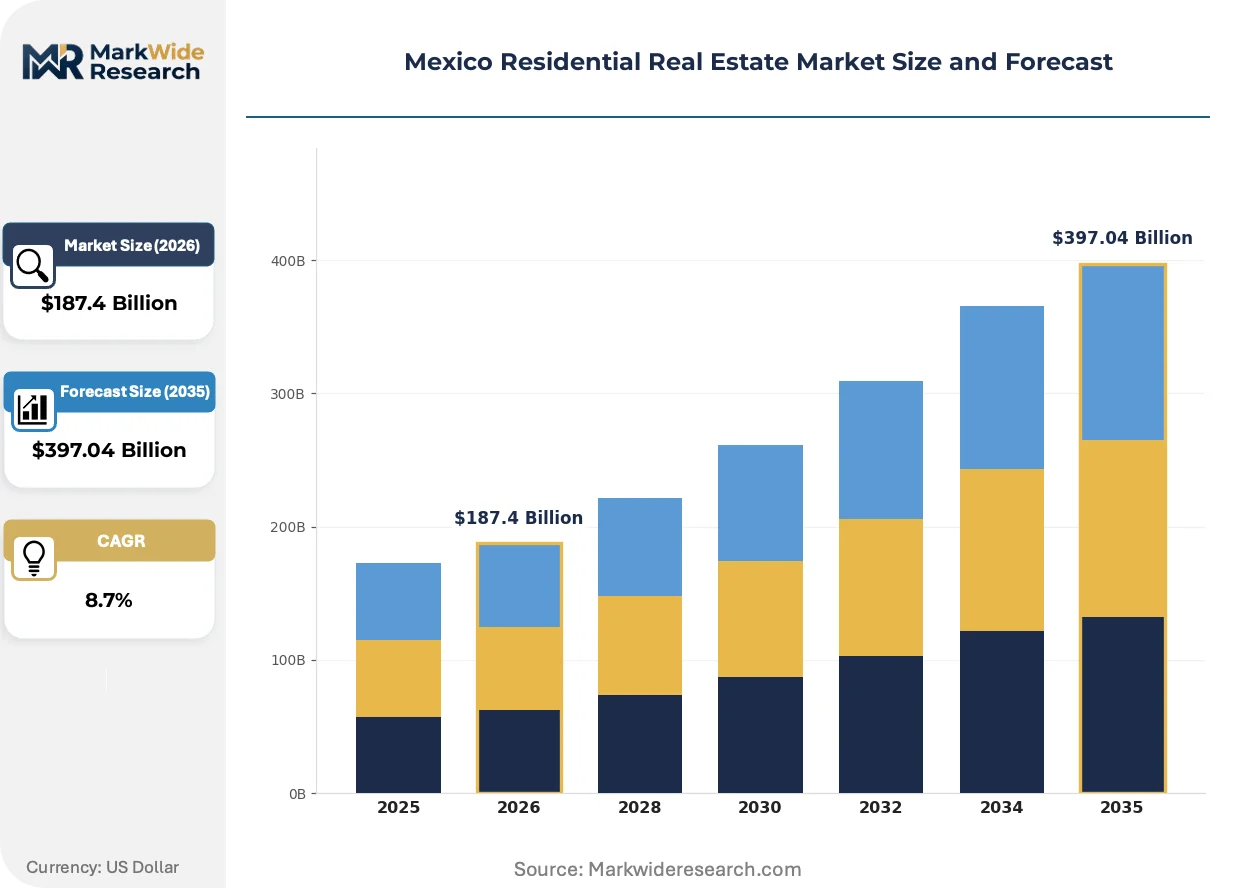
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Residential Real Estate Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Multi-Family Units Price Tier: Luxury, Mid-Range, Affordable, Economy Buyer Type: First-Time Buyers, Investors, Retirees, Families Purchase Method: Cash Purchase, Mortgage Financing, Rent-to-Own, Lease |
| Companies Covered | Ruba Residencial, ARA Consortium, Grupo Jomer, Grupo GP, Grupo Lar, Vinte Viviendas Integrales, Grupo SADASI, Grupo HIR, Inmobilia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Residential Real Estate Market Trends and Innovations
Digital tools and policy recalibration are compressing transaction friction and reshaping how Mexican households access, finance, and occupy residential property across price tiers.
Modular construction systems utilizing prefabricated concrete panels are fragmenting traditional on-site masonry workflows. Mid-market developers in Nuevo León and Jalisco are adopting these methods to reduce labor intensity and compress foundation-to-delivery cycles. The technology is fragmenting competitive positioning between vertically integrated builders with captive manufacturing capabilities and conventional subcontractors dependent on scarce skilled trades.
SHCP fiscal incentives for affordable housing developers are tightening environmental compliance thresholds while expanding subsidy pools for qualifying projects. The industrial consequence is a bifurcation between developers with in-house sustainability expertise and those facing delayed approvals. The affordable tier absorbs the largest policy impact as INFONAVIT-linked projects must now meet enhanced energy efficiency standards to access full guarantee backing.
Buyer preference is rotating toward smaller unit footprints with premium amenity packages as household size compresses and remote work elevates home-office functionality requirements. This pattern displaces traditional three-bedroom layouts in favor of flexible two-bedroom configurations with dedicated workspace zones. The shift is most visible in Mexico City condominiums where land scarcity forces density optimization and buyers prioritize location over square footage.
Mexico Residential Real Estate Market Segmentation
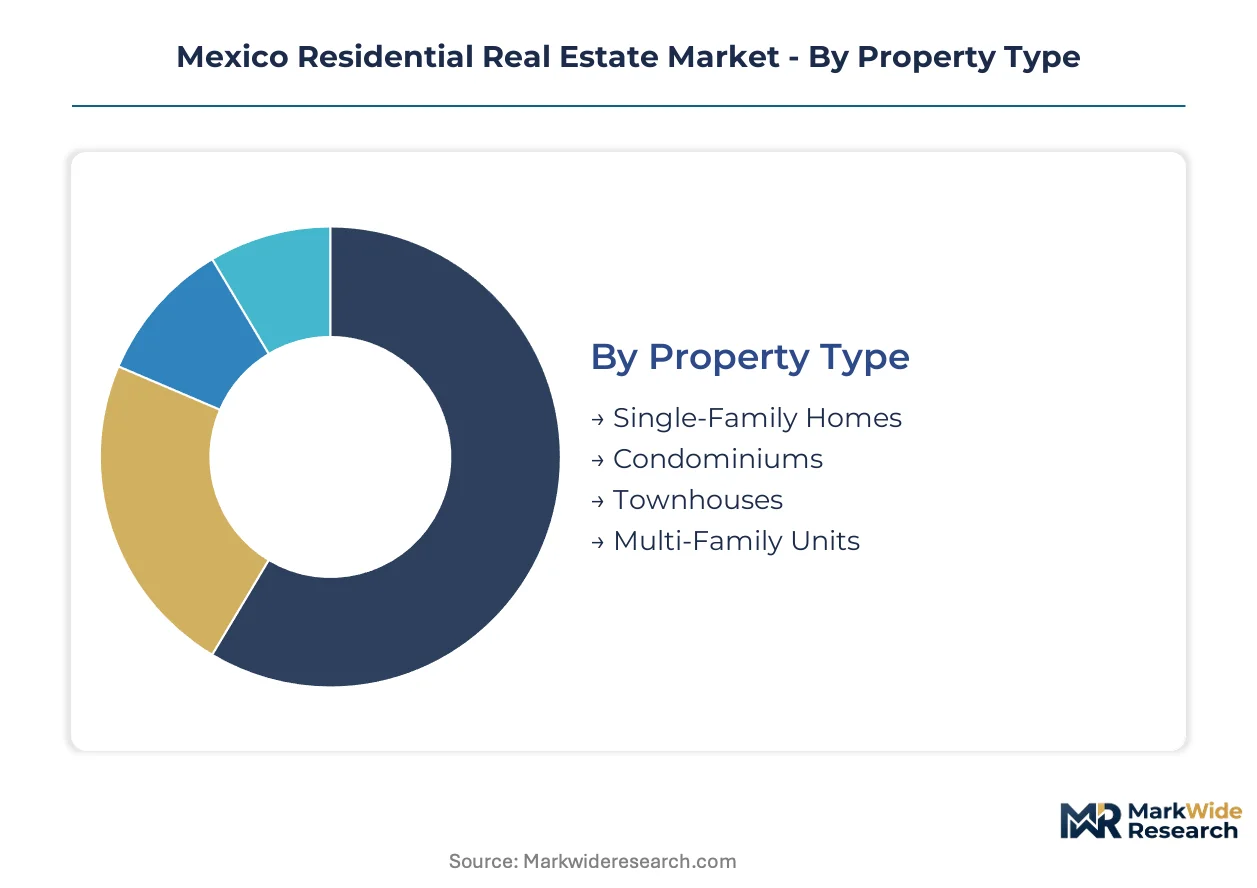
Segmentation in Mexico's residential market reveals how INFONAVIT credit flows, construction labor constraints, and municipal zoning fragmentation create divergent opportunity surfaces across property configurations and buyer profiles. Developers must align product specifications with financing channel accessibility and regional absorption velocity.
Property Type:
Single-family homes flow primarily through INFONAVIT-subsidized channels in secondary cities, while condominiums dominate cash-and-mortgage transactions in Mexico City and Guadalajara where land scarcity elevates density requirements.
- Single-Family Homes:Detached structures on individual lots, typically constructed with reinforced concrete frames and clay brick infill adapted to seismic codes. Demand concentrates in Bajío industrial corridor cities including León and Querétaro where manufacturing job growth sustains household formation for INFONAVIT-qualifying buyers.
- Condominiums:Multi-story vertical dwellings with shared structural systems and common amenity spaces, requiring specialized masonry crews for core-and-shell construction. Absorption is strongest in Mexico City peripheral zones and Guadalajara metro expansion corridors where young professional households prioritize location flexibility over square footage.
- Townhouses:Attached single-family units sharing party walls with individual ground-floor access, occupying intermediate density zones between detached homes and mid-rise condominiums.
- Multi-Family Units:Small-scale rental-oriented buildings of two to four units, typically developed by individual investors rather than institutional builders and concentrated in university-adjacent neighborhoods.
By volume, Single-Family Homes leads. By growth pace, Condominiums is expanding most quickly.
Price Tier:
Cost tier stratification determines which regulatory frameworks and financing channels govern project feasibility, with federal subsidy thresholds creating sharp discontinuities in buyer qualification pools.
- Affordable:Units priced within INFONAVIT maximum loan ceilings, constructed with standardized designs that reduce on-site labor intensity and qualify for SHCP fiscal incentives. This tier absorbs the largest transaction volume through federal mortgage guarantee programs now extending to informal workers.
- Luxury:Premium residences in Polanco, Santa Fe, and Valle Poniente featuring enhanced seismic engineering and imported finishes, purchased through cash transactions or private banking channels by domestic executives and international buyers.
- Mid-Range:Market-rate products for formally employed households exceeding INFONAVIT income caps but seeking mortgage financing through commercial banks.
- Economy:Entry-level units at minimum code compliance, typically developed by small regional builders with limited vertical integration and concentrated in peripheral municipalities with lower land costs.
Affordable captures the greatest buyer volume. Luxury delivers the highest per-unit margins.
Buyer Type:
Customer profile determines financing documentation requirements, decision timeline compression, and sensitivity to interest rate movements across Mexico's bifurcated credit system.
- First-Time Buyers:Households accessing INFONAVIT credit for initial homeownership, now including workers without formal payroll documentation under recent system reforms. This segment drives absorption in Guanajuato and Querétaro manufacturing zones.
- Investors:Cash purchasers acquiring rental income properties or appreciation plays, concentrated in Mexico City condominium markets and coastal vacation home zones threatened by proposed foreign ownership restrictions.
- Retirees:Downsizing households liquidating prior residences for debt-free purchases, favoring single-level townhouses in central Mexico climate zones.
- Families:Multi-generational households requiring three-bedroom configurations, increasingly displaced by smaller unit footprints as developers optimize for remote-work-compatible layouts.
First-Time Buyers dominates transaction count. Investors show the steepest expansion trajectory in premium zones.
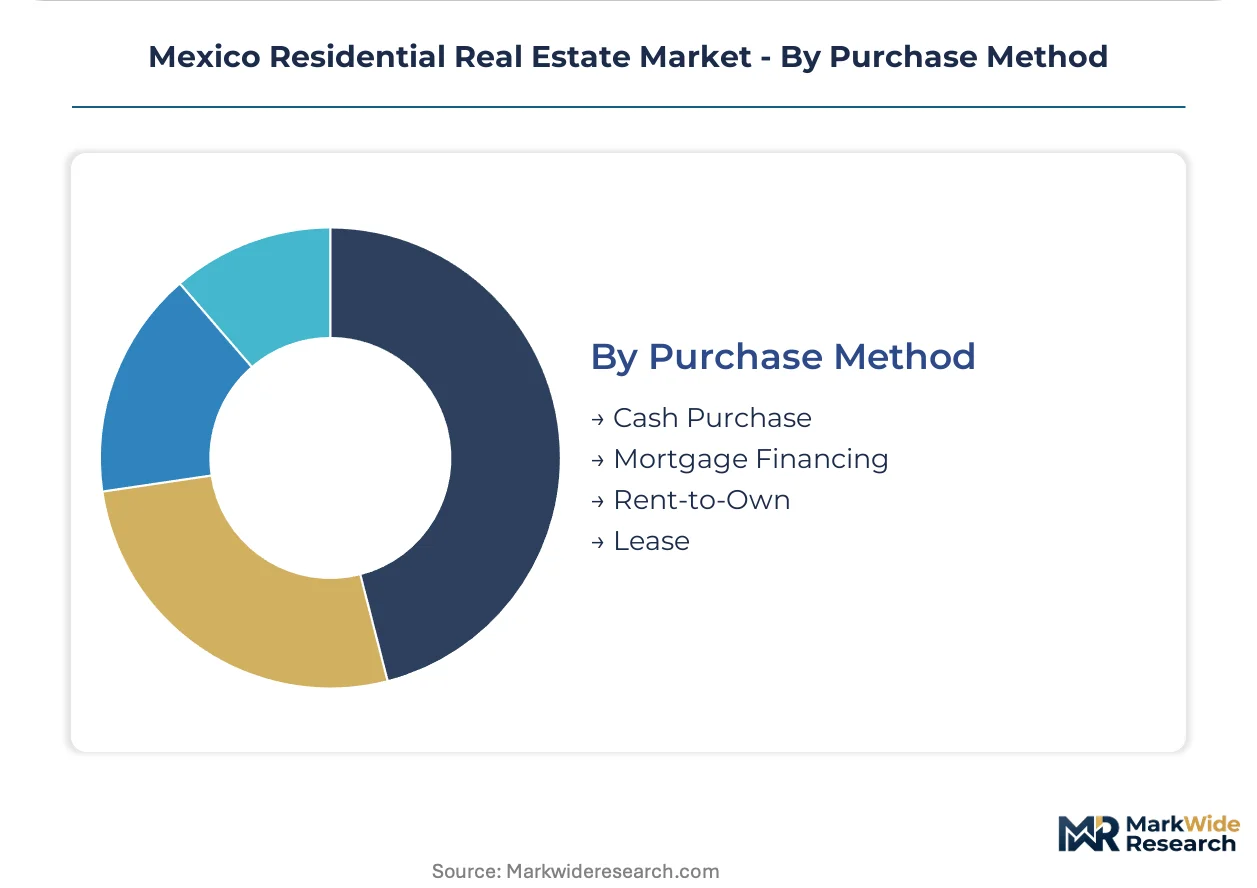
Purchase Method:
Transaction structure shapes developer cash flow timing, construction financing requirements, and exposure to monetary policy transmission through Banxico rate adjustments.
- Mortgage Financing:INFONAVIT-subsidized and commercial bank channels requiring formal income documentation, now expanding through fintech platform convergence to reduce closing friction.
- Cash Purchase:Full upfront payment eliminating credit approval risk, prevalent in luxury segments and investor acquisitions where title transfer velocity matters.
- Rent-to-Own:Structured lease arrangements with purchase optionality, filling gaps for households building credit history or awaiting formal employment documentation.
- Lease:Pure rental contracts without ownership conversion, sustaining demand in Guadalajara and Monterrey metro zones where mobility preferences delay purchase commitment.
Mortgage Financing channels the greatest unit volume. Cash Purchase is gaining share fastest in coastal luxury markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's residential market fragments sharply between formal mortgage-financed corridors and cash-dominant zones, with the Bajío and northern border states absorbing INFONAVIT-subsidized volume while coastal markets serve discretionary purchasers.
Mexico City Metro
Condominium absorption concentrates in peripheral municipalities along the Tren Interurbano expansion corridor, where young professional households trade square footage for transit accessibility. INFONAVIT credit penetration remains lower here than in industrial zones, with commercial bank mortgages and cash purchases dominating transaction structures. Santa Fe and Polanco sub-markets sustain luxury absorption through domestic executive demand and limited new supply.
Nuevo León
Monterrey anchors northern Mexico's most active single-family construction pipeline, with Grupo Jomer and regional specialists competing for formally employed households in García and Apodaca peripheral zones. State-level environmental impact assessments filter project approvals, compressing buildable density in the Santa Catarina watershed. Direct employment of masonry crews rather than subcontractor networks distinguishes competitive positioning among active builders.
Jalisco
Guadalajara's light rail extensions into Zapopan and Tlajomulco create transit-oriented development zones with land pricing advantages relative to Mexico City comparable corridors. Remote work normalization elevates demand for smaller unit footprints with dedicated workspace configurations. Municipal zoning fragmentation across the metropolitan area generates regulatory friction that extends pre-construction timelines.
Bajío Region
Guanajuato and Querétaro manufacturing corridors sustain the highest household formation velocity nationally, with automotive and aerospace job creation driving INFONAVIT-qualifying buyer pools. León and Querétaro city markets absorb standardized affordable housing designs that reduce on-site labor intensity. Federal mortgage guarantee program reforms extending credit to informal workers are expanding addressable demand in Silao and Irapuato satellite municipalities.
Northern Border States
Tijuana, Ciudad Juárez, and Matamoros markets bifurcate between maquiladora workforce housing and cross-border investment properties threatened by proposed constitutional restrictions on foreign ownership near frontiers. Cash transactions dominate the investor segment, while INFONAVIT channels serve formal manufacturing employees. Cement and rebar input cost volatility forces developers to absorb margin compression or delay launches during price spikes.
Mexico Residential Real Estate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Mexico's residential construction market, with vertical integration into captive manufacturing and direct labor employment distinguishing the upper tier from subcontractor-dependent regional builders. The competitive landscape compresses into three archetypes: vertically integrated national developers controlling cost structures through standardized designs and in-house production capabilities; regional specialists anchoring specific metropolitan markets through local land banking relationships; and affordable-tier volume builders optimizing for INFONAVIT qualification thresholds. Dominant competitive moves include geographic expansion into Bajío manufacturing corridors and portfolio diversification toward rental-oriented multi-family products.
Within the integrated developer tier, Ruba Residencial and Vinte Viviendas Integrales exemplify cost-control strategies through standardized construction systems and reduced on-site labor intensity. Grupo Jomer occupies a position among Monterrey-based builders distinguished by direct employment of specialized masonry crews. These three entities represent contrasting approaches to skilled labor scarcity: captive manufacturing, design standardization, and workforce direct employment respectively.
| Leading Market Players |
|---|
| Ruba Residencial |
| ARA Consortium |
| Grupo Jomer |
| Grupo GP |
| Grupo Lar |
| Vinte Viviendas Integrales |
| Grupo SADASI |
| Grupo HIR |
| Inmobilia |
| Others |
Pricing and Supply Chain Analysis
Scale economies in cement and rebar procurement anchor cost structures for Mexico's largest developers, compressing price floors for mid-market competitors while elevating barriers for regional specialists dependent on spot-market material sourcing. This concentration dynamic feeds directly into pricing power stratification across INFONAVIT-subsidized, commercial mortgage, and cash-purchase channels.
Pricing Analysis
Long-term offtake contracts with Cemex and Grupo Cementos de Chihuahua dominate cement procurement for volume builders, insulating Ruba Residencial and Vinte Viviendas Integrales from spot-price volatility that squeezes smaller competitors. Price differentiation hinges on vertical integration depth and SHCP green certification status, with LEED-equivalent projects commanding regulatory fast-tracking that offsets construction cost premiums. Pricing pressure stems from skilled masonry labor scarcity in Guanajuato and Querétaro, where wage escalation compresses margins for standardized affordable housing. First-time INFONAVIT buyers exhibit acute price sensitivity, while luxury cash purchasers in Polanco and Santa Fe absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Mexico and the United States anchor reinforced concrete supply, with domestic rebar fabrication concentrated in Monterrey and Puebla while specialty seismic-grade steel draws from U.S. Gulf Coast mills. Clay brick infill and ceramic roofing tiles source from regional kilns in Jalisco and Nuevo León, creating localized dependencies that fracture national procurement strategies. Supply chain risk centers on cement input cost volatility tied to energy pricing and freight logistics across the Bajío industrial corridor. Distribution runs through developer-direct bulk purchasing for large projects, with smaller builders channeling through regional construction supply cooperatives that extend payment terms but elevate unit costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
INFONAVIT credit system reforms are disrupting Mexico's residential real estate market by expanding mortgage access to informal workers, creating a high-growth inflection that reshapes developer targeting and competitive positioning across the affordable tier.
For Market Incumbents: Shield market share in Guanajuato and Querétaro manufacturing corridors by accelerating direct employment of specialized masonry crews before labor scarcity intensifies. Prioritize backward integration into prefabricated concrete panel manufacturing to reduce on-site labor intensity and compress delivery timelines. Certification investment in SHCP environmental compliance thresholds will differentiate project pipelines as regulatory friction tightens for non-compliant competitors. For New Entrants and Emerging Players: Anchor in Guadalajara's light rail expansion corridors where transit-oriented development zones offer land pricing advantages relative to Mexico City comparable markets. Target the mid-range condominium segment for young professional households prioritizing location flexibility over square footage, as remote work normalization sustains demand for smaller unit footprints with dedicated workspace configurations. Digital mortgage origination partnerships with fintech platforms reduce documentation friction and accelerate closing velocity against traditional INFONAVIT channel incumbents. For Investors and Strategic Acquirers: Regional specialists with captive land banking in Jalisco and Nuevo León represent acquisition targets positioned for Guadalajara metro expansion absorption. Long-term viability hinges on exposure to formal employment growth corridors rather than discretionary coastal vacation markets threatened by proposed constitutional foreign ownership restrictions. Monitor INFONAVIT informal worker credit penetration rates as the critical signal for demand expansion velocity in secondary manufacturing cities.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Panel Manufacturing Scale-Up | Captive production of concrete panels reduces labor intensity and compresses foundation-to-delivery cycles for active builders. |
| Direct Masonry Crew Employment | Specialized construction workforce control insulates project timelines from subcontractor scarcity in central Mexico growth zones. |
| Green Certification Investment | SHCP environmental compliance streamlining accelerates approvals for LEED-equivalent projects in affordable housing segments. |
| Transit-Oriented Development Positioning | Land banking along Guadalajara light rail extensions captures underpriced corridors relative to Mexico City comparable zones. |
| Digital Mortgage Platform Integration | Fintech convergence with INFONAVIT channels reduces documentation friction and accelerates closing timelines for qualified buyers. |
Research Methodology
Desk research of INFONAVIT credit disbursement records, SHCP fiscal incentive filings, and municipal zoning registries preceded structured interviews with development project directors, construction supply procurement managers, mortgage origination officers, and municipal planning officials across Mexico City, Guadalajara, Monterrey, and Bajío corridor cities. Secondary validation drew from cement industry trade data, housing finance system reports, and seismic engineering certification body records. Bottom-up project pipeline enumeration triangulated against top-down mortgage origination volume trends to anchor market sizing.
Variance decomposition across property type, price tier, buyer profile, and purchase method segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from regression against manufacturing employment growth, household formation velocity, and credit system penetration assumptions. Forecast inputs incorporated construction labor availability indices and cement price volatility bands specific to Mexico's residential construction sector.
Decision-makers should treat outputs as directional under sustained INFONAVIT reform implementation and manufacturing corridor job creation assumptions; material deviation in constitutional foreign ownership restrictions or seismic certification bottlenecks would warrant model refresh. Recalibration cycles align with material shifts in federal mortgage guarantee program scope and municipal zoning harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
United States Residential Real Estate Market