
 Qatar Residential Real Estate Market | 2026-2036
Qatar Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Residential Real Estate Market Analytics
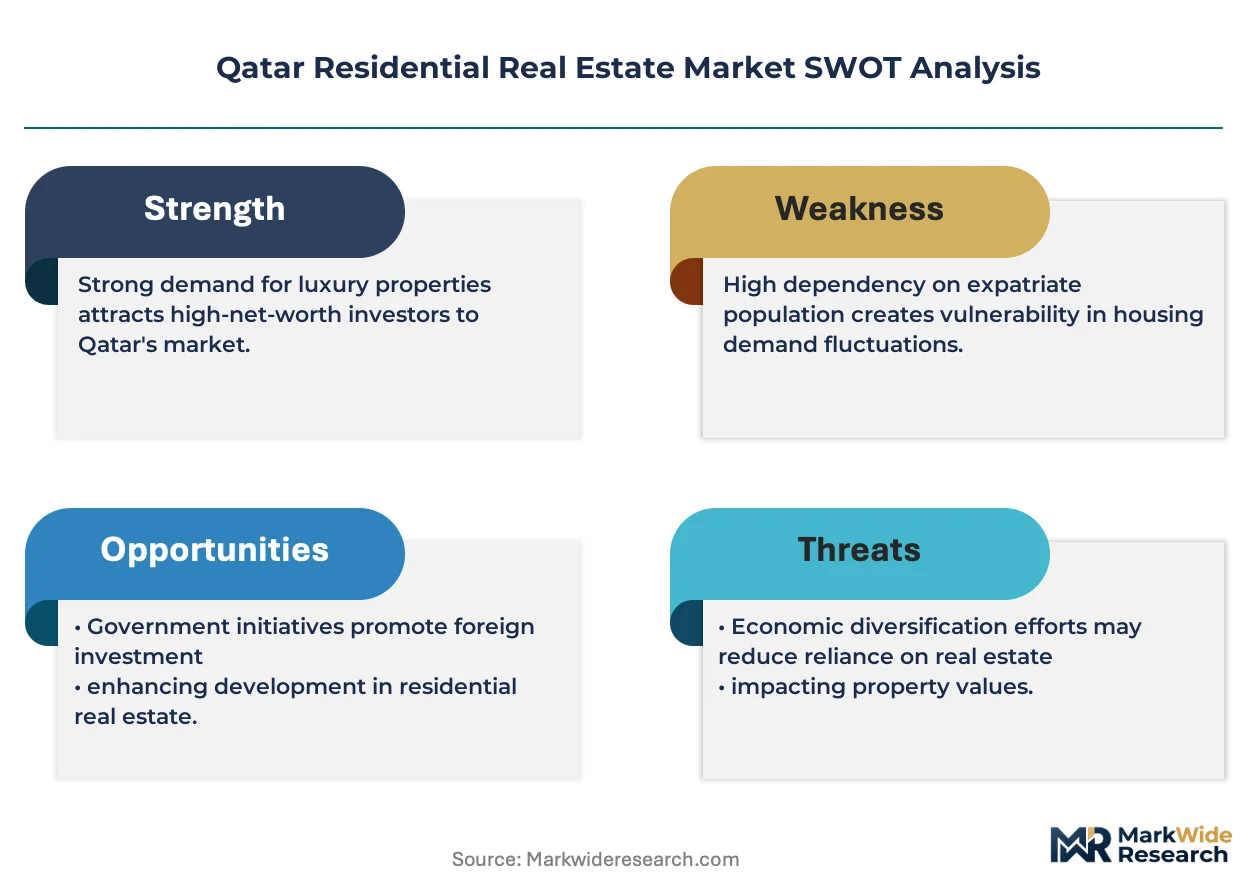
Premium villa specifications with smart-home infrastructure and district cooling integration is unwinding across Doha's northern corridor. Qatari Diar Real Estate Company leverages its sovereign-backed land bank to dominate waterfront master plans. Msheireb Properties differentiates through heritage-sensitive urban regeneration in the capital's historic core. Ezdan Holding Group sustains volume leadership in mid-income apartment blocks across Al Wakra and Al Khor.
Qatar residential real estate comprises purpose-built housing units ranging from studio apartments to detached villas, constructed with reinforced concrete frames, thermal insulation rated for desert climates, and integrated smart metering systems designed to shelter permanent residents and long-term expatriates. The property type dimension tilts toward villas and townhouses where foreign ownership zones generate premium margin pools, while apartments serve the rental-heavy expatriate workforce. Customer type segmentation reveals first-time buyers and investors as the active demand poles, with financing model choices increasingly favoring mortgage instruments as Qatar Central Bank expands eligible lender rosters.
Qatar's Ministry of Municipality and Environment enforces building permits tied to green construction codes, while the Qatar Central Bank regulates mortgage-to-value ratios and foreign buyer eligibility. These frameworks shape product standards by mandating energy efficiency thresholds and restricting speculative leverage. Stakeholders must monitor how Lusail's infrastructure completion timelines and World Cup legacy asset conversions alter absorption patterns in premium sub-markets.
Market Dynamics
Qatar's updated building energy codes are compressing development timelines and forcing developers to integrate district cooling and smart metering infrastructure into all new residential towers, fundamentally altering project economics and procurement patterns.
Growth Catalysts
- Foreign ownership liberalization:Designated freehold zones in Lusail and The Pearl-Qatar now permit non-Qatari nationals to purchase residential units outright, unlocking capital inflows from high-net-worth expatriate households across the Gulf Cooperation Council.
- Qatar Central Bank mortgage expansion:Eligible lender rosters now include additional conventional and Islamic banks, extending fixed-rate financing instruments to mid-income segments previously excluded from formal credit channels.
- Legacy asset conversion pipeline:World Cup-era worker accommodation clusters are being retrofitted into permanent residential stock, with the Ministry of Municipality and Environment fast-tracking permit approvals for compliant redevelopment schemes.
Market Restraints
- Construction input cost volatility:Reinforced steel and aluminum cladding prices fluctuate with Gulf spot markets, squeezing margin buffers on fixed-price development contracts signed before commodity spikes.
- Labor concentration risk:Specialized MEP contractors for district cooling integration are concentrated among Doha-based firms, creating bottleneck risks when multiple master-planned communities hit simultaneous completion milestones.
- Green code compliance friction:Qatar's mandatory thermal insulation ratings for desert climates require imported high-performance materials not yet stocked by local distributors, extending procurement lead times.
Strategic Opportunities
- Al Wakra corridor expansion:Ezdan Holding Group's volume leadership in this southern municipality demonstrates latent demand for mid-income apartments among healthcare and logistics workforce clusters near Hamad Port.
- Heritage-sensitive regeneration:Msheireb Downtown Doha's adaptive reuse model offers a replicable template for secondary historic districts in Al Rayyan and Umm Salal municipalities seeking differentiated positioning.
- Smart-home technology convergence:Integration of IoT-enabled energy management with Qatar General Electricity and Water Corporation's smart grid infrastructure creates premium pricing power for tech-forward villa specifications.
Industry Challenges
- Certification timeline compression:Qatar Green Building Council's sustainability ratings now require third-party verification of post-occupancy energy performance, adding 4-6 months to handover schedules.
- Skill scarcity in building automation:Systems integrators capable of commissioning BMS-to-utility grid interfaces command premium wages, inflating soft costs for master-planned community developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Residential Real Estate Market |
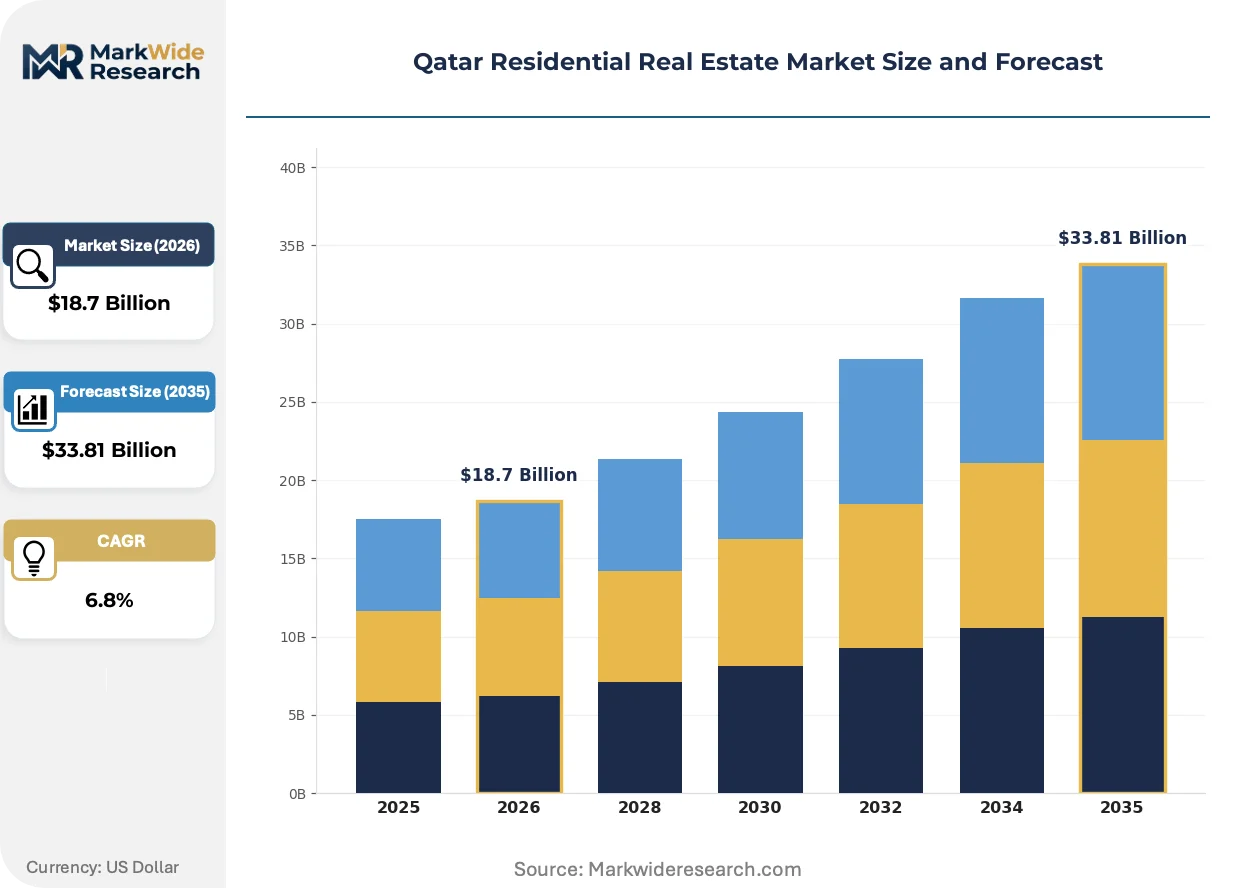
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Apartments, Villas, Townhouses, Duplexes Customer Type: First-time Buyers, Investors, Renters, Expats Price Tier: Luxury, Mid-range, Affordable, Budget Financing Model: Cash Purchase, Mortgage Financing, Lease-to-Own, Rent |
| Companies Covered | Qatari Diar Real Estate Company, Mazaya Real Estate Development, Ezdan Holding Group, Msheireb Properties, First Qatar Real Estate Development Co., Barwa Real Estate, Al Mana Real Estate, Al Asmakh Real Estate, United Development Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Residential Real Estate Market Evolving Landscape
Residential development in Qatar is pivoting from speculative volume to performance-guaranteed product, with buyers demanding verified operational efficiency and developers responding through technology-heavy specifications and service-layer unbundling.
Modular prefabrication for bathroom pods and kitchen cores is fragmenting traditional construction workflows. Boutique developers in Lusail's Fox Hills district now source complete wet-zone modules from UAE-based manufacturers, compressing on-site labor hours by half. This technology is fragmenting the subcontractor base, as specialized module integrators displace conventional masonry and tiling crews from critical-path schedules.
Qatar's Ministry of Municipality and Environment now mandates GSAS certification for all government-leased residential stock. This green building standard forces developers to document embodied carbon in structural concrete and aluminum systems, raising upfront specification costs. Premium villa segments absorb these premiums through branded sustainability positioning, while mid-income apartment developers seek GSAS-ready design templates to minimize re-engineering.
Buyer due diligence has intensified around operational cost transparency. Expatriate investors now request three-year historical utility data before committing to The Pearl-Qatar or Lusail waterfront units, treating cooling and service charge inflation as primary risk factors. This behavior shift is most visible among Gulf Cooperation Council nationals acquiring Doha properties as rental income vehicles, who now prioritize buildings with verified district cooling efficiency over speculative capital appreciation narratives.
Qatar Residential Real Estate Market Segmentation
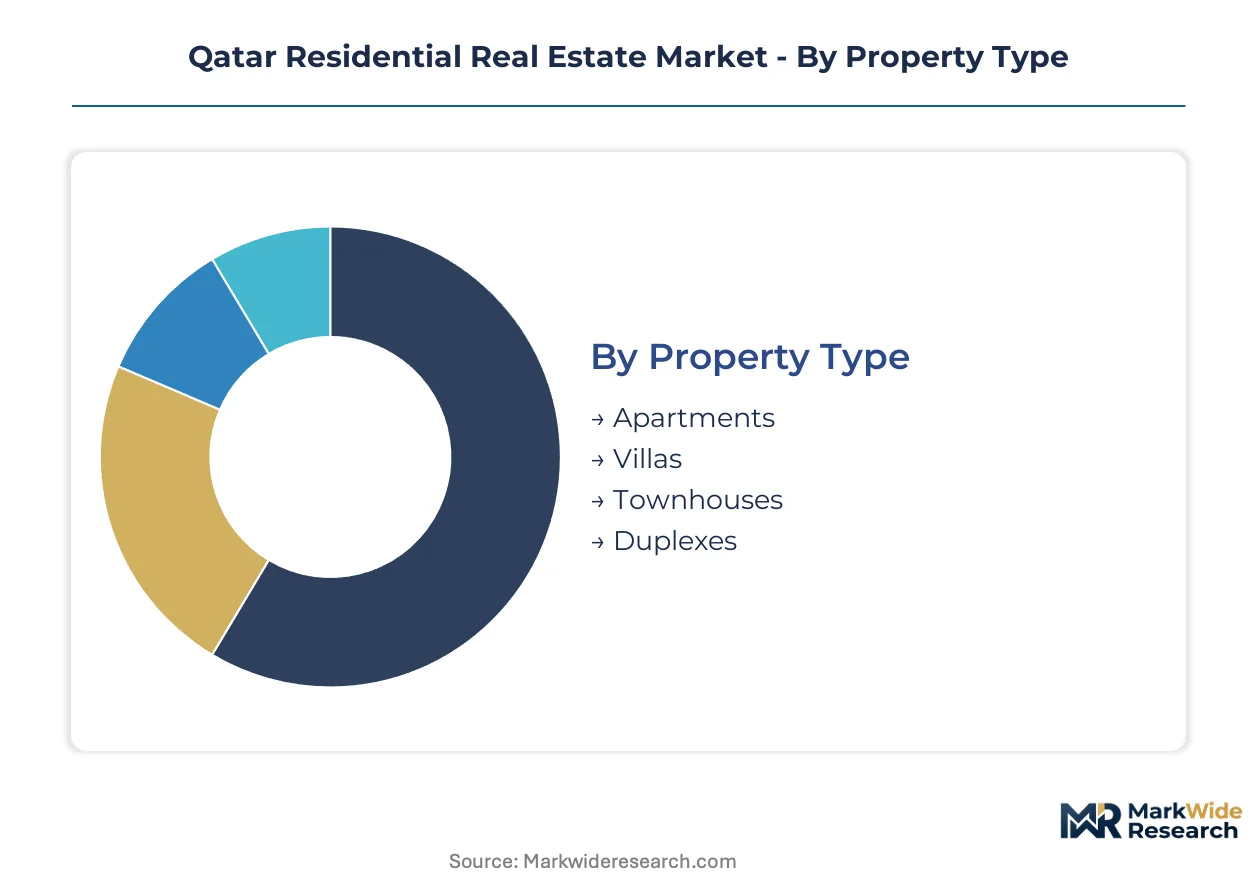
Segmentation in Qatar's residential real estate market reveals how regulatory frameworks and buyer eligibility rules create distinct commercial zones. Qatar Central Bank mortgage expansion and Ministry of Municipality foreign ownership designations channel demand into specific property categories and financing instruments.
Property Type:
Qatar's Ministry of Municipality and Environment applies differentiated building energy codes across structural typologies, with villas facing stricter thermal insulation mandates than apartments.
- Villas:Detached units with reinforced concrete frames and integrated smart metering systems command premium margins in Doha's northern corridor and Lusail's waterfront districts. Qatar Central Bank mortgage eligibility extends to freehold villa zones, concentrating high-net-worth expatriate demand in The Pearl-Qatar and Lusail City.
- Apartments:Mid-rise and high-rise residential towers serve Qatar's rental-heavy expatriate workforce, particularly in Al Wakra and Al Khor municipalities. District cooling integration is mandatory under updated energy codes, compressing development timelines for new tower projects.
- Townhouses:Attached multi-level units bridge the gap between villa privacy and apartment density, attracting small-family segments in master-planned communities.
- Duplexes:Two-unit stacked configurations offer limited inventory in heritage-sensitive regeneration zones like Msheireb Downtown Doha.
Established volume favors apartments; emerging adoption favors villas.
Customer Type:
Buyer eligibility rules under Qatar Central Bank regulations and Ministry of Interior residency frameworks segment the market into four distinct customer profiles with divergent financing access.
- Investors:Gulf Cooperation Council nationals and designated foreign nationals acquiring rental income vehicles in freehold zones now demand three-year historical utility data before committing, prioritizing verified district cooling efficiency over speculative appreciation narratives.
- First-time Buyers:Qatari nationals accessing subsidized land allocation programs and expanded mortgage lender rosters drive absorption in affordable and mid-range segments across Al Rayyan and Umm Salal municipalities.
- Expats:Long-term resident professionals with transferable employment contracts concentrate rental demand in service-charge-transparent buildings near healthcare and logistics clusters.
- Renters:Short-to-medium term workforce housing needs absorb legacy World Cup accommodation assets undergoing permanent conversion.
Volume concentration sits with investors; regulatory tailwinds favor first-time buyers.
Price Tier:
Cost stratification aligns with Qatar General Electricity and Water Corporation smart grid integration levels and GSAS certification tiers, creating four distinct specification bands.
- Luxury:Smart-home infrastructure with IoT-enabled energy management and BMS-to-utility grid interfaces commands premium pricing in Lusail's Fox Hills district and The Pearl-Qatar waterfront corridors.
- Mid-range:GSAS-ready design templates minimize re-engineering costs for developers targeting healthcare and logistics workforce clusters near Hamad Port.
- Affordable:Standard thermal insulation ratings and conventional cooling systems serve entry-level Qatari buyers in peripheral municipalities.
- Budget:Retrofitted World Cup-era worker accommodation clusters compete on location proximity to industrial zones.
Margin pool depth favors luxury; absorption velocity favors mid-range.
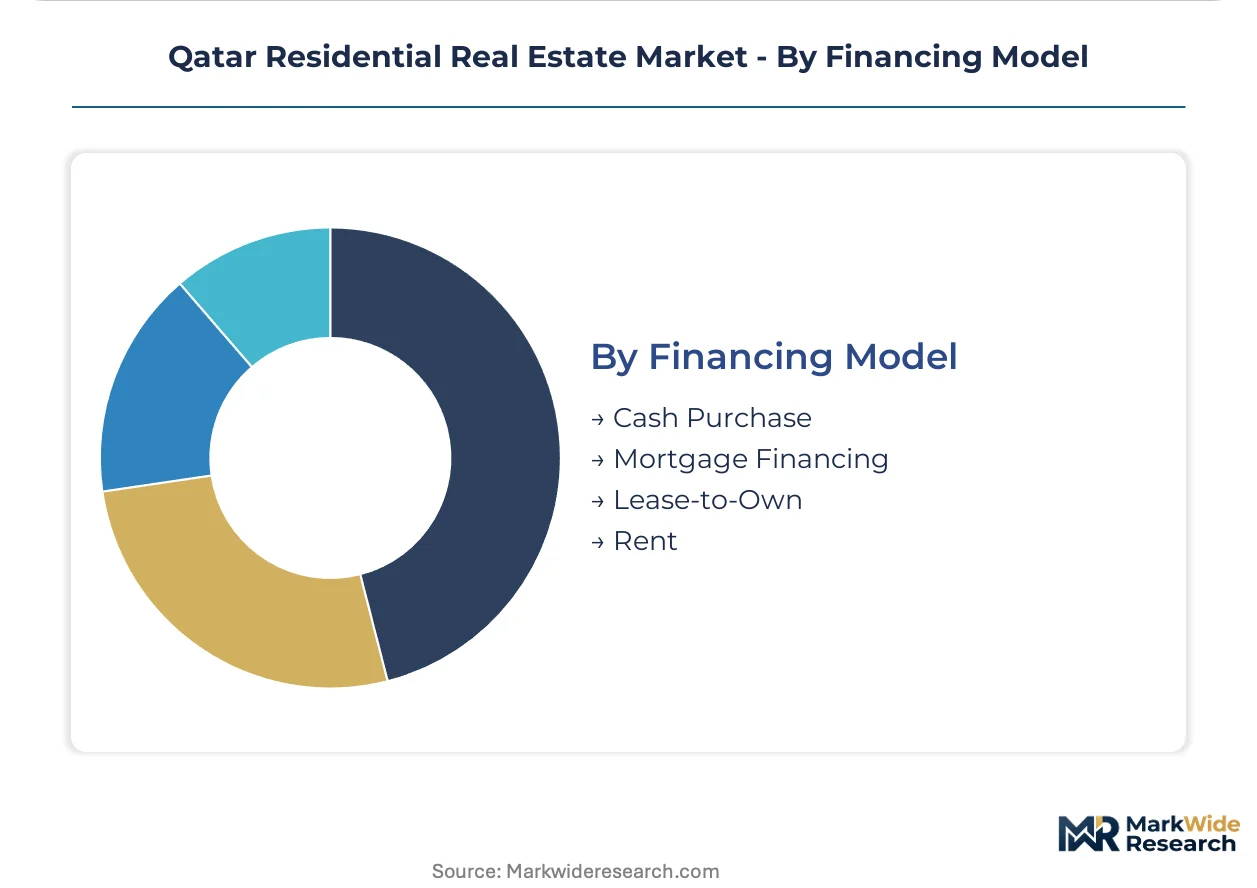
Financing Model:
Qatar Central Bank regulatory frameworks determine instrument availability across resident categories, with mortgage-to-value ratios and foreign buyer eligibility shaping transaction structures.
- Mortgage Financing:Expanded eligible lender rosters now include additional conventional and Islamic banks, extending fixed-rate instruments to mid-income segments previously excluded from formal credit channels.
- Cash Purchase:High-net-worth Gulf Cooperation Council nationals and designated expatriates deploy capital directly in freehold zones, bypassing leverage restrictions.
- Lease-to-Own:Structured payment programs for Qatari nationals in government allocation schemes bridge affordability gaps in emerging municipalities.
- Rent:Dominant transaction mode for non-eligible foreign residents and short-term contract workers, with service charge transparency now a primary selection criterion.
Transaction volume flows through rent; regulatory expansion elevates mortgage financing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development activity concentrates in Qatar's coastal municipalities where sovereign land banks and foreign ownership zones overlap. Lusail City, The Pearl-Qatar, and Doha's northern corridor absorb the bulk of premium residential investment, while southern municipalities serve workforce housing needs.
Lusail City
Waterfront districts in this master-planned municipality attract high-net-worth expatriate households from Gulf Cooperation Council states. Qatar Central Bank mortgage expansion extends to freehold zones here, enabling fixed-rate financing for non-Qatari buyers. Fox Hills and Marina districts concentrate smart-home villa specifications with district cooling integration.
The Pearl-Qatar
Foreign ownership liberalization permits outright purchase by designated non-nationals in this artificial island development. Ministry of Municipality and Environment building energy codes mandate GSAS certification for new towers, extending procurement timelines. Porto Arabia and Qanat Quartier sub-districts command premium margins on verified operational efficiency metrics.
Al Wakra
Mid-income apartment demand surges among healthcare and logistics workforce clusters near Hamad Port. Ezdan Holding Group's volume leadership demonstrates latent absorption capacity in this southern municipality. Qatar General Electricity and Water Corporation smart grid integration lags northern districts, constraining premium pricing power.
Msheireb Downtown Doha
Heritage-sensitive urban regeneration differentiates this historic core district from greenfield master plans. Ministry of Municipality permits for adaptive reuse projects receive expedited processing. Boutique duplex inventory serves small-family segments seeking capital appreciation with cultural proximity to central business district employment.
Al Rayyan and Umm Salal
First-time Qatari buyers access subsidized land allocation programs in these peripheral municipalities. Qatar Central Bank eligible lender rosters now include Islamic banks serving mid-range segments. Standard thermal insulation ratings and conventional cooling systems dominate specification bands in affordable tiers.
Qatar Residential Real Estate Market Competitive Landscape
Concentration sits with sovereign-backed developers controlling waterfront land banks. The competitive structure divides between state-linked master planners, mid-income volume specialists, and heritage-focused regenerators. Strategic moves center on GSAS certification pre-positioning and smart-home technology bundling to justify premium pricing.
Within the sovereign-linked tier, Qatari Diar Real Estate Company and Barwa Real Estate occupy positions anchored by preferential land access. Ezdan Holding Group exemplifies the volume-driven mid-income archetype across southern municipalities. Msheireb Properties represents the differentiated regenerator model with heritage-sensitive positioning in Doha's historic core.
| Leading Market Players |
|---|
| Qatari Diar Real Estate Company |
| Mazaya Real Estate Development |
| Ezdan Holding Group |
| Msheireb Properties |
| First Qatar Real Estate Development Co. |
| Barwa Real Estate |
| Al Mana Real Estate |
| Al Asmakh Real Estate |
| United Development Company |
| Others |
Value Network & Pricing Analysis
GSAS certification from Qatar Green Building Council gates both supplier qualification and price differentiation simultaneously, forcing developers to document embodied carbon in structural concrete and aluminum systems while buyers absorb premiums through verified sustainability positioning.
Pricing Analysis
Qatar's mandatory thermal insulation ratings for desert climates dictate the pricing tier structure across residential development. Three-tier pricing structure across premium, standard, and economy levels separates Lusail waterfront villas with IoT-enabled energy management from Al Wakra mid-income apartments with conventional cooling systems. Price differentiation rests on GSAS certification tier and smart grid integration level, with premium segments commanding justified premiums while mid-range developers seek GSAS-ready templates to minimize re-engineering. Cost compression in mid-income apartment construction is intensifying because imported high-performance insulation materials extend procurement lead times. Expatriate investors purchasing rental income vehicles in The Pearl-Qatar demonstrate lowest price sensitivity, prioritizing verified district cooling efficiency over capital appreciation narratives.
Supply Chain Analysis
China and the United Arab Emirates anchor reinforced steel and modular prefabrication supply for Qatar's residential construction sector. The supply chain draws from UAE-based manufacturers for complete wet-zone bathroom pods and kitchen cores, while Chinese mills feed structural steel and aluminum cladding tied to Gulf spot market volatility. Raw material dependencies center on reinforced concrete frames, thermal insulation rated for desert climates, and district cooling MEP components. Single-source vulnerability concentrates among Doha-based specialized MEP contractors for district cooling integration, creating bottleneck risks when multiple master-planned communities hit simultaneous completion milestones. Distribution runs through sovereign-backed developers with preferential land bank access, channeling volume through Qatari Diar and Barwa Real Estate procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's residential real estate market operates as a defensive-moat story anchored by regulatory entrenchment, where Ministry of Municipality foreign ownership designations and Qatar Central Bank mortgage eligibility frameworks create structurally protected competitive positions.
For Market Incumbents: Compound sovereign land bank advantages by accelerating GSAS certification pre-positioning ahead of mandatory government-lease requirements. Vertical integration into district cooling MEP capabilities addresses specialized contractor concentration risk threatening simultaneous project completions. Capacity addition in Lusail's Fox Hills and Marina districts captures high-net-worth expatriate demand before foreign ownership liberalization fully matures.
For New Entrants and Emerging Players: Lead with modular prefabrication partnerships targeting mid-income apartment segments in Al Wakra and Al Khor municipalities where Ezdan Holding Group's volume leadership demonstrates latent absorption capacity. The most penetrable geography sits in southern workforce housing corridors near Hamad Port, where healthcare and logistics clusters generate sustained rental demand. A go-to-market angle emphasizing service-charge transparency and three-year historical utility data disclosure aligns with intensified buyer due diligence behaviors among Gulf Cooperation Council investors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-income volume specialists lacking smart-home technology bundling capabilities and heritage-sensitive regeneration expertise. Long-term viability across a five-to-ten year window favors developers with secured GSAS certification pipelines and Qatar Central Bank eligible lender relationships. The signal to watch as inflection indicator is Ministry of Municipality permit approval velocity for World Cup legacy asset conversions, which would signal absorption capacity expansion in premium sub-markets.
| Strategic Initiative | Industry Significance |
|---|---|
| GSAS Certification Pre-Positioning | Qatar Green Building Council mandates now govern government-leased residential stock eligibility. |
| District Cooling MEP Integration | Specialized contractor scarcity in Doha creates bottleneck risks for master-planned community developers. |
| Modular Prefabrication Partnerships | UAE-based wet-zone module manufacturers compress on-site labor hours by half for boutique developers. |
| Smart Grid Interface Development | Qatar General Electricity and Water Corporation infrastructure convergence enables premium villa pricing power. |
| Heritage-Sensitive Adaptive Reuse | Msheireb Downtown Doha's model offers replicable template for Al Rayyan and Umm Salal municipalities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Qatar Central Bank mortgage regulations, Ministry of Municipality building permit databases, and GSAS certification records. Primary interviews engaged real estate development executives, district cooling MEP contractors, Qatar Green Building Council certification officers, and Ministry of Municipality planning officials. Secondary validation incorporated Qatar Central Bank eligible lender rosters, Lusail City infrastructure completion timelines, and World Cup legacy asset conversion permit data. Bottom-up unit absorption modeling triangulated against top-down sovereign land bank deployment schedules.
Segmentation dimensions modeled include property type, customer type, price tier, and financing instrument across the projection horizon. The analytical framework incorporated foreign ownership liberalization trajectory, mortgage expansion eligibility rules, and green code compliance friction as industry-specific forecast inputs. CAGRs were derived through reconciling historical absorption patterns with infrastructure completion milestones and regulatory enforcement timelines.
Forecasts assume regulatory continuity in Qatar Central Bank mortgage-to-value frameworks and Ministry of Municipality foreign ownership designations; material policy shifts would require re-modeling. Specific risk factors include construction input cost volatility tied to Gulf spot markets and labor concentration risk among specialized MEP contractors. Recalibration cycles align with material shifts in Lusail infrastructure completion timelines and GSAS certification mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
India Residential Real Estate Market