
 Canada Residential Real Estate Market | 2026-2036
Canada Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Residential Real Estate Market Outlook
Buyer concentration among first-time millennials and remote-work relocators is pivoting development schedules toward mid-rise condominiums and suburban single-family inventory. Concord Pacific leverages its Vancouver land bank to dominate waterfront high-rise supply. Mattamy Homes anchors the low-rise segment across Ontario's exurban rings. Tridel differentiates through LEED-certified construction protocols in the Toronto core.
Canada residential real estate encompasses fee-simple land ownership, strata-title condominiums, and leasehold arrangements governed by provincial land title systems, with transactions typically requiring mortgage financing stress-tested against the Bank of Canada qualifying rate. Its primary commercial purpose is to provide shelter equity accumulation while functioning as the principal household wealth vehicle in Canadian financial planning. Condominium stock leads transaction velocity in Toronto and Vancouver due to land scarcity and zoning density bonuses. Single-family home supply faces structural constraint from greenbelt preservation policies and municipal servicing limits. Rental demand intensifies across affordable and mid-range price tiers as ownership barriers climb.
Canada Mortgage and Housing Corporation underwriting standards and the Office of the Superintendent of Financial Institutions B-20 mortgage guidelines shape national credit availability and borrower qualification thresholds. Provincial regulators including the Real Estate Council of Ontario and the British Columbia Financial Services Authority enforce licensing, disclosure, and anti-money-laundering compliance across sales channels. Municipal inclusionary zoning bylaws in Toronto and Vancouver mandate affordable-unit set-asides that alter project pro formas. Stakeholders must monitor interest rate trajectories and interprovincial migration flows to calibrate land acquisition timing and product mix decisions.
Market Dynamics
Millennial household formation and interprovincial migration flows are compressing development timelines across Ontario and British Columbia, forcing builders to accelerate mid-rise condominium delivery while navigating municipal servicing constraints.
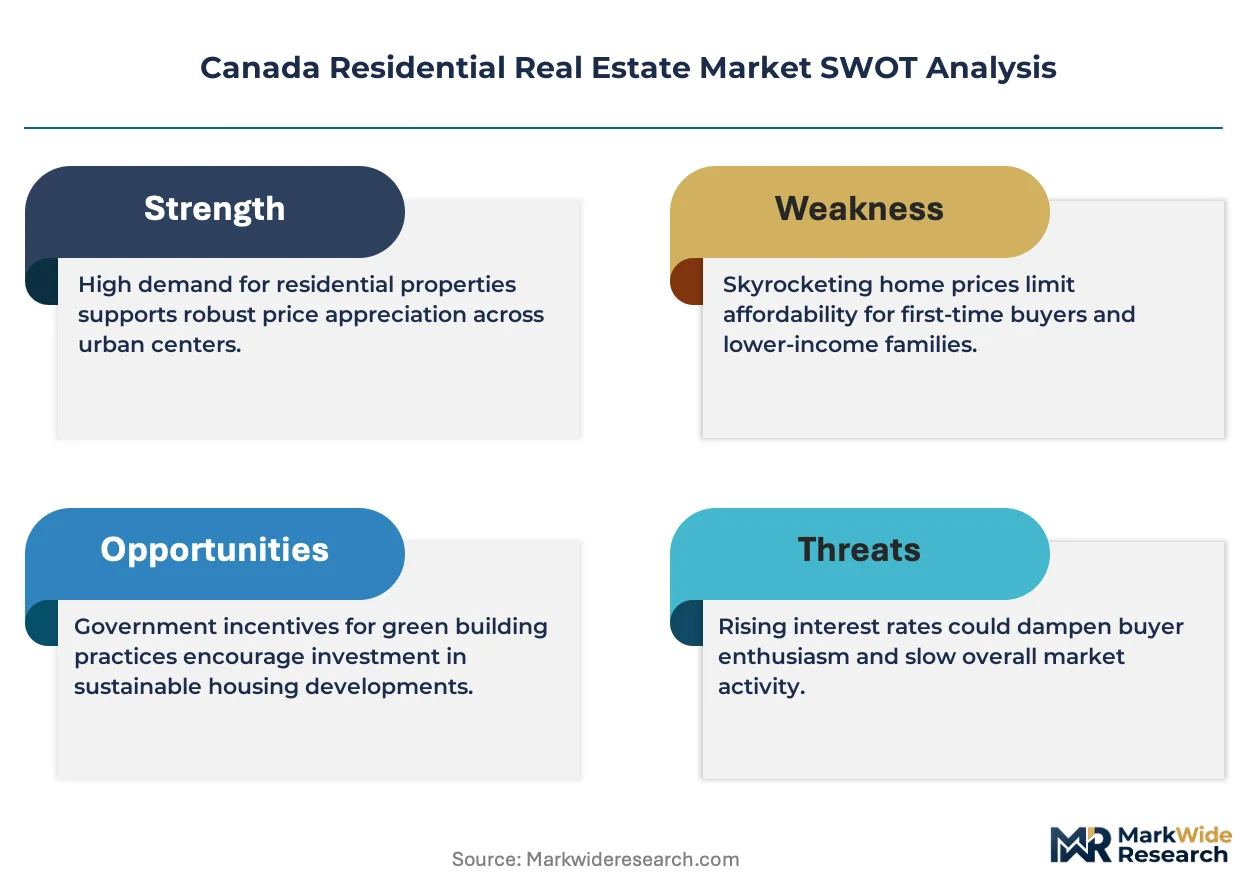
Growth Catalysts
- Canada Mortgage and Housing Corporation underwriting expansion:Federal mortgage insurance thresholds are stabilizing credit access for first-time buyers in high-cost urban corridors.
- Provincial rent control frameworks:British Columbia and Ontario stabilization policies are redirecting institutional capital toward purpose-built rental construction.
- Interprovincial migration concentration:Atlantic Canada and prairie province inflows are triggering secondary market inventory absorption in Halifax and Calgary.
Market Restraints
- Greenbelt preservation statutes:Ontario's protected land designations are structurally constraining single-family lot supply in the Greater Toronto Area.
- Municipal development charge escalation:Servicing cost recovery mechanisms in Vancouver and Toronto are inflating per-unit pro forma thresholds.
- Construction labor scarcity:Skilled trade availability gaps in framing and electrical trades are extending project completion timelines.
Strategic Opportunities
- Transit-oriented density bonuses:Ontario's Bill 23 and similar provincial instruments are unlocking higher FAR entitlements near GO Transit corridors.
- Mass timber structural systems:Hybrid engineered wood products are penetrating mid-rise construction as an alternative to concrete podium-and-tower typologies.
- Secondary market institutionalization:Purpose-built rental platforms are consolidating fragmented landlord ownership in Montreal and Ottawa.
Industry Challenges
- Municipal approval timeline volatility:Committee of adjustment and Ontario Land Tribunal processes are introducing permitting uncertainty.
- Climate resilience retrofit standards:British Columbia's step code and similar provincial energy mandates are requiring envelope specification upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Residential Real Estate Market |
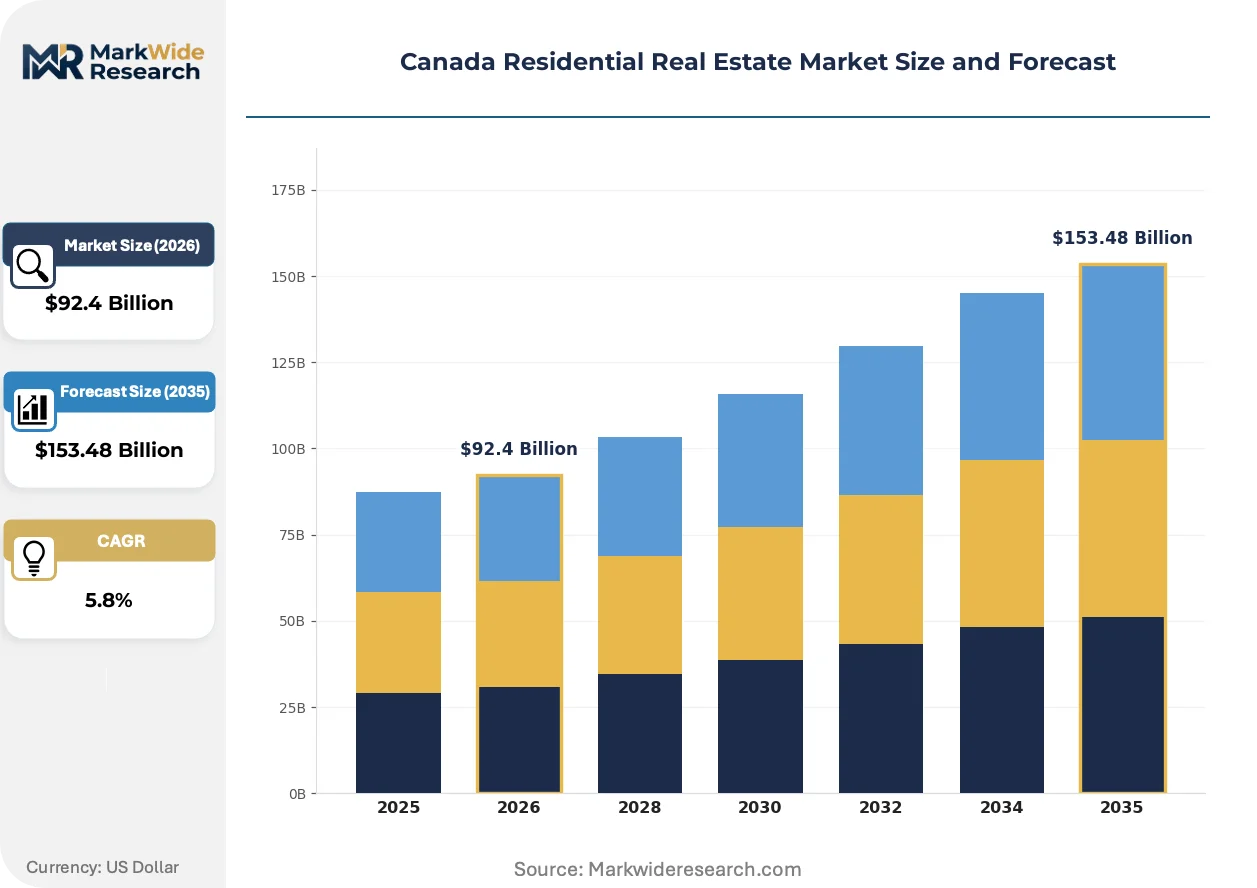
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominium, Single-Family Home, Townhouse, Multi-Family Unit Transaction Type: Purchase, Sale, Rental, Lease Price Tier: Affordable, Mid-Range, Luxury, Premium Sales Channel: Direct, Realtor, Auction, Online Listing |
| Companies Covered | Concord Pacific, Onni Group, Westbank Corp, Daniels Corporation, Tridel, Mattamy Homes, Blackstone, Artis REIT, BTB REIT, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Residential Real Estate Market Strategic Shifts
Digital transaction infrastructure and prefabrication methods are compressing traditional development cycles, while provincial housing supply legislation is overriding municipal zoning constraints to accelerate entitlement timelines.
Modular volumetric construction is expanding into mid-rise residential applications, enabling factory-controlled envelope assembly that reduces on-site labor dependency. Ontario-based developers are piloting six-to-twelve-storey hybrid modules for rental projects in Hamilton and Kitchener. This manufacturing shift is compressing weather-dependent construction schedules and standardizing unit finishes across dispersed sites.
British Columbia's Housing Supply Act is overriding municipal zoning restrictions to mandate density minimums in designated transit corridors, compelling Vancouver and Burnaby to approve projects that exceed local comprehensive plans. The legislation is accelerating project approvals for rental-focused developers. Municipalities are responding by negotiating community amenity contribution frameworks that preserve local revenue capture.
First-time buyer qualification patterns are shifting toward co-ownership structures and rent-to-equity transition products as mortgage stress-test thresholds persist. Alternative ownership models are gaining traction in Toronto and Vancouver where traditional down payment requirements exclude median-income households. Quebec's undivided co-ownership framework is attracting attention as a template for Ontario regulatory adaptation.
Canada Residential Real Estate Market Segmentation
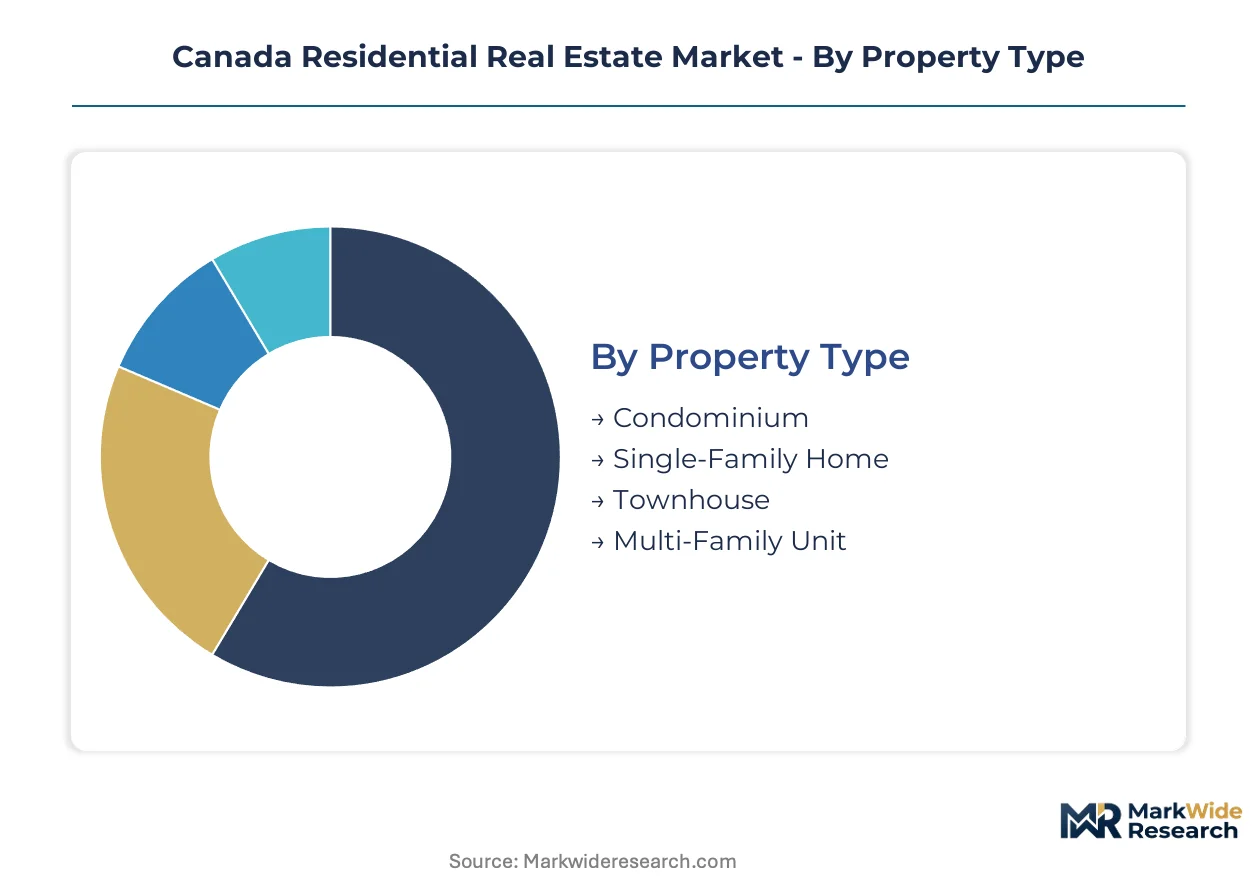
Segmentation in Canadian residential real estate reveals how regulatory frameworks, financing structures, and buyer demographics fragment demand across distinct transaction categories. Each segment carries unique approval burdens from CMHC underwriting standards to provincial land title requirements.
Property Type:
CMHC mortgage insurance and provincial strata property acts impose divergent compliance burdens across dwelling categories, with condominiums requiring additional reserve fund disclosures and single-family transactions triggering land transfer tax calculations.
- Condominium:Strata-title ownership governed by provincial condominium acts requires mandatory reserve fund studies and depreciation reports in British Columbia and Ontario. Demand concentrates in Toronto and Vancouver cores where land scarcity and density bonuses from municipal inclusionary zoning accelerate mid-rise tower approvals.
- Single-Family Home:Fee-simple land ownership with direct title transfer through provincial land registry systems. Supply faces structural constraint from Ontario's greenbelt preservation statutes and municipal servicing limits in Metro Vancouver's Agricultural Land Reserve boundaries.
- Townhouse:Hybrid ownership structures blending strata common elements with individual freehold parcels. Ontario's Bill 23 transit-oriented density provisions are unlocking stacked townhouse approvals near GO Transit corridors.
- Multi-Family Unit:Purpose-built rental stock governed by provincial residential tenancy acts and rent control frameworks. Institutional capital is redirecting toward this segment as British Columbia and Ontario stabilization policies alter developer pro formas.
Condominium stock sits at the top of the volume ranking, with multi-family units climbing the fastest as institutional rental platforms consolidate fragmented ownership.
Transaction Type:
Financing mechanics and tax treatment create distinct margin profiles across transaction modes, with purchase transactions requiring OSFI B-20 stress-tested qualification while rental arrangements trigger provincial tenancy board oversight.
- Purchase:Fee-simple or strata-title acquisition requiring CMHC mortgage insurance for high-ratio loans and provincial land transfer tax remittance. First-time buyer programs in Ontario and British Columbia are compressing down payment thresholds for median-income households.
- Sale:Disposition triggering capital gains exposure for non-principal residences and GST/HST obligations on new construction. The Real Estate Council of Ontario and British Columbia Financial Services Authority enforce anti-money-laundering disclosure across sales channels.
- Rental:Tenancy arrangements governed by provincial residential tenancy acts with rent control variations. Quebec's lease transfer framework and Ontario's standard lease requirements impose distinct regulatory burdens on landlords.
- Lease:Long-term ground lease structures predominate in Vancouver's leasehold condominium stock on federal or First Nations land. CMHC underwriting treats leasehold equity differently in mortgage qualification calculations.
Purchase transactions anchor revenue concentration, with rental arrangements gaining share fastest as ownership barriers persist.
Price Tier:
Municipal inclusionary zoning mandates and CMHC insurance thresholds segment the market into discrete affordability bands, with each tier attracting different financing structures and buyer qualification patterns.
- Affordable:Units priced below municipal median thresholds qualifying for federal rapid housing initiative funding and provincial affordable housing programs. Toronto and Vancouver inclusionary zoning bylaws mandate set-aside percentages in new developments.
- Mid-Range:The qualifying-rate-sensitive segment where OSFI B-20 stress-test thresholds most directly constrain purchasing power. Interprovincial migration flows from Ontario and British Columbia are absorbing mid-range inventory in Calgary and Halifax secondary markets.
- Luxury:High-value transactions triggering additional provincial speculation taxes in British Columbia and Toronto's municipal land transfer tax surcharges. Foreign buyer prohibitions and underused housing taxes are reshaping demand composition.
- Premium:Ultra-high-value waterfront and heritage-designated stock in Vancouver's Coal Harbour and Toronto's Yorkville. Limited supply and land assembly complexity sustain price elevation independent of broader cycle movements.
Mid-range product dominates transaction velocity, with affordable units expanding most quickly under federal supply-targeted funding programs.
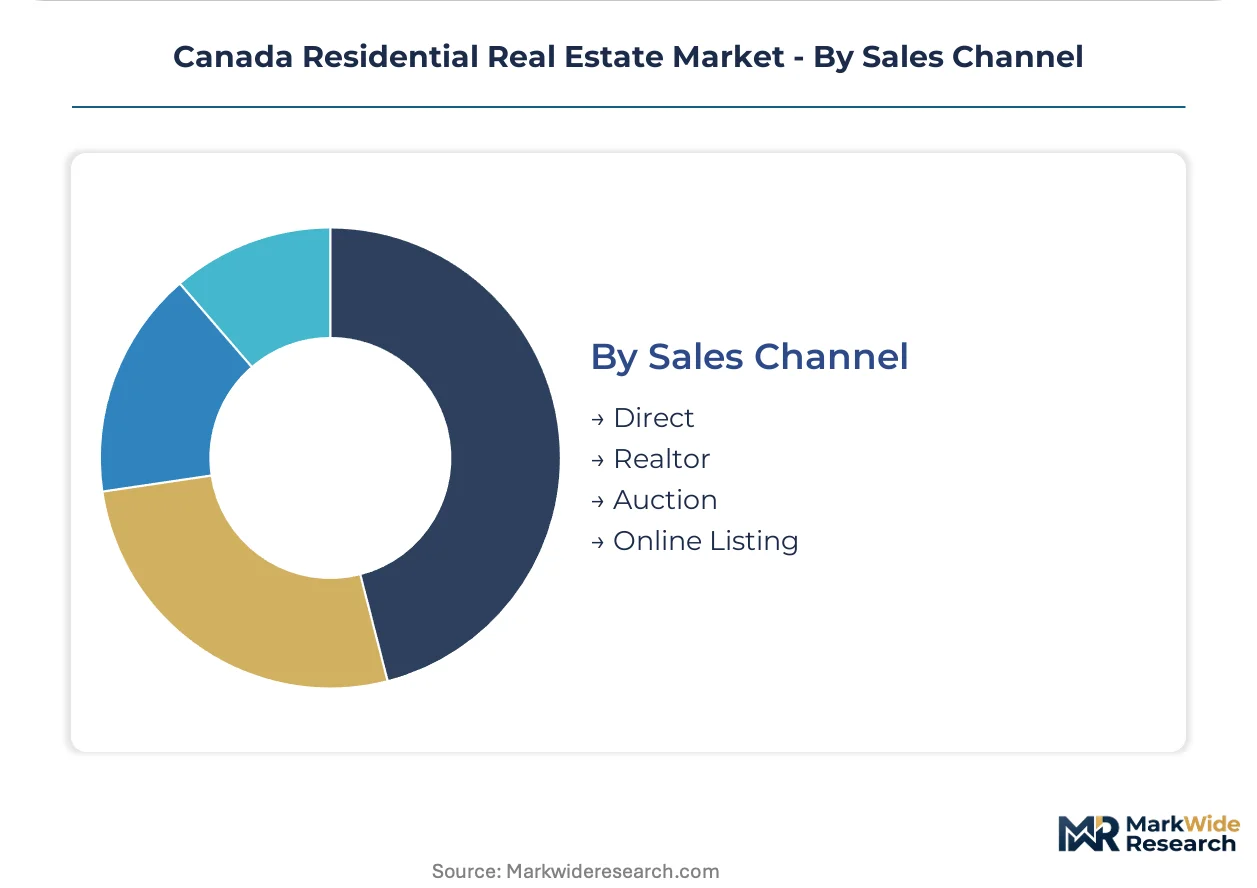
Sales Channel:
Regulatory licensing requirements and commission structures fragment distribution across channels, with realtor-mediated transactions subject to Real Estate Council discipline and direct sales triggering additional disclosure obligations.
- Direct:Developer-controlled sales through presentation centres and captive marketing platforms. Ontario's Tarion warranty corporation mandates specific disclosure timelines for new construction direct transactions.
- Realtor:Multiple listing service-mediated transactions governed by provincial real estate council codes of ethics. Commission structures and buyer representation agreements vary across provincial regulatory boundaries.
- Auction:Accelerated disposition for distressed or estate properties requiring court approval in some provincial jurisdictions. Limited penetration in residential markets compared to commercial or agricultural land sales.
- Online Listing:Digital platforms aggregating for-sale-by-owner and reduced-commission listings. British Columbia and Ontario regulators have issued guidance on digital advertising disclosure and anti-money-laundering compliance for platform-mediated transactions.
Realtor-mediated transactions command the largest volume share, with online platforms climbing fastest as digital infrastructure compresses search and transaction costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's transaction velocity outpaces British Columbia's dollar-per-unit metrics, while Alberta and Quebec attract divergent capital flows as interprovincial migration redistributes household formation patterns.
Ontario
First-time millennial buyers and remote-work relocators are compressing development timelines across the Greater Toronto Area. Ontario's Bill 23 transit-oriented density provisions unlock higher FAR entitlements near GO Transit corridors, accelerating mid-rise condominium approvals. Hamilton and Kitchener are absorbing overflow demand as Toronto's greenbelt preservation statutes constrain single-family lot supply.
British Columbia
Institutional capital is redirecting toward purpose-built rental construction under provincial rent stabilization policies. The Housing Supply Act overrides municipal zoning restrictions to mandate density minimums in designated transit corridors, compelling Vancouver and Burnaby to approve projects exceeding local comprehensive plans. Burnaby's Brentwood and Metrotown clusters are seeing accelerated rental-focused development.
Alberta
Interprovincial inflows from Ontario and British Columbia are triggering secondary market inventory absorption in Calgary. The absence of provincial rent controls attracts institutional capital seeking yield stability unavailable in Vancouver or Toronto. Calgary's downtown-to-suburban corridor is experiencing mid-range price tier velocity as migrating households capitalize on relative affordability.
Quebec
Montreal's purpose-built rental platforms are consolidating fragmented landlord ownership as institutional investors seek scale. The undivided co-ownership framework is attracting regulatory attention as a template for Ontario adaptation. The Greater Montreal Area is seeing secondary market institutionalization accelerate as rental demand intensifies across affordable and mid-range tiers.
Atlantic Canada
Halifax is absorbing interprovincial migration flows that bypass traditional Ontario and British Columbia destinations. Federal rapid housing initiative funding is targeting affordable unit delivery in Nova Scotia and New Brunswick. The Halifax Regional Municipality is experiencing development charge escalation as municipal servicing limits collide with compressed absorption timelines.
Canada Residential Real Estate Market Competitive Environment
Ontario-based developers anchor the low-rise and mid-rise segments; British Columbia specialists hold waterfront high-rise and rental-focused positions. The market structures around three tiers: integrated land-bank developers, regional production builders, and institutional rental platforms. Strategic archetypes include land-bank leveragers, transit-oriented density specialists, and purpose-built rental consolidators. Competitive moves concentrate on municipal entitlement acceleration and alternative ownership product development.
Among the integrated developer tier, Concord Pacific and Westbank Corp exemplify land-bank-leveraged positioning in Vancouver's constrained supply environment. Tridel occupies a position within the transit-oriented density specialist archetype, while Mattamy Homes anchors the regional production builder category across Ontario's exurban rings. Blackstone represents institutional capital deployment into purpose-built rental consolidation.
| Leading Market Players |
|---|
| Concord Pacific |
| Onni Group |
| Westbank Corp |
| Daniels Corporation |
| Tridel |
| Mattamy Homes |
| Blackstone |
| Artis REIT |
| BTB REIT |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration across Ontario and British Columbia land banks anchors developer pricing power by controlling entitlement timelines and limiting competing supply. This concentration enables tiered pricing strategies that extract premiums from transit-proximate locations while compressing margins in oversupplied submarkets.
Pricing Analysis
Capacity additions in Alberta and Atlantic Canada are reshaping price floors in secondary markets as interprovincial migration redirects demand from Toronto and Vancouver cores. Three-tier pricing structure across premium, standard, and affordable levels segments buyer qualification pools, with OSFI B-20 stress-test thresholds intensifying price sensitivity in mid-range tiers. Cost compression in suburban single-family product stems from greenbelt-constrained lot supply in the Greater Toronto Area. First-time millennial buyers exhibit highest price sensitivity, while luxury waterfront purchasers show least elasticity.
Supply Chain Analysis
Freight costs for engineered lumber and precast concrete components from Quebec, Ontario, and British Columbia manufacturing centers feed into project pro formas across dispersed sites. Construction inputs draw from Chinese steel fabrication, American gypsum board, and domestic mass timber processing. Single-source vulnerability concentrates in specialized glazing systems sourced from European suppliers. Distribution runs through developer-controlled procurement networks and general contractor tiering arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada residential real estate functions as a stable compounder underpinned by structural housing supply deficits that persist across federal policy cycles.
For Market Incumbents: Lock in land-bank positions near GO Transit corridors before Bill 23 density bonuses saturate entitlement pipelines. Secure framing and electrical trade capacity through multi-project labor agreements to mitigate completion timeline extension. Vertical integration into modular manufacturing compresses weather-dependent construction schedules.
For New Entrants and Emerging Players: Remote-work relocators seeking mid-range inventory in Calgary and Halifax represent an underserved buyer archetype with compressed local supply. Target purpose-built rental consolidation in Montreal and Ottawa where fragmented landlord ownership enables platform scale. Pursue co-ownership product development as mortgage stress-test thresholds exclude traditional qualification paths.
For Investors and Strategic Acquirers: Roll-up economics work for purpose-built rental platforms because provincial rent control frameworks redirect institutional capital toward yield-stabilized assets. Five-to-ten-year viability hinges on absorption of interprovincial migration flows into secondary markets. Monitor CMHC mortgage insurance threshold adjustments as inflection indicators for first-time buyer demand recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Transit-Oriented Density Entitlement | Ontario's Bill 23 unlocks higher FAR near GO Transit corridors, accelerating approval timelines. |
| Mass Timber Manufacturing Scale-Up | Hybrid engineered wood products reduce on-site labor dependency in mid-rise construction applications. |
| Purpose-Built Rental Platform Consolidation | Institutional capital captures yield stability unavailable in rent-controlled Vancouver or Toronto markets. |
| Alternative Ownership Product Development | Co-ownership structures address mortgage stress-test barriers for median-income households in high-cost cores. |
| Municipal Amenity Contribution Negotiation | Community benefit frameworks preserve local revenue capture under provincial density override legislation. |
Study Parameters
Coverage spans Ontario, British Columbia, Alberta, Quebec, and Atlantic Canada, with primary inputs from each region's development community. Interviews with land acquisition directors, municipal planning officials, condominium project marketers, and institutional portfolio managers combined with secondary validation from CMHC housing market data, provincial land registry transactions, municipal development charge bylaws, and OSFI regulatory guidance. Bottom-up project pipeline tracking and top-down macroeconomic triangulation anchored market sizing.
Granularity-level modeling distinguished property type, transaction mode, price tier, and sales channel dimensions across the projection horizon. Segment-level CAGRs derived from absorption rate trajectories, entitlement timeline distributions, and interprovincial migration flow projections. Forecast inputs incorporated interest rate sensitivity bands and construction labor availability indices.
Inputs from municipal planning departments and CMHC market reports were available through the study window; gaps in private land-bank transaction data introduce uncertainty bands around developer market share estimates. Forecasts reflect documented assumptions regarding policy continuity and migration pattern persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
United States Real Estate Brokerage Market