
 Mexico Combined Heat and Power Market | 2026-2036
Mexico Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Combined Heat and Power Market Foresight
Multi-source equipment procurement is expanding across Mexico's CHP landscape as project developers diversify beyond single-vendor dependencies. Capstone Turbine Corporation leverages its microturbine specialization to serve distributed commercial installations. General Electric Company anchors large-scale gas turbine deployments for industrial cogeneration complexes. Siemens AG competes across the full technology stack with integrated power island solutions.
Combined heat and power systems simultaneously generate electricity and useful thermal energy from a single fuel source, typically achieving total system efficiencies of 70-85 percent through waste heat recovery. These installations serve continuous-process industries requiring reliable steam, hot water, or chilled water alongside baseload power. Gas turbine technology dominates new capacity additions due to favorable natural gas pricing and rapid start-up capabilities. The industrial end-user segment absorbs the majority of megawatt-scale deployments, while commercial applications favor smaller reciprocating engine configurations. Onsite deployment models attract capital commitment from manufacturers seeking energy cost hedging.
The Comisión Federal de Electricidad retains transmission interconnection authority, while Mexico's energy regulator governs private generation permits under revised market rules. CRE licensing requirements and NOM environmental standards shape project feasibility timelines and equipment specification. Stakeholders must track regulatory interpretation consistency across federal and state permitting layers.
Market Dynamics
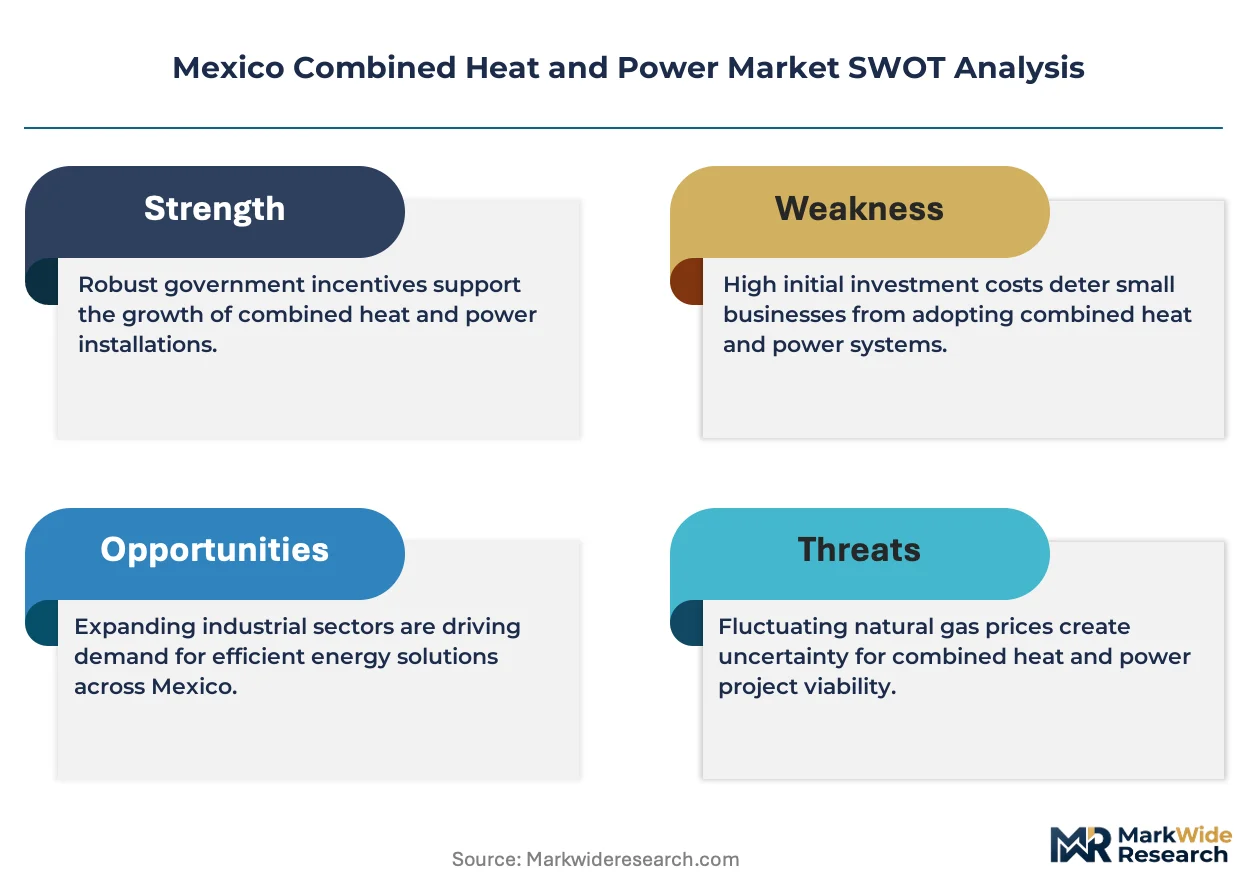
Natural gas price volatility and CRE permitting timelines are compressing project development cycles across Mexico's CHP landscape. Developers now front-load engineering design to secure interconnection queues before regulatory windows shift.
Growth Catalysts
- Energy Reform Framework:Private generation licensing under revised CRE rules enables industrial self-supply contracts previously restricted to CFE monopoly structures.
- Monterrey Manufacturing Corridor:Steel and cement producers anchor megawatt-scale gas turbine deployments seeking thermal baseload for continuous process operations.
- Waste Heat Recovery:Organic Rankine cycle bottoming systems boost total plant efficiency above 80 percent in food processing and chemical installations.
Market Restraints
- Natural Gas Import Dependency:Pipeline constraints from Texas and LNG terminal bottlenecks expose operators to Henry Hub price transmission volatility.
- Transmission Interconnection Queues:CFE grid authority creates 18-24 month delays for parallel operation permits in Baja California and Sonora industrial zones.
- Distributed Solar Substitution:Behind-the-meter PV plus battery configurations capture commercial load segments below 5 MW thermal demand threshold.
Strategic Opportunities
- Yucatan Peninsula Industrialization:Pemex refinery modernization and nearshoring manufacturing create greenfield CHP demand absent legacy grid infrastructure.
- Biogas Cogeneration:Agricultural waste-to-energy projects in Jalisco and Sinaloa qualify for NOM environmental credits under renewable dispatch rules.
- Performance Contracting:Energy Service Companies assume operational risk through guaranteed savings structures, bypassing industrial capex constraints.
Industry Challenges
- Specialized Technician Scarcity:Gas turbine combustion dynamics and control system calibration require skills concentrated among CFE-trained engineers approaching retirement.
- NOM Emissions Certification:Stack testing protocols and environmental impact statements add 8-12 months to project commissioning timelines.
- Legacy CFE Interconnection Standards:Synchronization equipment upgrades impose unplanned retrofit costs on early private generation assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Combined Heat and Power Market |
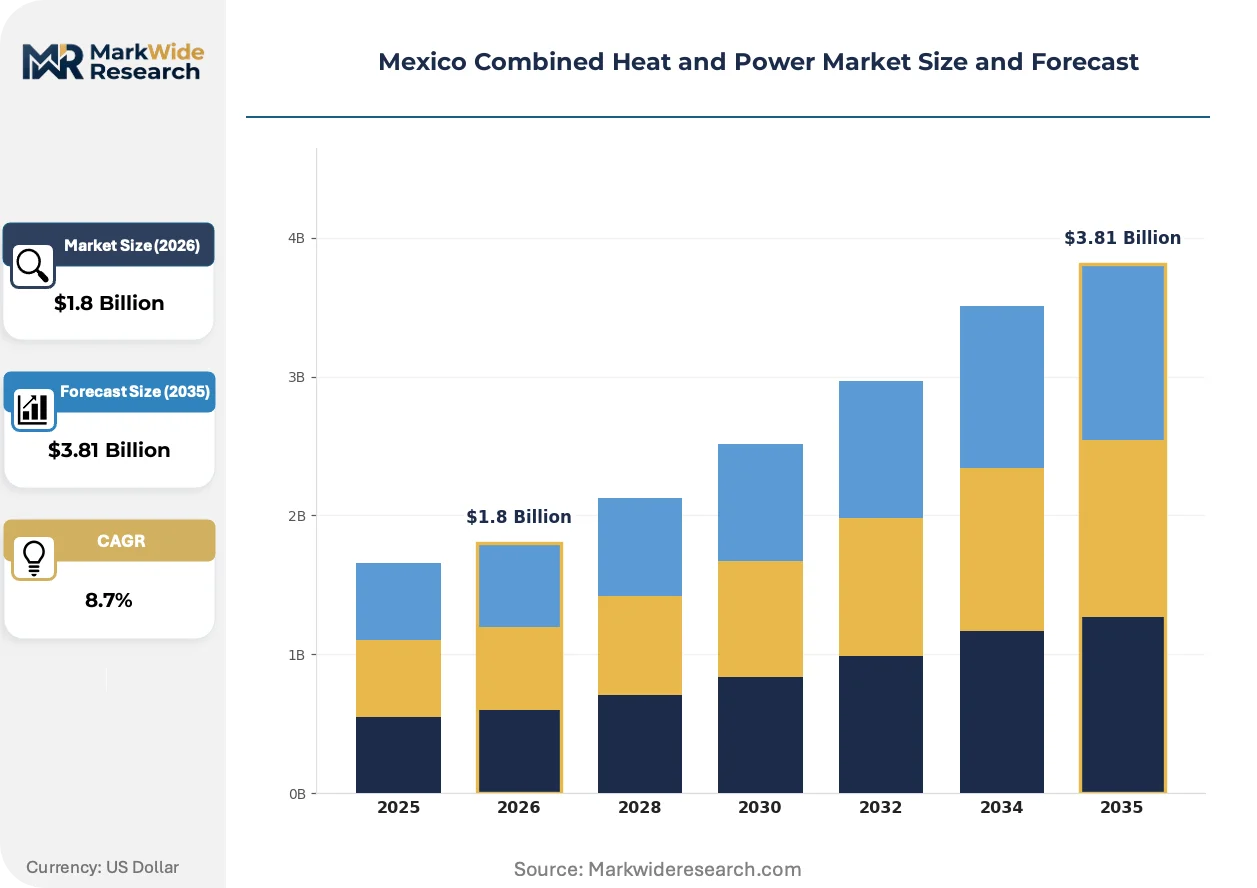
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbine, Steam Turbine, Reciprocating Engine, Fuel Cell End User: Industrial, Commercial, Residential, Institutional Deployment: Onsite, District Heating, Cogeneration Plant, Backup Power Fuel Type: Natural Gas, Biogas, Diesel, Biomass |
| Companies Covered | Capstone Turbine Corporation, SENER Engineering Group, General Electric Company, ContourGlobal, PEMEX Cogeneration and Services, Santos CMI, MAN Energy Solutions, Comisión Federal de Electricidad, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Combined Heat and Power Market Shifts & Advancements
Digital control architectures and modular plant designs are compressing deployment timelines while expanding operational flexibility for intermittent industrial loads.
Advanced microturbine packages with integrated heat recovery modules serve commercial and light industrial facilities below 2 MW electric capacity. Hospital and data center operators in Guadalajara and Queretaro favor these configurations for black-start capability and reduced footprint requirements. Capstone Turbine Corporation's technology stack is converging with building management system protocols, enabling real-time thermal load matching that displaces traditional boiler-turbine segregation.
CRE's 2023 technical standards revision mandates cybersecurity certification for grid-connected generation above 10 MW. Industrial developers must embed IEC 62443-compliant control networks into new project specifications. The automotive supplier cluster surrounding Tijuana faces accelerated compliance timelines as OEM customers demand supply chain energy security documentation.
Power purchase agreement structures now dominate procurement patterns for CHP installations serving multinational manufacturing subsidiaries. Industrial energy managers in Nuevo Leon prefer 10-15 year fixed-price thermal contracts over traditional equipment ownership models. This financing rotation concentrates risk assessment capabilities among specialized project developers rather than end-user engineering departments.
Mexico Combined Heat and Power Market Segmentation
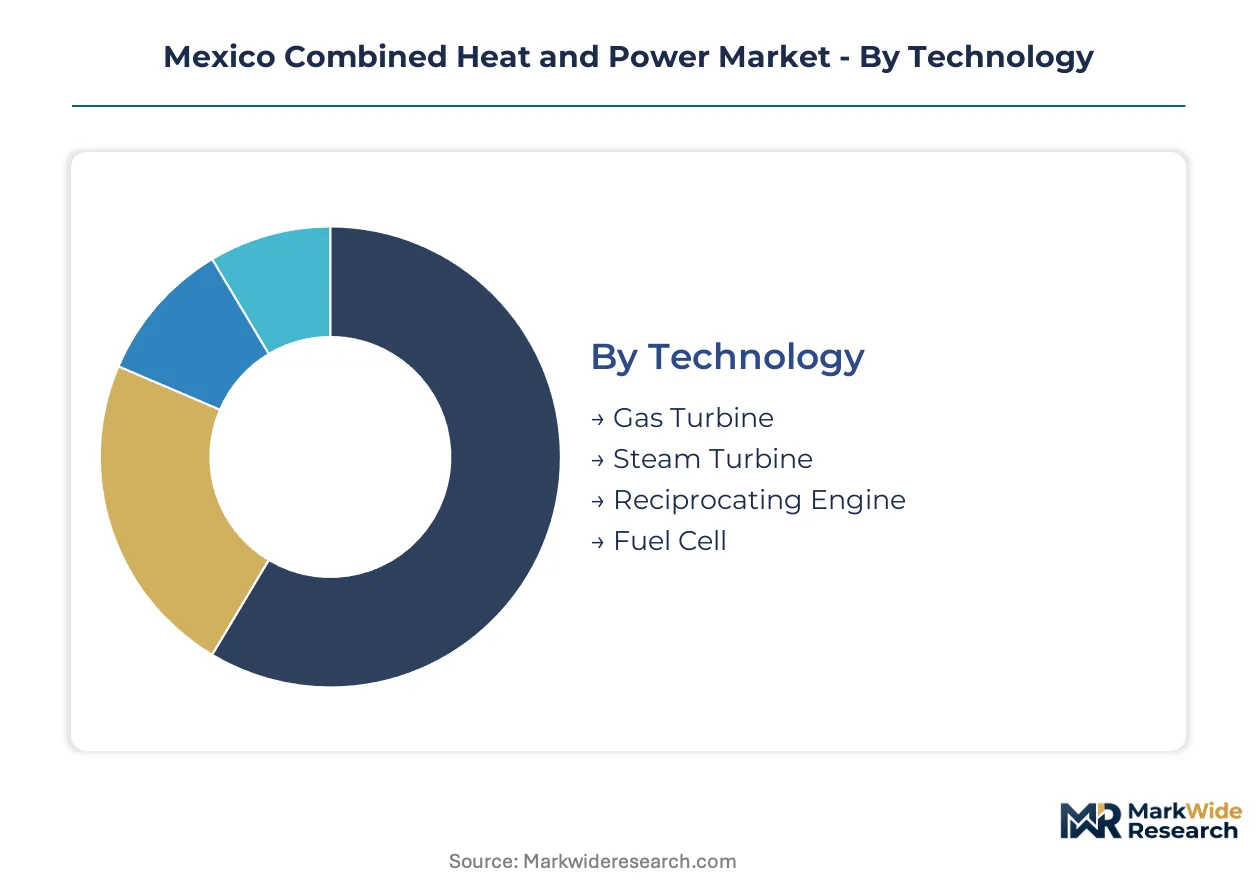
Technology selection and deployment configuration determine project economics across Mexico's CHP landscape. Each segmentation dimension carries distinct regulatory, operational, and capital implications that shape developer strategy.
Technology:
Customization intensity varies from standardized reciprocating engine packages to bespoke gas turbine island configurations engineered for specific thermal loads.
- Gas Turbine:Aeroderivative and heavy-frame configurations achieve 35-40% electrical efficiency with exhaust temperatures supporting steam generation for industrial process heat. Monterrey steel and cement producers favor these systems for continuous baseload operations requiring 10-50 MW thermal output.
- Steam Turbine:Backpressure and extraction-condensing designs integrate with existing boiler infrastructure in paper and chemical facilities. Tijuana maquiladora complexes deploy these where process steam demand exceeds electric load requirements.
- Reciprocating Engine:Lean-burn natural gas and dual-fuel configurations dominate sub-5 MW commercial installations with fast-start capability for intermittent industrial loads.
- Fuel Cell:Solid oxide and molten carbonate systems achieve 60% electrical efficiency with premium heat-to-power ratios for data center and hospital applications in Guadalajara and Queretaro.
Most installed capacity flows through Gas Turbine systems. Expansion is steepest in Reciprocating Engine deployments for distributed commercial loads.
End User:
Volume concentration and margin structure diverge sharply between continuous-process industrial operators and thermally intermittent commercial facilities.
- Industrial:Steel, cement, food processing, and chemical manufacturers absorb megawatt-scale deployments seeking thermal baseload for energy-intensive operations. These facilities prioritize 15-20 year asset life and NOM emissions compliance for uninterrupted production.
- Commercial:Hotels, retail complexes, and office buildings favor sub-2 MW configurations with modular heat recovery for space conditioning and hot water. CRE permitting timelines compress project cycles for these smaller thermal loads.
- Residential:Micro-CHP systems below 50 kW serve high-end developments in Mexico City and Monterrey where grid reliability concerns drive backup power investment.
- Institutional:Universities, government facilities, and military installations require black-start capability and islanding resilience for critical operations.
Industrial facilities command the largest share of aggregate megawatt capacity. Commercial applications are expanding most quickly as behind-the-meter economics improve.
Deployment:
Ownership structure and operational risk allocation separate captive onsite installations from third-party district heating models.
- Onsite:Industrial owners retain operational control and fuel price exposure through self-supply contracts permitted under revised CRE frameworks. These configurations dominate northern Mexico manufacturing corridors.
- District Heating:Centralized thermal distribution networks serve multiple commercial or residential buildings through insulated piping infrastructure. Limited deployment exists in Mexico City and Monterrey urban cores.
- Cogeneration Plant:Dedicated facilities export electricity to CFE grid under independent power producer arrangements with parallel operation permits.
- Backup Power:Emergency-only configurations with limited annual operating hours serve reliability-critical operations in Baja California and Sonora grid-constrained zones.
Onsite deployment captures the majority of commissioned capacity. Cogeneration Plant configurations face the steepest expansion trajectory as energy reform enables grid export economics.
Fuel Type:
Supply security and price volatility exposure differentiate pipeline-dependent natural gas from distributed biogas alternatives.
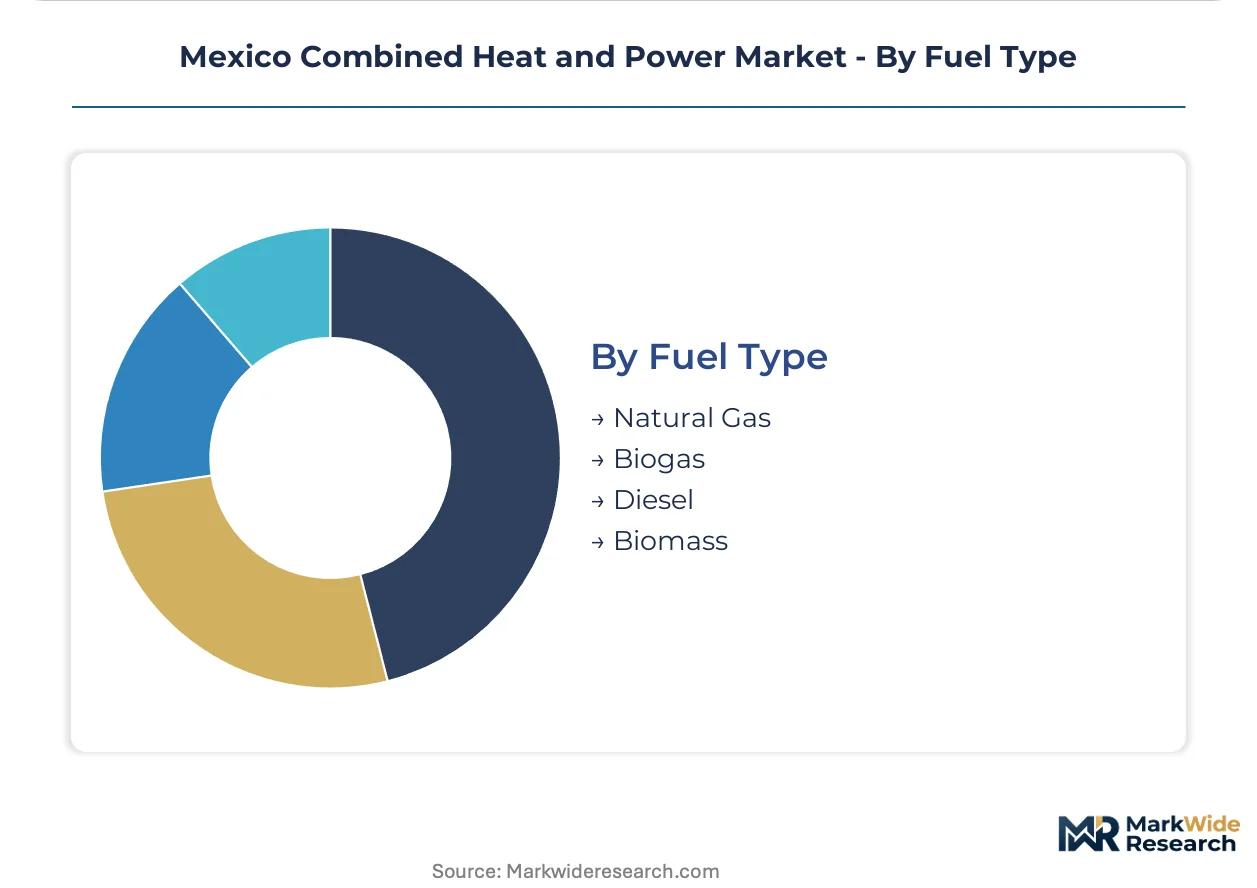
- Natural Gas:Pipeline deliveries from Texas and LNG terminal receipts supply 85% of operating CHP capacity. Henry Hub price transmission and CFE interruptible service contracts shape operating cost structures.
- Biogas:Agricultural waste digestion and landfill gas recovery qualify for NOM environmental credits under renewable dispatch rules. Jalisco tequila producers and Sinaloa livestock operations anchor project development.
- Diesel:Dual-fuel backup configurations and remote mining operations rely on liquid fuel security where pipeline infrastructure is absent.
- Biomass:Wood waste and agricultural residue combustion supports steam turbine installations in pulp and paper facilities with captive fuel supplies.
Natural Gas dominates current installed capacity. Biogas is gaining share fastest as NOM credit mechanisms improve project returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between state-level permitting efficiency and federal CRE compliance timelines is redirecting CHP investment toward sub-regions with streamlined environmental review processes. Project developers migrate toward jurisdictions where NOM certification timelines compress commissioning schedules. This geographic sorting concentrates capacity additions in northern industrial corridors and emerging southern zones with greenfield infrastructure advantages.
Nuevo León
Steel and cement manufacturers anchor megawatt-scale gas turbine deployments across the Monterrey metropolitan area. State environmental authorities coordinate with federal regulators to parallel-track NOM emissions certification and CRE generation permits. The Santa Catarina-Ramos Arizpe industrial corridor hosts the densest concentration of operating cogeneration capacity outside Mexico City.
Baja California
Maquiladora complexes and data center operators drive sub-5 MW reciprocating engine installations for thermal baseload and backup power resilience. CFE transmission interconnection queues extend 18-24 months for parallel operation permits, forcing developers toward captive onsite configurations. Tijuana and Mexicali manufacturing clusters absorb the majority of commercial-scale deployments in the region.
Jalisco
Tequila producers and livestock operations pioneer agricultural waste-to-energy biogas cogeneration qualifying for NOM environmental credits. The Guadalajara metropolitan area attracts hospital and university microturbine installations seeking black-start capability. CRE permitting timelines for sub-2 MW commercial projects run shorter here than in northern border states.
Yucatán Peninsula
Pemex refinery modernization and nearshoring manufacturing investment create greenfield CHP demand absent legacy grid infrastructure. Developers bypass CFE interconnection constraints entirely through dedicated island-mode installations. Mérida and surrounding industrial parks attract energy service companies offering performance contracting structures.
Mexico City Metro
High-end residential developments and institutional facilities drive micro-CHP adoption below 50 kW for grid reliability backup. District heating networks serve limited commercial concentrations in the urban core. Federal regulatory interpretation consistency varies between Mexico City and surrounding State of Mexico permitting layers.
Mexico Combined Heat and Power Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular microturbine and biogas specialization. The vendor base stratifies across three maturity tiers: multinational turbine manufacturers with integrated power island solutions, regional engineering constructors with project development capabilities, and specialized equipment distributors serving distributed commercial loads. Competitive positioning depends on CRE licensing support services and NOM compliance consulting rather than equipment differentiation alone. Market participants pursue strategic partnerships with energy service companies and geographic expansion into Yucatán greenfield zones.
Within the multinational turbine tier, General Electric Company and Siemens AG anchor large-scale industrial deployments with heavy-frame and aeroderivative configurations. Capstone Turbine Corporation occupies the distributed commercial specialization, serving sub-2 MW installations with integrated heat recovery modules. SENER Engineering Group represents the regional engineering constructor archetype, bridging equipment procurement and CRE permitting execution for Mexican industrial developers.
| Leading Market Players |
|---|
| Capstone Turbine Corporation |
| SENER Engineering Group |
| General Electric Company |
| ContourGlobal |
| PEMEX Cogeneration and Services |
| Santos CMI |
| MAN Energy Solutions |
| Comisión Federal de Electricidad |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Gas turbine combustion engineers concentrated in Nuevo León and trained under CFE legacy programs command wage premiums that widen pricing spreads between premium-tier integrated power island solutions and standardized reciprocating engine packages. Labor scarcity in specialized control system calibration and NOM emissions certification expertise concentrates cost advantages with established regional engineering constructors possessing captive technical workforces.
Pricing Analysis
Distributor margins on imported gas turbine components compress project-level returns for EPC contractors serving northern Mexico industrial corridors. Three-tier pricing structure across premium aeroderivative configurations, standard heavy-frame systems, and economy-grade reciprocating engines reflects certification tier differentiation and after-sales service bundling. Cost compression in sub-5 MW commercial segments intensifies as distributed solar-plus-battery alternatives capture price-sensitive hotel and retail buyers. Industrial steel and cement producers exhibit lowest price sensitivity due to continuous-process thermal baseload requirements and 15-20 year asset life calculations.
Supply Chain Analysis
Domestic-content mandates under Mexico's energy reform licensing framework reshape sourcing patterns for grid-connected generation above 10 MW. Equipment supply concentrates in the United States, Germany, and Japan for gas turbine power islands, control systems, and precision combustion components. Project development draws from specialized heat recovery steam generators, cybersecurity-certified control networks, and NOM-compliant emissions monitoring instrumentation. Single-source vulnerability in aeroderivative turbine blade casting creates procurement risk for time-sensitive commissioning schedules. Distribution runs through regional engineering constructors bridging multinational OEMs and Mexican industrial developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Mexico's CHP landscape rests on modular equipment standardization reducing field engineering hours and performance contracting structures capturing premium returns from operational risk assumption.
For Market Incumbents: Cement market position by deepening captive technician training pipelines to offset CFE-trained engineer retirement waves and securing long-term natural gas supply agreements insulating industrial customers from Henry Hub volatility. Backward integration into heat recovery steam generator fabrication reduces exposure to imported component lead time uncertainty. For New Entrants and Emerging Players: Capture white-space opportunity in Yucatán Peninsula greenfield zones where absent CFE grid infrastructure eliminates interconnection queue delays. Agricultural waste-to-energy biogas cogeneration in Jalisco and Sinaloa offers penetrable entry path with NOM environmental credit qualification. Partner with energy service companies to deploy performance contracting structures bypassing industrial capex constraints. For Investors and Strategic Acquirers: Energy service companies with CRE licensing execution capabilities and NOM compliance consulting expertise are the most active acquirer category in this space. Long-term viability centers on contracted revenue visibility from 10-15 year fixed-price thermal agreements with multinational manufacturing subsidiaries. Monitor CFE transmission interconnection queue clearance rates as inflection indicator for parallel operation permit economics.| Strategic Initiative | Industry Significance |
|---|---|
| Performance Contracting Expansion | Energy service companies assume operational risk through guaranteed savings structures, bypassing industrial capex constraints in Monterrey corridors. |
| Biogas Cogeneration Development | Agricultural waste-to-energy projects in Jalisco and Sinaloa qualify for NOM environmental credits under renewable dispatch rules. |
| Modular Microturbine Deployment | Integrated heat recovery packages below 2 MW serve Guadalajara hospitals and data centers seeking black-start resilience. |
| Cybersecurity Certification Investment | IEC 62443-compliant control networks become mandatory for grid-connected generation above 10 MW under CRE 2023 standards. |
| Yucatán Greenfield Expansion | Island-mode installations bypass CFE interconnection constraints entirely in Pemex refinery modernization zones. |
Research Methodology
Bottom-up industrial end-use modeling reconciled against top-down equipment supply tracking forms the analytical core of this study. Primary interviews with IPP project developers, EPC contractors, CFE interconnection planners, and fuel supply specialists combine with secondary validation from CRE licensing databases, NOM emissions certification records, and natural gas pipeline flow data. SEC filings of multinational turbine manufacturers and customs import records for power generation equipment provide supply-side triangulation.
Historical capacity addition trendlines and regulatory event sequencing inform projection framework construction across the analysis window. Segmentation dimensions modeled include fuel source, generation capacity tier, project ownership structure, and regional grid infrastructure maturity. CAGRs derive from equipment shipment tracking correlated with thermal load growth in named manufacturing corridors. Forecast inputs incorporate natural gas price scenario modeling and CRE permit approval velocity assumptions.
Natural gas price volatility, CRE regulatory interpretation shifts, and CFE transmission interconnection queue clearance delays are the dominant revision risks to projection assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Combined Cycle Power Plant Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Captive Power Generation Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Thermal Power Market
Power Generation
Solar Generator Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Shore Power Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Variable Speed Generator Market
Power Generation
Retail Electricity Market
Power Generation
Power Generation Technologies Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Iraq Power EPC Market