
 Dietary Fiber Gummies Market | 2026-2036
Dietary Fiber Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Dietary Fiber Gummies Market Analytics
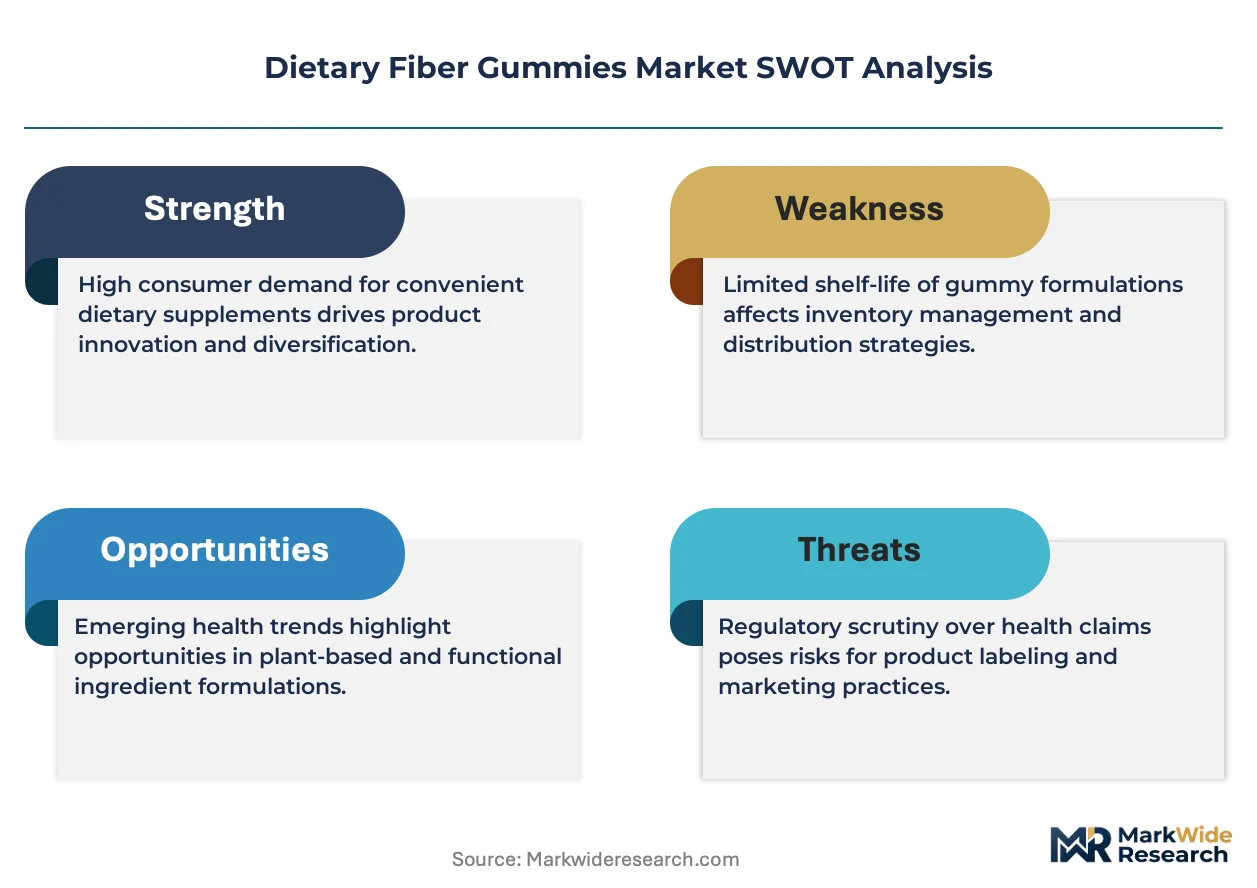
Asset-light contract manufacturing and white-label financing is rewriting competitive entry barriers in dietary fiber gummies. SMP Nutra leverages toll-manufacturing partnerships to extend production capacity without fixed-asset exposure. Nestlé S.A. anchors its position through captive R&D pipelines and direct-to-consumer channel control. NOW Foods competes on certified-organic sourcing and transparent supply-chain documentation.
Dietary fiber gummies are chewable confectionery matrices incorporating soluble and insoluble fiber sources such as inulin, psyllium husk, or polydextrose, typically dosed at two to four grams per serving to support digestive regularity and satiety signaling. The manufacturing process involves pectin or gelatin-based gelation, moisture-controlled starch molding, and protective coating to ensure shelf-stable fiber potency across ambient distribution. Sugar-Free Gummies and Functional Gummies lead margin pools as consumers trade up from basic regular formats toward clinically positioned, low-glycemic alternatives. Vegan Gummies represent the fastest-growing product type as plant-based pectin formulations displace conventional gelatin across European and North American retail sets. Health-Conscious Consumers drive volume expansion, while pediatric and senior end-user segments sustain premium pricing through condition-specific positioning.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements, mandating identity testing and contaminant screening that elevates compliance costs for new entrants. The EMA and national EU regulators apply novel food assessments to emerging fiber sources, creating asynchronous approval timelines that fragment product launch sequencing across Atlantic markets. FSSAI in India is tightening label-claim substantiation for functional foods, reshaping how brands position fiber content in emerging Asian retail channels. Stakeholders must monitor evolving fiber-source approval pathways and calibrate formulation pipelines to jurisdictions with the shortest regulatory clearance horizons.
Market Dynamics
Pediatric wellness programs in school nutrition settings are accelerating volume uptake among children, while FDA labeling mandates are compressing formulation flexibility and elevating compliance thresholds for new entrants.
Growth Catalysts
- Pediatric School Nutrition Integration:District-level wellness mandates in the United States are embedding fiber gummies into subsidized meal programs, creating institutional procurement pipelines that bypass retail margin erosion.
- FDA Labeling Stringency:Updated dietary supplement disclosure requirements are filtering out substandard competitors, concentrating shelf space among compliant manufacturers with verified fiber potency claims.
- Pectin Gelation Advances:Plant-based gelling technologies are enabling clean-label vegan formats that capture premium price points in California and New Jersey innovation clusters.
Market Restraints
- Inulin Price Volatility:Chicory root supply concentration in Belgium and the Netherlands exposes margin compression when weather events disrupt harvest cycles.
- EMA Novel Food Assessments:Asynchronous approval timelines for emerging fiber sources fragment product launch sequencing, delaying European market entry by 12-18 months relative to US clearance.
- Psyllium Husk Substitution:Whole-food fiber powders and fortified beverages compete on cost-per-serving metrics in price-sensitive household segments.
Strategic Opportunities
- FSSAI Label-Claim Reform:India's tightening substantiation standards for functional foods create first-mover advantage for brands with pre-validated fiber content documentation.
- Senior Condition-Specific Positioning:Satiety and glycemic management claims targeted at Medicare-adjacent demographics sustain premium pricing above pediatric equivalents.
- Direct-to-Consumer Subscription:Recurring revenue models bypass retail slotting fees and capture lifetime value through personalized dosing regimens.
Industry Challenges
- Moisture-Controlled Starch Molding Talent:Specialized confectionery process engineers command scarcity premiums, constraining capacity expansion timelines for contract manufacturers.
- Protective Coating Equipment Capex:Shelf-stability requirements demand precision coating lines that strain balance sheets for mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dietary Fiber Gummies Market |
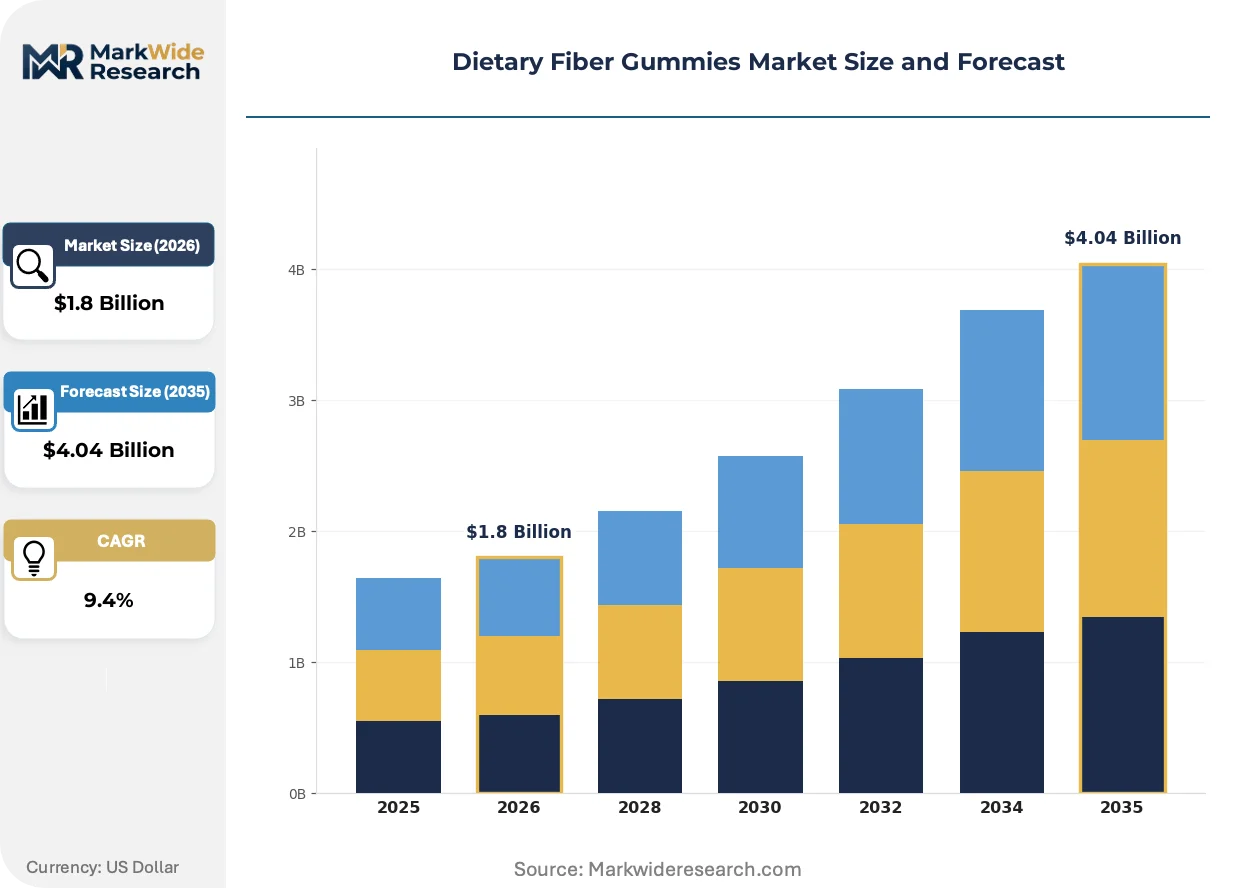
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegan Gummies, Sugar-Free Gummies, Regular Gummies, Functional Gummies End User: Children, Adults, Seniors, Health-Conscious Consumers Flavor: Fruit Flavors, Herbal Flavors, Chocolate, Others Packaging Type: Bottles, Pouches, Jars, Blister Packs |
| Companies Covered | Bayer AG, Makers Nutrition, Nestlé S.A., SMP Nutra, Gummi World, Unilever plc, NOW Foods, Vitaquest International, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dietary Fiber Gummies Market Evolving Landscape
Active migration from gelatin to pectin matrices, tightening purity mandates from Atlantic regulators, and channel disintermediation through subscription models are compressing legacy competitive advantages.
Pectin-based gelation systems are replacing conventional gelatin across North American and European retail sets. Health-conscious millennials and Gen Z buyers are rejecting animal-derived inputs at accelerating rates. The technology is migrating from niche vegan SKUs to mass-market standard formulations, collapsing the premium pricing differential that previously separated plant-based from conventional gummies.
REACH-compliant fiber sourcing documentation is becoming a non-negotiable entry ticket for EU distribution. EMA novel food assessments now require exhaustive toxicology dossiers for emerging prebiotic fibers like resistant dextrin. European brands are responding by front-loading regulatory investment and sequencing launches to prioritize jurisdictions with harmonized approval pathways.
Institutional procurement through school districts and corporate wellness programs is displacing individual retail purchases in volume terms. Third-party administrators and benefits platforms are aggregating demand and negotiating direct supply agreements. This concentration is most visible in United States employer-sponsored wellness initiatives, where fiber gummies are bundled with preventive health incentives.
Dietary Fiber Gummies Market Segmentation
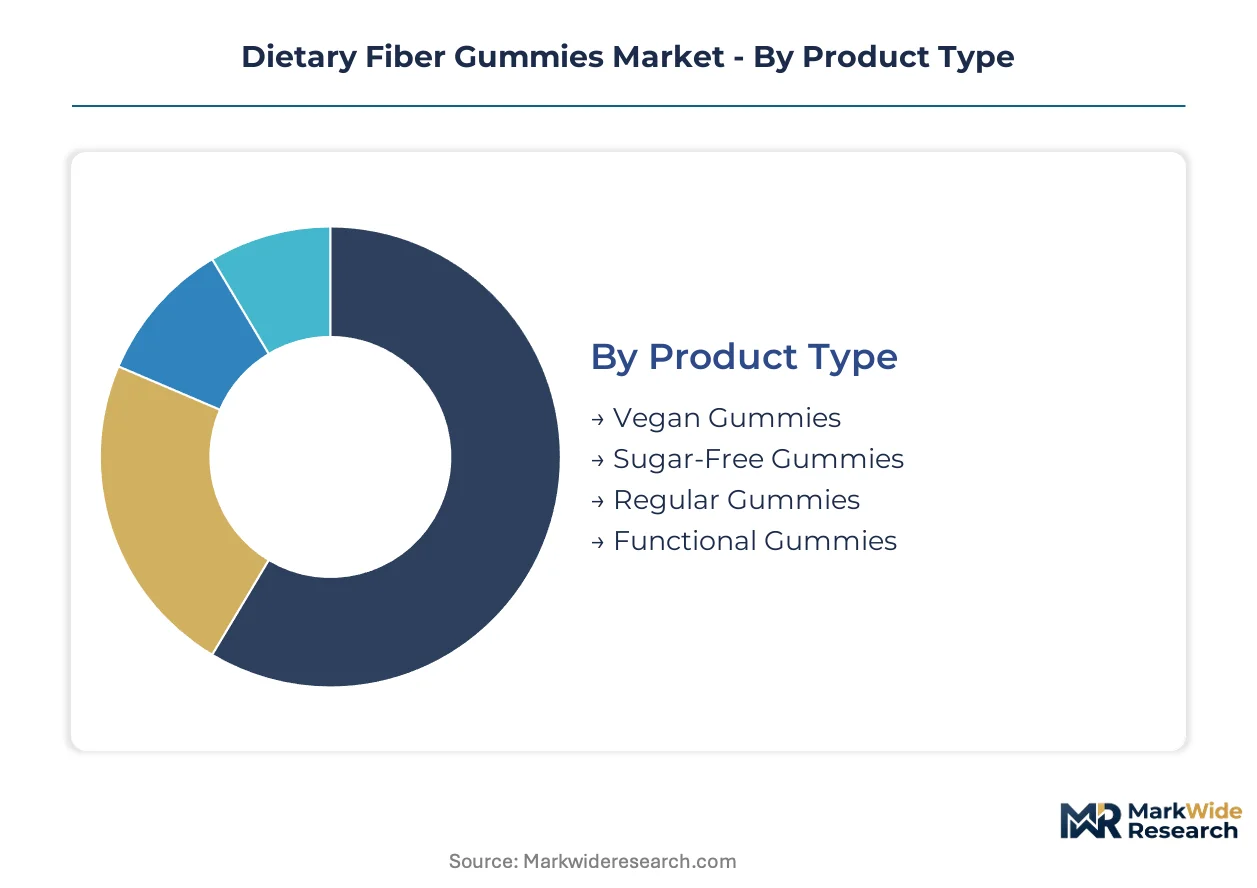
Dietary fiber gummies segment across four dimensions that determine manufacturing complexity, regulatory pathway, and channel strategy. Product type dictates gelation chemistry and certification requirements. End-user targeting shapes dosing protocols and claim substantiation. Flavor and packaging configurations influence retail velocity and replenishment cadence.
Product Type:
After-sales service intensity varies sharply across product types, with vegan and functional formats demanding technical support for shelf-stability troubleshooting that regular gummies rarely require.
- Sugar-Free Gummies:Polyol-sweetened matrices using maltitol or erythritol to achieve low-glycemic positioning without compromising texture. Demand concentrates in Medicare-adjacent senior segments across Florida and Arizona, where glycemic management claims drive reimbursement-adjacent purchasing.
- Functional Gummies:Clinically positioned formats incorporating added probiotics, prebiotics, or condition-specific actives beyond baseline fiber content. Pediatric wellness programs in Texas and California school districts are embedding these into institutional procurement pipelines.
- Vegan Gummies:Pectin-based gelation systems replacing conventional gelatin for plant-based positioning. European retailers in Germany and France are mandating vegan SKUs as standard rather than premium tier.
- Regular Gummies:Conventional gelatin-based formulations with basic fiber content claims. Price-sensitive household segments in India and Southeast Asia sustain volume despite margin compression.
Sugar-Free Gummies holds the largest share; momentum sits with Vegan Gummies.
End User:
Cost tier stratification runs deepest across end-user segments, with seniors commanding premium pricing that subsidizes value-engineered children's formats.
- Seniors:Condition-specific positioning around satiety signaling and glycemic management, with dosing regimens calibrated for polypharmacy contexts. Medicare-adjacent demographics in Pennsylvania and Ohio sustain pricing premiums above pediatric equivalents.
- Health-Conscious Consumers:Millennial and Gen Z buyers prioritizing clean-label certification and transparent supply-chain documentation. California and New Jersey innovation clusters serve this segment through direct-to-consumer subscription models.
- Children:Palatability-optimized formats with lower fiber doses per serving to ensure compliance. School nutrition programs in Illinois and Georgia are creating institutional demand bypassing retail margin structures.
- Adults:Mass-market positioning balancing convenience and efficacy for working-age demographics. Mass merchandisers in Texas and Florida drive volume through promotional bundling.
Seniors commands the highest margin tier; Health-Conscious Consumers are expanding most quickly.
Flavor:
Application context determines flavor selection, with fruit profiles dominating daily supplementation routines while herbal variants target condition-specific use cases.
- Fruit Flavors:Berry, citrus, and tropical profiles masking fiber aftertaste in daily-use formats. Retail velocity in United States mass channels favors strawberry and mixed berry SKUs.
- Herbal Flavors:Ginger, turmeric, and botanical infusions aligning with Ayurvedic and traditional medicine positioning. Indian and Southeast Asian markets show concentration for these variants.
- Chocolate:Indulgence-positioned formats competing with confectionery rather than supplement aisle placement. Premium European retailers in Switzerland and Belgium stock these as lifestyle products.
- Others:Unflavored or neutral profiles for stacking with other supplements. Clinical settings in Germany and Netherlands prefer these for protocol flexibility.
Fruit Flavors holds the largest share; momentum sits with Herbal Flavors.
Packaging Type:
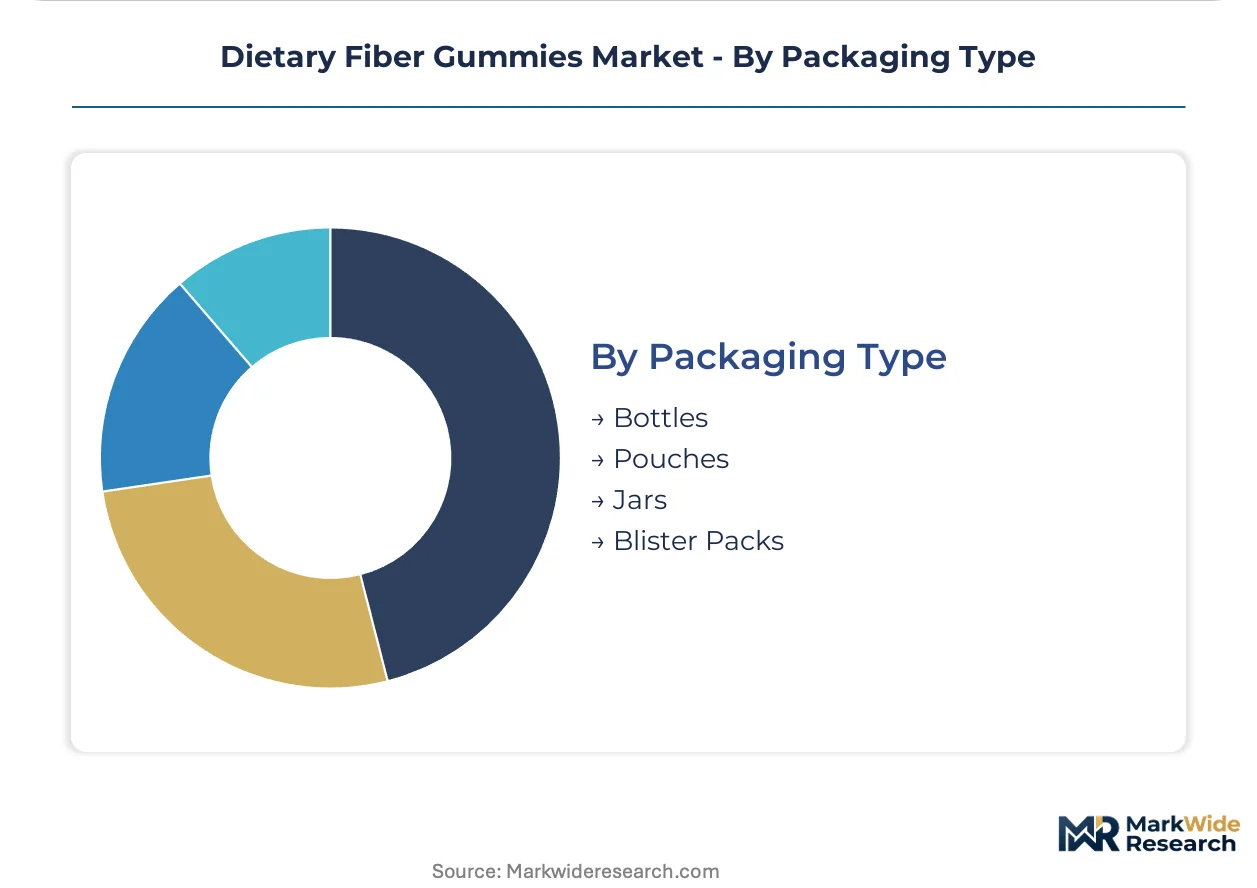
Customer type and purchase occasion shape packaging selection, with subscription channels favoring pouches while retail pharmacy demands bottle formats with child-resistant closures.
- Bottles:Rigid PET or HDPE containers with desiccant inserts for shelf-stability in humid climates. United States pharmacy and mass retail channels require this format for merchandising compatibility.
- Pouches:Flexible film structures reducing shipping cube and enabling direct-to-consumer subscription economics. California-based wellness brands are migrating volume to this format.
- Jars:Wide-mouth glass or plastic containers for bulk formats and family sizing. Club retailers in Texas and Florida favor these for value positioning.
- Blister Packs:Unit-dose aluminum-PVC configurations for clinical trial supplies and travel formats. European pharmaceutical channels in Germany and France specify these for compliance packaging.
Bottles holds the largest share; Pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious millennials and Gen Z buyers concentrate in coastal United States innovation clusters, while pediatric procurement programs and senior wellness demographics distribute demand across distinct metropolitan corridors.
United States
Pediatric wellness programs in Texas and California school districts drive institutional volume, while Medicare-adjacent seniors in Florida and Arizona sustain premium pricing for glycemic management formats. FDA labeling stringency filters substandard competitors and concentrates shelf space among verified manufacturers. Functional confectionery innovation clusters in California and New Jersey host pectin gelation advances and direct-to-consumer subscription economics.
Germany
European retailers in Germany mandate vegan SKUs as standard rather than premium tier, accelerating pectin-based gelation adoption across mass-market formulations. EMA novel food assessments require exhaustive toxicology dossiers for emerging prebiotic fibers, front-loading regulatory investment for brands seeking EU distribution. REACH-compliant fiber sourcing documentation anchors supply-chain verification protocols in Frankfurt and Hamburg distribution hubs.
India
FSSAI label-claim reform creates first-mover advantage for brands with pre-validated fiber content documentation in emerging retail channels. Pediatric palatability-optimized formats find traction in Maharashtra and Karnataka urban centers where nuclear households prioritize convenience. Ayurvedic and traditional medicine positioning drives herbal flavor variants in Delhi-NCR and Gujarat wellness markets.
United Kingdom
Millennial and Gen Z buyers in London and Southeast England prioritize clean-label certification and transparent supply-chain documentation for subscription-based purchasing. EMA asynchronous approval timelines delay European market entry relative to US clearance, reshaping launch sequencing for UK-based brands. Clinical trial supplies and travel formats in blister packaging concentrate in Cambridge and Oxford pharmaceutical corridors.
Netherlands
Inulin supply concentration in Belgium and the Netherlands exposes margin compression when weather events disrupt chicory root harvest cycles. EMA novel food assessments fragment product launch sequencing, with Amsterdam and Rotterdam serving as regulatory intelligence hubs for Atlantic market entry. Plant-based pectin formulations displace conventional gelatin across Dutch retail sets ahead of broader European adoption.
Dietary Fiber Gummies Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Large multinational conglomerates leverage captive R&D pipelines and direct-to-consumer platforms to defend margin positions. Asset-light contract manufacturers exploit toll-manufacturing partnerships to extend capacity without fixed-asset exposure. Certified-organic specialists compete on transparent supply-chain documentation and third-party verification. Dominant competitive moves include strategic partnerships for regulatory navigation and portfolio diversification into condition-specific positioning.
Within the multinational conglomerate tier, Bayer AG and Nestlé S.A. occupy positions anchored by pharmaceutical and nutrition heritage. Among asset-light contract manufacturers, SMP Nutra exemplifies toll-manufacturing scalability. Certified-organic specialists include NOW Foods, which sits within the transparent sourcing archetype. These three company types collectively represent the competitive vectors reshaping entry barriers and margin pools.
| Leading Market Players |
|---|
| Bayer AG |
| Makers Nutrition |
| Nestlé S.A. |
| SMP Nutra |
| Gummi World |
| Unilever plc |
| NOW Foods |
| Vitaquest International |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
Undercapacity in European pectin extraction facilities is compressing contract manufacturer margins while amplifying pricing power for integrated gelation technology holders in California and New Jersey innovation clusters.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA-grade cGMP compliance commanding 15-25% uplifts over basic food-grade positioning. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status, third-party potency verification, and direct-to-consumer subscription bundling. Cost compression in economy-tier regular gummies is intensifying because Indian and Southeast Asian contract manufacturers are absorbing chicory root price spikes to retain volume share. Health-conscious consumers in subscription channels show least price sensitivity, while price-sensitive household segments in mass retail drive promotional dependency.
Supply Chain Analysis
Tariff exposure between Belgium and the United States dominates margin risk planning for inulin-dependent formulations. Chicory root supply concentrates in Belgium and the Netherlands, with psyllium husk sourcing anchored in India and pectin extraction centered in Mexico and Brazil. Raw material dependencies include chicory root inulin, citrus peel pectin, and maltitol sweeteners. Single-source vulnerability in Belgian inulin processing creates 12-18 month hedge requirements. Distribution runs through institutional procurement pipelines in United States school districts, direct-to-consumer subscription fulfillment centers, and European pharmaceutical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from regulatory compliance investment cycles, with FDA labeling stringency and EMA novel food assessments now filtering out substandard competitors and concentrating returns among verified manufacturers.
For Market Incumbents: Build regulatory dossier depth as the primary moat by front-loading EMA toxicology investment for emerging prebiotic fibers and securing REACH-compliant fiber sourcing documentation ahead of EU distribution mandates. Threat from asset-light toll-manufacturers like SMP Nutra demands captive R&D pipeline acceleration in pectin gelation advances. Channel control through direct-to-consumer subscription platforms defends margin position against retail slotting fee erosion.
For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI label-claim reform window by pre-validating fiber content documentation for emerging retail channels. White-space concentration sits with senior condition-specific positioning in Medicare-adjacent demographics, where satiety and glycemic management claims sustain premium pricing above pediatric equivalents. Go-to-market angle should leverage toll-manufacturing partnerships to bypass protective coating equipment capex barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription archetypes with personalized dosing regimens, suggesting long-term viability concentrates in platform-enabled brands over transactional retail-dependent competitors. Acquisition target archetype: certified-organic specialists with transparent supply-chain documentation and existing FDA cGMP infrastructure. Signal to watch is EMA novel food assessment clearance velocity as inflection indicator for European market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Pectin Gelation Technology Licensing | Plant-based pectin formulations displace conventional gelatin across European retail sets ahead of mass-market adoption. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass retail slotting fees and capture lifetime value through personalized dosing regimens. |
| EMA Novel Food Dossier Investment | Front-loaded regulatory investment enables asynchronous launch sequencing prioritizing shortest clearance horizons. |
| Institutional Procurement Partnership | School district wellness mandates create volume pipelines that bypass retail margin erosion in United States markets. |
| Certified-Organic Supply Certification | Transparent supply-chain documentation defends positioning against NOW Foods and other third-party verification competitors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with contract manufacturing executives, regulatory affairs specialists at FDA and EMA, school district procurement directors, and direct-to-consumer brand operators; and secondary validation through FDA cGMP inspection databases, EMA novel food assessment registers, FSSAI label-claim notifications, and Nielsen retail audit data. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against institutional procurement disclosures anchored forecast integrity.
Forecast inputs span product type segmentation by gelation chemistry, end-user targeting by age demographic and condition specificity, flavor and packaging configuration by channel economics, and regional regulatory pathway differentiation. CAGRs were derived from installed base expansion modeling and replacement cycle analysis across the projection horizon. Industry-specific inputs include pediatric school nutrition program adoption curves and senior Medicare-adjacent purchasing propensity indices.
Sensitivities concentrate around EMA novel food assessment timeline delays, chicory root harvest volatility in Belgium and the Netherlands, and FSSAI enforcement intensity in Indian retail channels. Forecasts reflect assumptions about regulatory clearance velocity and fiber-source approval pathway convergence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
Bovine Lactoferrin Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market