
 Omega 3 Market | 2026-2036
Omega 3 Market Size, Share, and Industry Trends Forecast 2026-2036
Omega 3 Market Intelligence
The industry-wide push for sustainable sourcing of marine ingredients is recalibrating supply chain priorities and raw material selection. This shift favors suppliers with documented sustainable harvesting practices. Aker BioMarine positions itself with certified Antarctic krill harvesting, which appeals to environmentally conscious consumers. Pelagia AS leverages its large-scale fish processing infrastructure to supply traceable fish oil derivatives. Meanwhile, BASF SE competes by offering a diversified portfolio that includes both marine and alternative algal-based omega-3 sources.
Omega-3s are polyunsaturated fatty acids, primarily eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA), essential for human health. These compounds are integral to cell membrane structure and function, particularly in the brain and eyes. While fish oil remains the dominant product type by volume, algal oil represents the fastest-growing segment due to vegan, vegetarian, and sustainability preferences. Among end users, dietary supplement manufacturers constitute the largest buyer group, procuring bulk oils for encapsulation into softgels and capsules for retail distribution.
Regulatory frameworks dictate market access and product claims, creating a complex compliance environment. The U.S. FDA sets guidelines for qualified health claims on supplements, while the European Food Safety Authority (EFSA) enforces stringent criteria for novel food approvals and health claim substantiation. In China, the National Medical Products Administration (NMPA) governs the registration process for health food products. Future success hinges on navigating these disparate regional regulations while managing the volatility of marine raw material supply.
Market Dynamics
The market's structure is defined by the dual pressures of sustainable sourcing mandates for marine ingredients and the scientific validation required for health claims. This dynamic pits traditional fish oil suppliers against innovators in algal and other alternative omega-3 sources, reshaping supply chain priorities and product development.
Growth Catalysts
- Health Claim Regulations:Stricter validation frameworks, such as those from the European Food Safety Authority (EFSA), compel manufacturers to invest in clinical research, boosting demand for high-purity, scientifically substantiated omega-3 ingredients for dietary supplements.
- Infant Nutrition Segment:The fortification of infant formula with DHA to support cognitive and visual development is a significant catalyst. This demand is non-discretionary in many markets, creating a stable, high-value procurement channel for ingredient suppliers.
- Plant-Based Diets:The consumer shift towards vegan and vegetarian lifestyles is accelerating adoption of algal-based omega-3s. This trend opens new product development pathways for food and beverage fortification beyond traditional supplements.
Market Restraints
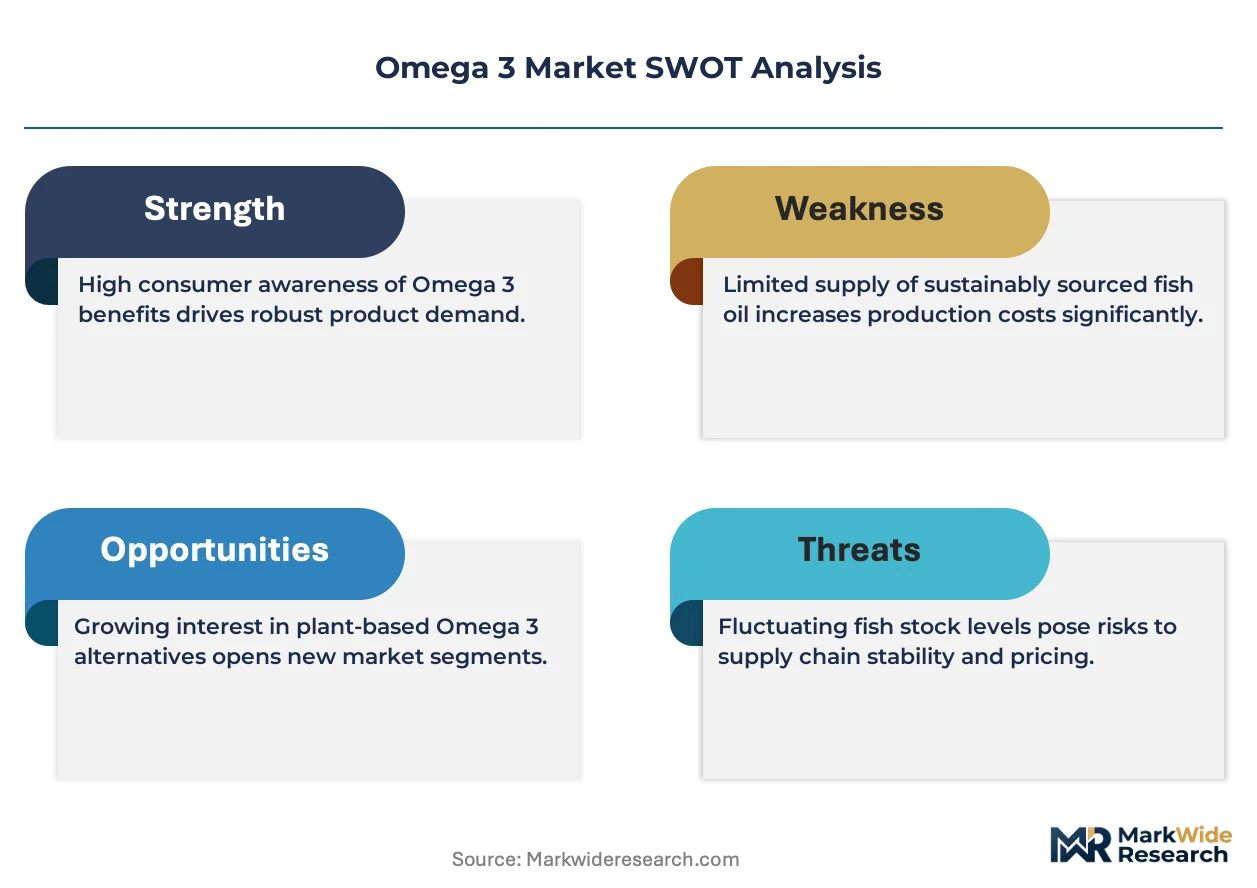
- Marine Raw Material Volatility:The supply of fish oil is subject to fluctuations in wild fish catch quotas and climate-related events, particularly affecting anchovy fisheries in Peru. This creates unpredictable input costs for refiners and manufacturers.
- Alternative Fatty Acids:The promotion of other healthy fats, such as omega-6 and omega-9 from plant sources like flaxseed or olive oil, can confuse consumers and potentially substitute for omega-3 purchases in less-informed segments.
- Novel Food Approval Hurdles:Gaining market access for new omega-3 sources, such as genetically modified algae, involves lengthy and costly novel food approval processes under bodies like the EFSA, slowing innovation.
Strategic Opportunities
- Pharmaceutical Grade EPA/DHA:Developing high-concentration EPA and DHA formulations for prescription drug applications targeting cardiovascular and inflammatory conditions represents a significant value-add opportunity. This moves beyond the dietary supplement space into regulated therapeutics.
- Southeast Asian Markets:Rising disposable incomes and health awareness in countries like Indonesia and Vietnam present an opportunity for market entry. Formulating products tailored to local dietary habits and distribution channels is critical for success.
- Microencapsulation Technology:Applying advanced microencapsulation allows for the incorporation of omega-3s into functional foods and beverages without affecting taste or smell. This opens up applications in dairy, baked goods, and juices.
Industry Challenges
- Supply Chain Traceability:Meeting the documentation and audit requirements for sustainability certifications like the Marine Stewardship Council (MSC) is a significant operational burden. This challenge is particularly acute for smaller suppliers lacking dedicated compliance teams.
- Oxidation and Stability:Preventing the oxidation of polyunsaturated fatty acids during processing and storage is a constant technical challenge. Failure to manage stability leads to rancidity, off-flavors, and reduced product efficacy, requiring specialized handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega 3 Market |
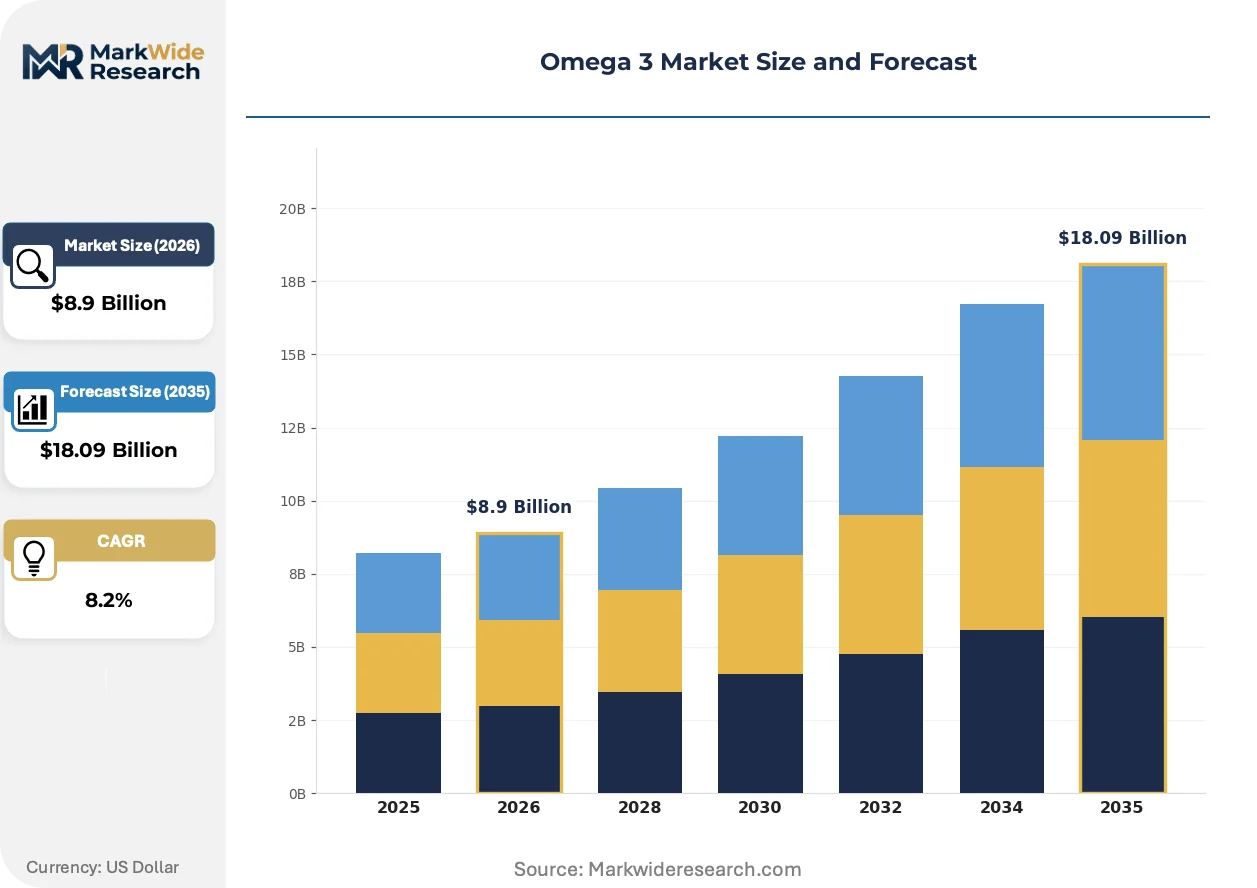
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $18.09 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Krill Oil, Algal Oil, Cod Liver Oil Form: Softgels, Liquid, Powder, Capsules Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Food Stores End User: Individuals, Athletes, Healthcare Practitioners, Dietary Supplement Manufacturers |
| Companies Covered | ADM, Aker BioMarine, BASF SE, Pelagia AS, Croda International PLC, Cargill, Incorporated, Kerry Group plc, Corbion, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega 3 Market Strategic Shifts & Innovations
The market is evolving from a commodity-driven model to one centered on application-specific, high-purity ingredients. This transition is driven by technological advancements in extraction and a deeper scientific understanding of EPA and DHA's distinct biological roles.
Algal fermentation technology allows for the production of DHA and EPA in controlled, land-based bioreactors, independent of marine ecosystems. Dietary supplement and infant formula manufacturers are increasingly adopting these algal oils to meet vegan and sustainability demands. This innovation is decentralizing the omega-3 supply chain, reducing reliance on geographically concentrated and volatile wild fish stocks.
Qualified health claims approved by the U.S. Food and Drug Administration (FDA) link EPA and DHA consumption to reduced risk of hypertension and coronary heart disease. These regulatory green lights provide manufacturers with powerful marketing tools to substantiate product benefits directly on packaging. The dietary supplement segment is most affected, using these approved claims to differentiate products and justify premium price points.
Consumer demand is shifting towards personalized nutrition, with individuals seeking omega-3 products tailored to specific life stages or health goals. This disrupts the one-size-fits-all supplement model, favoring brands that offer targeted formulations, such as high-EPA for mood support or high-DHA for cognitive function. This trend is most visible in developed markets like the United States and Germany, where direct-to-consumer services are gaining traction.
Omega 3 Market Segmentation
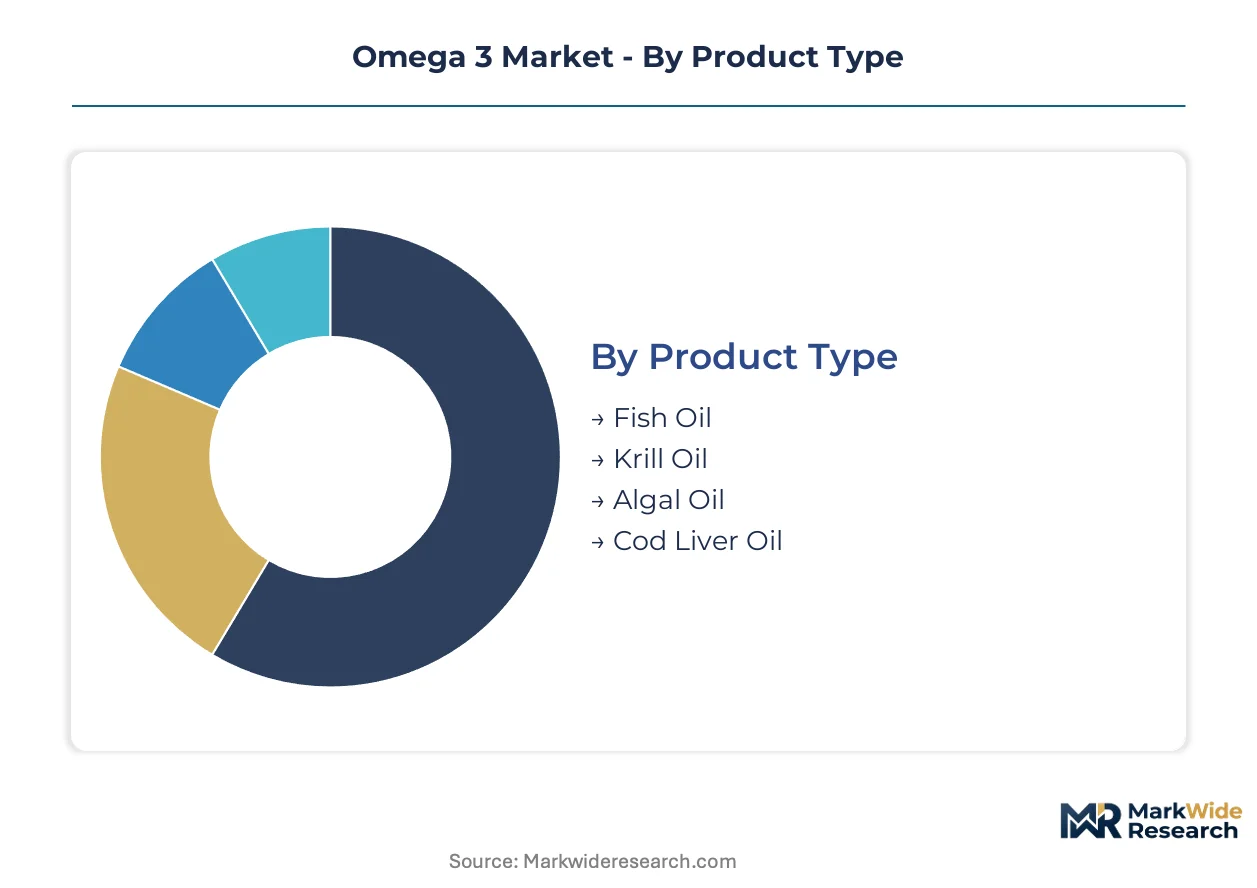
The segmentation of the omega-3 market is critical for understanding the varied demands and supply dynamics that shape product development and market access. Each segment reflects distinct consumer needs, technological applications, and distribution pathways, influencing strategic investments across the value chain.
Product Type:
The diverse product types within the omega-3 market reflect a spectrum from standardized commodity ingredients to highly specialized, application-specific formulations.
- Fish Oil:Fish oil, primarily sourced from cold-water fatty fish like anchovies and mackerel, contains both eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA) in varying ratios. Demand concentrates within the global dietary supplement sector, driven by established consumer recognition for cardiovascular health benefits.
- Algal Oil:Algal oil is derived from microalgae through fermentation, offering a plant-based source of DHA, and increasingly EPA. Demand is rapidly expanding among vegan and vegetarian consumers, particularly in developed markets like the United States, due to ethical and sustainability preferences.
- Krill Oil:Krill oil, extracted from Antarctic krill, provides EPA and DHA in phospholipid form, enhancing bioavailability. This product type targets consumers seeking premium, sustainably sourced marine omega-3s.
- Cod Liver Oil:Cod liver oil, derived from cod livers, offers a natural source of EPA, DHA, and Vitamin A and D. This traditional supplement maintains a steady consumer base, particularly in Northern European markets.
Most installed capacity flows through Fish Oil. Expansion is steepest in Algal Oil.
Form:
The physical forms of omega-3 products cater to varied consumer preferences regarding ease of consumption and dosage delivery.
- Softgels:Softgels encapsulate liquid omega-3 oils within a gelatin or plant-based shell, providing a convenient and taste-neutral delivery method. Consumer preference for discreet, easy-to-swallow formats drives demand, especially in the over-the-counter supplement aisle.
- Capsules:Capsules, typically hard-shelled, contain omega-3 oils often in powder or beadlet form, allowing for precise dosing and combination with other active ingredients. Pharmaceutical applications frequently utilize this form for controlled release and stability.
- Liquid:Liquid omega-3s offer dosage flexibility and are often favored for children or individuals with swallowing difficulties. This form is popular in family-sized bottles and flavored options.
- Powder:Powdered omega-3s, often microencapsulated, enable fortification of functional foods and beverages without taste interference. Food manufacturers increasingly integrate this form into dairy and baked goods.
The dietary supplement sector predominantly utilizes softgels and capsules. Innovation in microencapsulation is driving growth in powdered formats for food fortification.
Distribution Channel:
The channels through which omega-3 products reach consumers reflect diverse purchasing habits and brand positioning strategies.
- Online Retail:Online retail platforms offer extensive product selections, competitive pricing, and direct-to-consumer convenience for omega-3 supplements. This channel experiences significant expansion, particularly among digitally native consumers seeking detailed product information and reviews.
- Pharmacies:Pharmacies serve as trusted points of sale for omega-3 products, leveraging professional advice from pharmacists and perceived quality assurance. Consumers often purchase higher-purity or specialized formulations from these establishments, especially for health-specific needs.
- Supermarkets:Supermarkets provide broad accessibility to mass-market omega-3 brands, appealing to convenience-oriented shoppers. These stores focus on competitive pricing and widespread availability.
- Health Food Stores:Health food stores cater to consumers prioritizing natural, organic, and specialty omega-3 products. This channel emphasizes product transparency and ethical sourcing.
Digital platforms are rapidly gaining market share. Traditional brick-and-mortar outlets maintain their importance through localized accessibility and expert consultation.
End User:
Omega-3 products target a broad array of end-users, each with distinct needs and procurement patterns.
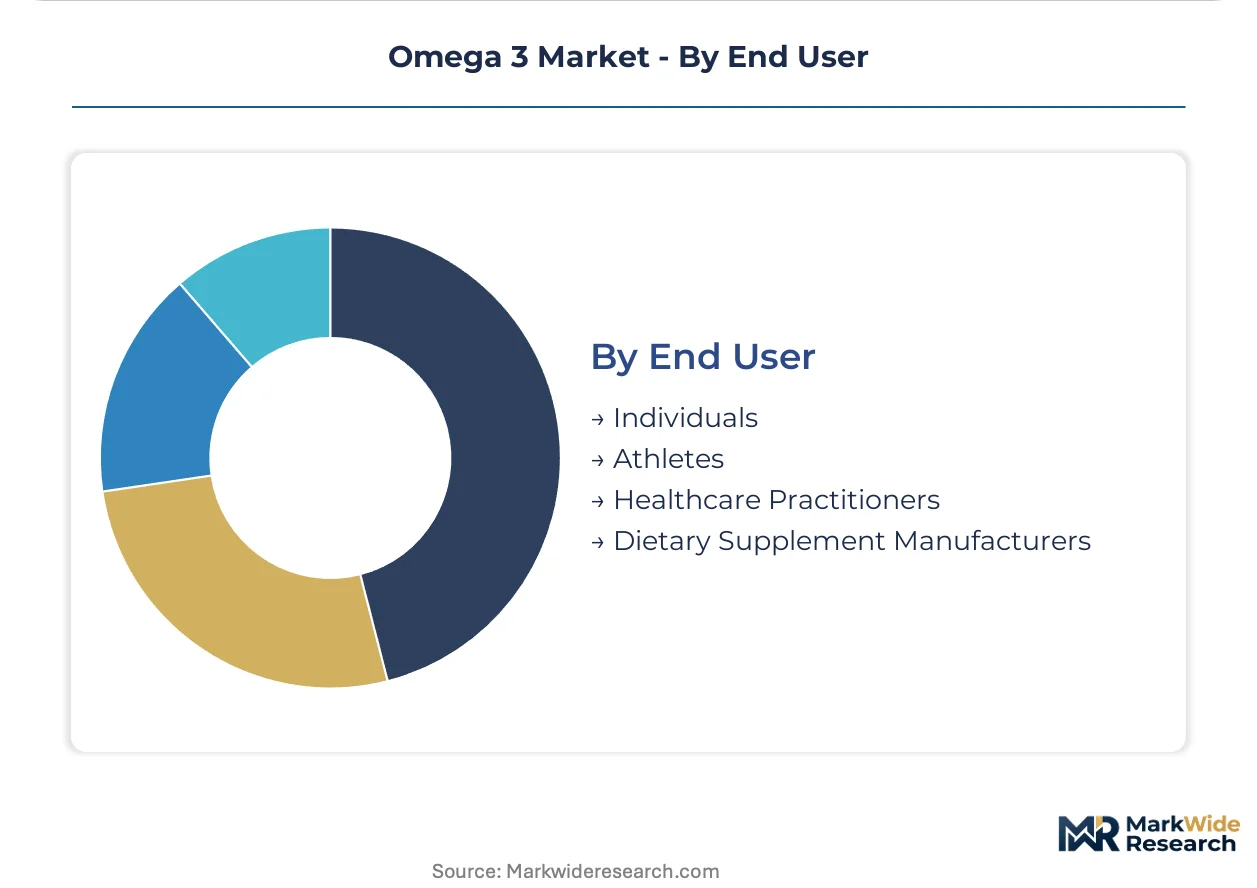
- Dietary Supplement Manufacturers:Dietary supplement manufacturers constitute the largest buyer group, procuring bulk omega-3 oils for encapsulation into consumer-ready softgels and capsules. Their demand is driven by the need for high-purity ingredients to meet retail distribution requirements and health claim substantiation.
- Individuals:Individuals represent the ultimate consumers of omega-3 products, purchasing supplements for general wellness, cognitive support, and cardiovascular health. Consumer health awareness and disposable income in developed markets significantly influence purchase decisions.
- Athletes:Athletes utilize omega-3s for anti-inflammatory benefits and recovery support, often seeking high-EPA formulations. Sports nutrition brands specifically target this performance-oriented segment.
- Healthcare Practitioners:Healthcare practitioners, including doctors and nutritionists, recommend specific omega-3 formulations for therapeutic applications or targeted health interventions. Their influence guides patient choices towards clinically validated products.
Ingredient suppliers primarily serve dietary supplement manufacturers. Consumer-facing brands directly engage individual buyers through various retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly educated workforce and advanced research infrastructure anchor demand for omega-3 products across developed markets. Consumer health awareness drives significant uptake of dietary supplements and functional foods. The market benefits from sophisticated regulatory environments that ensure product quality and efficacy.
United States
High consumer health awareness and significant disposable income drive demand for omega-3 supplements in the United States. The U.S. FDA sets guidelines for qualified health claims, influencing product differentiation. California's nutraceutical sector actively develops targeted formulations for specific health goals.
Germany
Germany exhibits strong demand for high-purity omega-3s, driven by an aging population and a preference for natural health solutions. The European Food Safety Authority (EFSA) enforces strict criteria for health claim substantiation. Hamburg's food processing industry integrates microencapsulated omega-3s into functional dairy products.
Japan
Japanese consumers prioritize omega-3 intake, influenced by a traditional fish-rich diet and a focus on cognitive health. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates health foods, ensuring product safety and efficacy. Osaka's food ingredient suppliers develop advanced encapsulation technologies for functional foods.
China
China's market for omega-3s expands with rising disposable incomes and a focus on infant nutrition. The National Medical Products Administration (NMPA) governs the registration process for health food products. Shanghai's rapidly expanding infant formula market drives procurement of high-DHA algal oils.
India
India's omega-3 market sees growth from increasing health awareness and the prevalence of lifestyle diseases. The Food Safety and Standards Authority of India (FSSAI) sets standards for food supplements. Bengaluru's growing nutraceutical sector focuses on affordable, high-volume omega-3 formulations.
Omega 3 Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the omega-3 market, creating a dynamic competitive environment. The industry exhibits a tiered structure, from large-scale marine ingredient suppliers to specialized formulators focusing on end-user products. Archetypes include marine oil giants leveraging vast harvesting and refining capabilities, biotechnology innovators developing alternative algal sources, and diversified nutrition companies offering broad portfolios. Strategic partnerships for novel ingredient development and portfolio diversification into higher-value applications are common competitive moves.
Specialists in marine sourcing, Aker BioMarine and Pelagia AS, exemplify companies leveraging established supply chains for fish and krill oil derivatives. Aker BioMarine anchors its position with certified Antarctic krill harvesting practices, appealing to environmentally conscious consumers. Pelagia AS focuses on large-scale fish processing infrastructure to supply traceable fish oil derivatives to the global market. Meanwhile, BASF SE represents a diversified portfolio approach, offering both marine and alternative algal-based omega-3 sources to various end-user segments. These companies collectively illustrate the spectrum of sourcing and product development strategies within the omega-3 industry.
| Leading Market Players |
|---|
| ADM |
| Aker BioMarine |
| BASF SE |
| Pelagia AS |
| Croda International PLC |
| Cargill, Incorporated |
| Kerry Group plc |
| Corbion |
| DSM-Firmenich |
| Others |
Cost & Logistics Intelligence
Captive supply arrangements for marine raw materials anchor both the supply position and pricing power for large integrated omega-3 producers. These arrangements provide stability against fluctuating wild fish catch quotas and climate-related events affecting key fisheries.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for high-purity omega-3 ingredients, especially for pharmaceutical and infant nutrition applications. Price differentiation stems from the EPA/DHA concentration, purity grade, and specific sustainability certifications like MSC. Pricing pressure stems from the volatility of marine raw material supply, particularly anchovy fisheries in Peru. Dietary supplement manufacturers procuring bulk oils are generally more price-sensitive than specialized infant formula producers.
Supply Chain Analysis
Dual-sourcing requirements for critical omega-3 ingredients often mandate multi-supplier qualification to mitigate risk and ensure continuity. Geographic supply concentrates in Peru for anchovy-derived fish oil, and increasingly in China for algal oil production. The supply chain relies heavily on raw material inputs like anchovies, krill, and cultivated microalgae. A structural supply chain risk involves commodity price volatility for marine ingredients. Distribution runs through direct sales to manufacturers for bulk ingredients, and via online retail and pharmacies for finished consumer products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The omega-3 market presents a margin-expansion story, driven by the premiumization of scientifically substantiated and specialized formulations.
For Market Incumbents: Deploy vertical integration to secure raw material supply, particularly for marine-based omega-3s. Invest in advanced extraction and purification technologies to produce high-concentration EPA/DHA, countering the threat from alternative fatty acids. Secure long-term supply contracts with sustainable fishing operations, leveraging certifications like MSC to differentiate products in environmentally conscious markets.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce platforms offer a viable entry point for niche omega-3 products. Target the growing personalized nutrition segment with tailored formulations, such as high-EPA for mood support or high-DHA for cognitive function. Emphasize novel algal sources and transparent sourcing to appeal to vegan and sustainability-focused consumers, especially in developed markets like the United States.
For Investors and Strategic Acquirers: Roll-up economics work for ingredient specialists because of the fragmented supply of high-purity, application-specific omega-3s. Focus on acquiring companies with proprietary algal fermentation technology or advanced microencapsulation capabilities. The long-term viability favors intellectual property in extraction and formulation. Increased M&A activity among alternative omega-3 producers signals an inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Algal Fermentation Scale-Up | Decentralizes omega-3 supply from marine ecosystems, reducing reliance on volatile wild fish stocks. |
| Microencapsulation Technology Investment | Enables seamless incorporation of omega-3s into functional foods and beverages without taste impact. |
| Clinical Trial Investment | Substantiates specific health claims, crucial for regulatory approval and premium product positioning. |
| Sustainable Sourcing Certification | Appeals to environmentally conscious consumers and meets evolving industry mandates for traceability. |
| High-Purity EPA/DHA Formulation | Targets pharmaceutical applications for cardiovascular and inflammatory conditions, moving beyond supplements. |
Research Approach
Direct dialogue with dietary supplement manufacturers, ingredient suppliers, regulatory affairs specialists, and nutraceutical R&D directors informed the qualitative assessment. This primary research was validated against secondary sources including EFSA guidance documents, FDA qualified health claims, NMPA health food registrations, and leading industry association reports. A robust bottom-up and top-down triangulation approach ensured data consistency.
Bottom-up analysis of demand across product types, forms, distribution channels, and end-users was cross-referenced with top-down market sizing over the projection horizon. Segmentation dimensions modeled included EPA:DHA ratios and specific application areas like infant nutrition. Compound annual growth rates were derived from historical growth trends and projected adoption rates of new technologies. Key forecast inputs included raw material availability forecasts and regulatory approval timelines for novel ingredients.
The model assumes a particular technology adoption path; alternative pathways for algal oil production would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and consumer health awareness. Deviation in marine raw material supply or shifts in novel food approval processes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Global Algal DHA and ARA Market