
 Chewable Coffee Market | 2026-2036
Chewable Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Chewable Coffee Market Analytics
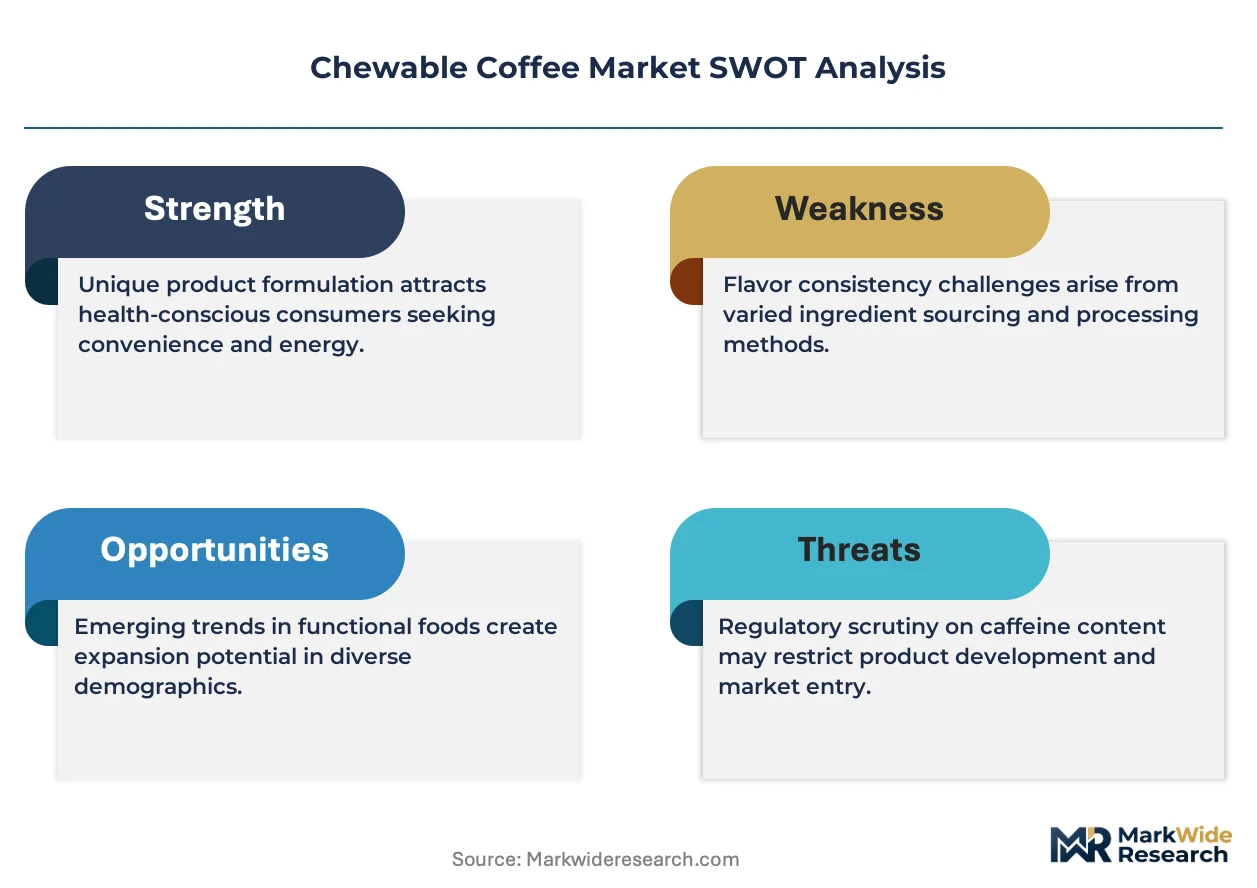
Premium functional-grade formulations is reorganizing competitive dynamics in chewable coffee. Viter Energy leverages its early-mover positioning in energy-focused gummy formats to sustain shelf presence across convenience channels. HVMN differentiates through nootropic-infused positioning that anchors its appeal among cognitive-performance seekers. Verb Energy competes via clean-label ingredient sourcing that dominates the athlete and wellness-adjacent segments.
Chewable coffee comprises compressed or gummy matrices containing spray-dried coffee extract, typically dosed at 50–100 mg caffeine per piece with binding agents such as pectin or gelatin. These products deliver portable, no-brew caffeine intake for commuters, shift workers, and travelers. The functional product type segment captures the deepest margin pools as adaptogen and nootropic fortification commands price premiums. Online retail channels represent the fastest-growing distribution pathway, though supermarkets still occupy the highest absolute volume for impulse-driven trial. Flavored variants lead packaging innovation, with single-serve blister packs gaining traction in gym and airport vending placements.
The FDA governs caffeine content labeling and novel ingredient notifications under the Federal Food, Drug, and Cosmetic Act, while state-level attorneys general in California and New York enforce Prop 65 warnings for acrylamide exposure. The USDA's National Organic Program shapes sourcing requirements for certified organic product lines. Stakeholders must monitor pending FDA guidance on caffeine consumption limits for non-beverage formats, as this will determine permissible serving sizes and directly reshape formulation decisions across the competitive set.
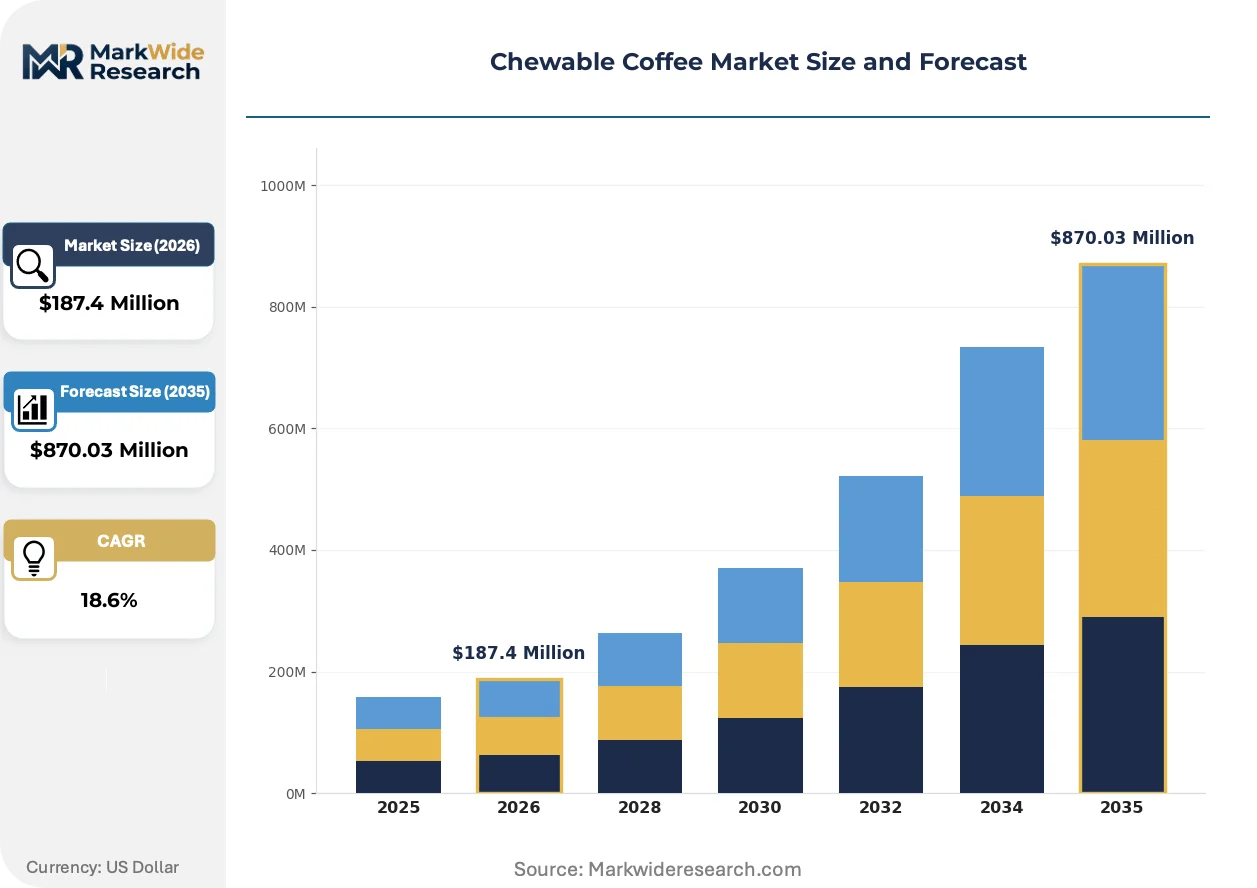
Market Dynamics
Portable caffeine formats are displacing traditional brewing rituals among time-constrained consumers, compressing the addressable market for conventional coffee equipment while expanding shelf space for compressed and gummy matrices in convenience retail.
Growth Catalysts
- Shift-Worker Scheduling Density:Healthcare, logistics, and hospitality sectors operate 24-hour rotations. These workers demand discrete, no-brew caffeine intake during restricted-break environments.
- FDA Novel Food Ingredient Pathways:The agency's clarified notification procedures for spray-dried coffee extracts and pectin-based binders accelerate formulation-to-shelf timelines for compliant manufacturers.
- Urban Commute Extension:Metropolitan transit corridors in the United States stretch average door-to-desk travel beyond 45 minutes. Commuters substitute brewing time with transit-consumable formats.
Market Restraints
- Acrylamide Exposure Liability:California's Prop 65 mandates warning labels for roasted coffee derivatives. Compliance costs and litigation exposure constrain margin recovery for mass-market entrants.
- Arabica Concentration Risk:Spray-dried extract supply clusters in Vietnam and Brazil. Weather volatility and port congestion transmit directly to input cost instability.
- Caffeine Ceiling Effects:FDA guidance on non-beverage caffeine serving sizes remains pending. Formulation teams face stranded R&D if thresholds tighten below current 100 mg piece dosing.
Strategic Opportunities
- Airport and Gym Vending Placements:Single-serve blister packs align with TSA liquid restrictions and post-workout recovery windows. These channels remain underpenetrated relative to conventional retail.
- Nootropic-Adaptogen Convergence:L-theanine, lion's mane, and ashwagandha fortification commands 40-60% price premiums over baseline caffeine matrices. Functional positioning opens wellness-adjacent buyer segments.
- USDA Organic Certification:National Organic Program compliance differentiates clean-label offerings. Certified supply chains access premium shelf placement in Whole Foods and Sprouts regional networks.
Industry Challenges
- Flavor Masking Expertise Scarcity:Spray-dried coffee extract carries bitter alkaloid loads. Food technologists with gummy matrix bitterness-suppression experience command premium compensation in tight labor markets.
- Cross-Channel Inventory Synchronization:Amazon Direct-to-Consumer velocity patterns diverge sharply from supermarket replenishment cycles. Manufacturers face working capital strain from dual forecasting models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chewable Coffee Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Instant, Flavored, Functional End User: Health-Conscious Consumers, College Students, Busy Professionals, Athletes Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Packaging Type: Bags, Bottles, Blister Packs, Pouches |
| Companies Covered | Viter Energy, Go Cubes by Nootrobox, Java Me Up, Kaffn8, Dry Brew, HVMN, Verb Energy, Stay Buzzed, Hector Beverages, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chewable Coffee Market Evolving Landscape
Formulation science and distribution architecture are diverging from beverage-industry templates. Manufacturers now engineer for shelf-stable portability rather than liquid consumption rituals.
Microencapsulation technology is bifurcating product architecture across the competitive set. This process coats caffeine and extract particles in lipid or polymer shells, masking bitterness while enabling timed-release absorption. Athletes and overnight-shift workers adopt these formats for sustained-alertness dosing without the jitter peaks of instant coffee. The structural consequence is compression of conventional instant-coffee sachet demand in travel and workplace channels.
EMA's evolving Novel Food Catalogue classifications for caffeine-containing gummies reshape European market entry protocols. The framework requires pre-market safety dossiers for non-traditional delivery formats, extending approval timelines relative to conventional beverages. German and Dutch regulators enforce stricter acrylamide thresholds than southern member states, fragmenting formulation standardization across the single market.
Subscription-based replenishment models displace supermarket impulse purchasing among repeat buyers. Direct-to-consumer platforms capture lifetime value through auto-ship algorithms calibrated to individual consumption cadence. This channel rotation concentrates most visible in United States coastal metropolitan corridors where delivery density minimizes shipping cost penalties.
Chewable Coffee Market Segmentation
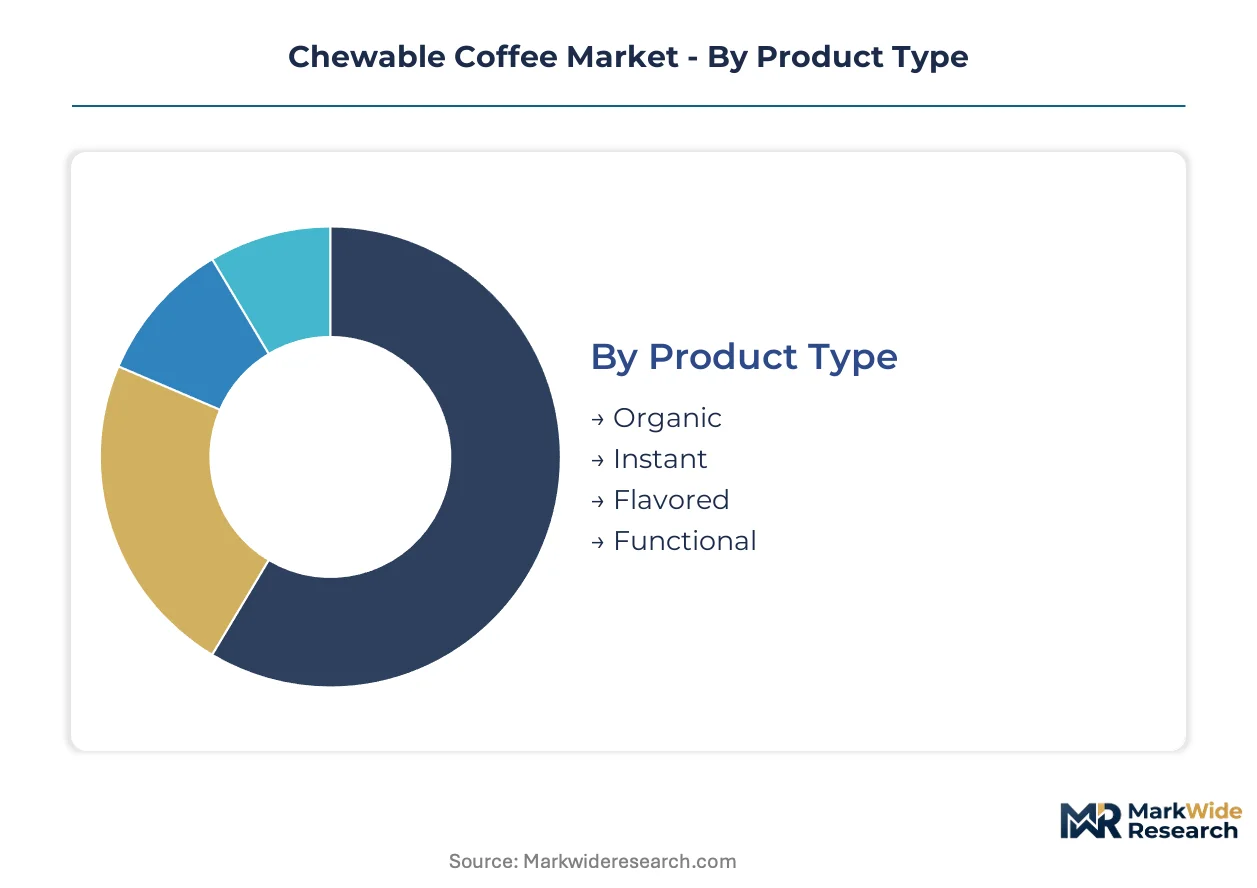
Segmentation in chewable coffee determines formulation pathways, regulatory exposure, and channel economics. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
FDA and USDA regulatory frameworks bifurcate this category between certified organic lines and conventional formulations, with novel food additive pathways governing functional fortification.
- Organic:USDA National Organic Program certification mandates supply chain traceability from spray-dried extract sourcing through final binding. Premium shelf placement in Sprouts and Whole Foods networks offsets 15-20% input cost premiums for compliant manufacturers.
- Functional:Nootropic and adaptogen fortification with L-theanine, lion's mane, or ashwagandha commands substantial price premiums. Athletes and cognitive-performance seekers in United States metropolitan corridors drive repeat purchase velocity through subscription channels.
- Instant:Compressed matrices with rapid dissolution profiles target travelers and shift workers needing immediate caffeine absorption.
- Flavored:Vanilla, mocha, and caramel masking systems reduce bitter alkaloid perception for mainstream palate expansion.
Functional handles the majority of throughput; Flavored is expanding most quickly on share.
End User:
Consumption context varies sharply across occupational and lifestyle segments, with break-time restrictions and portability requirements dictating product format preferences.
- Busy Professionals:Door-to-desk transit exceeding 45 minutes in United States urban corridors compresses brewing rituals. These buyers substitute traditional equipment with transit-consumable formats that bypass TSA liquid restrictions and office kitchen queues.
- Athletes:Pre-workout and mid-training dosing demands precise caffeine titration without gastrointestinal load from liquid consumption. Microencapsulated timed-release formats reduce jitter peaks during endurance activities.
- Health-Conscious Consumers:Clean-label scrutiny drives prop 65 awareness and organic certification verification at point of purchase.
- College Students:Price sensitivity and all-night study schedules favor bulk purchasing of baseline caffeine matrices.
Busy Professionals dominate absolute volume; Athletes show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics, with divergent replenishment cycles straining dual forecasting models.
- Online Retail:Direct-to-consumer auto-ship algorithms capture lifetime value through consumption cadence calibration. Amazon velocity patterns concentrate in coastal metropolitan United States corridors where delivery density minimizes shipping penalties.
- Supermarkets:Impulse-driven trial placement at checkout and energy product aisles sustains highest absolute volume for mass-market entrants.
- Convenience Stores:Single-serve blister packs align with grab-and-go purchasing in transit corridors and 24-hour operations.
- Specialty Shops:Gym and airport vending placements remain underpenetrated relative to conventional retail, offering premium positioning for functional formats.
Supermarkets absorb the largest share of unit movement; Online Retail is gaining share fastest.
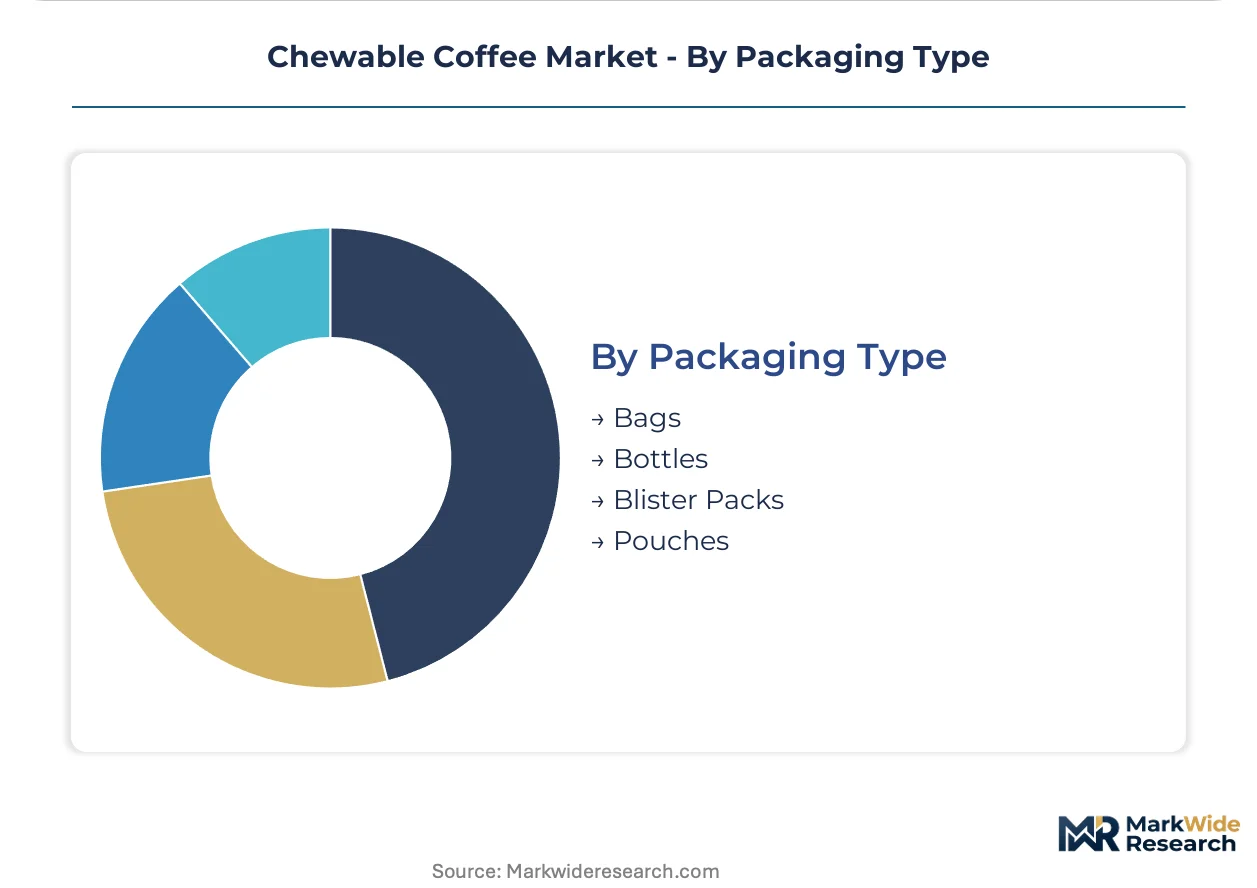
Packaging Type:
Material selection and unit configuration shape shelf stability, portability compliance, and per-unit economics across retail environments.
- Blister Packs:Single-serve aluminum-plastic laminates satisfy TSA liquid restrictions and gym bag portability. These formats command placement premiums in airport vending and fitness center micro-markets.
- Pouches:Flexible film structures with resealable zippers target multi-dose commuters and shift workers needing discrete portion control.
- Bottles:Rigid PET containers with desiccant inserts protect gummy matrices from humidity degradation in high-turnover retail.
- Bags:Bulk flexible packaging serves subscription replenishment and value-oriented collegiate segments.
Blister Packs carry the highest throughput concentration; Pouches are climbing the fastest on share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for spray-dried coffee extract concentrates in Vietnam and Brazil, while formulated product exports flow predominantly toward North American and European convenience retail channels. Trade imbalances in raw arabica processing create input cost volatility that manufacturers hedge through multi-origin sourcing contracts.
United States
Urban commute extension beyond 45 minutes in metropolitan corridors drives transit-consumable format substitution. FDA novel food ingredient notifications for pectin-based binders accelerate compliant product launches. California's Prop 65 enforcement on acrylamide exposure shapes warning label requirements for Los Angeles and San Francisco retail placements.
Germany
EMA Novel Food Catalogue pre-market safety dossiers extend approval timelines for caffeine-containing gummies entering the single market. Stricter acrylamide thresholds in northern member states fragment formulation standardization. Berlin and Hamburg distribution hubs channel functional fortified products toward wellness-adjacent consumer segments.
United Kingdom
Post-Brexit divergence from EU novel food pathways creates dual compliance burdens for cross-channel suppliers. FSA consultation on non-beverage caffeine formats mirrors pending FDA guidance. London metropolitan demand concentrates in subscription-based replenishment models calibrated to individual consumption cadence.
Vietnam
Robusta and arabica spray-dried extract supply clusters transmit weather volatility and port congestion directly to global input costs. Ministry of Industry and Trade export licensing frameworks shape raw material availability windows. Ho Chi Minh City processing facilities anchor Southeast Asian supply chain concentration for binding agent integration.
Brazil
Arabica concentration risk in Minas Gerais and São Paulo growing regions exposes manufacturers to climate-driven harvest variability. ANVISA novel food additive regulations govern import pathways for finished chewable matrices. São Paulo industrial corridors concentrate spray-drying capacity that supplies North American and European formulators.
Chewable Coffee Market Competitive Landscape
Listed leaders compete with private specialists across formulation sophistication and channel access dimensions. The vendor base clusters into three tiers: early-movers with convenience retail shelf presence, nootropic-infused premium-positioned players, and clean-label athletes targeting wellness segments. Strategic archetypes include energy-focused gummy specialists, cognitive-performance formulators, and organic-certified clean-label suppliers. Competitive moves concentrate on M&A for flavor masking technology acquisition and strategic partnerships for airport vending placement expansion.
Within the energy-focused archetype, Viter Energy and Verb Energy occupy positions exemplifying early-mover shelf presence and clean-label athlete targeting respectively. HVMN anchors the nootropic-infused premium tier through cognitive-performance positioning that commands substantial price premiums over baseline caffeine matrices. These three entities represent distinct competitive vectors: convenience channel density, wellness-adjacent certification, and functional fortification expertise.
| Leading Market Players |
|---|
| Viter Energy |
| Go Cubes by Nootrobox |
| Java Me Up |
| Kaffn8 |
| Dry Brew |
| HVMN |
| Verb Energy |
| Stay Buzzed |
| Hector Beverages |
| Others |
Value Network & Pricing Analysis
USDA National Organic Program certification gates both supplier qualification and price tier separation simultaneously. Manufacturers bearing certified supply chains access premium shelf placement in Sprouts and Whole Foods networks while commanding 15-20% input cost premiums that transmit directly to consumer-facing price points. This dual-gating mechanism concentrates margin recovery among incumbents with established organic traceability infrastructure.
Pricing Analysis
Busy professionals anchor a three-tier pricing structure across premium, standard, and economy levels. Subscription-based auto-ship models differentiate through consumption cadence calibration, while single-serve blister packs command placement premiums in airport vending. Cost compression in the economy tier intensifies because of arabica concentration risk in Vietnam and Brazil. College students exhibit highest price sensitivity; cognitive-performance seekers show lowest elasticity due to nootropic-adaptogen fortification premiums.
Supply Chain Analysis
Inventory cycles diverge sharply between Amazon Direct-to-Consumer velocity patterns and supermarket replenishment rhythms. Spray-dried coffee extract supply clusters in Vietnam and Brazil, with Ho Chi Minh City and São Paulo industrial corridors anchoring processing capacity. Binding agents such as pectin and gelatin rest on agricultural commodity markets. Single-source vulnerability concentrates in arabica harvest variability due to climate exposure. Distribution runs through convenience retail channels for impulse trial, with specialty gym and airport placements expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around subscription-platform aggregators that capture lifetime value through auto-ship algorithms. This concentration shifts margin extraction upstream toward channel controllers with consumption data advantages.
For Market Incumbents: Compound shelf presence in convenience retail through flavor masking technology acquisition that addresses food technologist scarcity. Defend against emerging nootropic-infused entrants by accelerating USDA Organic certification timelines. Prioritize backward integration into spray-dried extract sourcing to hedge arabica concentration risk.
For New Entrants and Emerging Players: Airport and gym vending micro-markets represent underpenetrated white-space where single-serve blister packs align with TSA liquid restrictions and post-workout recovery windows. Target health-conscious consumers through clean-label positioning that emphasizes Prop 65 compliance transparency. Deploy direct-to-consumer launch with subscription auto-ship to bypass incumbent-controlled retail gatekeepers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across functional fortification sub-segments as microencapsulation technology commoditizes. Long-term viability favors manufacturers with captive organic supply chains and established FDA novel food notification pathways. Acquisition target archetype: mid-tier formulators with bitterness-suppression expertise but underutilized distribution infrastructure. Monitor FDA guidance on non-beverage caffeine serving sizes as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Flavor Masking Technology Acquisition | Addresses food technologist scarcity that constrains gummy matrix formulation capacity. |
| USDA Organic Certification Investment | Unlocks premium shelf placement in Sprouts and Whole Foods regional networks. |
| Airport Vending Placement Expansion | Aligns with TSA liquid restrictions and captures transit-consumable demand concentration. |
| Subscription Auto-Ship Platform Launch | Captures lifetime value through consumption cadence calibration in coastal metropolitan corridors. |
| Nootropic-Adaptogen Fortification R&D | Commands price premiums from cognitive-performance seekers and wellness-adjacent segments. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at retailers, channel sales heads, and supply planners anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from FDA filings, USDA National Organic Program records, Nielsen retail audit data, and customs import records. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Sensitivity analysis tested forecast robustness across the projection horizon. The analytical framework modeled product type, end user, distribution channel, and packaging format dimensions alongside regional regulatory cluster variations. CAGRs derived from historical trajectory analysis and forward-looking consumption pattern shifts. Industry-specific inputs included shift-worker scheduling density metrics and urban commute extension data from metropolitan transit authorities.
Underlying assumptions cover FDA novel food ingredient pathway stability and arabica supply concentration persistence, with deviation risk concentrated in pending caffeine serving size guidance and climate-driven harvest variability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Roast to Order Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Robusta Coffee Beans Market
Coffee
South Korea Coffee Roaster Market
Coffee
Global Portable Coffee Makers Market
Coffee
Single Origin Coffee Market
Coffee
Adaptogen Coffee Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Coffee and Tea Capsule Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Coffee Roaster Market
Coffee
Decaffeinated Coffee Market
Coffee
GCC Instant Coffee Market