
 Curcumin Market | 2026-2036
Curcumin Market Size, Share, and Industry Trends Forecast 2026-2036
Curcumin Market Analysis
Multi-source turmeric procurement is hardening as a competitive requirement across the curcumin value chain. Synthite Industries Ltd. anchors India's export-oriented extraction infrastructure with backward integration into Kerala farming cooperatives. Sabinsa Corporation differentiates through patented bioavailability enhancement technologies for North American nutraceutical brands. Wacker Chemie AG operates fermentation-derived curcuminoid platforms that bypass agricultural supply volatility entirely.
Curcumin denotes the principal diarylheptanoid extracted from Curcuma longa rhizomes, typically standardized to 95% purity for pharmaceutical applications and characterized by poor aqueous solubility that drives formulation complexity. The compound serves primarily as an anti-inflammatory and antioxidant active in dietary supplements, functional foods, and topical dermatological preparations. Powder formulations dominate bulk ingredient trade, while capsule segments capture premium pricing through finished-dose convenience. Nutraceutical applications lead volume consumption, though pharmaceutical-grade extracts command the highest purity premiums and regulatory validation burdens. Oil-based delivery formats represent an emerging structural category where liposomal encapsulation technologies unlock absorption thresholds previously unattainable with standard powders.
FDA New Dietary Ingredient notifications and EFSA health claim assessments shape market access trajectories for curcumin suppliers targeting regulated jurisdictions. India's FSSAI standards for botanical extracts and BIS quality benchmarks govern domestic manufacturing compliance and export certification pathways. CSRD supply-chain disclosure requirements in Europe are forcing extraction houses to document turmeric provenance and solvent residue profiles. Stakeholders must weigh agricultural sourcing risk against biotechnological substitution timelines when committing to capacity investments.
Market Dynamics
India's PLI scheme for botanical extracts is forcing capacity commitments from extraction houses before biotechnological substitutes reach commercial scale, compressing decision windows for agricultural-dependent players.
Growth Catalysts
- FSSAI botanical extract standards:India's tightened purity benchmarks are accelerating domestic laboratory upgrades and export certification velocity for Kerala-based processors.
- Liposomal encapsulation:Pharmaceutical formulators are integrating oil-based delivery formats into anti-inflammatory pipelines to overcome curcumin's aqueous solubility barriers.
- Karnataka contract farming networks:Concentrated turmeric cultivation belts are securing long-term raw material commitments from European nutraceutical buyers seeking provenance documentation.
Market Restraints
- Monsoon-dependent agricultural inputs:Kerala and Karnataka rainfall volatility creates raw material availability uncertainty that extraction capacity cannot buffer.
- Fermentation-derived substitution:Wacker Chemie AG's biotechnology platforms threaten to bypass turmeric agriculture entirely within the forecast window.
- EMA pharmaceutical-grade validation:European regulatory burdens for 95% purity extracts extend commercialization timelines and capital recovery periods.
Strategic Opportunities
- CSRD supply-chain disclosure mandates:European corporate sustainability reporting is creating premium pricing tiers for documented turmeric provenance and solvent residue transparency.
- Topical dermatological applications:Functional food and cosmetic formulators are expanding beyond nutraceutical capsules into transdermal delivery systems.
- EFSA health claim assessments:Successful antioxidant and anti-inflammatory claim validations would unlock mass-market food fortification channels.
Industry Challenges
- Phytochemistry extraction expertise:Shortages of technicians skilled in supercritical CO2 and ethanol extraction methods constrain laboratory throughput expansion.
- FDA New Dietary Ingredient notification timelines:Extended review periods for novel delivery formats delay North American market entry and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curcumin Market |
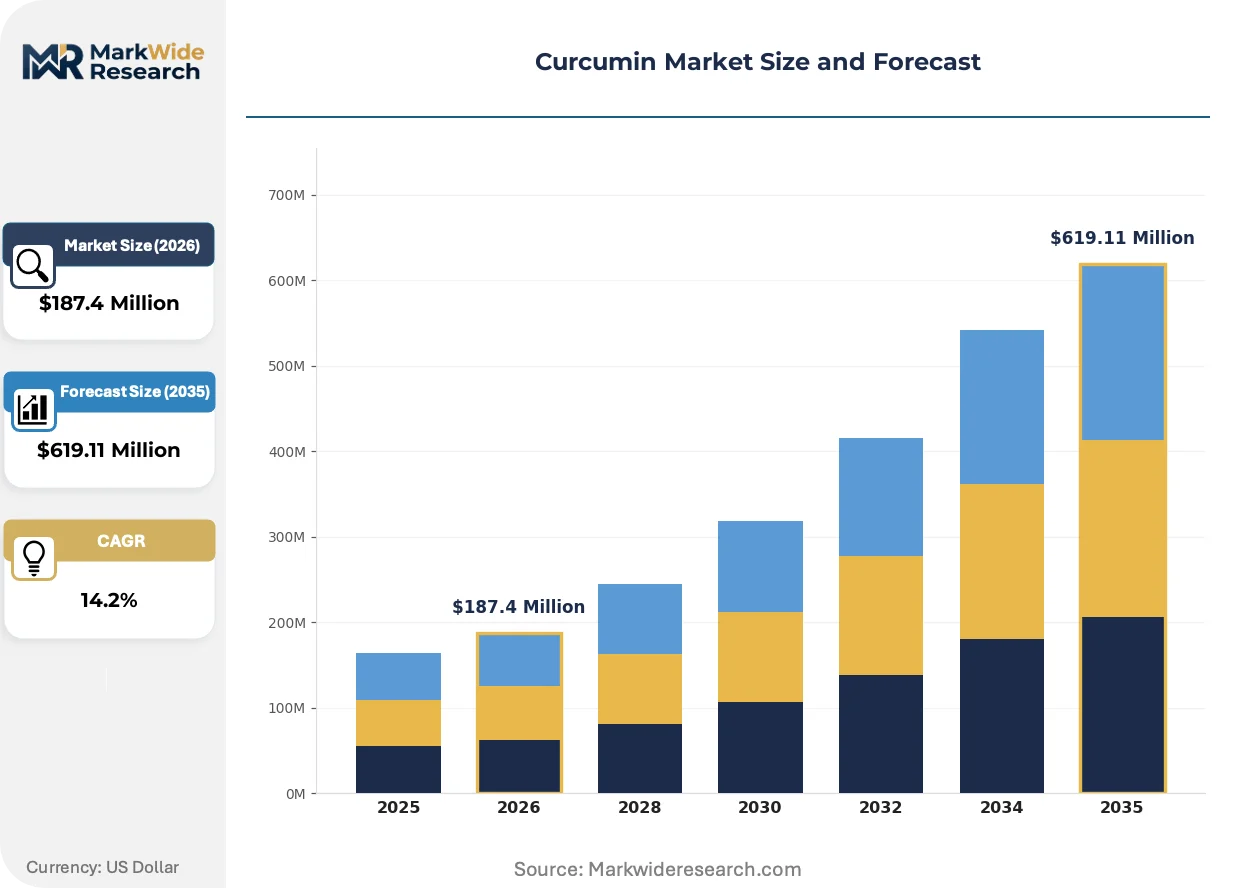
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Oil, Extract Application: Nutraceuticals, Pharmaceuticals, Food & Beverages, Cosmetics End User: Retail Consumers, Healthcare Professionals, Food Manufacturers, Cosmetic Brands Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | Synthite Industries Ltd., Biomax Life Sciences Ltd., Arjuna Natural Pvt. Ltd., SV Agrofood, Hindustan Mint & Agro Products Pvt. Ltd., Herboveda India Pvt. Ltd., Konark Herbals & Health Care Pvt. Ltd., Sabinsa Corporation, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curcumin Market Emerging Trajectories
Formulation complexity is becoming the primary competitive battleground as absorption limitations force delivery technology investments across the value chain.
Liposomal encapsulation systems are consolidating market share among pharmaceutical-grade suppliers. Dermatological and supplement manufacturers are adopting these oil-based formats faster than powder incumbents can reformulate. The technology is consolidating premium pricing power with extraction houses possessing in-house nanotechnology capabilities.
CSRD supply-chain disclosure requirements are reshaping procurement documentation burdens. European extraction houses must now verify turmeric farm-level provenance and solvent residue profiles for corporate buyers. Nutraceutical brands targeting EU markets are responding by demanding backward-integrated supplier relationships.
Buyer concentration among European nutraceutical distributors is compressing supplier negotiation leverage. Large contract farming networks in Kerala and Karnataka are consolidating volume commitments directly with finished-dose manufacturers, disintermediating traditional trading houses. This pattern is most visible in Germany and Netherlands import channels where sustainability certification now gates market access.
Curcumin Market Segmentation
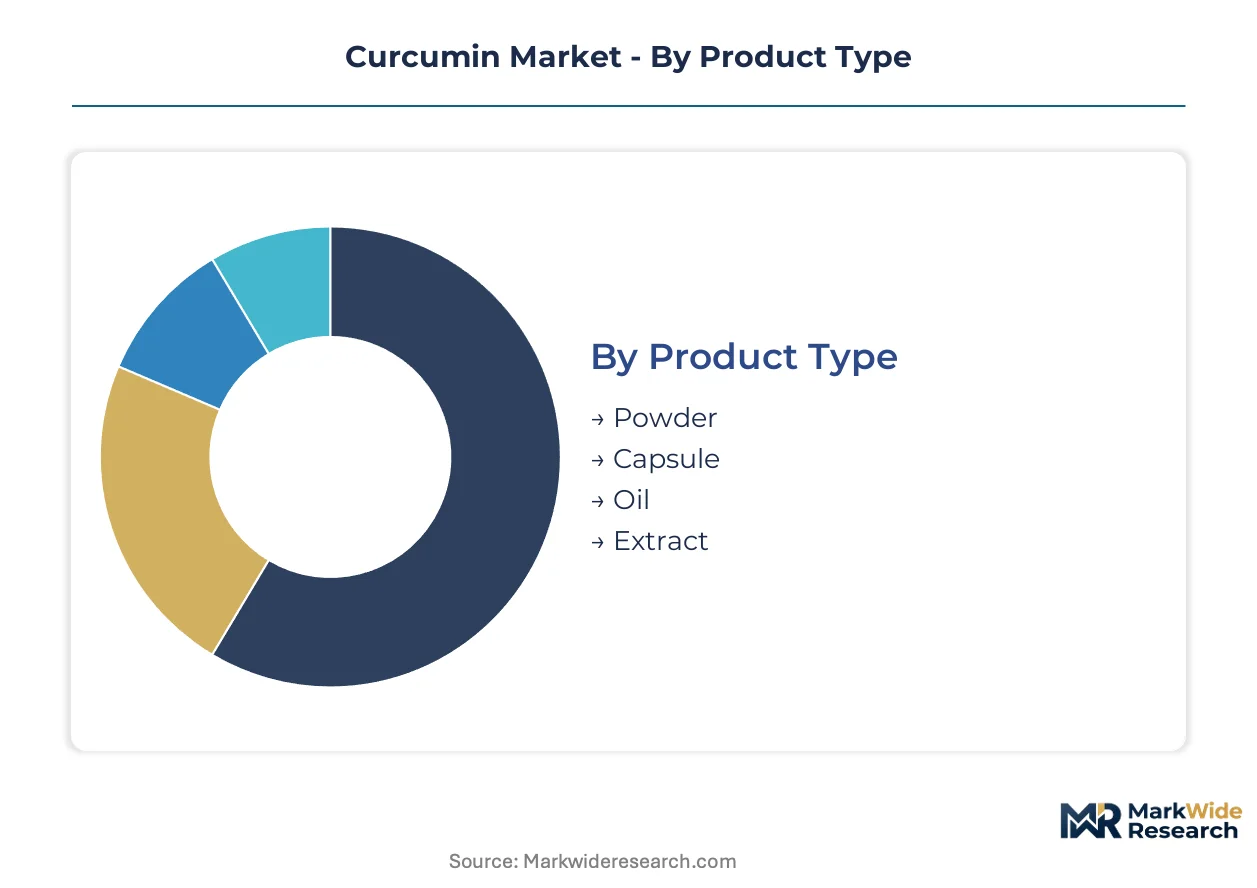
Curcumin suppliers face divergent formulation, regulatory, and margin requirements across product formats and buyer categories. Segmentation reveals where extraction technology investments concentrate and which distribution pathways gate market access for agricultural-dependent versus biotechnological supply sources.
Product Type:
Buyers differentiate primarily by solubility specifications and bioavailability enhancement requirements rather than raw purity alone.
- Powder:Standardized to 95% purity for bulk ingredient trade, powder dominates volume throughput in Kerala and Karnataka extraction facilities. Food manufacturers and supplement blenders in Germany and the Netherlands source powder for in-house encapsulation, though aqueous solubility limitations constrain pharmaceutical adoption.
- Capsule:Finished-dose convenience commands premium pricing through retail pharmacy and health food channels. North American nutraceutical brands specify capsule formats to bypass FDA New Dietary Ingredient notification complexity for novel delivery systems.
- Oil:Liposomal encapsulation technologies unlock absorption thresholds previously unattainable with standard powders. Pharmaceutical formulators in Switzerland and Japan are integrating oil-based formats into anti-inflammatory pipelines.
- Extract:Concentrated curcuminoid fractions serve cosmetic and topical dermatological applications requiring solvent residue documentation under CSRD supply-chain disclosure mandates.
Powder leads volumes today; oil-based formats are gaining share fastest.
Application:
Regulatory validation burdens and purity premiums separate pharmaceutical-grade demand from mass-market consumption channels.
- Nutraceuticals:Dietary supplements absorb the largest volume share, with European distributors consolidating procurement through backward-integrated Kerala suppliers. EFSA health claim assessments for antioxidant and anti-inflammatory positioning determine mass-market food fortification eligibility.
- Pharmaceuticals:95% purity extracts face EMA validation timelines that extend commercialization cycles. CDSCO in India and FDA in the United States impose parallel notification requirements that concentrate demand among extraction houses with dedicated regulatory affairs capabilities.
- Food & Beverages:Functional food formulators in Japan and South Korea specify lower-concentration extracts for beverage fortification, prioritizing taste masking over bioavailability enhancement.
- Cosmetics:Transdermal delivery systems are expanding beyond traditional nutraceutical capsules, with Korean and French cosmetic brands driving demand for documented turmeric provenance.
Nutraceuticals captures the largest volume position; pharmaceutical applications show the steepest expansion trajectory.
End User:
Professional versus retail buyer channels impose distinct documentation, certification, and technical support requirements on suppliers.
- Retail Consumers:Direct-to-consumer brands prioritize capsule convenience and online subscription models. Amazon and dedicated supplement platforms in the United States and United Kingdom dominate this channel.
- Healthcare Professionals:Clinician-directed prescribing concentrates in integrative medicine practices across Germany, Switzerland, and Australia, requiring batch-specific certificates of analysis and stability data.
- Food Manufacturers:Industrial buyers in bakery, dairy, and beverage segments procure powder formats at volume scale, with FSSAI compliance certification gating Indian domestic supply relationships.
- Cosmetic Brands:L'Oréal, Amorepacific, and Shiseido specify extract grades with verified solvent residue profiles and farm-level traceability documentation.
Food manufacturers lead volumes today; cosmetic brands are expanding most quickly.
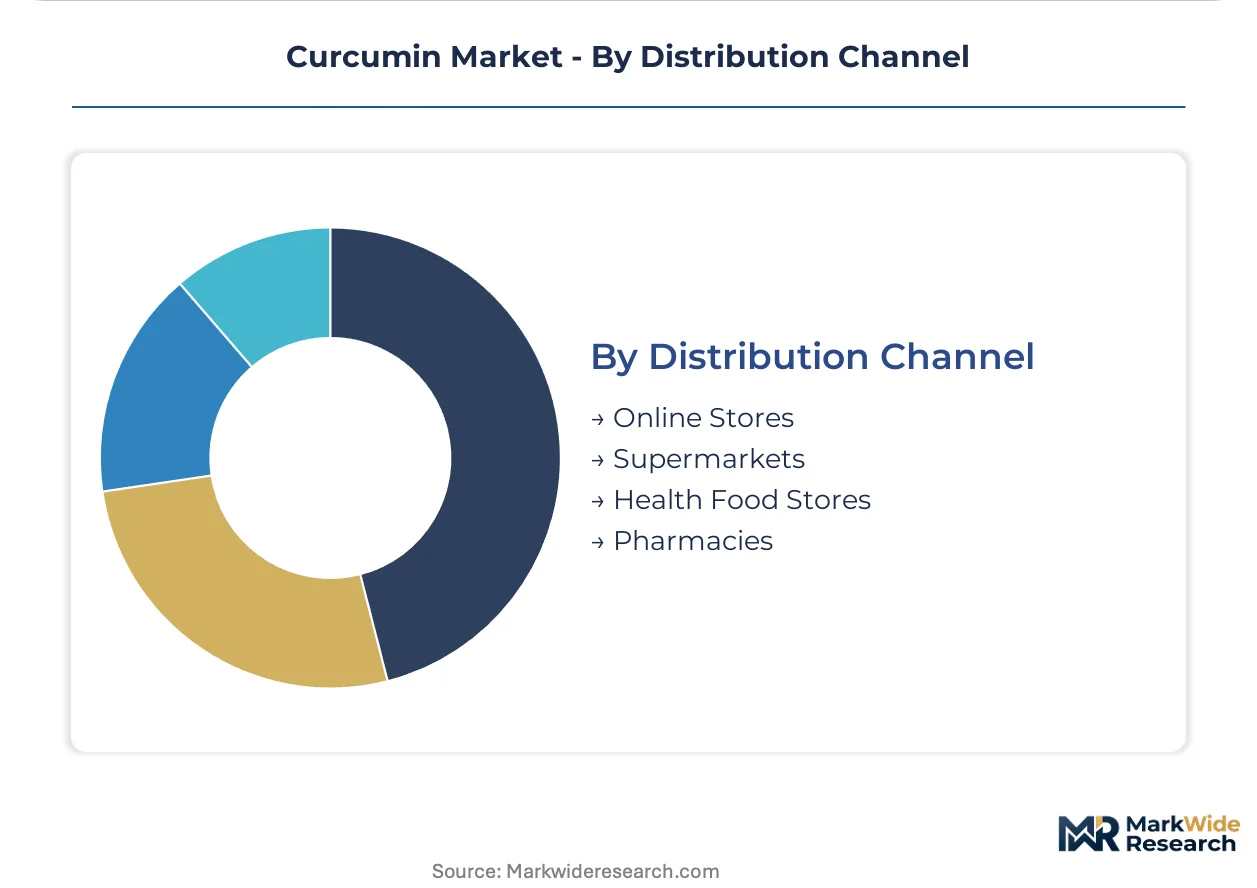
Distribution Channel:
Channel selection determines margin capture, brand control, and sustainability certification visibility to end buyers.
- Online Stores:Direct-to-consumer platforms enable subscription revenue models and bypass wholesale margin compression. iHerb and Thrive Market in North America consolidate volume from multiple Kerala-based extraction houses.
- Supermarkets:Mass retail placement requires finished-dose packaging and mass-market pricing tiers that agricultural-dependent suppliers struggle to meet.
- Health Food Stores:Specialist retailers in the Netherlands, Germany, and Australia prioritize organic certification and backward-integrated supplier relationships.
- Pharmacies:CVS, Walgreens, and Boots chains specify pharmaceutical-grade documentation that fermentation-derived suppliers can deliver more consistently than agricultural sources.
Online stores lead volumes today; pharmacy channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kerala and Karnataka anchor the curcumin supply base, with extraction infrastructure concentrated in India's southwestern turmeric belt. European nutraceutical buyers source heavily from these clusters, while North American and East Asian markets develop parallel procurement channels with distinct regulatory requirements.
India
Kerala's farming cooperatives supply concentrated raw material to Synthite Industries Ltd. and other extraction houses. The FSSAI tightened purity benchmarks for botanical extracts, accelerating laboratory upgrades across Kochi and Bengaluru processing facilities. Karnataka contract farming networks now secure long-term commitments directly with German and Dutch buyers, bypassing traditional trading intermediaries.
Germany
Pharmaceutical formulators in Basel-proximate regions integrate liposomal curcumin into anti-inflammatory pipelines. The EMA validation timelines for 95% purity extracts extend commercialization cycles, favoring suppliers with dedicated regulatory affairs capabilities. CSRD supply-chain disclosure mandates force documentation of turmeric provenance and solvent residue profiles for corporate sustainability reporting.
United States
North American nutraceutical brands prioritize capsule formats to circumvent FDA New Dietary Ingredient notification complexity. Sabinsa Corporation's patented bioavailability technologies serve this demand through domestic formulation partnerships. Amazon and iHerb consolidate procurement volume from multiple Kerala-based extraction houses, compressing wholesale margins.
Japan
Functional food manufacturers in Osaka and Tokyo specify lower-concentration extracts for beverage fortification, prioritizing taste masking over absorption enhancement. The PMDA maintains parallel notification requirements with FDA, concentrating demand among extraction houses with dual regulatory expertise. Pharmaceutical-grade oil formats from Swiss and Indian suppliers penetrate clinician-directed channels in integrative medicine practices.
Switzerland
Basel-based pharmaceutical formulators drive adoption of liposomal encapsulation for transdermal and oral delivery systems. Swissmedic standards for botanical extracts align with EMA benchmarks, creating regulatory coherence for cross-border EU supply. Cosmetic brands including L'Oréal specify extract grades with verified farm-level traceability for sustainability certification.
Curcumin Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-derived substitution pathways. The vendor base separates into agricultural-dependent extraction houses with Kerala farming cooperatives and fermentation-based platforms that bypass turmeric agriculture entirely. Three archetypes dominate: backward-integrated Indian processors, North American bioavailability specialists, and European biotechnological substitutes. Capacity commitments and regulatory certification velocity constitute the dominant competitive moves, with extraction houses racing to secure PLI scheme benefits before biotechnological alternatives reach commercial scale.
Within the agricultural-dependent tier, Synthite Industries Ltd. and Sabinsa Corporation exemplify divergent strategic positioning. Synthite Industries Ltd. anchors export-oriented extraction infrastructure through Kerala cooperative relationships. Sabinsa Corporation occupies the North American nutraceutical channel through patented delivery technologies. Wacker Chemie AG represents the biotechnological substitution threat, with fermentation-derived platforms threatening to displace turmeric agriculture within the forecast window.
| Leading Market Players |
|---|
| Synthite Industries Ltd. |
| Biomax Life Sciences Ltd. |
| Arjuna Natural Pvt. Ltd. |
| SV Agrofood |
| Hindustan Mint & Agro Products Pvt. Ltd. |
| Herboveda India Pvt. Ltd. |
| Konark Herbals & Health Care Pvt. Ltd. |
| Sabinsa Corporation |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
CSRD supply-chain disclosure mandates in Europe gate qualified supply relationships and premium-tier pricing access for extraction houses able to document turmeric farm-level provenance and solvent residue profiles. Buyers in Germany and the Netherlands now pay measurable premiums for backward-integrated Kerala suppliers with verified sustainability certification, while uncertified trading intermediaries face margin compression.
Pricing Analysis
Input-cost pass-through from monsoon-dependent turmeric agriculture in Kerala and Karnataka drives volatility in powder-grade curcumin, with contract farming networks securing price stability through long-term offtake agreements. Pricing stratifies across pharmaceutical-grade oil formats, standard powder for food manufacturers, and economy capsules for mass retail, with EMA validation burdens adding certification premiums to the top tier. Cost compression in standard powder runs through buyer consolidation among European nutraceutical distributors. Food manufacturers exhibit highest price sensitivity due to volume procurement and substitutability, while pharmaceutical formulators absorb premiums for documented purity.
Supply Chain Analysis
Workforce availability constraints in Kochi and Bengaluru processing facilities limit laboratory throughput expansion for supercritical CO2 and ethanol extraction methods. Geographic supply concentration centers on India, with secondary processing clusters in Germany and Switzerland for pharmaceutical-grade finishing. Raw material dependencies draw from Kerala farming cooperatives, Karnataka contract farming networks, and fermentation-derived substitutes from biotechnology platforms. Single-source vulnerability to monsoon rainfall volatility in southwestern India threatens raw material availability. Distribution runs through direct procurement relationships between extraction houses and European nutraceutical buyers, disintermediating traditional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The curcumin market functions as a stable compounder, with pharmaceutical formulator demand for anti-inflammatory actives providing steady volume foundations resistant to cyclical downturns.
For Market Incumbents: Anchor Kerala cooperative relationships through PLI scheme capacity commitments before fermentation-derived substitutes reach commercial scale. Deepen backward integration into Karnataka contract farming networks to secure documented provenance for CSRD-compliant European buyers. Invest in liposomal encapsulation capabilities to capture pharmaceutical-grade pricing premiums as oil-based formats gain share. For New Entrants and Emerging Players: FSSAI botanical extract standards in India open a window for domestic laboratory operators to capture share from export-focused incumbents neglecting compliance upgrades. Target cosmetic brand procurement in France and South Korea, where transdermal delivery system demand outpaces qualified supplier availability. Pursue white-label manufacturing partnerships with North American direct-to-consumer brands seeking to bypass FDA New Dietary Ingredient notification complexity. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap extraction houses with captive farming cooperatives because buyer consolidation among European distributors favors scaled suppliers with provenance documentation. The 5-10 year viability window hinges on biotechnological substitution timelines, with fermentation platforms threatening agricultural dependence. Watch Wacker Chemie AG's commercial scale-up milestones as the inflection signal for agricultural asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Kerala cooperative relationships secure CSRD-compliant provenance documentation for European pharmaceutical buyers. |
| Liposomal Encapsulation Technology Investment | Oil-based delivery formats unlock EMA-validated pharmaceutical pipelines previously inaccessible to powder incumbents. |
| FSSAI Laboratory Certification Upgrade | Domestic compliance velocity captures share from export-focused competitors neglecting Indian regulatory alignment. |
| Long-term Supply Agreement with European Distributors | Direct procurement relationships with German and Dutch buyers disintermediate margin-compressing trading intermediaries. |
| Regulatory Affairs Capability Buildout | Dedicated FDA and EMA submission expertise accelerates commercialization timelines for novel delivery formats. |
Methodological Framework
Direct dialogue with extraction house technical directors, Kerala farming cooperative managers, European nutraceutical procurement leads, and pharmaceutical formulator R&D heads grounded qualitative findings in operational reality. Secondary validation drew from FSSAI botanical extract standards documentation, EFSA health claim assessment records, CDSCO pharmaceutical-grade validation guidelines, and SEC filings from publicly traded suppliers. Bottom-up volume estimates from Kerala and Karnataka processing facilities triangulated against top-down demand projections from European import data and North American dietary supplement channel audits.
Segmentation outputs across product type, application, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical volume trajectories adjusted for PLI scheme capacity addition timelines and biotechnological substitution threat curves. Forecast inputs incorporated monsoon rainfall variability indices, EMA validation pipeline backlogs, and fermentation platform commercialization milestones specific to curcuminoid production.
Revisions become necessary when biotechnological substitutes achieve cost parity with agricultural extraction, EFSA health claim assessments unlock mass-market food fortification channels, or PLI scheme benefits expire without capacity utilization stabilization. Forecasts reflect documented assumptions about regulatory timeline continuity and turmeric yield stability. Material deviation in substitution economics, European sustainability mandate enforcement intensity, or Indian agricultural policy direction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Global Liver Health Supplements Market