
 Fiber Supplements Market | 2026-2036
Fiber Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Supplements Market Analysis
EU Green Deal nutrition targets is consolidating demand for clinically validated fiber ingredients across European supplement portfolios. Procter & Gamble leverages its pharmacy channel control to sustain Metamucil's visibility in retail clinics. NOW Foods anchors its position through vertical integration into organic inulin sourcing. GSK Group differentiates via pharmacist-directed recommendation programs in UK and German markets.
Fiber supplements are concentrated or synthesized preparations of non-digestible carbohydrates, typically delivering five to ten grams of soluble or insoluble fiber per serving, manufactured through milling, extraction, or fermentation processes to support digestive regularity, glycemic moderation, and cholesterol management. Psyllium husk dominates prescription-adjacent channels due to its FDA-recognized cholesterol reduction claims, while inulin experiences accelerated adoption in functional food fortification. Powder formulations remain the margin pool leader due to lower unit production costs and bulk packaging flexibility.
FDA maintains strict identity standards for dietary fiber labeling under its Nutrition Facts framework, while EFSA evaluates health claim substantiation through its NDA panel, and India's FSSAI enforces additive purity thresholds for imported fiber concentrates. These overlapping compliance regimes elevate testing and documentation burdens for cross-border suppliers. Stakeholders must monitor evolving fiber definition harmonization between FDA and Codex Alimentarius to anticipate reformulation obligations and market access conditions.
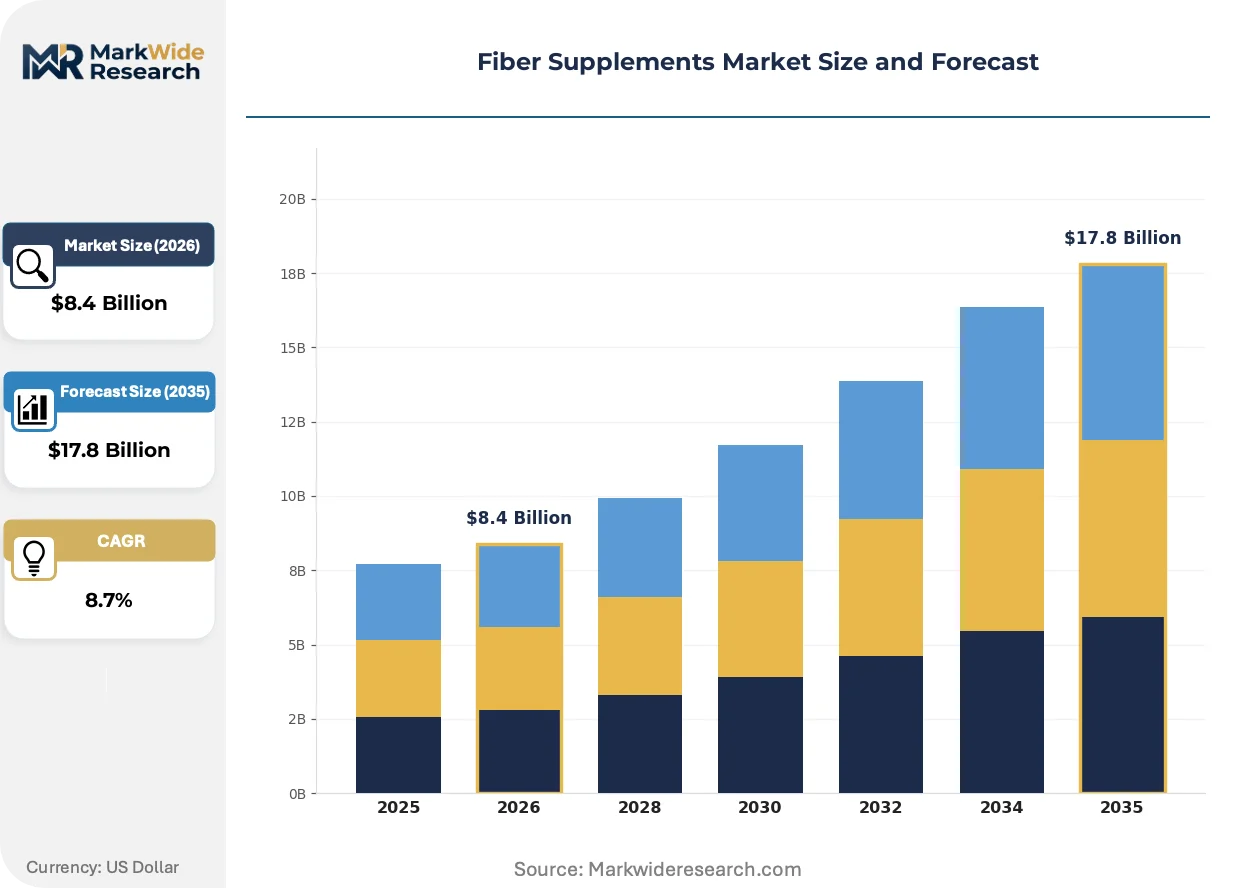
Market Dynamics
FDA's 2023 dietary fiber definition update is forcing reformulation across psyllium and inulin portfolios, while EU Nutrition and Health Claims Regulation scrutiny tightens substantiation requirements for cholesterol and glycemic claims.
Growth Catalysts
- EU Green Deal nutrition targets:Mandated fiber fortification in processed foods is pulling clinically validated ingredients into supplement-adjacent functional food channels across Germany, France, and Italy.
- Gut microbiome research maturation:Fermentation-derived prebiotics are gaining pharmacy shelf space as prescribers recognize synbiotic combinations for metabolic syndrome management.
- India FSSAI additive purity thresholds:Import standard harmonization is consolidating procurement toward certified suppliers capable of documentation-heavy cross-border shipments.
Market Restraints
- Psyllium husk supply concentration:Gujarat and Rajasthan processing clusters in India account for disproportionate raw material flow, exposing formulators to monsoon-dependent crop volatility.
- EFSA health claim substantiation costs:Randomized controlled trial requirements for Article 13.1 claims impose six-figure validation burdens that marginalize mid-tier ingredient suppliers.
- Synthetic soluble fiber substitution:Maltodextrin and polydextrose fortification in budget functional foods competes directly with natural fiber positioning in price-sensitive retail tiers.
Strategic Opportunities
- Brazil ANVISA harmonization pathway:Pending alignment with Codex Alimentarius fiber definitions creates first-mover positioning for suppliers with pre-validated dossiers.
- Direct-to-consumer microbiome testing integration:Personalized fiber recommendations based on at-home gut analysis are opening subscription revenue models beyond traditional retail pharmacy.
- Japan FOSHU regulatory channel:Specific Health Use approval for viscous soluble fibers enables premium positioning in aging-population digestive health segments.
Industry Challenges
- Clinical trialist recruitment bottlenecks:GI endpoint studies require specialized CRO capabilities that concentrate in Boston, Basel, and Singapore, extending claim validation timelines.
- Legacy ERP-to-batch traceability integration:FDA 21 CFR Part 111 compliance demands real-time genealogy tracking that strains mid-sized contract manufacturers with paper-based quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Supplements Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Psyllium Husk, Inulin, Wheat Bran, Chia Seeds Form: Powder, Capsule, Liquid, Bar End User: Adults, Athletes, Seniors, Children Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Procter & Gamble, GSK Group, Archer Daniels Midland, Nestlé Health Science, NOW Foods, Renew Life, Benefiber, Metamucil, Garden of Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Supplements Market Emerging Trajectories
Microbiome-targeted delivery formats and fermentation-based production methods are compressing the gap between pharmaceutical-grade and nutraceutical-grade fiber specifications.
Precision fermentation of human milk oligosaccharide analogs is electrifying next-generation prebiotic development. Infant formula manufacturers in the Netherlands and Denmark are accelerating offtake agreements for 2'-fucosyllactose substitutes. This biotechnology is compressing cost curves for bioactive fibers previously extractable only from botanical sources.
EFSA's 2024 guidance on glycemic response claims tightens carbohydrate classification thresholds. Supplement manufacturers must now isolate and quantify non-digestible fractions through AOAC-approved methods. Powder and capsule segments in Germany and Spain face reformulation timelines to retain existing packaging claims.
Pharmacist-directed recommendation programs are displacing self-selection in UK and German retail clinics. Training investments by pharmacy chains elevate clinically validated psyllium above generic fiber blends. This channel consolidation concentrates volume with suppliers capable of supporting point-of-sale educational materials.
Fiber Supplements Market Segmentation
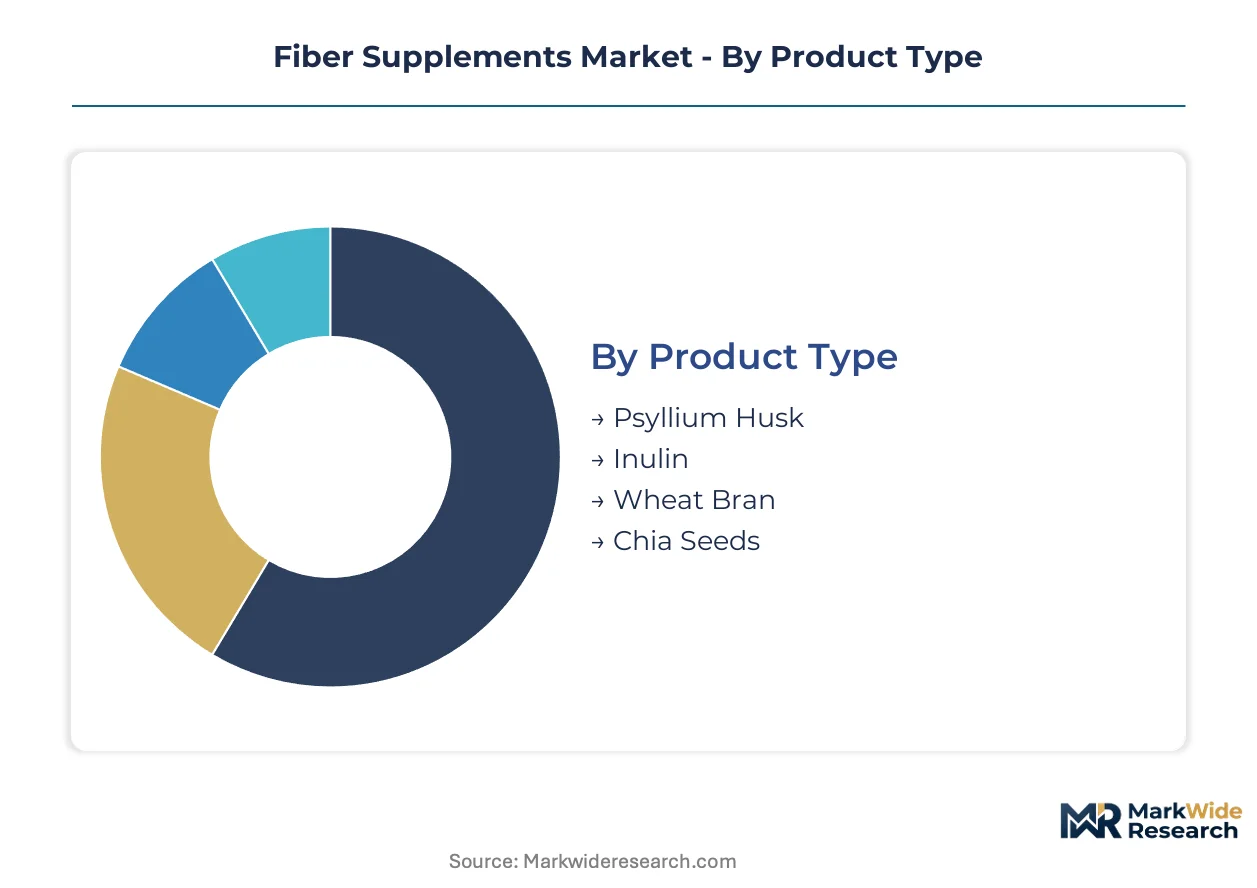
Fiber supplement segmentation reveals distinct upgrade cycles across product generations, with consumers shifting from basic bulk powders toward clinically validated formats. Formulation sophistication and channel accessibility now determine competitive positioning more than raw ingredient sourcing alone.
Product Type:
Upgrade cycles in fiber supplementation accelerate as consumers replace generic bulk fibers with clinically substantiated alternatives backed by regulatory-approved health claims.
- Psyllium Husk:Soluble fiber derived from Plantago ovata seed coats delivers viscous gel-forming properties that FDA recognizes for cholesterol reduction claims. Demand concentrates in United States pharmacy channels where pharmacist recommendations drive prescription-adjacent purchases under updated dietary fiber labeling requirements.
- Inulin:Fructan polysaccharide extracted from chicory root or Jerusalem artichoke serves prebiotic functions through selective fermentation by gut microbiota. Functional food manufacturers in Germany and France integrate inulin for EU Green Deal-aligned fiber fortification mandates in processed food categories.
- Wheat Bran:Insoluble fiber from outer grain layers accelerates intestinal transit through water absorption and bulk formation.
- Chia Seeds:Whole-food fiber source combining soluble and insoluble fractions with omega-3 fatty acid content.
Volume placements concentrate in psyllium husk; the faster expansion belongs to inulin.
Form:
Cost tier differentiation separates manufacturing-scale powder operations from premium-positioned delivery innovations requiring specialized encapsulation or stabilization technology.
- Powder:Bulk dry formulations offer lowest unit economics through simplified packaging and minimal processing steps. NOW Foods and similar suppliers leverage backward integration into organic sourcing to defend margin position in this high-volume tier.
- Capsule:Pre-measured gelatin or vegetable cellulose shells enable precise dosing compliance and portability for travel and workplace consumption. Athletes and frequent travelers in United States direct-to-consumer channels drive capsule segment expansion.
- Liquid:Ready-to-drink suspensions or concentrates dissolve instantly without mixing equipment.
- Bar:Food-matrix integration positions fiber within meal-replacement or snack formats competing with conventional nutrition bars.
Margin extraction peaks in capsule formats; liquid applications are climbing the fastest as convenience positioning penetrates younger demographics.
End User:
Application-specific requirements reshape formulation specifications across demographic segments with divergent digestive tolerance thresholds and compliance motivations.
- Adults:General population segment encompasses preventive health seekers managing weight, glycemic response, or routine regularity through daily supplementation. United States consumers dominate this category under FDA dietary fiber definition updates that clarify eligible fiber types for Nutrition Facts panel claims.
- Athletes:Performance-oriented users require low-residue, rapid-transit options that minimize gastrointestinal distress during training and competition. German sports nutrition brands formulate specialized low-FODMAP fiber blends for this tolerance-sensitive segment.
- Seniors:Age-related digestive slowing and polypharmacy interactions necessitate gentle, drug-interaction-tested formulations.
- Children:Palatability and texture constraints drive gummy, chewable, or flavor-masked powder innovations.
Absolute volume concentrates in adult formulations; pediatric applications are gaining share fastest as early-life microbiome programming research validates parental purchase decisions.
Distribution Channel:
Customer type and purchase occasion fragmentation splits fiber supplement flow across channels with incompatible service models and margin structures.
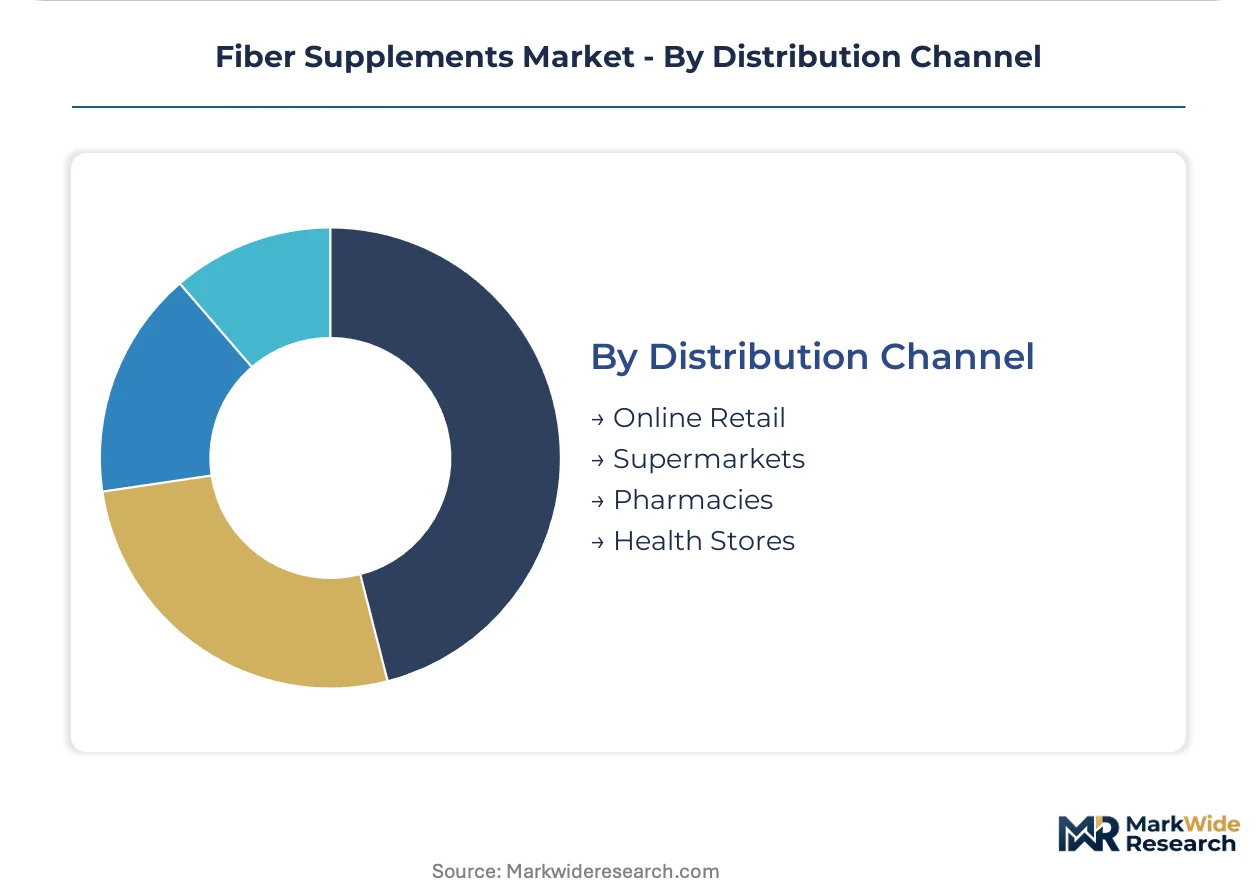
- Pharmacies:Pharmacist-directed recommendation programs in United Kingdom and Germany elevate clinically validated psyllium above self-selection. GSK Group and Procter & Gamble invest in point-of-sale educational materials to secure shelf positioning in this trust-dependent channel.
- Online Retail:Direct-to-consumer platforms enable subscription models and personalized microbiome-test integration for recurring revenue capture. United States-based digital-native brands exploit this channel to bypass retail slotting fee barriers.
- Supermarkets:Mass-market placement competes on price-per-serving against private label alternatives.
- Health Stores:Specialty retailers emphasize organic certification, non-GMO verification, and whole-food ingredient positioning.
Revenue concentration sits with pharmacies; online retail demonstrates the steepest expansion trajectory as digital health integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ahmedabad anchors psyllium husk processing capacity, with Gujarat and Rajasthan clusters supplying raw material to formulators worldwide. FDA dietary fiber definition updates are reshaping import documentation requirements for Indian exporters. Monsoon-dependent crop cycles in these western states expose supply chains to annual volatility.
United States
Pharmacy channel consolidation elevates clinically validated psyllium above generic alternatives. FDA's 2023 dietary fiber labeling update clarifies eligible fiber types for Nutrition Facts panels. Boston and Basel host specialized CRO capabilities for GI endpoint studies that manufacturers require for claim substantiation.
Germany
Functional food manufacturers expand inulin procurement for EU Green Deal-aligned fortification mandates. EFSA's NDA panel enforces randomized controlled trial standards for Article 13.1 health claims. Hamburg and Frankfurt pharmacy chains invest in point-of-sale educational materials to steer consumer selection.
India
FSSAI additive purity thresholds for imported fiber concentrates consolidate procurement toward certified suppliers. Gujarat processing clusters account for disproportionate global psyllium husk flow. CDSCO and FSSAI overlapping compliance regimes elevate testing burdens for cross-border shipments.
United Kingdom
Pharmacist-directed recommendation programs displace self-selection in retail clinics. MHRA and EFSA-aligned claim substantiation requirements filter marginal suppliers from pharmacy shelves. London and Manchester pharmacy chains concentrate volume with dossier-capable ingredient suppliers.
Japan
Aging-population digestive health segments create demand for FOSHU-approved viscous soluble fibers. METI and PMDA regulate Specific Health Use claims through clinical validation requirements. Tokyo and Osaka functional food manufacturers accelerate offtake agreements for fermentation-derived prebiotics.
Fiber Supplements Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and channel control dimensions. Pharmacy-directed recommendation programs and clinically validated dossiers separate tier-one suppliers from bulk ingredient traders. Three archetypes dominate: multinational consumer health conglomerates with pharmacy channel control, vertically integrated organic specialists with captive raw material supply, and fermentation biotechnology platforms with precision prebiotic pipelines. Dominant competitive moves include backward integration into certified raw material sourcing and pharmacist training investments to secure retail clinic positioning.
Within the multinational consumer health tier, Procter & Gamble and GSK Group exemplify pharmacy channel anchoring through point-of-sale educational infrastructure. NOW Foods represents the vertically integrated specialist archetype with organic inulin sourcing control. These three entities occupy positions across distinct competitive vectors rather than direct segment overlap.
| Leading Market Players |
|---|
| Procter & Gamble |
| GSK Group |
| Archer Daniels Midland |
| Nestlé Health Science |
| NOW Foods |
| Renew Life |
| Benefiber |
| Metamucil |
| Garden of Life |
| Others |
Supply Flow & Price Mechanics
Precision fermentation of human milk oligosaccharide analogs is compressing cost curves for bioactive fibers while simultaneously concentrating production capacity among biotechnology platforms with capital-scale bioreactor infrastructure. This production-method transition simultaneously reshapes cost economics and supply concentration by displacing botanical extraction-dependent suppliers.
Pricing Analysis
Outcome-based pricing anchors premium tiers to clinically validated cholesterol reduction and glycemic moderation claims recognized by FDA and EFSA. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived prebiotics from commodity psyllium powders and synthetic soluble fiber substitutes. Cost compression in economy tiers intensifies as maltodextrin fortification competes directly with natural fiber positioning. Price sensitivity peaks among budget functional food manufacturers; clinical validation investment insulates premium suppliers.
Supply Chain Analysis
Dual-sourcing requirements from formulators mandate multi-supplier qualification across Gujarat, Rajasthan, and emerging European chicory processing clusters. Raw material flows draw from Plantago ovata seed coats, chicory root biomass, and fermentation feedstocks including glucose and yeast extracts. Single-source vulnerability concentrates in Indian monsoon-dependent crop cycles. Distribution runs through pharmacy wholesale networks, direct-to-consumer platforms, and functional food ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into certified raw material sourcing and captive bioreactor capacity represents the dominant vertical-integration race, with pharmacy channel control and clinical dossier capabilities as the decisive downstream levers.
For Market Incumbents: Lock in pharmacist-directed recommendation programs through point-of-sale educational investments that elevate clinically validated psyllium above generic fiber blends. Secure backward integration into organic inulin sourcing to defend margin position against commodity price volatility. Synthetic soluble fiber substitution and budget private label expansion threaten volume retention in mass-market tiers. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models integrating at-home microbiome testing for personalized fiber recommendations. Target pediatric applications as the most penetrable segment where early-life microbiome programming research validates parental purchase decisions. Exploit online retail channel expansion to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in fermentation biotechnology platforms with precision prebiotic pipelines and validated FOSHU dossiers. Long-term viability favors suppliers with clinical trial capabilities spanning Boston and Basel CRO networks. Watch EFSA Article 13.1 claim approval velocity as the inflection indicator for premium positioning sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Sourcing | Captive supply of organic inulin from European chicory farms insulates against raw material volatility. |
| Pharmacist Training Investment | Point-of-sale educational materials in Hamburg and Frankfurt pharmacy chains steer consumer selection toward validated brands. |
| Fermentation Capacity Scale-Up | Bioreactor infrastructure for human milk oligosaccharide analogs compresses cost curves against botanical extraction. |
| Direct-to-Consumer Platform Launch | Subscription models with microbiome test integration bypass retail slotting fees and capture recurring revenue. |
| FOSHU Regulatory Dossier Development | Specific Health Use approval in Japan enables premium positioning in aging-population digestive health segments. |
Methodological Framework
Independent corroboration across primary interviews with fiber supplement brand managers, pharmacy chain procurement directors, functional food R&D leads, and regulatory affairs specialists, combined with secondary validation through FDA labeling guidance documents, EFSA NDA panel opinions, FSSAI additive purity notifications, and customs trade flow data, underwrites the qualitative findings. Bottom-up volume triangulation against top-down market sizing ensures consistency across estimation approaches.
Rate-of-change decomposition separates volume growth from price realization across the analysis window, with segmentation modeling across product type, delivery form, end-user demographic, and distribution channel dimensions. CAGRs derive from trend extrapolation of historical consumption patterns adjusted for regulatory inflection points including FDA dietary fiber definition updates and EU Green Deal fortification mandates. Forecast inputs incorporate pharmacy channel expansion rates and fermentation technology adoption curves.
Monsoon crop failure, EFSA health claim rejection, and FDA-Codex Alimentarius definition divergence are the dominant revision risks. Deviation in regulatory harmonization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Africa Beta Glucan Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Global Digestive Enzymes Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
North America Dietary Supplements Market