
 CBD Nutraceuticals Market | 2026-2036
CBD Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Nutraceuticals Market Analysis
Hemp-derived isolate is recalibrating cost structures across CBD nutraceutical manufacturing as processors shift from full-spectrum extraction to refined cannabinoid concentrates. Charlotte's Web, Inc. leverages its seed-to-shelf vertical integration to control raw material quality across Colorado and Kentucky cultivation operations. CV Sciences, Inc. competes through its PlusCBD brand portfolio, which sustains broad retail distribution through mass-market pharmacy and natural product channels. Green Roads differentiates via pharmacist-formulated product lines that anchor its positioning in practitioner-recommended wellness segments.
CBD nutraceuticals encompass cannabidiol-infused dietary supplements formulated for oral or sublingual consumption, typically containing 5–50 mg of CBD per serving alongside carrier oils, terpenes, or synergistic botanical extracts such as melatonin or turmeric. These products undergo supercritical CO2 or ethanol extraction followed by winterization and decarboxylation to activate cannabinoid content, with standardization targeting consistent potency profiles for consumer safety and label claim verification. Oils and tinctures occupy the dominant revenue position due to established consumer familiarity and flexible dosing protocols, while gummies represent the fastest-expanding format as confectionery manufacturing expertise migrates into wellness applications. Sublingual delivery commands premium positioning based on rapid buccal absorption kinetics, whereas ingestion formats compete on convenience and palatability in mass-market retail.
The FDA maintains enforcement discretion over CBD dietary supplements pending formal rulemaking, while the 2018 Farm Bill de-scheduled hemp-derived cannabinoids with less than 0.3% THC, creating a bifurcated federal-state regulatory landscape that shapes interstate commerce and product liability exposure. EFSA novel food evaluations in Europe impose toxicological data requirements that filter market entrants by capital intensity and clinical documentation capacity. Stakeholders must monitor pending FDA regulatory pathways and state-level THC threshold variations to determine manufacturing location, distribution scope, and product formulation strategies.
Market Dynamics
The FDA's unresolved enforcement discretion over CBD dietary supplements creates a structural drag on interstate commerce, forcing manufacturers to navigate a patchwork of state-level THC thresholds and product liability exposures that shape formulation strategies and distribution scope.
Growth Catalysts
- Sports nutrition adoption:Athletic recovery programs across collegiate and professional leagues are integrating cannabidiol-infused formulations into post-training protocols, normalizing sublingual tinctures among competitive athletes.
- EFSA novel food pathway:Germany's structured authorization process under European Food Safety Authority guidelines has established a precedent for toxicological documentation that neighboring jurisdictions now reference.
- Supercritical CO2 refinement:Advanced extraction equipment is lowering winterization and decarboxylation costs for mid-scale processors, compressing batch-to-batch potency variance below 5%.
Market Restraints
- Hemp biomass input volatility:Colorado and Kentucky cultivation operations face weather-driven yield swings that transmit directly to isolate pricing, squeezing margin buffers for toll processors.
- THC threshold fragmentation:State-level variations in allowable trace cannabinoid content create interstate shipment barriers and force redundant testing protocols at each border.
- Clinical documentation gaps:EFSA toxicological data requirements filter market entrants by capital intensity, excluding smaller firms lacking GLP-certified laboratory partnerships.
Strategic Opportunities
- Practitioner channel expansion:Pharmacist-formulated product lines targeting wellness clinics and integrative medicine practices command premium positioning with recurring subscription models.
- Gummy format migration:Confectionery manufacturing expertise from established food technology hubs is transferring into CBD-infused edible production, opening mass-market retail placement.
- Federal rescheduling anticipation:Pending FDA rulemaking on dietary supplement classification could unlock institutional pharmacy distribution and employer-sponsored wellness program inclusion.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC and mass spectrometry specialists capable of validating cannabinoid potency profiles command compensation premiums that strain quality control budgets.
- Label claim verification timelines:Third-party certification through NSF International or USP requires 12-18 month documentation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Nutraceuticals Market |
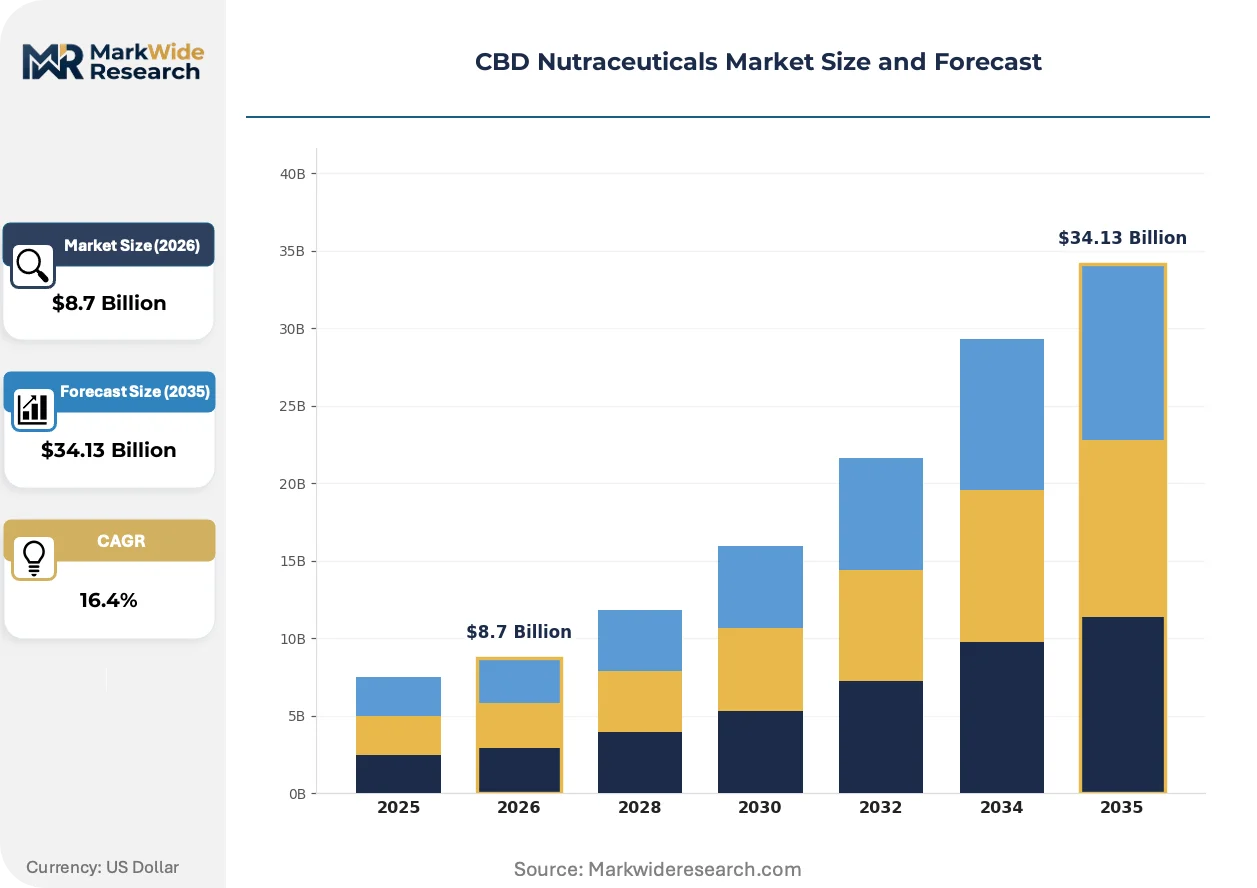
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Oils, Gummies, Tinctures Delivery Mode: Sublingual, Topical, Ingestion, Inhalation Customer Type: Health Conscious, Athletes, Seniors, General Wellness Application: Stress Relief, Pain Management, Sleep Support, Nutritional Supplement |
| Companies Covered | Charlotte's Web, Inc., Elixinol, CV Sciences, Inc., Medical Marijuana, Inc., Irwin Naturals, Diamond CBD, Green Roads, Medterra CBD, Foria Wellness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Nutraceuticals Market Emerging Trajectories
Formulation science and delivery mechanism engineering are compressing the gap between pharmaceutical-grade standards and consumer wellness products, with manufacturers investing in bioavailability enhancement and stability testing previously reserved for prescription drug development.
Nanoemulsion technology is decentralizing absorption efficiency benchmarks across oral CBD formats. Sports nutrition brands and clinical wellness programs are adopting lipid-based delivery systems at accelerating rates. This shift is decentralizing competitive advantage from raw material scale toward formulation intellectual property and pharmacokinetic documentation.
EFSA novel food evaluations are tightening toxicological documentation standards for CBD isolate imports into European Economic Area markets. The industrial consequence is a bifurcation between capital-intensive entrants with GLP laboratory partnerships and regional formulators dependent on toll manufacturing. German market participants are responding by consolidating captive cultivation and extraction assets to control documentation lineage from seed to finished good.
Buyer concentration among mass-market pharmacy chains is compressing supplier negotiation cycles and unbundling traditional distributor relationships. Natural product retailers and practitioner channels are being displaced by direct-to-pharmacy contracts with centralized formulary committees. This pattern is most visible in United States markets where CVS Health and Walgreens Boots Alliance have established dedicated CBD product review boards with 90-day qualification timelines.
CBD Nutraceuticals Market Segmentation
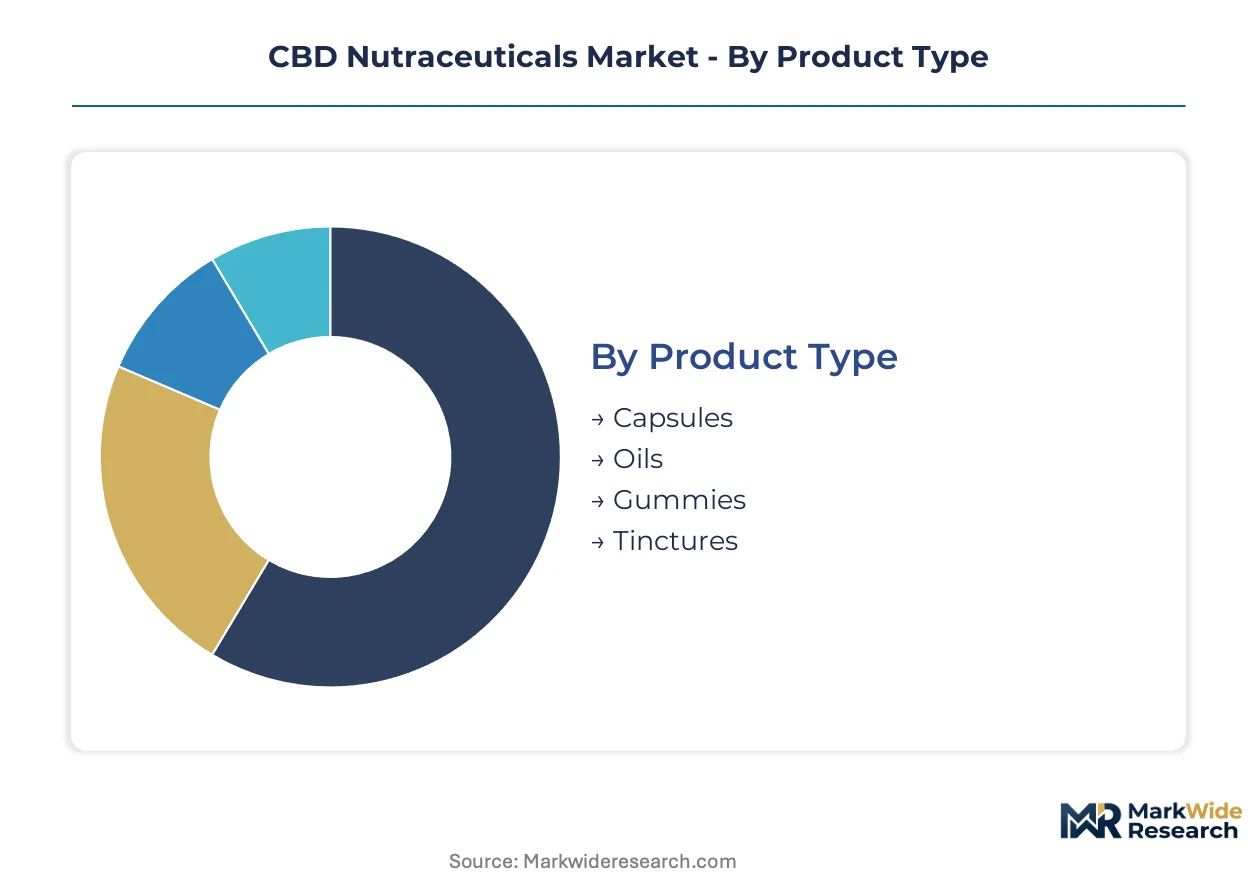
Product format selection directly determines manufacturing capital requirements, shelf stability protocols, and distribution channel access for CBD nutraceutical suppliers. Delivery mechanism engineering and customer targeting strategies further stratify competitive positioning across price tiers and regulatory exposure levels.
Product Type:
Consumer upgrade cycles from conventional wellness supplements to CBD-infused alternatives are compressing format innovation timelines as manufacturers race to match established supplement consumption rituals.
- Oils:Liquid formulations in amber glass bottles with calibrated droppers deliver 5–50 mg CBD per serving in carrier oils such as MCT or hemp seed oil. German pharmacy chains and US natural product retailers concentrate demand here, driven by established consumer familiarity with tincture dosing protocols and flexible titration for personalized regimens.
- Gummies:Confectionery-format edibles incorporate CBD isolate into pectin or gelatin matrices with flavor masking and precise 10–25 mg dosing per piece. Mass-market retail placement in US pharmacy chains and UK health food stores is accelerating, fueled by migration of food technology expertise from traditional candy manufacturing into wellness applications.
- Capsules:Softgel and hard-shell formats encapsulate CBD oil in gelatin or plant-based shells for taste-neutral ingestion with standardized dosing.
- Tinctures:Alcohol-based or glycerin extracts offer rapid sublingual absorption with extended shelf stability compared to oil-based alternatives.
Oils sit at the top of the volume ranking, with gummies climbing the fastest.
Delivery Mode:
Cost tier differentiation separates premium-positioned rapid-absorption formats from economy-oriented ingestion methods, with pricing stratification reflecting bioavailability documentation investments and equipment amortization schedules.
- Sublingual:Buccal membrane absorption bypasses first-pass hepatic metabolism, achieving onset within 15–30 minutes. Practitioner-recommended wellness programs and collegiate athletic recovery protocols in the United States and Germany favor this route, supported by pharmacokinetic studies documenting superior bioavailability versus ingestion.
- Ingestion:Gastrointestinal absorption through capsules, edibles, or beverages offers convenience and palatability at lower per-dose manufacturing cost. UK and Netherlands retail channels show strongest concentration, driven by mass-market consumers prioritizing format familiarity over absorption speed.
- Topical:Transdermal creams and balms target localized application with minimal systemic cannabinoid exposure.
- Inhalation:Vaporized CBD delivers rapid pulmonary absorption, though regulatory scrutiny in multiple jurisdictions constrains commercial expansion.
Ingestion commands the volume lead, while sublingual formats gain share fastest among clinically positioned product lines.
Customer Type:
Application-specific targeting aligns formulation strength, companion ingredients, and channel strategy with distinct wellness objectives and purchasing authority patterns.
- General Wellness:Maintenance-dose products with 5–15 mg CBD serve daily supplementation rituals alongside multivitamins and omega-3 regimens. US mass-market pharmacy and UK high-street health retailers concentrate demand, driven by normalization of hemp-derived ingredients in preventive health routines.
- Athletes:Post-training recovery formulations with 25–50 mg CBD plus anti-inflammatory botanicals target NCAA, professional league, and amateur endurance competitors. Collegiate athletic programs in Colorado, Oregon, and Germany are integrating these products into sanctioned recovery protocols, despite lingering WADA monitoring status for cannabinoids.
- Health Conscious:Organic-certified, full-spectrum, and terpene-retained products appeal to ingredient-discerning consumers with established supplement sophistication.
- Seniors:Low-dose, drug-interaction-screened formulations with pharmacist consultation support address polypharmacy concerns and sleep quality priorities.
General Wellness occupies the volume apex, with Athletes expanding most quickly as sports institutional acceptance advances.
Application:
Supply concentration in stress and sleep categories reflects raw material sourcing advantages for companion ingredients such as melatonin, L-theanine, and adaptogenic botanicals.
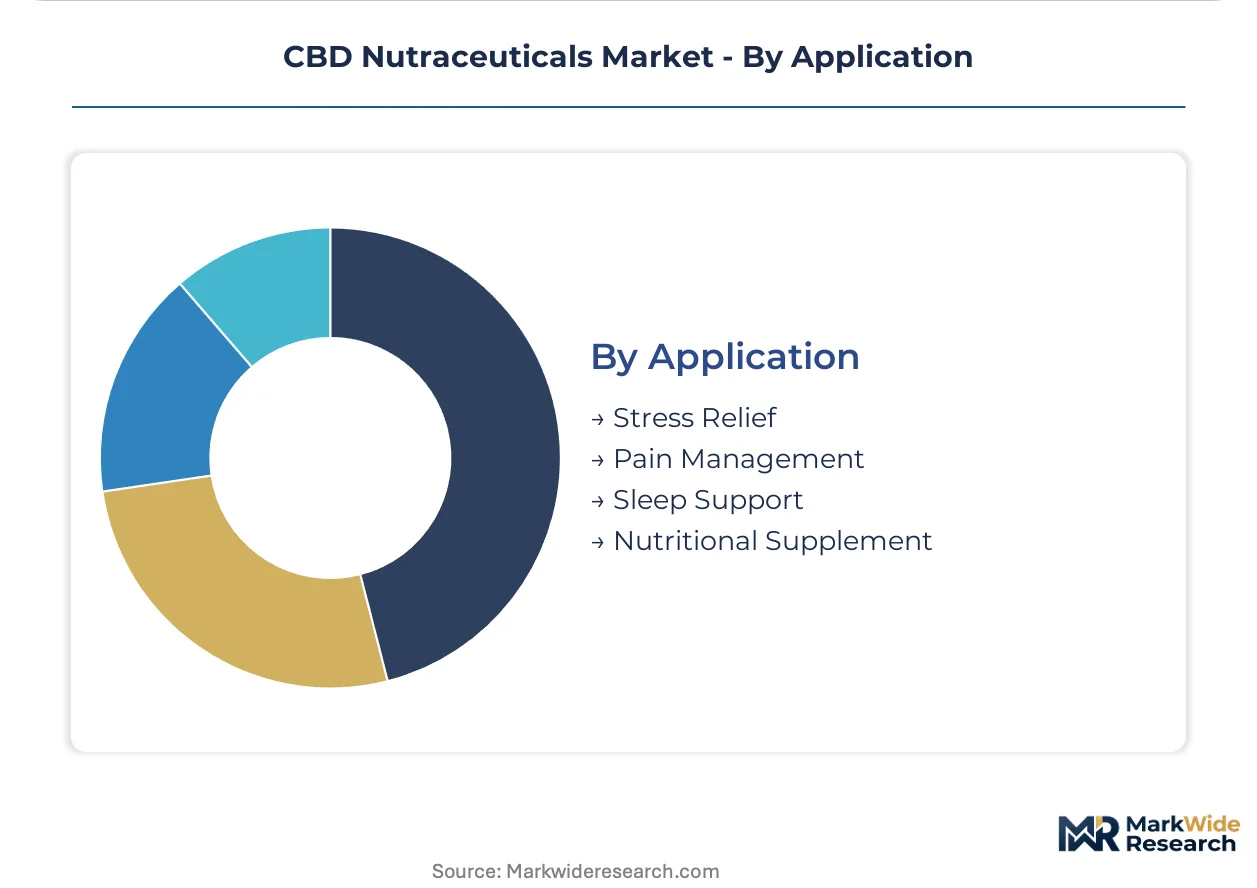
- Sleep Support:CBD-melatonin and CBD-magnesium combinations target circadian rhythm regulation with 10–30 mg evening doses. US direct-to-consumer subscription models and German pharmacy channels show strongest demand concentration, driven by documented consumer willingness to pay premium pricing for non-habit-forming alternatives to prescription sleep aids.
- Stress Relief:Adaptogen-combined formulations with ashwagandha or L-theanine address acute anxiety and chronic cortisol management. UK and California wellness clinic distribution is expanding, fueled by employer-sponsored mental health program inclusion and integrative medicine practitioner recommendations.
- Pain Management:Anti-inflammatory positioned products with turmeric or boswellia co-formulation target exercise recovery and age-related joint discomfort.
- Nutritional Supplement:General wellness positioning as a daily micronutrient equivalent alongside vitamins and minerals.
Sleep Support leads volume rankings, with Stress Relief demonstrating the steepest expansion trajectory among employer wellness program categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colorado's Front Range corridor anchors North American CBD nutraceutical manufacturing, hosting the densest concentration of supercritical CO2 extraction facilities and third-party testing laboratories serving both domestic and export markets.
United States
FDA enforcement discretion over dietary supplement classification shapes interstate commerce patterns, with manufacturers clustering in Colorado and Kentucky to leverage established hemp cultivation infrastructure. The 2018 Farm Bill's 0.3% THC threshold creates state-level fragmentation, forcing redundant testing protocols at each border crossing.
Germany
EFSA novel food authorization processes filter market entrants by toxicological documentation capacity, concentrating compliant product distribution through pharmacy chains in Berlin and Munich. Bavarian and North Rhine-Westphalian processors are consolidating captive cultivation assets to control seed-to-shelf documentation lineage.
United Kingdom
Food Standards Agency novel food validation requirements drive capital intensity barriers, with London and Manchester emerging as formulation centers serving stress-relief and sleep-support applications. High-street health retailers and direct-to-consumer subscription models concentrate demand in Greater London.
Netherlands
Opium Act exemptions for hemp-derived products with negligible THC content enable Rotterdam and Amsterdam to function as import and redistribution hubs for European Economic Area markets. Dutch toll processors specialize in gummy format manufacturing for UK and German brand owners.
Australia
TGA down-scheduling of low-dose CBD to pharmacist-only medicine status opens practitioner channel expansion, with Sydney and Melbourne hosting the primary distribution infrastructure. Victorian and New South Wales cultivation licenses are scaling to meet anticipated pharmacy formulary inclusion.
CBD Nutraceuticals Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents extend from core oils into gummies and capsule formats to secure mass-market retail placement. The vendor base clusters around three strategic archetypes: seed-to-shelf vertically integrated cultivators, toll-dependent formulators, and pharmacist-positioned wellness brands. Capacity expansion and third-party certification acquisition constitute the primary competitive moves, with NSF International and USP verification serving as retail gatekeeping mechanisms.
Within the vertically integrated tier, Charlotte's Web, Inc. and CV Sciences, Inc. exemplify upstream control strategies through captive Colorado and Kentucky cultivation operations. Green Roads occupies a distinct position among pharmacist-formulated specialists targeting practitioner-recommended wellness segments. These three entities represent contrasting responses to FDA regulatory uncertainty—vertical integration versus formulation differentiation versus channel specialization.
| Leading Market Players |
|---|
| Charlotte's Web, Inc. |
| Elixinol |
| CV Sciences, Inc. |
| Medical Marijuana, Inc. |
| Irwin Naturals |
| Diamond CBD |
| Green Roads |
| Medterra CBD |
| Foria Wellness |
| Others |
Supply Flow & Price Mechanics
Hemp biomass costs in Colorado and Kentucky cultivation zones transmit directly through toll processing contracts to finished isolate pricing tiers downstream. Weather-driven yield volatility in these states squeezes margin buffers for mid-scale processors unable to secure long-term offtake agreements with biomass suppliers.
Pricing Analysis
Input-cost pass-through from hemp biomass to finished CBD isolate operates through contract-based long-term offtake agreements and spot market purchases. Price differentiation stems from certification grade — NSF International or USP verification commands premium positioning — and volume scale, with mass-market pharmacy chains extracting favorable terms through centralized procurement. Pricing pressure stems from isolate oversupply as supercritical CO2 equipment deployment accelerates batch throughput. General wellness consumers in mass-market retail show highest price sensitivity, while practitioner-recommended sublingual formats retain pricing power among collegiate athletic programs.
Supply Chain Analysis
Freight costs from Colorado and Kentucky extraction facilities to US pharmacy distribution centers and Rotterdam redistribution hubs constitute a material share of landed product cost. Geographic supply concentration centers on the United States, Germany, and the Netherlands, with Dutch toll processors specializing in gummy format manufacturing for export markets. Raw material dependencies include hemp biomass, MCT carrier oils, and pectin or gelatin matrices for edible formats. Supply chain risk manifests as single-source vulnerability in supercritical CO2 equipment procurement from specialized German and Italian manufacturers. Distribution runs through direct-to-pharmacy contracts with centralized formulary committees displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in CBD nutraceuticals rests on supercritical CO2 cost compression and the premium-tier shift toward pharmacist-formulated, practitioner-channel positioning. The structural path to sustainable profitability favors upstream control and certification investment over commodity volume plays.
For Market Incumbents: Acquire captive extraction assets in Colorado or Kentucky to secure biomass supply lineage and isolate cost predictability. Consolidate GLP-certified laboratory partnerships to meet EFSA toxicological documentation requirements for European market access. Defend against toll-dependent formulators by locking in multi-year pharmacy chain formulary placements before FDA rulemaking clarifies dietary supplement classification.
For New Entrants and Emerging Players: The premium-economy price gap in sports nutrition recovery formulations offers white-space entry with 25–50 mg dose positioning below established clinical brands. Target collegiate athletic programs in Oregon and Colorado with subscription-model recovery protocols as institutional acceptance normalizes. Penetrate through direct-to-consumer channels with nanoemulsion bioavailability claims before mass-market retail gatekeeping hardens around third-party certification requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA novel food compliance costs exceed smaller formulators' capital access, creating acquisition opportunities for documented European market entrants. Long-term viability favors vertically integrated cultivators with seed-to-shelf traceability over toll-dependent brands exposed to isolate price volatility. Watch FDA dietary supplement rulemaking as the definitive inflection signal for institutional pharmacy distribution and employer wellness program inclusion.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Acquisition | Colorado and Kentucky hemp operations secure biomass cost predictability against weather-driven yield swings. |
| EFSA Novel Food Compliance Investment | GLP laboratory partnerships unlock German pharmacy chain distribution through toxicological documentation. |
| Practitioner Channel Expansion | Pharmacist-formulated lines command recurring subscription revenue from integrative medicine clinics. |
| Nanoemulsion Technology Deployment | Bioavailability enhancement differentiates sports nutrition positioning against conventional oil formats. |
| Direct-to-Pharmacy Contracting | CVS Health and Walgreens formulary placement bypasses traditional distributor margin extraction. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction facility operators, pharmacy chain formulary directors, sports nutrition brand managers, and regulatory affairs specialists with secondary validation. Primary sources included supercritical CO2 equipment manufacturers, third-party testing laboratories, and hemp cultivation cooperative representatives. Secondary data drew from FDA enforcement discretion memoranda, EFSA novel food evaluation registers, state-level THC threshold compilations, and pharmacy chain annual procurement disclosures. Bottom-up isolate production estimates and top-down retail channel revenue assessments were triangulated against trade flow data.
Comparable-period anchoring established baseline reference points across historical cultivation yield patterns and retail placement expansion trajectories. The analytical framework modeled segmentation dimensions spanning product format, delivery mode, customer type, and application across the projection horizon. CAGRs were derived from volume trajectory analysis incorporating hemp acreage expansion, extraction capacity deployment, and pharmacy channel penetration rates. Industry-specific forecast inputs included EFSA evaluation queue timing and FDA rulemaking probability assessments.
Caveats apply where FDA dietary supplement classification decisions, EFSA toxicological data requirement modifications, or state-level THC threshold harmonization could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Global Digestive Enzymes Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
Phytoceramide Supplement Market