
 Mood Support Supplements Market | 2026-2036
Mood Support Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Mood Support Supplements Market Analytics
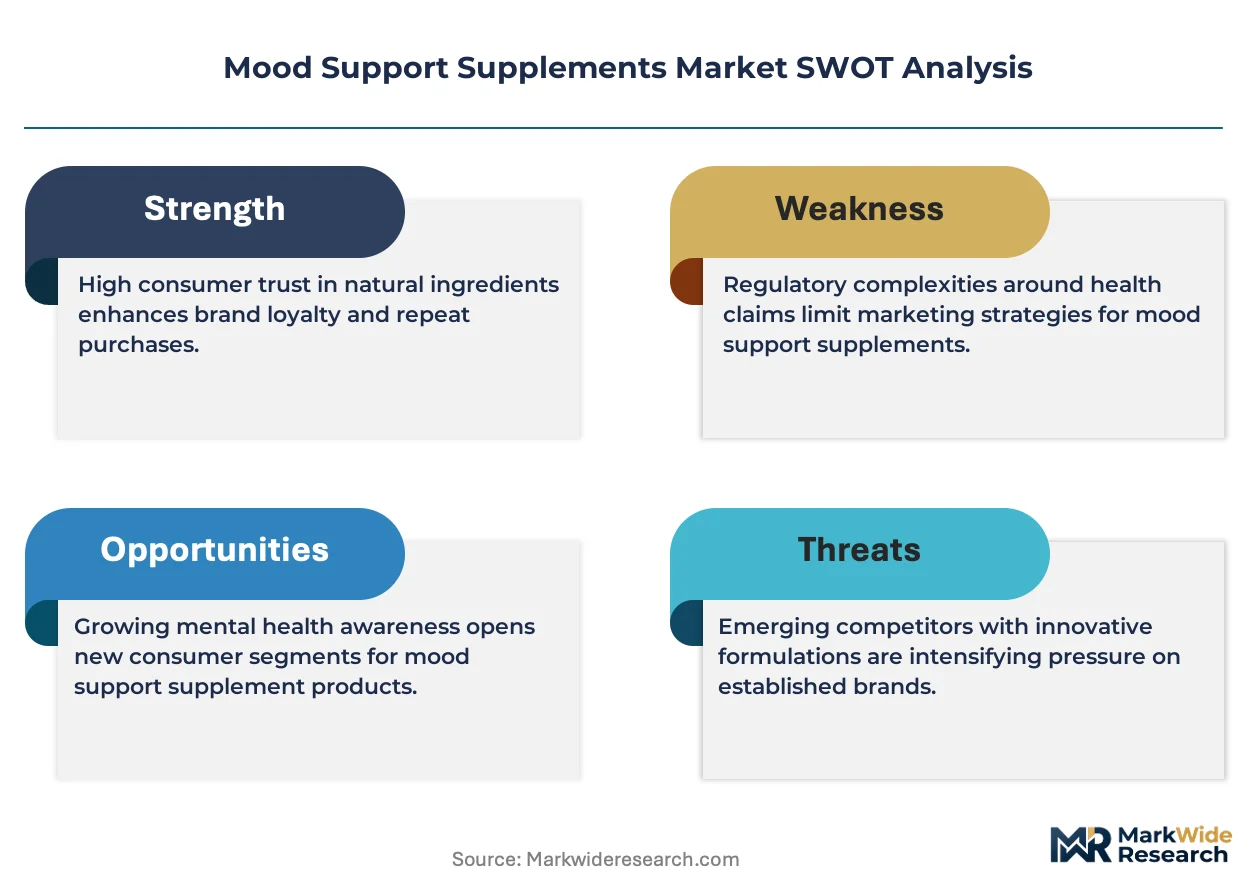
Corporate wellness procurement is decoupling from traditional employee assistance programs and redirecting toward preventive mental health portfolios. NOW Foods leverages vertical control over raw botanical sourcing to sustain margin stability across volatile herb markets. Thorne Research anchors its position through practitioner-exclusive distribution that restricts price-based competition. Garden of Life differentiates via third-party certifications that command premium positioning in retail channels.
Mood support supplements comprise bioactive compounds—primarily herbal extracts, amino acid precursors, and micronutrients—formulated to modulate neurotransmitter synthesis, HPA axis function, or circadian regulation. Standardized extraction ratios and marker compound verification determine batch consistency and therapeutic reliability. Herbal extracts occupy the deepest margin pools due to supply scarcity of authenticated raw materials and complex phytochemical profiling requirements. Amino acid segments register the fastest trajectory as consumers seek targeted serotonin and GABA pathway modulation. Capsule formulations dominate volume while gummies capture adolescent and senior expansion segments through palatability advantages.
The FDA exercises post-market surveillance authority under DSHEA while cGMP inspections enforce manufacturing quality benchmarks. The FTC monitors structure-function claims to prevent unsubstantiated efficacy assertions in direct-to-consumer advertising. Stakeholders must monitor enforcement priority shifts between New Dietary Ingredient notifications and aggressive warning letter campaigns as the agency recalibrates oversight bandwidth.
Market Dynamics
Workplace wellness procurement is redirecting capital from reactive employee assistance programs toward preventive adaptogenic portfolios, compressing traditional pharmaceutical intervention cycles and elevating botanical extraction standards.
Growth Catalysts
- DSHEA Modernization Debates:Congressional discussions around updating the 1994 Dietary Supplement Health and Education Act are creating compliance clarity that institutional buyers require for bulk procurement contracts.
- Urban Millennial Demand Concentration:Stress-management alternatives to prescription interventions are concentrating demand in United States metropolitan corridors, pulling venture capital into nootropic formulation startups.
- Adaptogenic Extraction Technologies:Supercritical CO2 and ethanol extraction methods are improving marker compound consistency, enabling therapeutic reliability claims that practitioner channels reward.
Market Restraints
- Authenticated Raw Material Scarcity:Supply concentration for certified organic ashwagandha and rhodiola in India and Siberia creates price volatility that compresses margin stability for mid-tier formulators.
- FTC Structure-Function Enforcement:Aggressive warning letter campaigns targeting unsubstantiated efficacy assertions in direct-to-consumer advertising are increasing legal review costs and delaying campaign launches.
- Prescription Anxiolytic Substitution:Generic SSRI accessibility and telehealth prescribing expansion present low-cost alternatives that constrain premium supplement pricing power in severe anxiety segments.
Strategic Opportunities
- Gummy Format Expansion:Palatability-driven delivery systems are capturing adolescent and senior adherence segments that capsule formulations historically abandoned.
- Practitioner-Exclusive Distribution:Clinical credentialing requirements create defensive moats against price-based competition while capturing insurance-adjacent reimbursement flows.
- Third-Party Certification Premiums:NSF International and USP verification protocols command retail shelf placement advantages that justify 15-40% price elevation in mass-market channels.
Industry Challenges
- Phytochemical Profiling Talent Scarcity:Analytical chemists capable of validating standardized extraction ratios and batch-to-batch marker consistency command compensation premiums that strain R&D budgets.
- New Dietary Ingredient Notification Backlogs:FDA review timelines for novel botanical compounds extend 12-18 months, freezing product pipeline velocity and eroding first-mover advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mood Support Supplements Market |
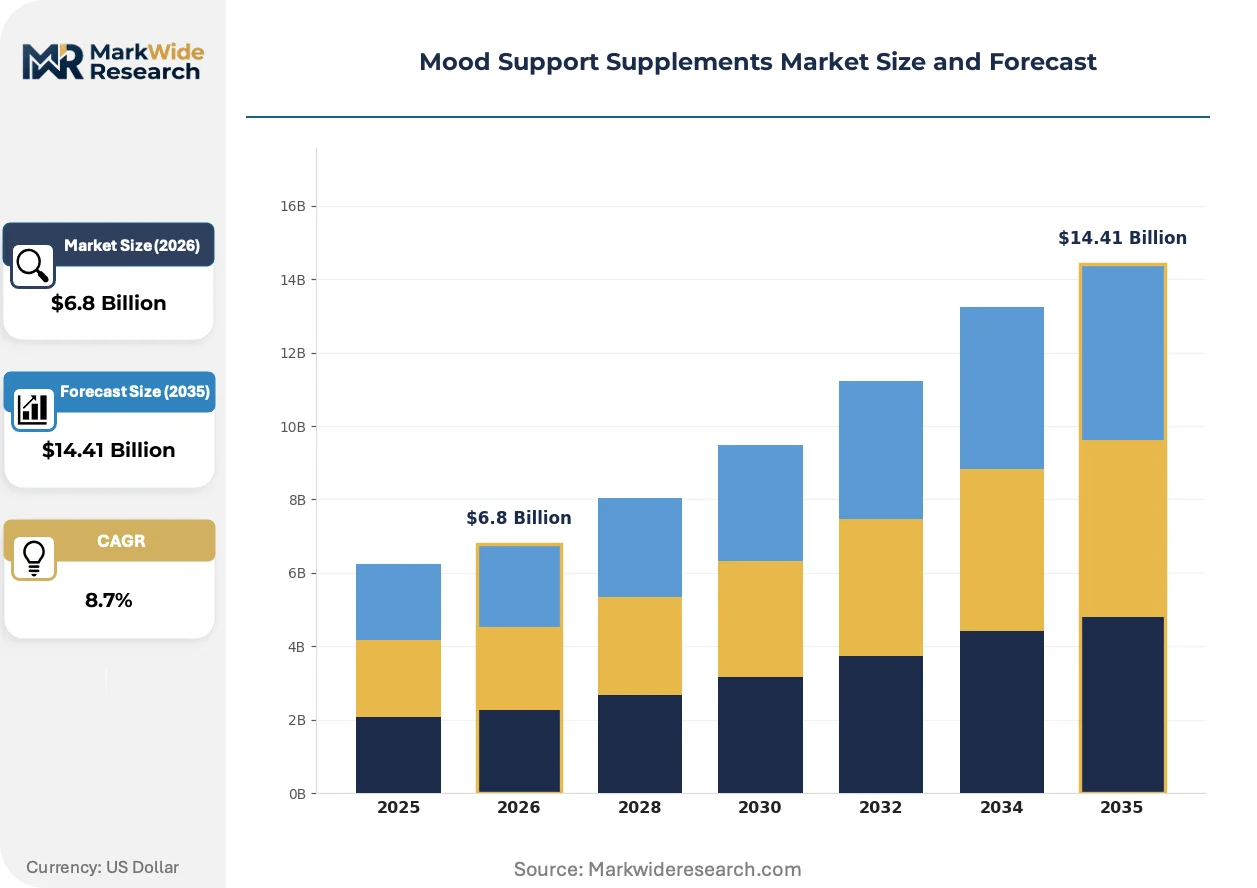
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Amino Acids, Vitamins, Minerals Formulation: Capsules, Powders, Gummies, Liquid End User: Adults, Seniors, Adolescents, Athletes Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Nature's Bounty, NOW Foods, Garden of Life, Gaia Herbs, Thorne Research, Life Extension, GNC, Solgar, Herbalife Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mood Support Supplements Market Evolving Landscape
Formulation science is converging with circadian biology research, repositioning mood support from acute symptom management toward chronobiological optimization. This shift is reshaping ingredient selection, dosing protocols, and channel positioning across the value chain.
Microencapsulation technology is absorbing volatile compounds like saffron extract and L-theanine, protecting bioactive integrity through gastric transit and enabling sustained-release kinetics. Functional food manufacturers are adopting these delivery systems at accelerating rates. The structural consequence is compression of traditional capsule volume share as beverage and bar formats capture convenience-oriented consumption occasions.
The FDA's evolving enforcement framework is prioritizing cGMP inspection frequency over NDI notification volume, redirecting manufacturer compliance investment toward manufacturing quality systems rather than novel ingredient pipelines. Dietary supplement contract manufacturers in California and Utah are responding by consolidating production into fewer, higher-capacity facilities that justify dedicated quality personnel.
Subscription direct-to-consumer models are displacing retail replenishment cycles, capturing recurring revenue through personalized dosing algorithms and biometric feedback integration. Urban millennials in Austin, Denver, and Brooklyn represent the densest adoption geography. This channel shift is forcing traditional brick-and-mortar retailers to unbundle point-of-sale consultation services as standalone revenue streams.
Mood Support Supplements Market Segmentation
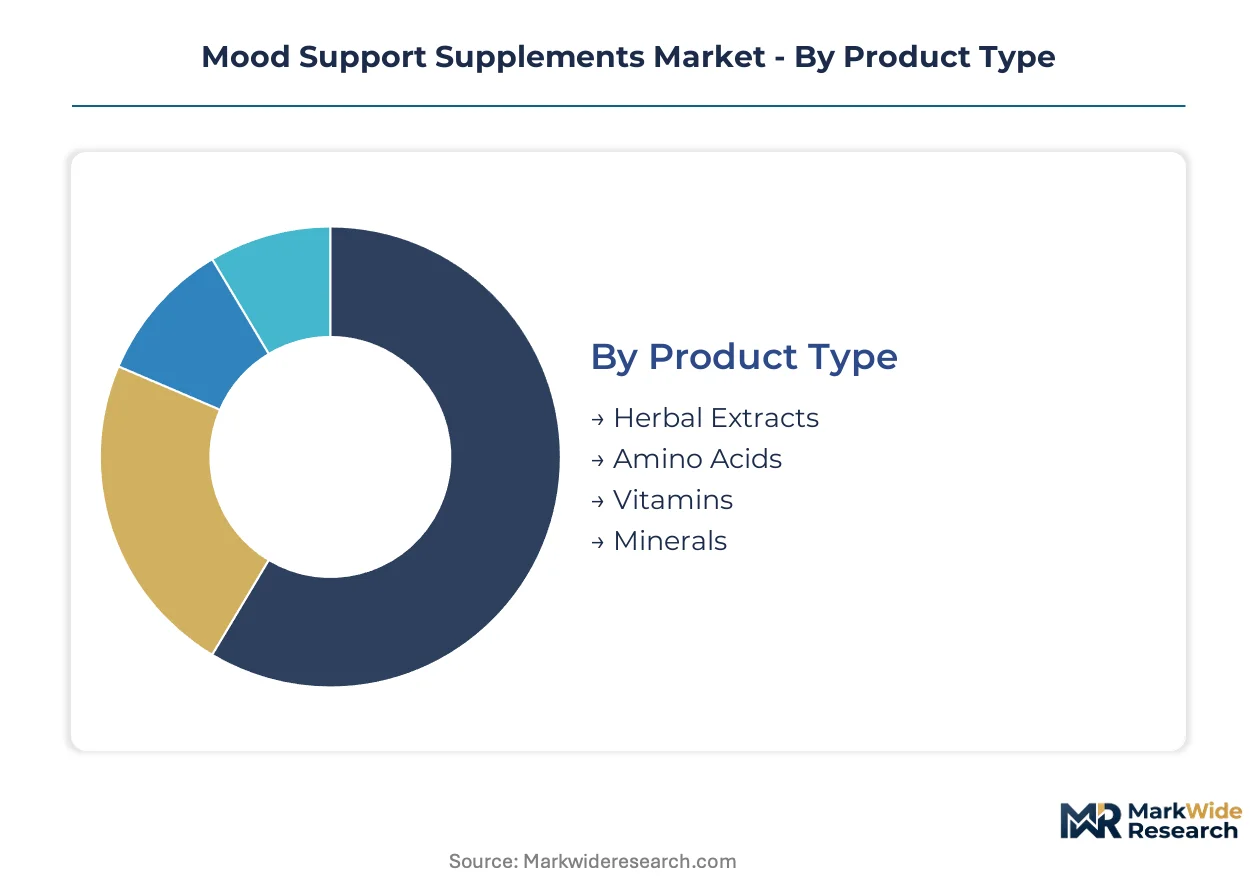
Segmentation in mood support supplements determines regulatory pathway complexity, margin architecture, and channel access. Certification requirements vary sharply across product categories, with herbal extracts demanding the most intensive phytochemical documentation while mineral formulations face simpler USP verification protocols.
Product Type:
Herbal extracts carry the heaviest certification burden through marker compound verification and DNA authentication protocols, while amino acids and vitamins navigate more streamlined USP or NSF pathways.
- Herbal Extracts:Standardized botanical compounds including ashwagandha, rhodiola, and saffron require complex phytochemical profiling and authenticated raw material chains. Demand concentrates among urban millennials in Austin and Brooklyn seeking alternatives to prescription anxiolytics, though supply scarcity in India and Siberia creates persistent price volatility.
- Amino Acids:Precursor compounds such as L-theanine, 5-HTP, and GABA modulate specific neurotransmitter pathways with measurable pharmacokinetic profiles. Athletes and biohackers in Denver represent the densest adoption geography, pulling venture capital into nootropic formulation startups targeting serotonin and GABA modulation.
- Vitamins:B-complex and D3 formulations support methylation and circadian regulation with established USP monographs simplifying compliance.
- Minerals:Magnesium and zinc compounds address HPA axis function through simpler regulatory pathways than botanical alternatives.
Herbal extracts sit at the top of the volume ranking, with amino acids climbing the fastest.
Formulation:
Manufacturing cost tiers separate capsule and powder formats at the economy end from gummy and liquid delivery systems commanding premium positioning through palatability-driven formulation complexity.
- Capsules:Gelatin and vegetable cellulose shells dominate volume through manufacturing efficiency and shelf stability. Adults constitute the core end-user segment, with practitioner-exclusive distribution channels in the United States rewarding therapeutic reliability claims.
- Gummies:Palatability-driven delivery systems capture adolescent and senior adherence segments through flavor masking and chewable formats. Supermarkets and online retail channels in metropolitan corridors justify 15-40% price elevation over capsule equivalents.
- Powders:Bulk formats serve athlete and biohacker segments with dosing flexibility and cost efficiency.
- Liquid:Sublingual and beverage formats enable rapid absorption claims for acute stress management occasions.
Capsules generate the highest absolute volume, while gummies gain share fastest among format-switching consumers.
End User:
Application intensity varies by life stage and physiological demand, with athletes requiring performance-optimized stacks and seniors prioritizing drug-interaction safety.
- Adults:Working-age professionals aged 25-45 drive baseline demand through workplace wellness procurement and direct-to-consumer subscription models. Corporate wellness programs in Austin, Denver, and Brooklyn are redirecting capital from employee assistance programs toward preventive adaptogenic portfolios.
- Seniors:Medication-aware formulations emphasizing drug-interaction safety and gentle onset kinetics. Gummy formats capture this segment through palatability advantages that capsule formulations historically abandoned.
- Adolescents:School-related stress management with parental oversight requirements shaping flavor and format preferences.
- Athletes:Performance-optimized stacks with NSF Certified for Sport or Informed Sport verification commanding premium positioning in specialty retail.
Adults constitute the largest addressable population, with athletes showing the steepest per-capita spending trajectory.
Distribution Channel:
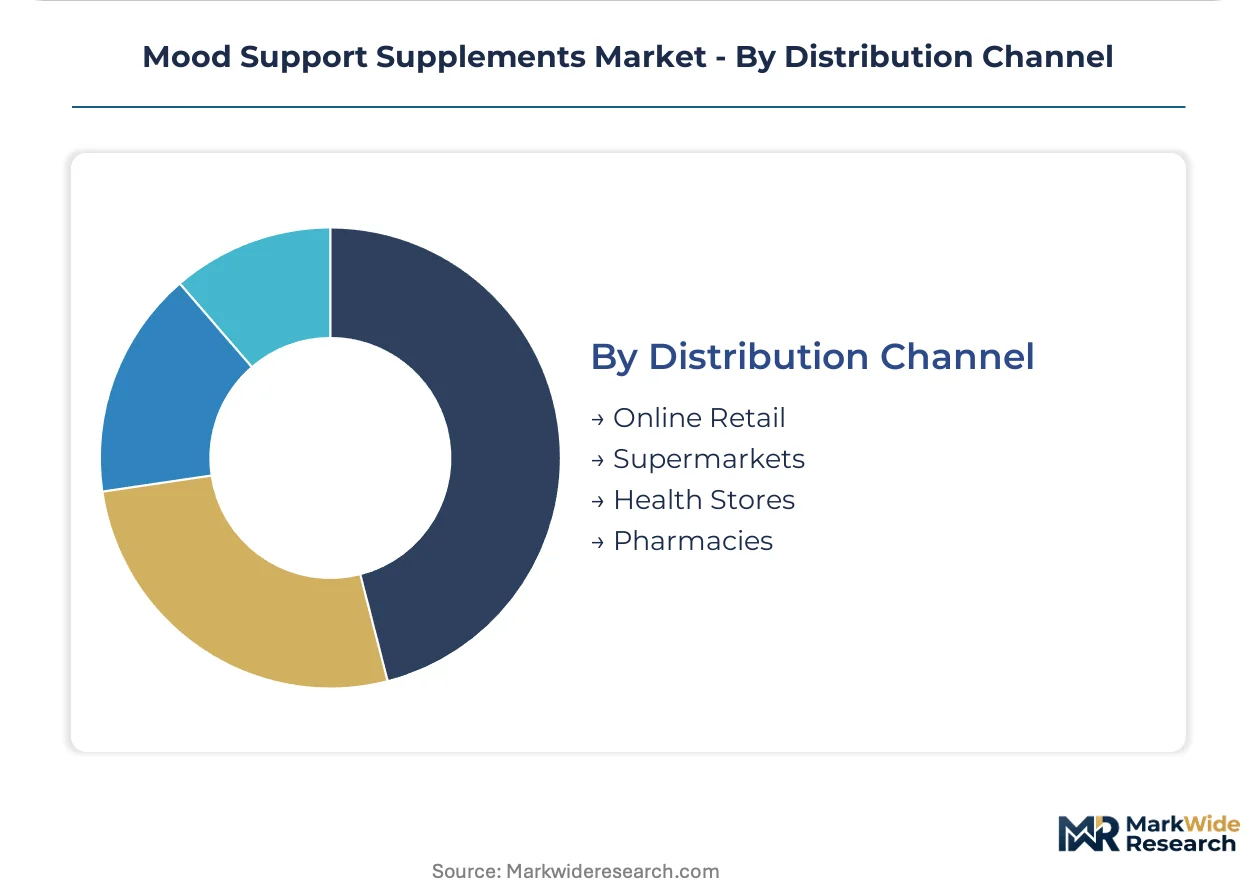
Channel concentration reflects consumer information needs and replenishment urgency, with health stores and pharmacies serving consultation-heavy purchases while online retail captures subscription-driven recurring revenue.
- Online Retail:Direct-to-consumer platforms with personalized dosing algorithms and biometric feedback integration capture recurring revenue. Urban millennials in Brooklyn and Austin represent the densest adoption geography, displacing traditional retail replenishment cycles.
- Health Stores:Practitioner-adjacent positioning with trained staff enabling structure-function claim explanation and third-party certification verification. NSF International and USP verification protocols command shelf placement advantages.
- Supermarkets:Mass-market accessibility for established brands with simplified claims and competitive unit economics.
- Pharmacies:Clinical credibility positioning adjacent to pharmaceutical interventions, with pharmacist consultation requirements creating defensive moats.
Online retail leads transaction volume, with health stores expanding fastest through practitioner channel integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting contract manufacturing capacity toward jurisdictions with lower cGMP compliance costs, while demand concentration in high-income markets pulls finished goods through specialized distribution channels. India and China capture upstream extraction and formulation activities, whereas the United States and Germany dominate value-added packaging and practitioner-channel distribution.
United States
Urban millennials in Austin, Denver, and Brooklyn drive demand for stress-management alternatives to prescription interventions. FDA post-market surveillance under DSHEA and escalating FTC structure-function enforcement reshape compliance investment priorities. California and Utah host consolidated contract manufacturing facilities that justify dedicated quality personnel under intensified cGMP inspection frequency.
Germany
Practitioner-channel preference for therapeutic reliability claims elevates botanical extraction standards among pharmacy-adjacent formulators. EFSA novel food assessments and BfArM borderline product classifications create regulatory clarity that institutional buyers require for bulk procurement. Bavaria and Baden-Württemberg concentrate phytochemical profiling laboratories serving central European distribution networks.
India
Supply scarcity of certified organic ashwagandha concentrates cultivation and primary processing in Maharashtra and Karnataka. FSSAI licensing requirements and Ayurveda export certification protocols govern raw material authentication for international buyers. Hyderabad and Bengaluru house analytical chemistry capacity validating standardized extraction ratios for export markets.
China
Domestic demand for nootropic formulations accelerates as middle-class consumers seek cognitive enhancement products. NMPA health food registration and SAMR advertising enforcement create compliance frameworks that diverge from Western regulatory models. Zhejiang and Jiangsu provinces integrate traditional medicine extraction with modern supercritical CO2 processing infrastructure.
Canada
Natural Health Product regulations under Health Canada establish pre-market licensing requirements that exceed DSHEA thresholds. British Columbia and Ontario concentrate direct-to-consumer subscription operations targeting cross-border United States demand. Vancouver and Toronto serve as logistics hubs for personalized dosing algorithm platforms with biometric feedback integration.
Mood Support Supplements Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with practitioner-exclusive channels rewarding therapeutic reliability claims while mass-market retail prioritizes unit economics. The vendor base organizes around three archetypes: vertically integrated botanical processors, practitioner-credentialed formulators, and subscription-native direct-to-consumer platforms. Consolidation pressures concentrate among mid-tier formulators facing raw material price volatility and extended FDA New Dietary Ingredient notification timelines. Dominant competitive moves include backward integration into authenticated raw material sourcing and capacity consolidation into fewer, higher-throughput manufacturing facilities.
Among practitioner-credentialed specialists, Thorne Research and Gaia Herbs exemplify distribution strategies that restrict price-based competition through clinical channel access. NOW Foods anchors the vertically integrated tier through captive supply chains that sustain margin stability across volatile herb markets. Garden of Life occupies a position within the certification-premium segment where third-party verification commands retail shelf placement advantages.
| Leading Market Players |
|---|
| Nature's Bounty |
| NOW Foods |
| Garden of Life |
| Gaia Herbs |
| Thorne Research |
| Life Extension |
| GNC |
| Solgar |
| Herbalife Nutrition |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap botanical processors in Maharashtra and Karnataka anchor raw material procurement, translating authenticated ashwagandha scarcity into disciplined pricing power that resists commoditization pressure from mass-market gummy entrants. This ownership structure feeds back into supply choices through captive cultivation relationships that preempt spot-market volatility.
Pricing Analysis
Distributor margin layers separate practitioner-exclusive channels commanding 35-50% markup from direct-to-consumer subscription models compressing intermediary take. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—NSF International and USP verification protocols justify 15-40% elevation over uncertified alternatives. Pricing pressure stems from generic SSRI accessibility through telehealth prescribing, constraining premium positioning in severe anxiety segments. Corporate wellness procurement exhibits lowest price sensitivity due to insurance-adjacent reimbursement flows, while adolescent gummy segments face highest elasticity.
Supply Chain Analysis
Freight cost absorption from Siberian rhodiola and Indian ashwagandha concentrates elevates landed costs for North American formulators, compressing margin stability at mid-tier processors. Supply draws from India, China, and Siberia for authenticated botanicals, with amino acid precursors sourcing from Chinese fermentation infrastructure and German pharmaceutical-grade synthesis. Raw material dependencies center on certified organic rootstock, supercritical CO2 extraction equipment, and validated analytical chemistry capacity. Single-source vulnerability runs through Maharashtra ashwagandha cultivation zones facing climate volatility. Distribution runs through practitioner-exclusive channels, direct-to-consumer subscription platforms, and health store retail tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mood support supplements rests on extraction technology cost-down curves and certification-premium tier migration, as supercritical CO2 standardization reduces batch failure rates while third-party verification commands shelf placement premiums.
For Market Incumbents: To counter subscription-native platform encroachment in urban millennial segments, anchor practitioner-exclusive distribution through clinical credentialing requirements that restrict price-based competition, and consolidate manufacturing into fewer, higher-capacity facilities in California and Utah that justify dedicated FDA cGMP quality personnel under intensified inspection frequency. For New Entrants and Emerging Players: Begin with gummy format white space in senior adherence segments that capsule formulations historically abandoned, targeting medication-aware drug-interaction safety positioning. Capture adolescent school-related stress management through palatability-driven flavor innovation, leveraging parental oversight requirements as trust-building channel. Deploy direct-to-consumer subscription models with personalized dosing algorithms in Austin, Denver, and Brooklyn corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier formulators facing raw material price volatility and extended FDA New Dietary Ingredient notification timelines. Five-to-ten year viability favors vertically integrated botanical processors with captive supply chains or practitioner-credentialed specialists with insurance-adjacent reimbursement access. Monitor FDA enforcement priority shifts between NDI notification volume and cGMP inspection frequency as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Authenticated Sourcing | Captive cultivation in Maharashtra and Karnataka insulates margin stability from certified organic ashwagandha scarcity. |
| Practitioner-Exclusive Distribution Expansion | Clinical credentialing requirements create defensive moats against price-based competition in United States metropolitan corridors. |
| Gummy Format Manufacturing Scale-Up | Palatability-driven delivery systems capture adolescent and senior adherence segments abandoned by capsule formulations. |
| Third-Party Certification Investment | NSF International and USP verification protocols command retail shelf placement advantages justifying premium positioning. |
| Subscription Platform Technology Development | Personalized dosing algorithms with biometric feedback integration displace traditional retail replenishment cycles. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with formulation scientists, corporate wellness procurement directors, practitioner channel managers, and dietary supplement contract manufacturing executives with secondary validation through FDA warning letter databases, FTC enforcement archives, NSF International certification registries, and customs trade data for authenticated botanical imports.
Historical trendline analysis across therapeutic reliability claim evolution and format preference shifts informs projection architecture. Segmentation dimensions modeled include product type, formulation, end user life stage, and distribution channel intensity. CAGRs derive from fitted growth curves reconciled against regulatory pathway velocity and channel penetration saturation thresholds. Forecast inputs incorporate DSHEA modernization legislative tracking and supercritical CO2 extraction capacity expansion trajectories.
Caveats apply where FDA enforcement recalibration between NDI notifications and cGMP inspections, authenticated raw material climate disruption, or telehealth prescribing regulatory expansion could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Africa Nutraceutical Market
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Raspberry Ketones Market