
 Pulse Products Market | 2026-2036
Pulse Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pulse Products Market Outlook
Organic certification under USDA National Organic Program standards is collapsing the supplier base for premium pulse derivatives, favoring processors with verified farm-to-facility traceability. Cargill leverages its North American origination network to secure identity-preserved yellow pea streams for protein fractionation. Roquette Frères anchors European supply through its dedicated pulse protein extraction complex in France. AGT Food and Ingredients dominates Canadian lentil processing with vertically controlled cleaning and splitting operations.
Pulse products encompass dried, edible seeds of leguminous crops—principally lentils, chickpeas, peas, and beans—typically containing 20-25% protein by dry weight and processed through milling, fractionation, or whole-seed cleaning for food, feed, and ingredient applications. Lentils and chickpeas sustain the highest margin pools in retail-packaged formats where origin labeling and quick-cooking varieties command price premiums. Peas lead growth in industrial applications, particularly protein isolate and starch extraction for plant-based meat analogues. The flour production segment competes on functional protein content, with specialty mills differentiating through particle size distribution and water absorption specifications tailored to bakery and extrusion customers.
FDA food facility registration and FSMA preventive controls requirements shape import access for foreign pulse processors serving the United States, while EU REACH and F-Gas Regulation govern solvent use and emissions in European protein extraction facilities. India's FSSAI fortification standards and PLI scheme for food processing infrastructure redirect domestic capacity toward value-added pulse derivatives. Stakeholders must monitor evolving allergen labeling thresholds for pulse proteins in major import jurisdictions and calibrate certification investments against shifting customer procurement gatekeeping.
Market Dynamics
EU Green Deal sustainability standards are collapsing the supplier base for premium pulse derivatives by mandating verified farm-to-facility traceability, forcing processors to rebuild origination networks around carbon-accounted sourcing corridors.
Growth Catalysts
- Plant-based protein adoption:Food manufacturers are reformulating meat analogues around yellow pea and fava bean isolates to meet clean-label requirements from retail chains.
- India's PLI scheme for food processing infrastructure:Domestic capital subsidies are redirecting capacity toward value-added pulse derivatives and reducing import dependency for split and milled products.
- FSSAI fortification standards:Mandatory micronutrient enrichment in school feeding programs is creating institutional offtake for protein-dense pulse flours.
Market Restraints
- Input cost volatility:Fertilizer and freight cost spikes from Black Sea corridor disruptions are compressing margins for commodity-grade whole pulse traders.
- Supply concentration risk:Canadian and Australian lentil origination dominates global exportable surplus, exposing buyers to weather-driven volume shocks.
- Regulatory friction:EU REACH registration requirements for novel protein extraction solvents are extending facility commissioning timelines by 18-24 months.
Strategic Opportunities
- Underpenetrated African markets:Urbanization in Nigeria and Ethiopia is accelerating demand for quick-cooking lentil formats that bypass traditional overnight soaking.
- Regulatory tailwind:USDA National Organic Program certification is creating premium price pools for identity-preserved organic chickpea streams in North American retail.
- Technology convergence:Dry fractionation paired with membrane filtration is enabling simultaneous protein-starch separation without hexane solvent use.
Industry Challenges
- Skill gap in protein analytics:Commercial laboratories capable of validating functional properties in pulse isolates remain scarce outside Rotterdam and Winnipeg.
- Capex intensity:Food-grade protein extraction facilities require stainless steel contact surfaces and cleanroom environments that multiply capital costs versus feed-grade operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulse Products Market |
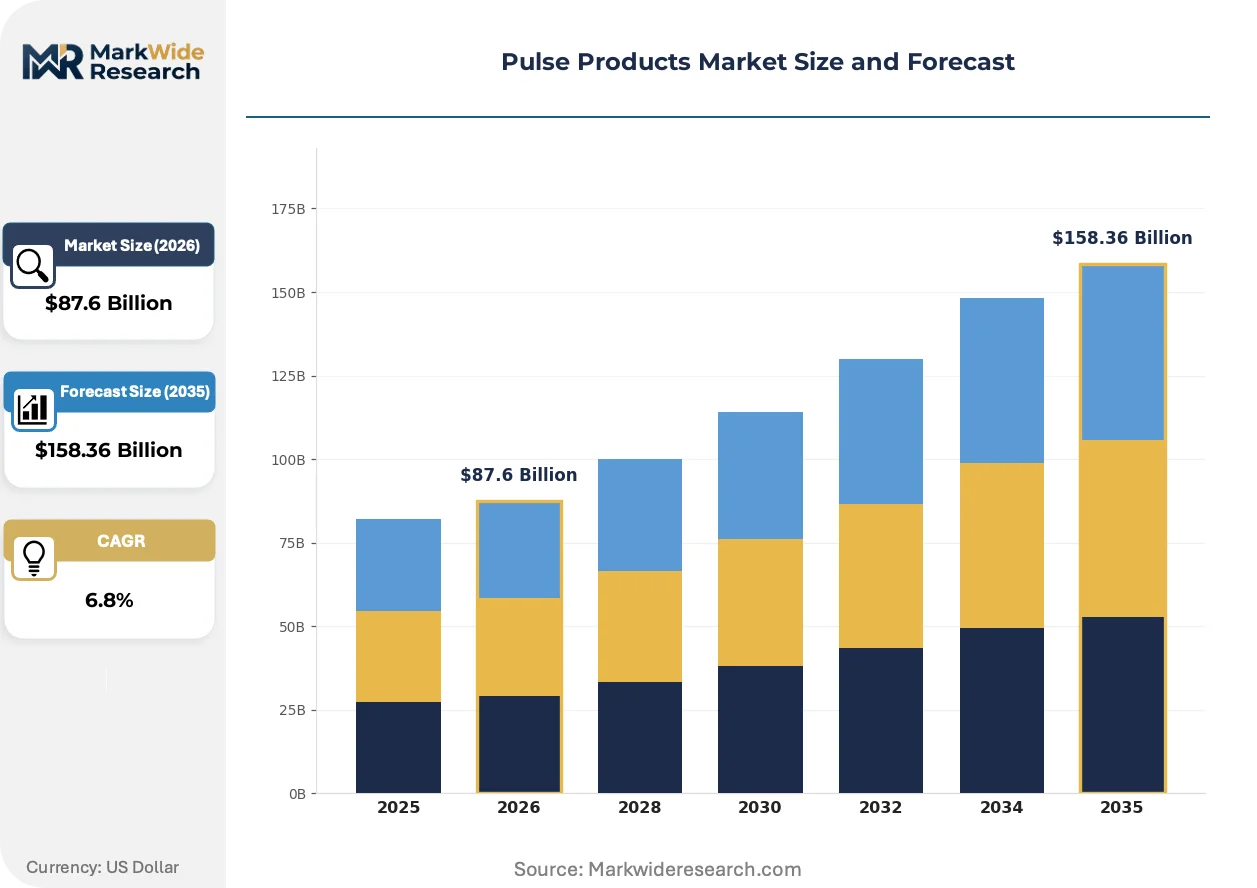
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lentils, Chickpeas, Peas, Beans End Use: Food Industry, Feed Industry, Snacks, Flour Production Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores Packaging Type: Bags, Cans, Vacuum Packs, Bulk Packaging |
| Companies Covered | AGT Food and Ingredients, Cargill, Olam International, Archer Daniels Midland Company, Ingredion Incorporated, Roquette Frères, Beneo GmbH, Glanbia Plc, Adani Wilmar Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulse Products Market Strategic Shifts
Processing technology and procurement protocols are rewriting competitive advantage in pulse derivatives, with sustainability verification and functional performance now inseparable from commercial viability.
Dry fractionation using pin milling and air classification is supplanting wet extraction for mid-protein concentrate production. Plant-based meat startups in California and the Netherlands are adopting these lower-capital systems to secure 55-60% protein ingredients without solvent handling permits. The shift is compressing the addressable market for traditional wet-fractionation specialists while fragmenting supply across regional toll processors.
EU F-Gas Regulation phase-down schedules are forcing protein extraction facilities to abandon hydrofluorocarbon-based refrigeration in favor of ammonia or CO2 systems. French and Dutch processors face 2027 deadlines for equipment replacement that will idle capacity during retrofit windows. The regulatory pressure is accelerating consolidation toward facilities with capital reserves to absorb compliance-driven downtime.
Identity-preserved contracting is displacing spot-market purchasing for premium pulse streams. European ingredient buyers now require lot-level DNA verification and carbon intensity scoring that spot brokers cannot deliver. The behavioral shift is most visible in German and Swiss bakery ingredient procurement, where reformulation cycles now begin 18 months ahead with designated origination partners rather than commodity suppliers.
Pulse Products Market Segmentation
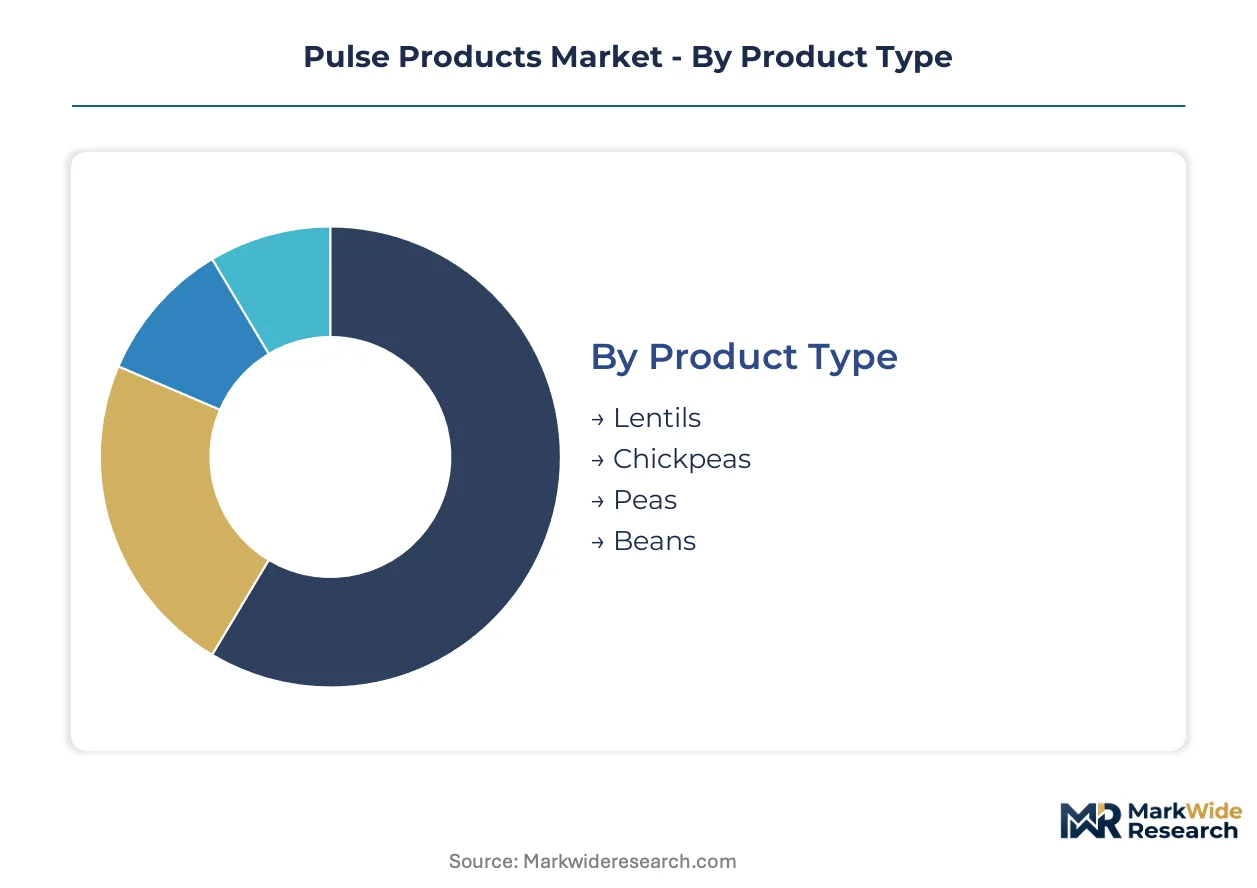
Pulse product value pools fragment across four structural dimensions, with protein content and processing intensity determining margin capture. Understanding segment boundaries reveals where identity-preserved sourcing commands premiums versus commodity trading.
Product Type:
Margin pools concentrate in protein-rich varieties where fractionation economics favor isolate extraction, while whole-seed retail competes on origin branding and convenience formats.
- Peas:Yellow and green pea varieties contain 20-25% protein by dry weight, making them the preferred feedstock for isolate and concentrate production. Demand is concentrating in Dutch and Californian plant-based meat facilities where Roquette and emerging toll processors secure identity-preserved streams for clean-label analogues. Wet and dry fractionation investments are accelerating around Portage la Prairie and Lethbridge processing clusters.
- Lentils:Red and green lentil segments sustain premium pricing in quick-cooking retail formats where Saskatchewan and Australian origin labeling supports brand positioning. Indian domestic consumption anchors volume offtake, with government procurement programs absorbing significant split and whole red lentil supply for subsidized distribution networks.
- Chickpeas:Kabuli and desi types dominate Middle Eastern and South Asian culinary applications, with size grading determining export tier placement.
- Beans:Kidney, black, and navy bean varieties serve institutional foodservice and canning operations with lower protein recovery economics than pea fractionation.
The dominant share belongs to peas, while lentils are closing the gap fastest on retail premiumization and Indian government procurement expansion.
End Use:
Application economics separate ingredient-grade protein streams from whole-seed commodity trading, with regulatory fortification mandates creating institutional volume anchors.
- Food Industry:Plant-based meat manufacturers in the Netherlands and California reformulate around pea and fava bean isolates to meet retailer clean-label requirements. Wet fractionation facilities face EU REACH solvent registration delays that extend commissioning timelines.
- Flour Production:Specialty mills differentiate through particle size distribution and water absorption specifications tailored to German and Swiss bakery customers. Protein content certification drives procurement gatekeeping in premium gluten-free and high-protein bakery segments.
- Snacks:Roasted and extruded pulse formats gain shelf space in North American natural channel retail, with flavor innovation and texture claims supporting price positioning.
- Feed Industry:Dehulled and processed pulse meals compete with soybean meal in European and Canadian aquaculture and poultry rations, with digestibility coefficients determining formulation inclusion rates.
Food industry applications command the value premium, though flour production is expanding most quickly on FSSAI fortification mandates in Indian school feeding programs.
Distribution Channel:
Channel selection determines traceability requirements and margin retention, with direct procurement relationships displacing spot-market intermediation in premium segments.
- Supermarkets:Origin-labeled retail packs with quick-cooking claims sustain price premiums in German, Swiss, and North American grocery channels where consumer willingness-to-pay for convenience and provenance remains elevated.
- Wholesale:Bulk shipments to food manufacturers and institutional buyers concentrate volume in containerized and break-bulk formats, with identity-preserved contracting replacing spot purchasing for protein isolate feedstock.
- Online Retail:Direct-to-consumer pulse and specialty flour sales accelerate in urban Indian and Nigerian markets where traditional retail penetration remains limited.
- Specialty Stores:Organic and ethnic grocery channels in North America and Europe stock heritage varieties and small-lot origin pulses at substantial markups over commodity equivalents.
Supermarkets retain the largest volume share, while wholesale channels are gaining ground fastest on processor-direct contracting for ingredient-grade streams.
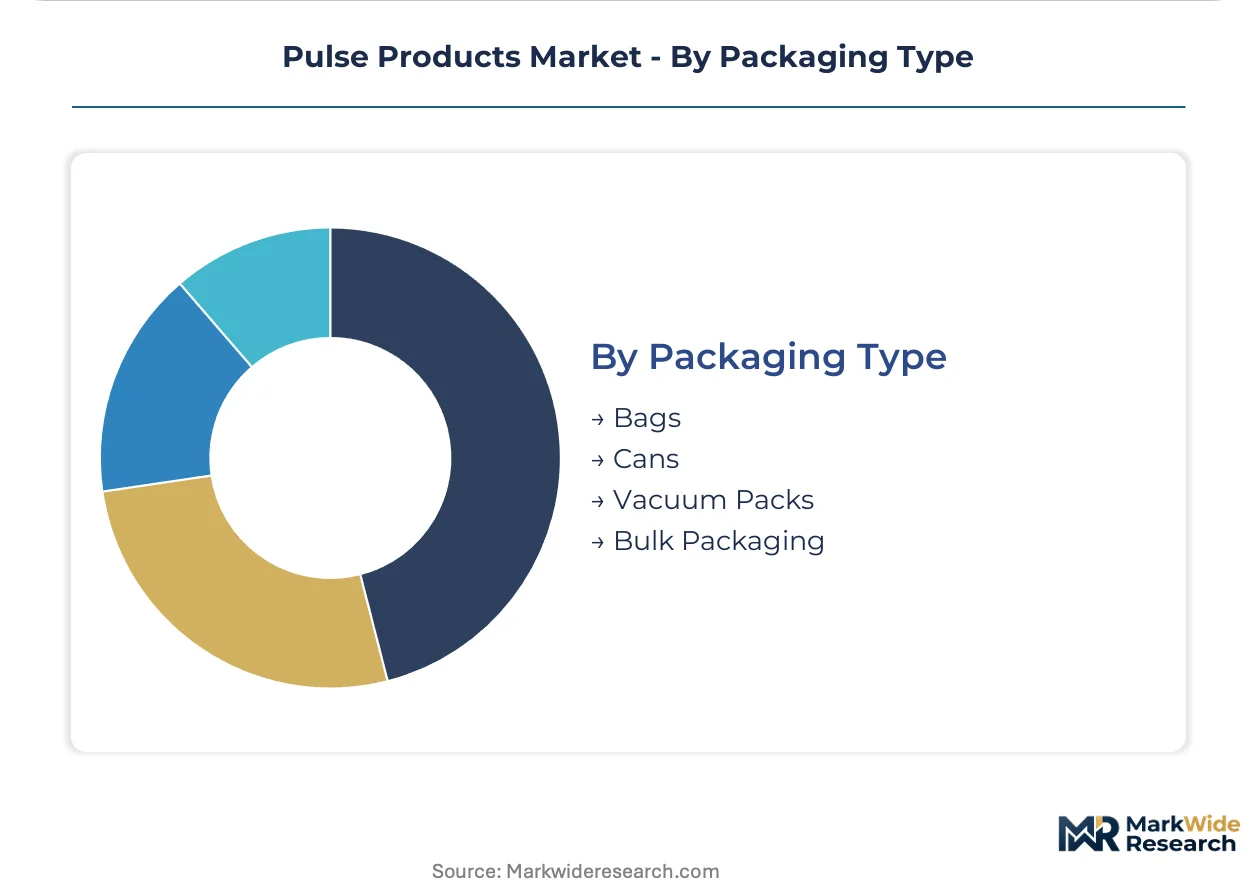
Packaging Type:
Packaging investment separates retail-branded premium positioning from commodity bulk handling, with shelf-life extension technologies enabling geographic market expansion.
- Bags:Multi-layer laminate and paper-based retail bags dominate North American and European grocery shelf presentation, with resealability and portion-control features supporting brand differentiation.
- Vacuum Packs:Oxygen-barrier packaging extends shelf stability for premium organic and quick-cooking lentil formats, enabling distribution to humid climate markets where traditional packaging fails.
- Bulk Packaging:Polypropylene totes and containers serve food manufacturing and foodservice procurement, with lot-level traceability coding satisfying EU Green Deal and USDA organic verification requirements.
- Cans:Pre-cooked and ready-to-serve pulse products capture convenience-oriented segments in North American and European retail, though metal packaging costs constrain margin expansion.
Bags hold the prevailing volume position, yet vacuum packs are advancing most rapidly on extended shelf-life demands in African and Southeast Asian export markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient buyers in plant-based meat manufacturing, fortified flour procurement, and quick-cooking retail formats drive geographic demand concentration. Government-backed agricultural programs and sustainability verification requirements reshape sourcing corridors across major producing and consuming nations.
India
FSSAI fortification standards and PLI scheme subsidies redirect domestic processing capacity toward protein-dense pulse derivatives for school feeding programs. Government procurement networks absorb significant split red lentil volumes through subsidized distribution channels. Processing clusters in Gujarat and Madhya Pradesh expand cleaning and splitting operations to capture PLI-backed infrastructure incentives.
United States
USDA National Organic Program certification creates premium price pools for identity-preserved organic chickpea streams in retail channels. FDA food facility registration and FSMA preventive controls shape import access for foreign processors serving American food manufacturers. California and Midwest plant-based meat startups drive pea protein isolate demand through toll processing relationships.
Canada
Saskatchewan and Alberta lentil origination dominates global exportable surplus, exposing buyers to weather-driven volume shocks. Canadian pulse processors leverage vertically controlled cleaning operations to secure premium positioning in quick-cooking retail formats. Portage la Prairie and Lethbridge processing clusters attract fractionation investments for protein-starch separation capacity.
France
EU F-Gas Regulation phase-down schedules force protein extraction facilities to abandon hydrofluorocarbon refrigeration by 2027. Roquette Frères anchors European supply through its dedicated pulse protein extraction complex. Northern French processors face compliance-driven downtime during ammonia system retrofits, accelerating consolidation toward capital-reserved facilities.
Australia
Red lentil exports from southern growing regions compete with Canadian supply for Middle Eastern and South Asian destination markets. Australian processors differentiate through origin labeling and quality grading systems that command premiums in retail-branded formats. Victorian and South Australian handling facilities invest in lot-level traceability coding to satisfy EU Green Deal verification requirements.
Pulse Products Market Competitive Environment
Player mix skews toward integrated agricultural processors with origination networks and specialized ingredient manufacturers with fractionation capabilities. Market structure exhibits tiered consolidation where large-scale traders coexist with regional toll processors. Dominant archetypes include vertically integrated origination-to-ingredient processors, dedicated protein extraction specialists, and diversified agricultural conglomerates with pulse portfolios. Competitive moves center on identity-preserved contracting relationships and capacity expansion in low-solvent fractionation technology.
Within the integrated processor tier, Cargill leverages its North American origination network to secure identity-preserved yellow pea streams, while Roquette Frères occupies a position as a European protein extraction anchor through its dedicated French facility. AGT Food and Ingredients exemplifies the regional specialist archetype with vertically controlled Canadian lentil operations. These three entities represent distinct competitive positions spanning global trading, European ingredient supply, and North American specialty processing.
| Leading Market Players |
|---|
| AGT Food and Ingredients |
| Cargill |
| Olam International |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Roquette Frères |
| Beneo GmbH |
| Glanbia Plc |
| Adani Wilmar Limited |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of inventory cover across European pulse protein facilities compresses pricing power during Canadian harvest windows, tightening the feedback loop between Saskatchewan origination delays and Rotterdam spot premiums. This inventory-to-origination dynamic rewards processors with backward integration into farm-level contracting while exposing spot-dependent traders to margin volatility.
Pricing Analysis
Cost-plus contracts indexed to Winnipeg Commodity Exchange lentil futures dominate Canadian-Australian export corridors, with protein content premiums and EU Green Deal carbon intensity scores driving price differentiation. Three-tier pricing structure across premium, standard, and economy levels separates identity-preserved organic chickpeas from commodity splits and feed-grade screenings. Pricing pressure stems from Black Sea fertilizer cost pass-through into farmgate economics, with quick-cooking retail formats showing least price sensitivity due to convenience-driven consumer loyalty.
Supply Chain Analysis
Strait of Hormuz transit underwrites Middle Eastern chickpea import security, yet Canadian, Australian, and Indian origination anchors global exportable surplus for lentils and peas. Processing draws from Saskatchewan cleaning facilities, French protein extraction complexes, and Indian PLI-subsidized splitting operations. Single-source vulnerability concentrates in Canadian lentil exports during drought cycles. Distribution runs through Rotterdam bulk terminals for European ingredient manufacturers and Mumbai-JNPT corridor for Indian domestic fortification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulse product markets trace agricultural commodity cycles with fertilizer cost normalization and plant-based protein demand recovery now converging to lift processor margins from cyclical troughs.
For Market Incumbents: Consolidate origination networks through identity-preserved contracting with Saskatchewan and Australian growers to lock in premium retail streams before EU Green Deal traceability mandates harden. Acquire toll fractionation capacity in Portage la Prairie or Lethbridge to capture pea protein isolate demand from California plant-based meat manufacturers facing solvent permitting delays.
For New Entrants and Emerging Players: Lead with quick-cooking lentil formats targeting Nigerian and Ethiopian urban retail where traditional overnight soaking requirements limit penetration. Partner with Indian FSSAI-compliant fortification suppliers to access institutional offtake from school feeding programs, bypassing established commodity trading channels.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium play because EU carbon-accounting requirements and USDA organic certification are structurally collapsing the supplier base for verified pulse derivatives. Target mid-cap Canadian processors with captive Saskatchewan origination and EU REACH-compliant extraction assets. Watch ammonia refrigeration retrofit timelines at French and Dutch facilities as inflection signals for capacity-constrained pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Level Contracting | Identity-preserved origination secures EU Green Deal-compliant traceability premiums for Rotterdam processors. |
| Dry Fractionation Technology Deployment | Pin milling and air classification bypass REACH solvent registration delays for California plant-based meat startups. |
| Ammonia Refrigeration Retrofit | F-Gas Regulation compliance at French facilities prevents 2027 capacity idling versus stranded HFC-dependent competitors. |
| Indian PLI Scheme Utilization | Gujarat and Madhya Pradesh processing clusters capture government subsidies for value-added pulse derivative capacity. |
| Quick-Cooking Format Innovation | Humid-climate vacuum packaging extends shelf stability for Nigerian and Ethiopian urban distribution networks. |
Study Parameters
Desk research of customs trade databases, EU REACH registration filings, and FSSAI fortification standards preceded structured interviews with pulse processing plant managers, ingredient procurement leads at Dutch plant-based meat manufacturers, Canadian agricultural origination specialists, and Indian food processing infrastructure planners. Primary fieldwork validated secondary data from USDA National Organic Program certification records and Saskatchewan crop insurance filings. Bottom-up volume estimates triangulated against top-down protein demand projections across the analysis window.
Variance decomposition across product type, end-use application, and distribution channel dimensions shaped the analytical framework, with pea isolate demand, lentil retail premiumization, and Indian government procurement modeled as distinct growth vectors. CAGRs derived from historical volume trajectories adjusted for PLI scheme capacity additions and EU F-Gas Regulation compliance timelines. Forecast inputs incorporated fertilizer cost pass-through elasticity and plant-based meat formulation substitution rates.
Forecasts assume regulatory continuity in EU Green Deal implementation, USDA organic certification standards, and Indian PLI scheme disbursement schedules; material policy shifts would require re-modeling origination economics and premium tier viability. Practitioners should keep alternative scenarios live as Black Sea corridor stability and ammonia refrigeration retrofit completion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Europe Nutraceutical Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Red Yeast Rice Market