
 North America Omega-3 Products Market | 2026-2036
North America Omega-3 Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Omega-3 Products Market Analytics
Algal-derived DHA is decoupling North American omega-3 supply chains from volatile fishmeal economics, creating new margin structures for finished goods. DSM-Firmenich leverages its biotechnology platform to sustain fermentation-based EPA output at commercial scale. Aker BioMarine anchors Antarctic krill oil supply through its vertically controlled harvesting fleet. Abbott Laboratories competes in clinical nutrition with prescription-grade omega-3 formulations for cardiovascular risk management.
Omega-3 products encompass concentrated sources of eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA), typically delivered at potencies ranging from 300 mg to over 1,000 mg per serving unit, extracted via molecular distillation or supercritical CO2 processing for oxidation-sensitive lipid stabilization. These formulations serve cardiovascular, cognitive, prenatal, and anti-inflammatory therapeutic endpoints across human and animal health applications. Fish oil maintains volume leadership in dietary supplements, though algal oil captures the fastest expansion as vegan and sustainably sourced positioning commands retail price premiums. Krill oil occupies a concentrated margin pool in premium health stores and direct-to-consumer channels, differentiated by phospholipid-bound absorption claims.
The FDA's qualified health claims and the EPA's fisheries sustainability assessments jointly shape raw material sourcing legitimacy and finished product market access across the United States. Health Canada regulates natural health product licensing through site-specific good manufacturing practice audits and label claims substantiation. Stakeholders must monitor evolving EPA fisheries stock assessments and Health Canada label modernization initiatives to secure long-term formulation and positioning flexibility.
Market Dynamics
Fermentation-based algal oil production is restructuring North American omega-3 supply economics, decoupling finished goods pricing from volatile wild-catch fishmeal markets and enabling vegan-certified positioning at retail.
Growth Catalysts
- FDA Qualified Health Claims Framework:Cardiovascular benefit labeling for EPA and DHA continues expanding permissible marketing channels for dietary supplement and functional food manufacturers across the United States.
- Aging Demographics in Sun Belt States:California, Florida, and Texas concentrate demand for cognitive and heart health formulations among consumers over 55 seeking preventive nutrition protocols.
- Supercritical CO2 Extraction:This oxidation-sensitive lipid stabilization process enables higher-potency concentrates exceeding 1,000 mg per serving unit for pharmaceutical-grade applications.
Market Restraints
- Anchovy and Sardine Catch Volatility:Peruvian and Chilean fisheries supply concentration exposes raw material costs to El Niño-driven stock fluctuations and quota restrictions.
- Health Canada Licensing Timelines:Site-specific good manufacturing practice audits and label claims substantiation create 18-24 month regulatory friction for new natural health product entries.
- Algal Oil Production Scale Constraints:Fermentation capacity bottlenecks limit commercial EPA output to specialty applications despite superior sustainability credentials.
Strategic Opportunities
- Clinical Nutrition Protocols:Hospital and long-term care facilities in Ontario and Quebec present underpenetrated channels for prescription-grade omega-3 formulations targeting cardiovascular risk management.
- Direct-to-Consumer Subscription Models:Krill oil phospholipid-bound absorption claims support premium pricing through personalized nutrition platforms bypassing traditional retail markup structures.
- EPA Fisheries Sustainability Assessments:Stakeholders leveraging positive stock assessments gain sourcing legitimacy and finished product market access differentiation.
Industry Challenges
- Omega-3 Oxidation Chemistry Expertise:Molecular distillation and encapsulation process engineering talent scarcity constrains quality control at mid-tier contract manufacturers.
- Health Canada Label Modernization Compliance:Evolving natural health product regulations demand continuous reformulation investment to maintain license validity.
- Multi-Source Raw Material Integration:Blending fish, krill, and algal oils into stable finished goods requires complex supply chain orchestration and certificate-of-analysis reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Omega-3 Products Market |
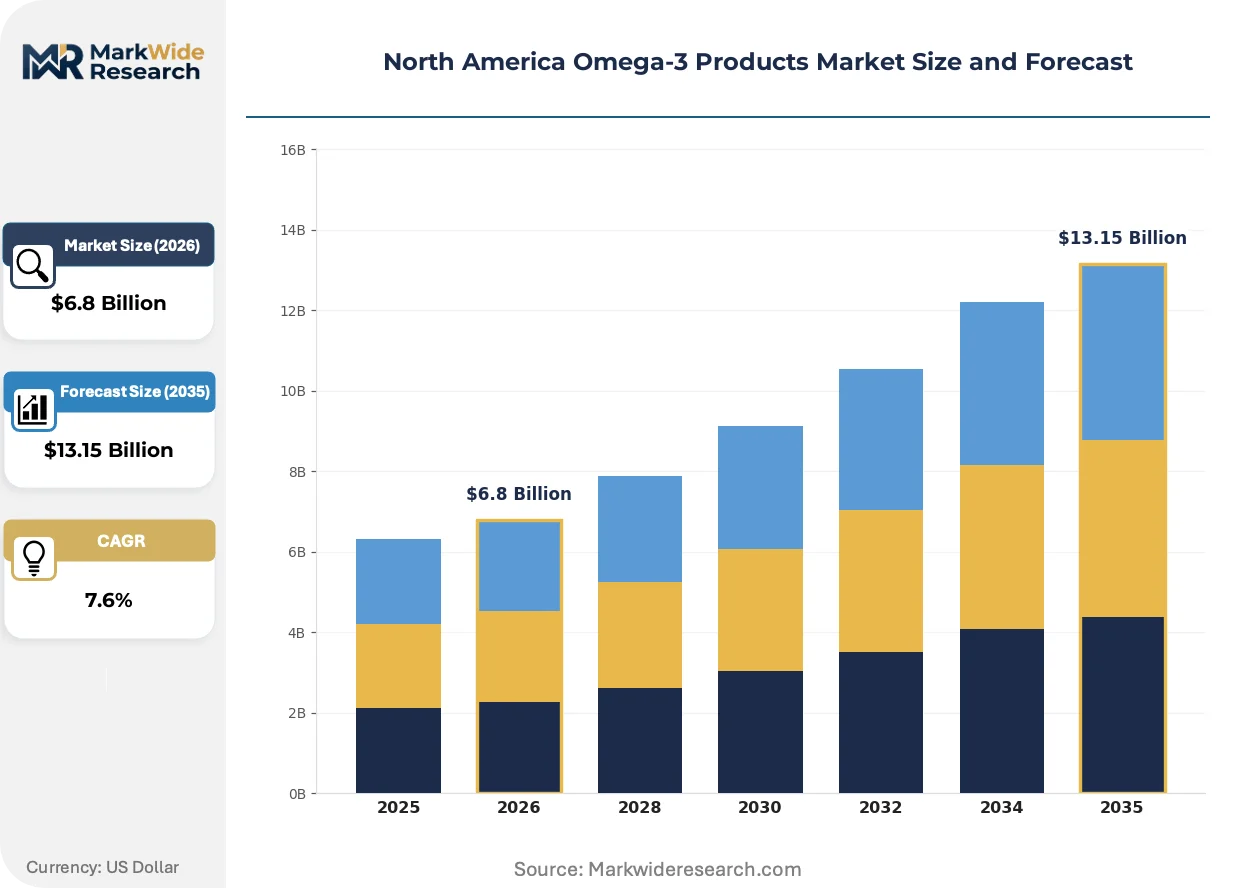
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Algal Oil, Krill Oil, Flaxseed Oil Application: Dietary Supplements, Fortified Foods, Pharmaceuticals, Animal Feed Distribution Channel: Online Retail, Health Stores, Supermarkets, Pharmacies Customer Type: Health-Conscious Consumers, Athletes, Pregnant Women, Seniors |
| Companies Covered | Unilever, Abbott Laboratories, GNC, Herbalife Nutrition, Amway Corp, BASF SE, Aker BioMarine, Croda International, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Omega-3 Products Market Evolving Landscape
Biotechnology platforms and regulatory science are converging to transform how North American omega-3 products are manufactured, certified, and distributed across human and animal health verticals.
Algal-derived DHA and EPA from fermentation bioreactors is overtaking traditional marine extraction for vegan-positioned supplements and infant formula applications. Dietary supplement brands targeting sustainability-conscious millennials and Generation Z consumers are adopting algal oil at accelerated procurement rates. This biotechnology shift is compressing reliance on wild-catch fisheries while enabling price premiums of 40-60% above standard fish oil concentrates.
The FDA's qualified health claims framework for omega-3 fatty acids continues validating cardiovascular benefit labeling with expanded permissible language for reduced coronary heart disease risk. This regulatory clarity permits broader marketing claims for EPA and DHA concentrates in dietary supplements and functional foods. Manufacturers are responding by reformulating toward higher EPA ratios to align with FDA-recognized evidence thresholds.
Subscription-based direct-to-consumer distribution is displacing mass-market retail for premium omega-3 segments. Personalized nutrition platforms using biomarker testing and AI-driven dosing recommendations are capturing high-margin repeat purchasers seeking clinical-grade potencies. This channel rotation is most visible in California and New York metro areas where telehealth-integrated supplement prescribing has gained regulatory traction.
North America Omega-3 Products Market Segmentation
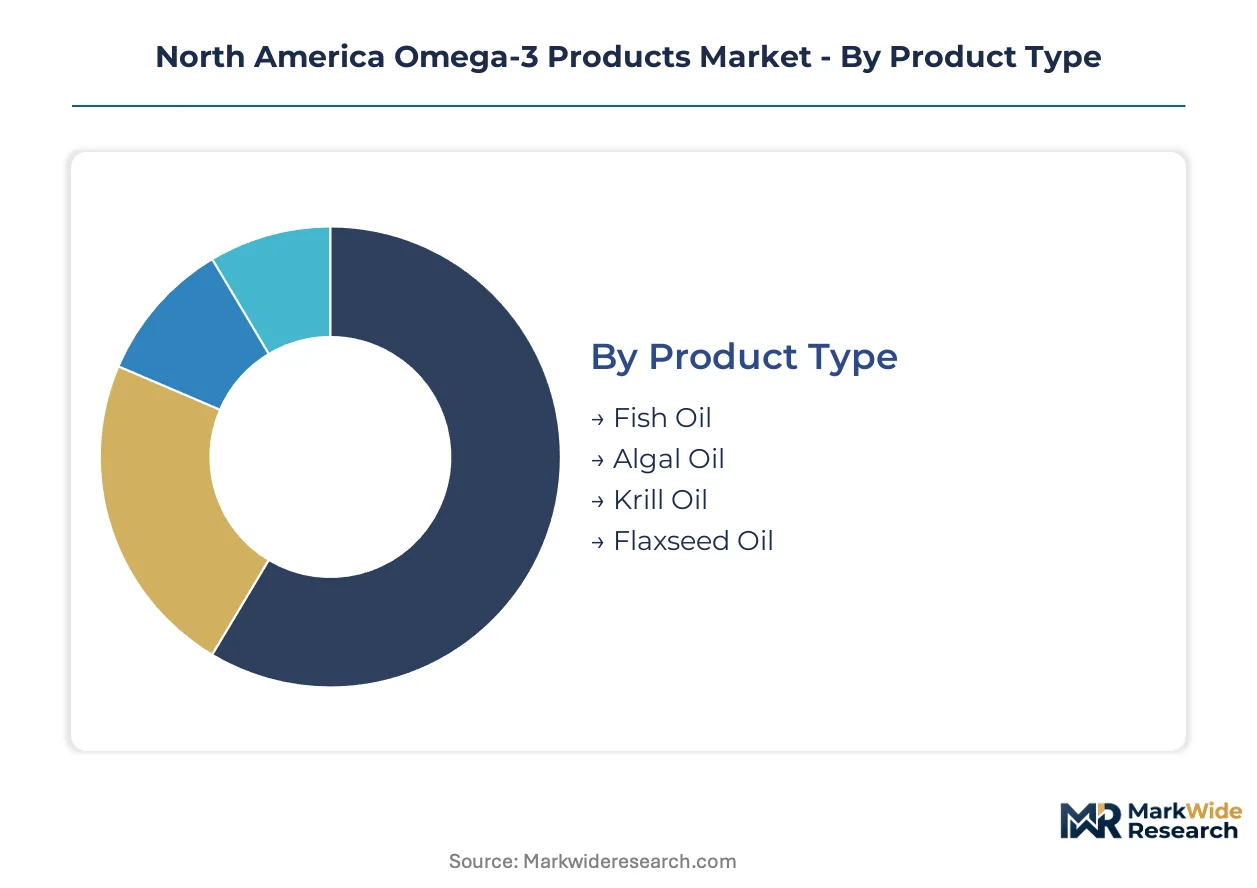
Omega-3 product segmentation in North America reflects divergent supply economics and regulatory pathways across marine, algal, and plant-derived sources. Each category channels distinct margin structures, certification requirements, and consumer positioning strategies that shape manufacturer portfolio allocation.
Product Type:
Fish oil dominates volume throughput while algal oil commands the steepest price premiums, creating a bifurcated competitive landscape across mass-market and specialty retail tiers.
- Fish Oil:Concentrated EPA and DHA extracts from anchovy, sardine, and mackerel fisheries, processed via molecular distillation or supercritical CO2 for oxidation stability. Demand concentrates in California and Florida among consumers over 55 seeking cardiovascular support, with supply exposed to Peruvian catch volatility under EPA fisheries assessments.
- Algal Oil:Fermentation-derived DHA and emerging EPA outputs from biotechnology platforms, carrying vegan certification and 40-60% retail premiums above fish oil. California and New York metro areas show the fastest adoption among sustainability-positioned millennials and Generation Z consumers.
- Krill Oil:Phospholipid-bound omega-3s from Antarctic harvesting operations, differentiated by absorption claims in premium health stores and direct-to-consumer channels.
- Flaxseed Oil:Plant-derived ALA precursor requiring enzymatic conversion to EPA/DHA, serving vegetarian-positioned formulations with lower bioavailability profiles.
Mature deployment sits with fish oil. Newer deployment is concentrated in algal oil.
Application:
Channel economics separate clinical-grade formulations from commodity nutrition, with prescription pathways demanding distinct regulatory substantiation and manufacturing controls.
- Dietary Supplements:Softgel, liquid, and gummy delivery formats ranging from 300 mg to 1,000+ mg serving potencies, dominating consumer-direct procurement through online retail and health stores. FDA qualified health claims for cardiovascular benefit labeling expand permissible marketing language across United States distribution.
- Pharmaceuticals:Prescription-grade EPA and DHA concentrates exceeding 1,000 mg per unit, requiring FDA drug approval or Health Canada natural health product licensing for cardiovascular risk management protocols in hospital and long-term care settings.
- Fortified Foods:Microencapsulated omega-3 powders integrated into dairy alternatives, infant formula, and functional beverages, facing oxidation stability challenges during thermal processing.
- Animal Feed:Aquaculture and pet nutrition applications, with algal DHA gaining traction in premium pet food positioning and sustainable aquafeed formulations.
Volume concentration rests with dietary supplements. Margin expansion is climbing the fastest in pharmaceuticals.
Distribution Channel:
Channel selection determines pricing architecture and consumer relationship depth, with digital platforms capturing repeat purchase loyalty at the expense of traditional retail markup structures.
- Online Retail:Subscription-based direct-to-consumer models leveraging biomarker testing and AI-driven dosing recommendations, concentrated in California and New York where telehealth-integrated supplement prescribing has gained regulatory traction under FDA enforcement discretion.
- Health Stores:Premium positioning for krill oil and high-potency fish oil concentrates, with trained staff delivering phospholipid absorption and sustainability credential education.
- Supermarkets:Mass-market fish oil and fortified food placements competing on unit price, facing margin compression from private label entrants.
- Pharmacies:Clinical-grade and prescription omega-3 formulations, with CVS and Walgreens chains expanding pharmacist-guided supplement counseling in Ontario and Quebec under Health Canada natural health product regulations.
Established presence remains with health stores. Subscription-driven expansion is gaining share fastest in online retail.
Customer Type:
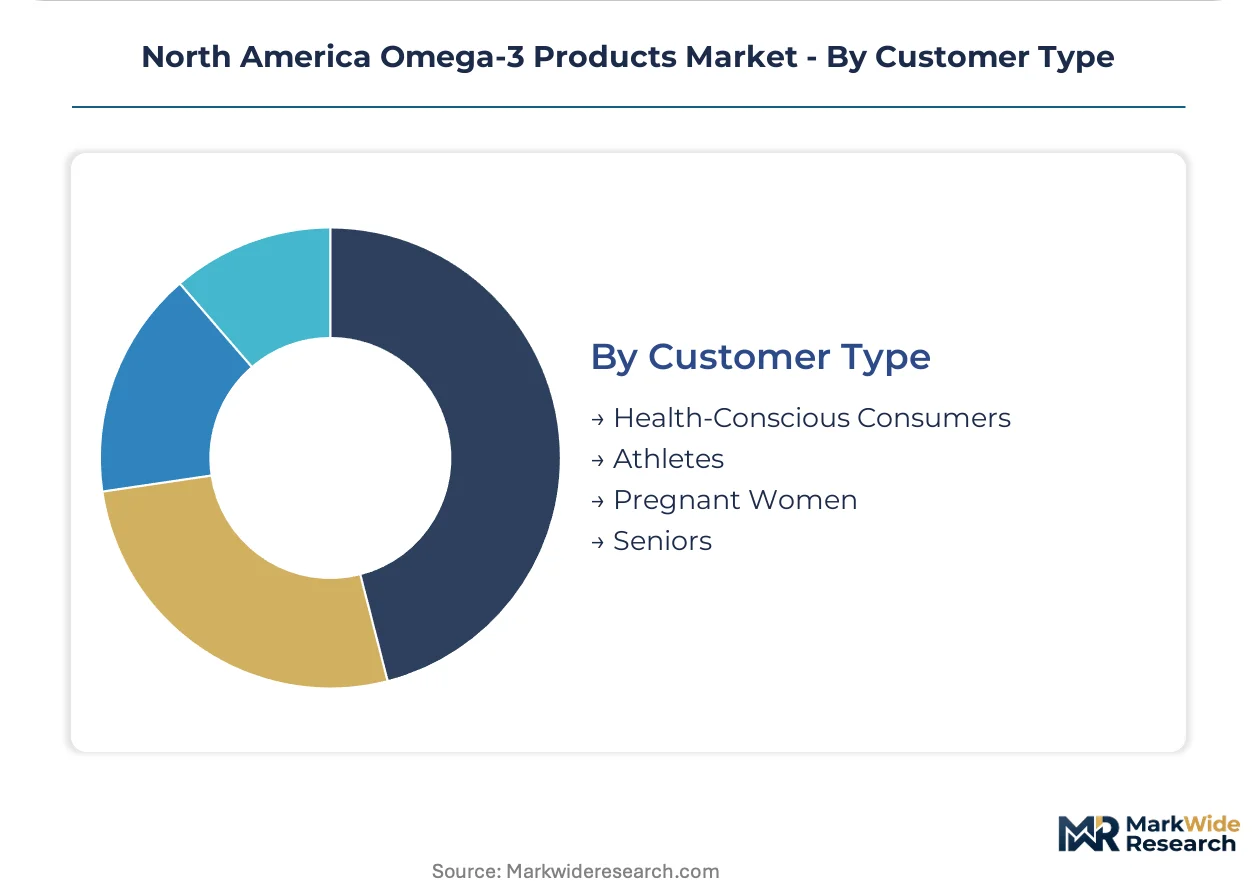
Demographic targeting aligns formulation potency, delivery format, and messaging with distinct life-stage health priorities and purchasing authority patterns.
- Seniors:Consumers over 55 in Sun Belt states seeking cognitive and cardiovascular preventive nutrition, driving demand for high-potency EPA concentrates validated by FDA qualified health claims.
- Pregnant Women:DHA-focused prenatal formulations emphasizing fetal neurodevelopment, with algal oil capturing preference among consumers avoiding marine contaminant concerns.
- Health-Conscious Consumers:Broad demographic pursuing general wellness optimization, price-sensitive in supermarket channels but responsive to sustainability certifications in premium retail.
- Athletes:Anti-inflammatory and recovery-positioned omega-3s, often combined with other condition-specific ingredients in sports nutrition formulations.
Primary volume sits with seniors. Steepest expansion trajectory is visible among pregnant women prioritizing contaminant-free algal sources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sun Belt tax incentives and life-sciences clustering drive omega-3 manufacturing concentration across North America. Special economic zones in Florida, Texas, and Southern California anchor fermentation-based algal oil production and pharmaceutical-grade formulation facilities serving domestic and export demand.
United States
California and Florida concentrate demand among consumers over 55 seeking cardiovascular and cognitive support formulations. FDA qualified health claims for EPA and DHA cardiovascular benefits expand permissible marketing language for dietary supplement manufacturers. Greater Boston and Research Triangle Park host clinical nutrition R&D facilities developing prescription-grade omega-3 protocols for hospital systems.
Canada
Ontario and Quebec present underpenetrated channels for prescription-grade omega-3 formulations in long-term care and hospital settings. Health Canada natural health product licensing requires site-specific good manufacturing practice audits and label claims substantiation, creating 18-24 month regulatory timelines. Toronto and Vancouver clusters concentrate biotechnology fermentation capacity for algal-derived DHA production.
Mexico
Bajío Region pharmaceutical manufacturing zones attract contract formulation facilities serving North American export markets. COFEPRIS regulatory alignment with FDA standards facilitates cross-border dietary supplement distribution. Guadalajara metro area concentrates softgel and encapsulation capacity for U.S. and Canadian brand owners seeking cost-optimized production.
North America Omega-3 Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade formulations consolidating around FDA-approved drug pathways and dietary supplements fragmenting across private label and branded entrants. The vendor base organizes into three strategic archetypes: multinational nutrition conglomerates with clinical nutrition divisions, biotechnology platforms with fermentation-based algal oil capabilities, and vertically integrated Antarctic krill harvesters. Dominant competitive moves include backward integration into raw material supply and strategic partnerships with personalized nutrition platforms.
Within the biotechnology platform tier, DSM-Firmenich and Aker BioMarine occupy distinct positions. DSM-Firmenich exemplifies fermentation-based supply decoupled from marine catch volatility. Aker BioMarine anchors Antarctic krill oil sourcing through vertically controlled harvesting operations. Abbott Laboratories represents the clinical nutrition archetype with prescription-grade formulation capabilities.
| Leading Market Players |
|---|
| Unilever |
| Abbott Laboratories |
| GNC |
| Herbalife Nutrition |
| Amway Corp |
| BASF SE |
| Aker BioMarine |
| Croda International |
| DSM-Firmenich |
| Others |
Value Network & Pricing Analysis
Captive supply of Antarctic krill harvesting fleets anchors both raw material security and premium pricing power for phospholipid-bound omega-3 concentrates. This integration choice insulates specialized operators from Peruvian anchovy catch volatility while enabling 40-60% retail premiums over standard fish oil formulations.
Pricing Analysis
Volume throughput concentrates in mass-market fish oil softgels competing on unit cost, while margin capture concentrates in algal oil and krill oil tiers commanding sustainability and absorption premiums. Price differentiation rests on certification grade and phospholipid-bound bioavailability claims. Cost compression in commodity fish oil is intensifying because private label entrants and El Niño-driven raw material volatility squeeze contract manufacturer margins. Supermarket channels show highest price sensitivity; direct-to-consumer subscription platforms show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Peruvian and Chilean anchovy fisheries supplying EPA concentrates to North American refiners. Raw material procurement draws from Antarctic krill harvesting, fermentation bioreactors in California and Ontario, and wild-catch marine oils. Tariff exposure on imported concentrates creates structural risk for U.S.-based finished goods manufacturers. Distribution runs through health stores and online retail for premium tiers, pharmacies for clinical-grade formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity bottlenecks for algal EPA production prop pricing power across vegan-certified segments, constraining volume expansion despite accelerating procurement rates from sustainability-positioned buyers.
For Market Incumbents: Lock in multi-year offtake agreements with biotechnology fermentation platforms before capacity expansion saturates algal oil premiums. Deepen backward integration into Antarctic krill harvesting to defend phospholipid-bound positioning against emerging algal entrants. Prioritize Health Canada site licensing investments to secure 18-24 month regulatory timelines for Ontario and Quebec hospital channel access. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models leveraging biomarker testing integration, where telehealth-aligned prescribing in California and New York lowers customer acquisition costs versus retail shelf placement. Target underpenetrated long-term care facilities in Ontario for prescription-grade cardiovascular formulations. Lead with vegan-certified algal DHA to bypass incumbent fish oil supply chain complexity. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational nutrition conglomerates seeking fermentation biotechnology capabilities and clinical nutrition R&D assets. Long-term viability favors platforms with captive algal oil supply and Health Canada licensing infrastructure over pure-brand supplement marketers. Watch EPA fisheries stock assessment downgrades as inflection indicators for raw material cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | DSM-Firmenich and biotechnology platforms scale algal EPA output to meet vegan-certified demand growth. |
| Health Canada Site Licensing | Accelerated natural health product approvals unlock hospital and long-term care distribution channels in Ontario. |
| Direct-to-Consumer Subscription Launch | Biomarker-integrated platforms bypass retail markup and capture repeat purchase loyalty in California metro areas. |
| Antarctic Harvesting Fleet Investment | Vertically controlled krill supply secures phospholipid-bound omega-3 positioning against algal oil substitution. |
| Supercritical CO2 Extraction Scale-Up | Higher-potency concentrates exceeding 1,000 mg per serving enable pharmaceutical-grade cardiovascular applications. |
Research Methodology
FDA qualified health claim filings, EPA fisheries stock assessments, and Health Canada natural health product licensing databases formed the secondary backbone of this analysis. Primary interviews with fermentation biotechnology directors, dietary supplement procurement managers at CVS and Walgreens, and clinical nutrition formulary directors at Ontario hospital systems validated supply chain and pricing assumptions. Bottom-up and top-down triangulation reconciled volume estimates across extraction technology tiers and distribution channels.
Bottom-up modeling anchored projections in fermentation capacity buildouts, wild-catch quota allocations, and channel-specific pricing structures across the analysis window. Segmentation dimensions included source type, application tier, distribution format, and customer life-stage. CAGRs derived from supply-constrained growth ceilings in algal oil and demand elasticity patterns in aging Sun Belt demographics. Forecast inputs incorporated Health Canada licensing timeline distributions and El Niño frequency patterns affecting Peruvian catch volatility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained anchovy fishery quota restrictions or breakthrough EPA yields from algal fermentation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
India Whey Protein Market