
 Radiation Shielding Materials Market | 2026-2036
Radiation Shielding Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Shielding Materials Market Analysis
The EU Green Deal is expanding requirements for sustainable material sourcing across medical and industrial infrastructure. SCHOTT AG leverages its specialty glass expertise to supply radiation-transparent yet protective viewing panels for imaging suites. MAVIG GmbH sustains its position through integrated suspension systems that combine structural support with lead-equivalent shielding. Nippon Electric Glass anchors Asian supply chains with borosilicate formulations optimized for diagnostic equipment manufacturers.
Radiation shielding materials are engineered compositions designed to attenuate ionizing energy through absorption, reflection, or scattering mechanisms, typically incorporating high atomic number elements such as lead or hydrogen-rich polymers with densities exceeding 0.94 g/cm³ for effective neutron moderation. Their primary purpose is to protect personnel, sensitive electronics, and biological tissues from hazardous exposure in controlled environments. Borated polyethylene leads material type growth due to its combined thermal neutron capture and gamma attenuation properties in compact reactor shielding applications. Healthcare facilities dominate end user demand as proton therapy centers and PET-MRI installations require site-specific fabricated components with precise lead equivalency ratings. Nuclear power plants represent the most stringent specification environment where regulatory-mandated inspection cycles drive replacement demand for degraded concrete biological shields.
The U.S. Nuclear Regulatory Commission enforces 10 CFR Part 20 dose limits that mandate continuous shielding integrity verification, while the EPA administers standards for radioactive material containment in decommissioning contexts. The International Atomic Energy Agency's Safety Standards Series provides the harmonized technical baseline that national regulators transpose into licensing conditions for facility operators. Stakeholders must monitor evolving fusion energy demonstration timelines where tritium handling protocols will demand novel lithium-bearing shielding architectures and qualification pathways.
Market Dynamics
The EU Medical Device Regulation is tightening material traceability mandates while proton therapy centers demand site-specific shielding with precise lead equivalency ratings, compressing procurement cycles and elevating qualification burdens for fabricators.
Growth Catalysts
- Healthcare Infrastructure Modernization:Germany's concurrent hospital expansion and nuclear decommissioning programs are generating concentrated demand for borated polyethylene and lead-equivalent composites in imaging suites and containment structures.
- 10 CFR Part 20 Enforcement:The U.S. Nuclear Regulatory Commission's dose limit verification requirements mandate continuous shielding integrity monitoring, driving replacement cycles for degraded concrete biological shields in licensed facilities.
- Fusion Energy Demonstration Timelines:Tritium handling protocols in experimental reactors are creating qualification pathways for lithium-bearing shielding architectures with novel thermal neutron capture properties.
Market Restraints
- Lead Price Volatility:Primary lead supply concentration in Chinese smelters exposes fabricators to input cost swings that compress margin buffers on fixed-price installation contracts.
- Polymer Feedstock Constraints:High-density polyethylene and boron carbide additive supply bottlenecks limit production scalability for neutron-shielding sheet manufacturers serving compact reactor developers.
- REACH Registration Burden:The European Chemicals Agency's substance authorization requirements for boron compounds add compliance overhead that disadvantages smaller compounders against integrated multinationals.
Strategic Opportunities
- India Healthcare Expansion:The country's PLI scheme for medical devices is attracting diagnostic equipment manufacturers who require certified shielding suppliers for domestic installation compliance.
- Decommissioning Services Integration:Contractors bundling shielding removal, waste characterization, and disposal under EPA radioactive material containment standards are capturing margin from fragmented service procurement.
- Glass-Ceramic Convergence:Specialty glass formulators combining borosilicate transparency with neutron-absorbing rare-earth doping are penetrating viewing panel applications previously served by leaded acrylic.
Industry Challenges
- Radiation Protection Engineering Talent Scarcity:Qualified health physicists capable of translating dose calculations into fabrication specifications remain concentrated at national laboratories and major utilities, constraining independent shielding designer growth.
- IAEA Harmonization Gaps:National regulators transpose Safety Standards Series guidelines into divergent licensing conditions, forcing manufacturers to maintain multiple qualification dossiers for equivalent product categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Shielding Materials Market |
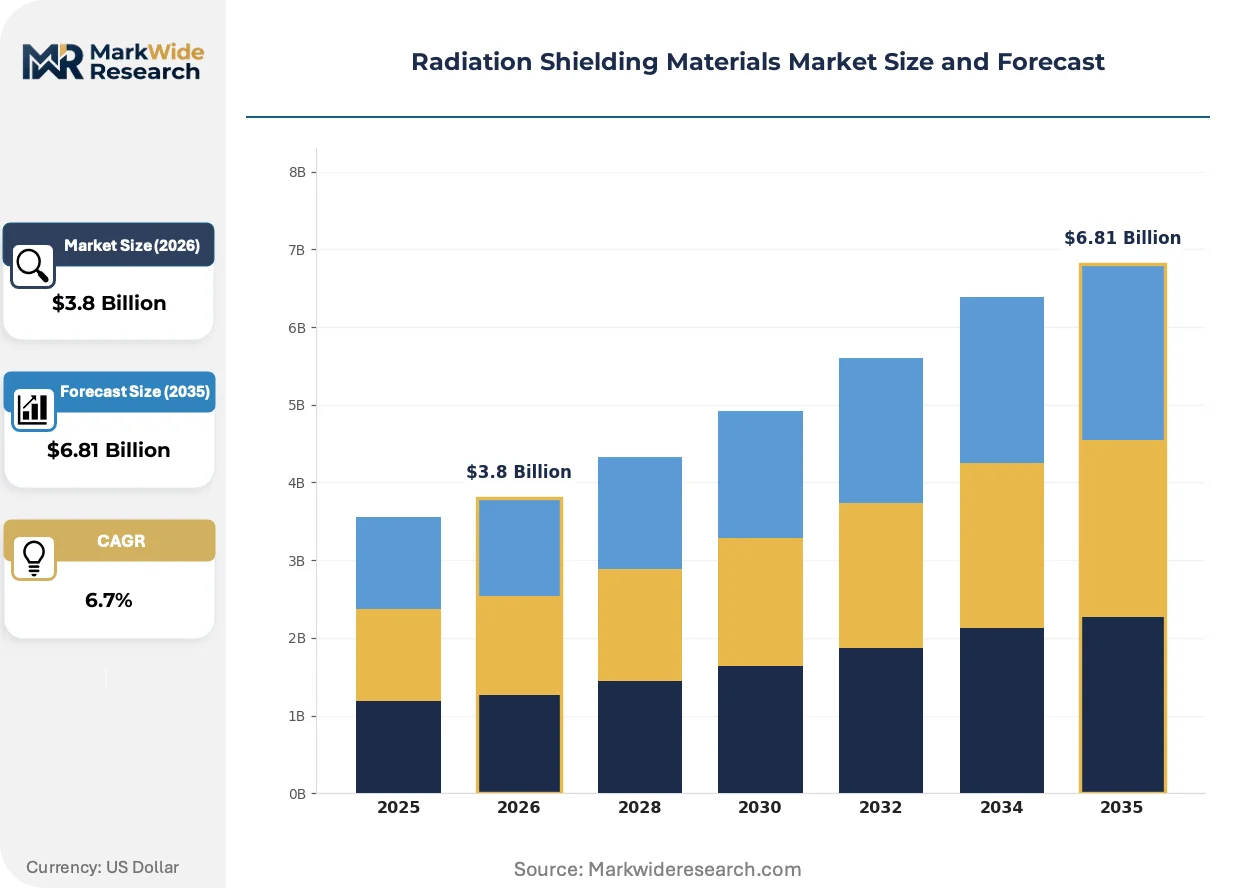
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lead, Concrete, Borated Polyethylene, Steel End User: Healthcare Facilities, Nuclear Power Plants, Research Laboratories, Industrial Applications Application: X-ray Protection, Nuclear Radiation Shielding, Medical Imaging, Particle Physics Form: Blocks, Sheets, Coatings, Fabricated Components |
| Companies Covered | Ray-Bar Engineering Corporation, MAVIG GmbH, Corning Incorporated, Mirion Technologies, Inc., Nuclead Inc., SCHOTT AG, MarShield Custom Radiation Shielding, Gaven Industries, Inc., Nippon Electric Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Shielding Materials Market Emerging Trajectories
Computational shielding design tools and additive manufacturing are compressing prototyping cycles while regulatory pressure on lead toxicity accelerates material substitution research across medical and industrial applications.
Artificial intelligence-driven Monte Carlo simulation software is automating dose distribution modeling for complex geometries that previously required weeks of manual calculation. Proton therapy center developers in the United States and Germany are adopting these platforms to validate custom aperture designs before fabrication commitment. This capability is automating the iteration cycle between physicists and fabricators, reducing rework rates on site-specific installations.
REACH authorization timelines for boron compounds are extending qualification periods for new neutron-shielding formulations, forcing compounders to front-load toxicological dossier investment years ahead of commercial deployment. The European Chemicals Agency's prioritization of endocrine disruptor screening is particularly affecting borated polyethylene suppliers serving fusion research facilities. German and French reactor developers are responding by accelerating in-house material certification programs to secure supply chain continuity.
Diagnostic equipment buyers are consolidating vendor relationships around single-source shielding integrators who assume liability for lead equivalency certification and installation compliance. Large hospital systems in the United States are displacing fragmented procurement of panels, doors, and viewing windows with turnkey room contracts that bundle design, fabrication, and regulatory documentation. This concentration is most visible in academic medical centers establishing proton therapy capabilities, where project complexity favors integrated suppliers over component specialists.
Radiation Shielding Materials Market Segmentation
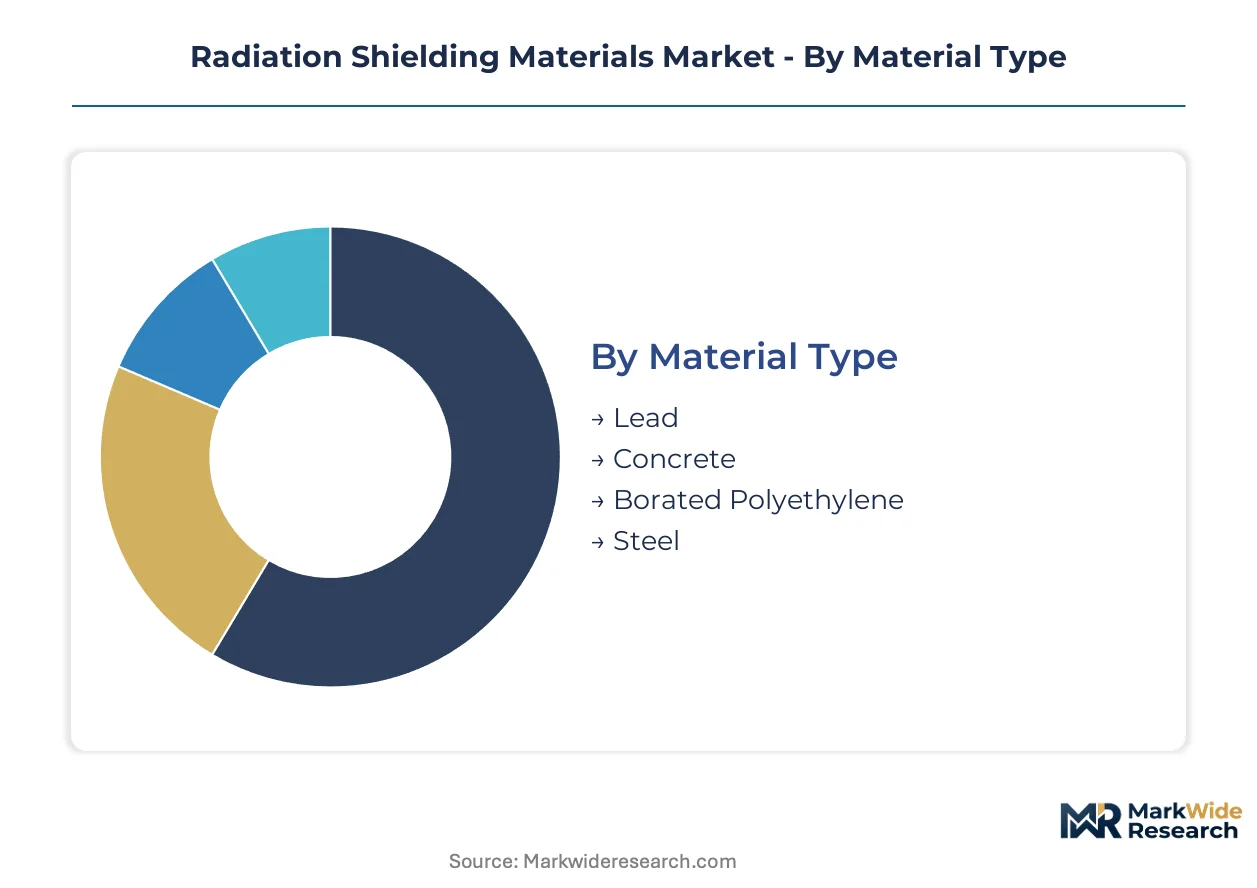
Segmentation in radiation shielding materials reveals how technical specifications diverge across end-use environments. Material composition, form factor, and application requirements create distinct procurement patterns that suppliers must navigate.
Material Type:
Supply concentration varies sharply across material categories, with primary metal sourcing and polymer additive availability determining regional production clusters.
- Lead:High-density metallic lead remains the reference standard for gamma attenuation in medical imaging suites. German hospital modernization programs and U.S. proton therapy installations sustain demand despite REACH toxicity pressures.
- Borated Polyethylene:Hydrogen-rich polymer matrices loaded with boron carbide deliver combined thermal neutron capture and gamma shielding in compact reactor applications. Fusion research facilities in France and Germany are accelerating qualification timelines for next-generation formulations.
- Concrete:Standard and heavyweight concrete formulations serve permanent biological shielding in nuclear containment structures. Decommissioning projects across multiple geographies drive replacement demand for degraded installations.
- Steel:Alloyed and stainless steel configurations provide structural shielding in industrial radiography and transport cask applications. Steel absorbs the bulk of installed capacity; borated polyethylene is expanding most quickly.
Lead maintains volume leadership in medical applications; borated polyethylene is climbing the fastest on compact reactor deployment.
End User:
Customer procurement sophistication spans from standardized hospital purchasing to nuclear utility engineering specifications that mandate decades-long performance documentation.
- Healthcare Facilities:Imaging suites, proton therapy centers, and PET-MRI installations require site-specific fabricated components with precise lead equivalency ratings. Diagnostic equipment consolidation around turnkey room contracts is displacing fragmented component sourcing.
- Nuclear Power Plants:Licensed facilities operate under continuous shielding integrity verification mandates per 10 CFR Part 20 and equivalent national regulations. Concrete biological shield degradation drives scheduled replacement cycles.
- Research Laboratories:Fusion energy demonstration programs and particle physics facilities demand novel lithium-bearing architectures for tritium handling protocols. ECHA boron compound authorization timelines extend qualification periods for neutron-shielding formulations.
- Industrial Applications:Non-destructive testing, food irradiation, and radiography operations utilize portable shielding solutions with mobility requirements. Industrial applications absorb the bulk of installed capacity; research laboratories are gaining share fastest.
Healthcare facilities dominate current procurement volume; research laboratories show the steepest expansion trajectory on fusion energy investment.
Application:
Application-specific shielding performance requirements determine material selection, with dose rate targets and occupancy factors driving thickness calculations.
- X-ray Protection:Diagnostic radiography and fluoroscopy suites employ lead-equivalent barriers ranging from 0.5 mm to 3.0 mm depending on tube voltage and workload factors.
- Nuclear Radiation Shielding:Reactor containment, fuel handling, and waste storage applications combine concrete biological shields with specialized polymer or metal overlays for neutron and gamma attenuation.
- Medical Imaging:CT, PET, and hybrid modality installations require architect-integrated shielding with viewing window transparency and door interlock compatibility. Medical imaging absorbs the bulk of installed capacity; particle physics is expanding most quickly.
- Particle Physics:Accelerator facilities and detector assemblies utilize active shielding systems with real-time dose monitoring and automated access control integration.
Medical imaging commands the largest addressable base; particle physics investment is accelerating fastest on major facility upgrades.
Form:
Manufacturing process selection—casting, extrusion, machining, or additive fabrication—locks in lead time and customization latitude for specific installation geometries.
- Blocks:Cast or molded monolithic units serve permanent installations in reactor containment and vault construction where field modification is impractical.
- Sheets:Rolled or extruded flat stock enables on-site cutting and fitting for retrofit applications and temporary shielding barriers.
- Coatings:Spray-applied or troweled radiation-resistant formulations provide conformal coverage for complex geometries and corrosion protection.
- Fabricated Components:Custom-machined doors, viewing windows, and modular panels integrate structural, shielding, and aesthetic functions for imaging suite turnkey contracts. Fabricated components absorb the bulk of installed capacity; coatings are expanding most quickly.
Fabricated components capture the majority of value-added revenue; coatings are climbing the fastest on maintenance and retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European demand concentration where hospital modernization and nuclear decommissioning programs generate overlapping procurement cycles for borated polyethylene and lead-equivalent composites.
United States
Proton therapy center construction in Houston and academic medical corridor expansion in Boston drive site-specific shielding procurement with precise lead equivalency ratings. The U.S. Nuclear Regulatory Commission enforces 10 CFR Part 20 dose limit verification that mandates continuous shielding integrity monitoring. Texas Medical Center installations exemplify turnkey room contract consolidation displacing fragmented component sourcing.
Germany
Concurrent hospital expansion in Bavaria and nuclear containment decommissioning in Lower Saxony concentrate demand for borated polyethylene and concrete biological shield replacement. The EU Medical Device Regulation tightens material traceability mandates while REACH authorization timelines extend qualification periods for boron compounds. Karlsruhe fusion research facilities accelerate lithium-bearing shielding architecture qualification pathways.
France
ITER fusion demonstration timelines in Provence-Alpes-Côte d'Azur create procurement pull for novel neutron-shielding formulations with tritium handling compatibility. The European Chemicals Agency's endocrine disruptor screening prioritization affects borated polyethylene suppliers serving reactor developers. Paris-region hospital networks consolidate vendor relationships around single-source shielding integrators.
Japan
Diagnostic equipment manufacturer clusters in Osaka and Nagoya require certified borosilicate viewing panel supply for PET-MRI integration. METI standards harmonization with IAEA Safety Standards Series reduces qualification dossier duplication for domestic fabricators. Tsukuba research corridor particle physics facilities drive active shielding system procurement with real-time dose monitoring.
India
The PLI scheme for medical devices attracts diagnostic equipment manufacturers to Maharashtra and Gujarat who require certified shielding suppliers for domestic installation compliance. CDSCO tightening of biocompatibility standards elevates qualification burdens for fabricators serving healthcare infrastructure expansion. Hyderabad medical technology corridor concentrates demand for architect-integrated shielding with door interlock compatibility.
Radiation Shielding Materials Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and turnkey integration capability. The vendor base organizes into three tiers: integrated multinationals with full regulatory dossier libraries, regional fabricators with hospital network relationships, and specialized compounders serving reactor-specific neutron formulations. Consolidation pressure favors turnkey room contractors bundling design, fabrication, and compliance documentation. Capacity expansion and strategic partnerships represent the dominant competitive vectors as proton therapy project complexity elevates barriers to component-only suppliers.
Among German-based fabricators, MAVIG GmbH and SCHOTT AG occupy positions spanning integrated suspension systems and specialty glass viewing panels respectively. Ray-Bar Engineering Corporation anchors North American presence across lead-equivalent barrier fabrication. These three exemplify the premium-tier orientation where regulatory documentation capability and hospital network penetration determine contract capture rates in academic medical center proton therapy installations.
| Leading Market Players |
|---|
| Ray-Bar Engineering Corporation |
| MAVIG GmbH |
| Corning Incorporated |
| Mirion Technologies, Inc. |
| Nuclead Inc. |
| SCHOTT AG |
| MarShield Custom Radiation Shielding |
| Gaven Industries, Inc. |
| Nippon Electric Glass |
| Others |
Supply Flow & Price Mechanics
Academic medical center proton therapy procurement teams concentrate demand for turnkey room contracts, compressing vendor selection around integrated suppliers who bundle lead equivalency certification with installation liability. This buyer consolidation enforces project-based pricing with penalty clauses for dose verification failure, elevating margin capture for dossier-complete fabricators while squeezing component-only specialists.
Pricing Analysis
Lead equivalency certification tied to continuous 10 CFR Part 20 compliance monitoring anchors value-based pricing for installed shielding systems. Three-tier pricing structure across certified-premium, standard-registered, and uncertified-economy levels separates turnkey integrators from regional fabricators and commodity sheet suppliers. Cost compression in lead-equivalent composites is intensifying because REACH toxicity pressures accelerate material substitution R&D. Hospital purchasing committees exhibit highest price sensitivity on standardized X-ray barrier components, while nuclear utilities show lowest sensitivity given regulatory-mandated replacement cycles.
Supply Chain Analysis
Direct-to-facility project contracting handles hospital and reactor developer demand, bypassing distribution intermediaries for complex installations. Primary lead supply concentrates in Chinese smelters, boron carbide additives draw from Turkish and Argentine sources, and high-density polyethylene resin clusters in U.S. Gulf Coast petrochemical complexes. Single-source vulnerability in pharmaceutical-grade boron compound supply exposes neutron-shielding formulators to ECHA authorization delays. Distribution runs through certified fabricator networks with NRC or national regulator quality program accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Borated polyethylene production capacity constraints at qualified compounders prop pricing power for incumbent integrators serving fusion research and compact reactor developers.
For Market Incumbents: Hedge against lead substitution acceleration by deepening captive supply of boron carbide additives and lithium-bearing polymer formulations. Secure capacity expansion slots at Turkish boron refiners before ECHA prioritization extends authorization timelines for new compound suppliers. For New Entrants and Emerging Players: Launch via CDSCO-certified fabrication partnerships targeting India's PLI scheme medical device corridor, where domestic shielding supplier scarcity creates first-mover advantage. Bundle architect-integrated room design with door interlock compatibility to displace fragmented component imports. For Investors and Strategic Acquirers: The window for entry favors turnkey integrators with NRC 10 CFR Part 20 dossier libraries and academic medical center reference installations. Watch ITER tritium handling protocol finalization as signal for lithium-bearing shielding architecture demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Carbide Supply | ECHA authorization bottlenecks favor compounders with captive Turkish or Argentine feedstock. |
| Turnkey Room Contract Bundling | Texas Medical Center installations demonstrate margin capture from design-fabrication-compliance integration. |
| Lithium-Bearing Polymer Certification | Karlsruhe fusion research protocols create qualification pathway for tritium-compatible shielding. |
| CDSCO Biocompatibility Dossier Investment | Hyderabad medical technology corridor demands certified suppliers for domestic installation compliance. |
| Decommissioning Services Integration | EPA radioactive material containment standards enable margin capture from bundled removal-characterization-disposal. |
Methodological Framework
Document review covered customs trade data on lead and boron compound shipments, ECHA substance authorization databases, and NRC inspection reports, complemented by interviews with health physicists at national laboratories, biomedical engineers at academic medical centers, procurement managers at proton therapy developers, and technical directors at borated polyethylene compounders. Secondary validation drew from IAEA Safety Standards Series documentation, EU MDR technical files, and hospital GPO contract databases. Bottom-up demand modeling across material types and end-use segments was triangulated against top-down macroeconomic indicators.
Cross-referencing historical capacity utilization patterns with panel input from reactor developers and diagnostic equipment manufacturers informed the analytical framework across the projection horizon. Segmentation dimensions modeled included material composition, end-user vertical, application environment, and form factor manufacturing process. CAGRs were derived from iterative reconciliation of demand-side procurement forecasts with supply-side capacity expansion announcements. Fusion energy demonstration timelines and REACH authorization velocity served as industry-specific forecast inputs.
Lead price volatility at Chinese smelters, ECHA endocrine disruptor screening prioritization, and proton therapy center construction delays are the dominant revision risks to installed base projections. Periodic stress-testing of base assumptions against IAEA harmonization gaps and health physicist talent scarcity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Polypropylene Foams Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Technical Foam Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Insulation Products Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Global Acoustic Insulation Material Market