
 Fire Protective Materials Market | 2026-2036
Fire Protective Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Protective Materials Market Intelligence
The shift toward materials with 120-minute fire-resistance ratings is rotating the market toward higher-value intumescent coatings and firestop products. Sika AG leverages its extensive portfolio in construction chemicals to capture this specification-driven demand in commercial building projects. BASF SE competes on chemical innovation in its polymer-based intumescent lines for industrial infrastructure. Similarly, Hilti Corporation specializes in engineered firestop systems for complex mechanical, electrical, and plumbing penetrations.
Fire protective materials are substances engineered to resist or delay combustion and heat transfer, preserving structural integrity during a fire event. Their function relies on mechanisms like intumescence, where coatings expand to form an insulating char layer, or the inherent non-combustibility of materials like fire-resistant glass. Intumescent coatings and firestop products lead the product segments, driven by widespread adoption in building construction. Aerospace and marine applications command higher margins due to strict certification needs.
Building codes, such as ASTM E119 in the United States and Europe's EN 13501 series, define critical performance requirements for fire resistance. Regulatory bodies like the US EPA and ECHA also influence material composition by restricting certain halogenated flame retardants under environmental safety rules. Material suppliers must now balance achieving higher fire-resistance ratings with developing formulations that meet evolving health and safety mandates.
Market Dynamics
The convergence of stringent building codes and the expansion of high-value infrastructure, such as data centers and transportation hubs, represents the central force shaping the fire protective materials market. This dynamic compels a market-wide rotation toward higher-performance, certified material systems.
Growth Catalysts
- Regulatory Mandates:Europe's Construction Products Regulation (CPR) imposes harmonized standards for fire performance, compelling manufacturers to certify products to specific Euroclasses and driving demand for materials with higher fire-resistance ratings across the continent.
- Infrastructure Expansion:The construction of data centers in the United States and energy infrastructure in India is creating concentrated demand for advanced firestop systems and intumescent coatings to protect critical assets and ensure operational continuity.
- Material Specification Shifts:A preference for thin-film intumescent coatings in commercial architecture is growing due to their aesthetic finish compared to bulky cementitious materials, expanding their use on exposed structural steel.
Market Restraints
- Raw Material Cost Volatility:The pricing of key precursors for polymer-based intumescent coatings, such as ammonium polyphosphate and melamine, is subject to fluctuations in chemical supply chains, creating margin pressure for manufacturers.
- Environmental Regulations:Restrictions on certain halogenated flame retardants under regulations like the EU's REACH and rules from the US EPA force costly reformulation efforts to develop effective and compliant alternatives without compromising fire performance.
- Threat of Substitution:In certain structural applications, non-combustible materials like mineral wool insulation and specially treated gypsum board offer a lower-cost alternative to coatings, limiting market penetration in price-sensitive construction segments.
Strategic Opportunities
- Electric Vehicle Sector:The need for thermal runaway prevention in electric vehicle battery packs creates a significant opportunity for lightweight, high-temperature fire protective materials, including ceramic blankets, mica sheets, and specialized coatings.
- High-Rise Residential Retrofits:Updated fire safety codes for existing high-rise residential buildings, particularly in Europe and Australia, present a substantial market for retrofitting structures with modern firestop systems and compartmentation solutions.
- ASEAN Infrastructure Growth:Rapid urbanization and infrastructure development in Southeast Asian nations provide an underpenetrated market for fire protective materials, especially in new commercial, transport, and industrial projects.
Industry Challenges
- Complex Certification Pathways:Achieving compliance with standards like ASTM E119 and EN 13501 involves prolonged and expensive testing cycles, creating a significant barrier to entry and delaying the commercialization of new product formulations.
- Skilled Applicator Scarcity:The performance of many fire protective systems, particularly spray-applied coatings and firestops, depends on correct on-site installation, but a shortage of certified and trained applicators can lead to inconsistent quality.
- Formulation Expertise Deficit:Developing non-halogenated, low-VOC formulations that meet both stringent fire codes and environmental health standards requires specialized chemical engineering talent, which remains in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Protective Materials Market |
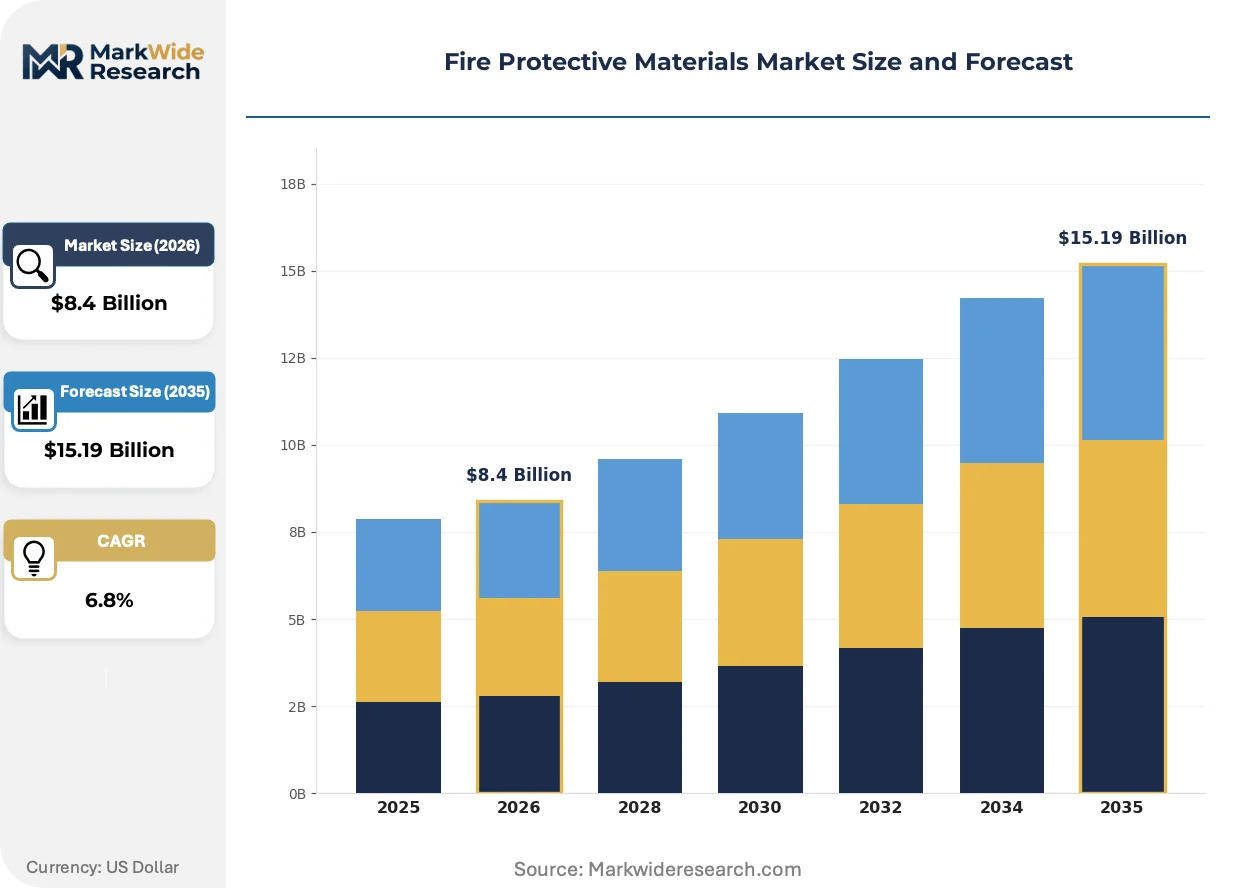
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Coatings, Fire-Resistant Glass, Firestop Products, Passive Fire Protection Application: Building Construction, Industrial Manufacturing, Aerospace, Marine End User: Construction Firms, Aerospace Manufacturers, Oil & Gas Companies, Government Agencies Installation Type: On-site, Prefabricated, Modular, Retrofitting |
| Companies Covered | 3M, Akzo Nobel N.V., Hilti Corporation, Sika AG, BASF SE, Morgan Advanced Materials, Specified Technologies Inc., Etex Group, RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Protective Materials Market Strategic Shifts & Innovations
Product development is increasingly focused on creating multi-functional materials that combine fire resistance with other properties like acoustic insulation or corrosion protection. This shift reflects end-user demand for integrated solutions that solve multiple challenges in complex building and industrial environments.
Bio-based and non-toxic formulations represent a significant innovation frontier. Research is accelerating into fire retardant chemistries derived from sources like lignin, casein, and plant-based polyols to meet sustainability mandates from regulators and corporate buyers. The adoption of these materials is driven by green building certifications. This innovation is fragmenting the supply chain by introducing new bio-refinery inputs alongside traditional petrochemicals.
China's updated GB standards for fire safety in buildings are forcing a rapid upgrade in material performance across its domestic construction industry. These regulations mandate more rigorous testing protocols and higher fire-resistance classifications for materials used in public infrastructure and high-rise structures. The policy directly impacts both local manufacturers and international suppliers, who must now re-certify products for the Chinese market.
A clear behavioral shift among engineering and construction firms is the move toward specifying complete, tested firestop systems over purchasing individual components. This disrupts the traditional channel of selling standalone sealants, wraps, or collars, favoring suppliers that offer engineered solutions for complex MEP penetrations. The trend is most visible in high-specification projects like hospitals and airports in North America and Western Europe.
Fire Protective Materials Market Segmentation
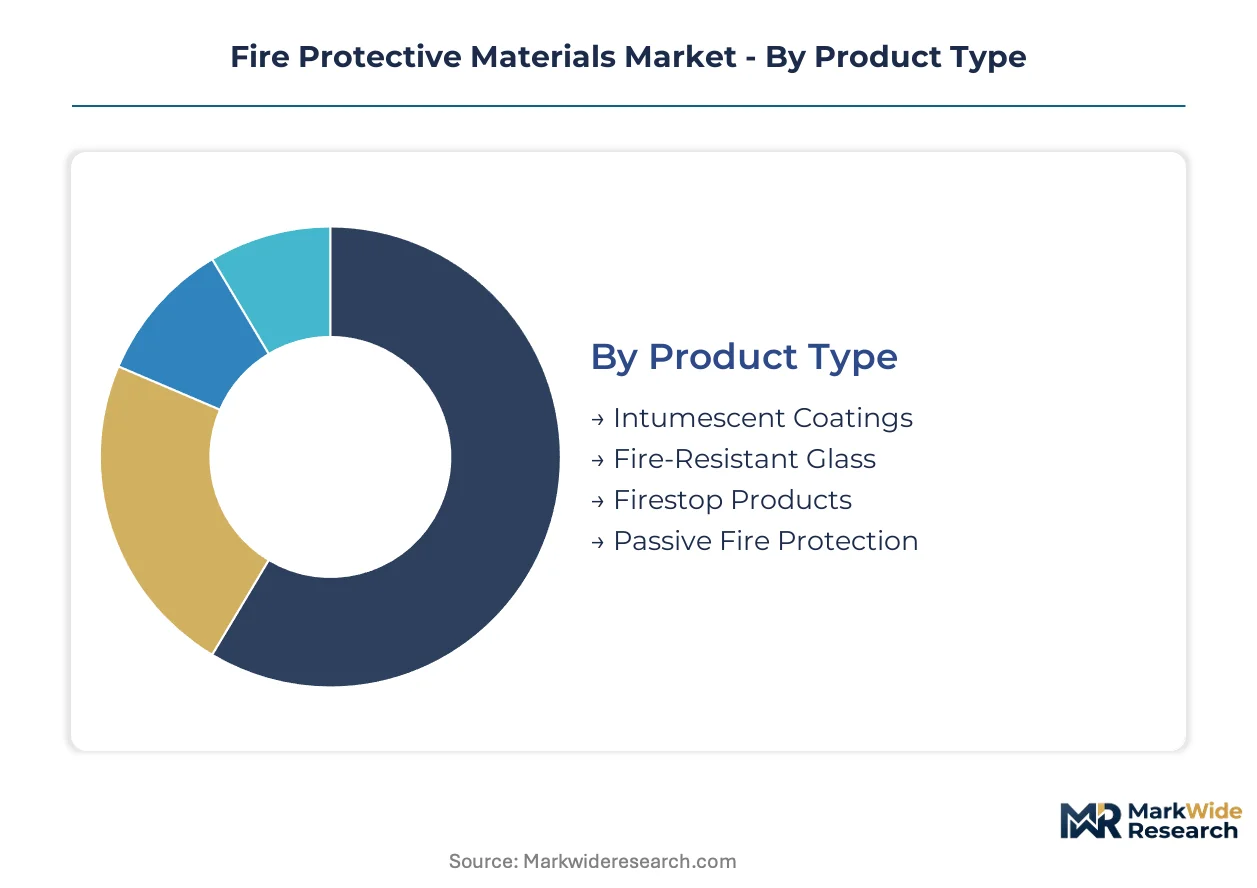
Segmentation in the fire protective materials market highlights diverse performance requirements across various applications. Understanding these distinct segments allows manufacturers to tailor solutions for specific compliance needs and operational environments. This differentiation is crucial for addressing varied regulatory landscapes across global construction and industrial sectors.
Product Type:
Regulatory bodies globally differentiate fire protective materials based on their inherent resistance mechanisms and certified performance standards.
- Intumescent Coatings:These coatings expand when exposed to heat, forming an insulating char layer that protects structural steel and other substrates from rapid temperature increase. Demand concentrates in high-rise commercial structures and data centers in Europe, driven by stringent EN 13501 fire classification requirements.
- Firestop Products:Engineered systems prevent the spread of fire and smoke through openings and penetrations in fire-rated walls and floors, maintaining compartmentation integrity. Their adoption is critical in complex mechanical, electrical, and plumbing penetrations within North American hospitals and transportation hubs, adhering to ASTM E119 standards.
- Fire-Resistant Glass:This specialized glazing maintains integrity and reduces heat transfer during a fire, finding application in fire-rated doors and partitions in public buildings.
- Passive Fire Protection:This broad category includes non-combustible materials like mineral wool and gypsum, providing inherent fire resistance in general building construction.
Established volume favors Passive Fire Protection; emerging adoption favors Intumescent Coatings.
Application:
Application segmentation highlights the diverse operational environments where fire protective materials are deployed.
- Building Construction:This segment encompasses residential, commercial, and institutional structures, requiring materials to meet specific fire resistance ratings for structural integrity and occupant safety. Demand is intense in China and India due to rapid urbanization and the expansion of high-rise commercial and residential projects under updated GB standards.
- Aerospace:Materials in this sector must provide lightweight fire resistance for aircraft cabins, cargo bays, and engine compartments, often with thermal runaway prevention capabilities. Strict certification needs from bodies like the FAA in the United States drive demand for advanced ceramic blankets and specialized coatings in aircraft manufacturing.
- Industrial Manufacturing:Fire protective solutions safeguard critical infrastructure, machinery, and personnel in facilities like chemical plants and power generation sites.
- Marine:Materials for marine vessels and offshore platforms must resist fire in harsh environments, complying with international maritime safety regulations for passenger and crew protection.
Building Construction applications command the largest market share, while Aerospace applications consistently yield higher margins.
End User:
End-user segmentation reflects the primary purchasers and specifiers of fire protective materials.
- Construction Firms:These entities directly procure and install fire protective materials for new builds and retrofits, often driven by project specifications and local building codes. Their demand for complete firestop systems is particularly high in North American and Western European high-specification projects like hospitals.
- Government Agencies:Agencies procure materials for public infrastructure projects, military installations, and regulatory compliance within their own facilities. Updated fire safety codes for existing high-rise residential buildings in Europe and Australia drive significant retrofit demand from municipal housing authorities.
- Aerospace Manufacturers:These companies integrate lightweight, high-performance fire protective materials into aircraft components during the manufacturing process.
- Oil & Gas Companies:This sector requires specialized fire and blast protection for offshore platforms, refineries, and pipelines to ensure operational safety.
Construction Firms represent the largest consumer base, with Government Agencies driving significant demand for infrastructure and retrofit projects.
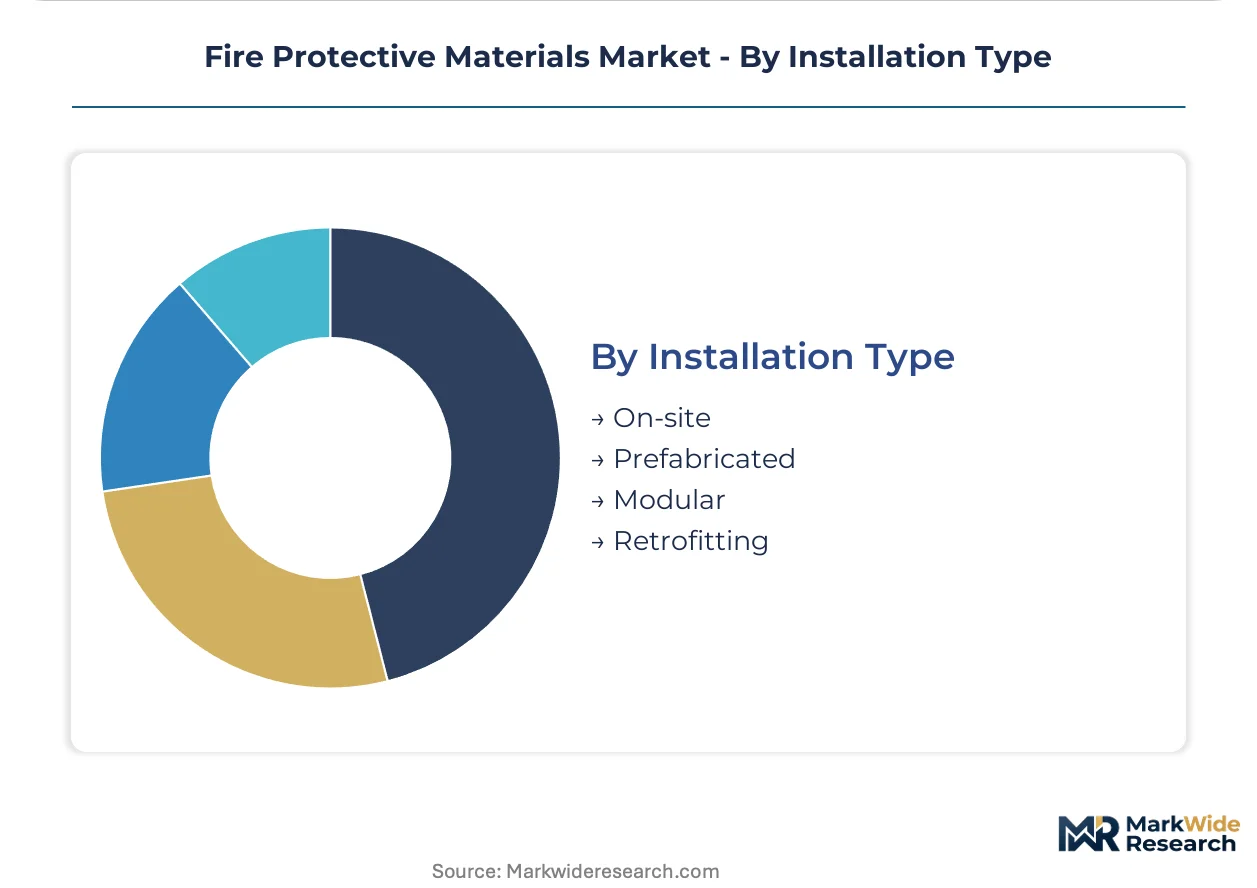
Installation Type:
Installation type differentiates how fire protective materials are integrated into structures.
- On-site:This involves direct application or installation of materials at the construction site, often requiring specialized labor for spray-applied coatings or complex firestop systems. The scarcity of skilled applicators in North America poses a challenge for consistent quality in large commercial building projects.
- Retrofitting:This segment addresses the upgrade of fire safety in existing structures, integrating modern materials and systems without extensive demolition. Updated fire safety codes for high-rise residential buildings in Europe and Australia create substantial demand for these specialized installations.
- Prefabricated:Components like fire-rated panels or pre-assembled firestop devices are manufactured off-site, then delivered for quicker installation.
- Modular:This involves integrating fire protection into factory-built modules for construction projects, enhancing efficiency and quality control before on-site assembly.
On-site installations dominate new construction, while Retrofitting offers substantial growth opportunities driven by evolving safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of fire protective materials demand sits with rapidly industrializing economies and regions implementing stringent building codes. These diverse regulatory and development landscapes compel material suppliers to tailor product offerings and certification efforts for specific national markets. Infrastructure projects and safety mandates drive significant material consumption across continents.
United States
Demand for advanced fire protective materials in the United States stems from extensive data center construction and aerospace manufacturing. The Federal Aviation Administration (FAA) mandates rigorous fire resistance standards for aircraft components, driving innovation in lightweight materials. Major aerospace clusters in Seattle and Wichita, alongside data center hubs in Virginia, concentrate high-performance material procurement.
China
Rapid urbanization and ambitious infrastructure development projects in China create immense demand for fire protective materials. Updated GB standards for fire safety in buildings now require higher performance classifications for construction materials. Industrial zones in the Yangtze River Delta and Pearl River Delta are key consumption centers for intumescent coatings and firestop systems.
Germany
Germany's robust construction sector and focus on sustainable building practices drive the adoption of high-value fire protective solutions. Europe's Construction Products Regulation (CPR) and national DIN standards compel manufacturers to certify products to specific Euroclasses. Automotive and chemical manufacturing hubs, particularly in Bavaria and North Rhine-Westphalia, utilize specialized fire protection for industrial facilities.
India
India's expanding energy infrastructure and commercial building boom fuel significant demand for fire protective materials. The Bureau of Indian Standards (BIS) continually updates fire safety codes for various construction types. Major metropolitan areas like Mumbai and Delhi, experiencing rapid high-rise development, are focal points for firestop products and intumescent applications.
Australia
Updated fire safety codes for existing high-rise residential buildings in Australia create substantial retrofit demand for modern fire protective systems. The Building Code of Australia (BCA) specifies stringent fire resistance levels for new and refurbished structures. Sydney and Melbourne, with their dense urban environments, represent key markets for compartmentation solutions and fire-resistant glass.
Fire Protective Materials Market Key Industry Players
Concentration sits with large diversified construction chemical and material groups alongside specialized fire protection system providers. The market exhibits a tiered structure, ranging from global conglomerates to regional niche players. Dominant competitive moves include strategic partnerships for system integration and continuous portfolio diversification to meet evolving regulatory demands.
Among leading construction chemical suppliers, Sika AG and BASF SE represent comprehensive portfolios in intumescent coatings and sealants, leveraging their global distribution networks. Hilti Corporation exemplifies a specialized system provider, focusing on engineered firestop solutions for complex mechanical, electrical, and plumbing penetrations. These companies navigate stringent certification pathways to maintain their competitive positions.
| Leading Market Players |
|---|
| 3M |
| Akzo Nobel N.V. |
| Hilti Corporation |
| Sika AG |
| BASF SE |
| Morgan Advanced Materials |
| Specified Technologies Inc. |
| Etex Group |
| RPM International Inc. |
| Others |
Cost & Logistics Intelligence
Project-based procurement locks in material specifications and pricing early for large infrastructure builds, ensuring both supply access and cost visibility for complex fire protective systems. This structured approach helps manage the inherent volatility of raw material inputs and specialized product requirements.
Pricing Analysis
Europe's Construction Products Regulation (CPR) dictates the pricing tier structure for fire protective materials, driving demand for certified products with specific Euroclass performance ratings. Pricing operates on a project-based model, with significant differentiation based on certification level, performance ratings like 120-minute fire resistance, and customization for complex mechanical, electrical, and plumbing penetrations. Pricing pressure stems from raw material cost volatility for chemical precursors such as ammonium polyphosphate. Construction firms for general building applications exhibit higher price sensitivity compared to aerospace manufacturers or data center operators.
Supply Chain Analysis
Fluctuations in ocean freight rates and port congestion impact the inbound logistics costs for fire protective material precursors. Geographic supply concentrates in China for key chemical raw materials like ammonium polyphosphate, while specialized polymers and advanced formulations originate from Europe and the United States. The supply chain faces structural risk from commodity price volatility for chemical inputs and regulatory restrictions on certain halogenated flame retardants. Distribution runs through direct sales channels for large-scale construction projects and specialized distributors for smaller, regional installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A market shift toward specifying complete, tested firestop systems represents a consolidation among buyers, altering procurement patterns for fire protective materials.
For Market Incumbents: Consolidate market share through strategic acquisitions of niche technology firms specializing in non-halogenated or bio-based formulations. Invest heavily in advanced certification processes for new product lines to counter the threat of substitution by lower-cost, generic materials. Expand global distribution networks, particularly in rapidly urbanizing regions, leveraging existing customer relationships and regulatory expertise.
For New Entrants and Emerging Players: Lead with innovative, multi-functional materials that combine fire resistance with properties like acoustic insulation or corrosion protection. Target underpenetrated segments such as high-rise residential retrofits in Australia, where updated fire safety codes create significant demand. A go-to-market angle focusing on integrated system solutions for electric vehicle battery thermal management offers a high-margin entry point.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized firestop system providers with robust intellectual property in non-halogenated formulations and strong certification portfolios. The long-term viability of this market is anchored in perpetual regulatory upgrades and continuous infrastructure expansion. A key signal to watch is the increase in government tenders for comprehensive fire safety upgrades in existing high-rise residential buildings.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Develop sustainable, non-halogenated retardants to meet evolving environmental mandates and corporate buyer demands. |
| Long-term Supply Agreement | Secure critical raw materials like ammonium polyphosphate amidst price volatility and supply chain disruptions. |
| Joint Venture | Partner with construction firms to offer integrated fire protection solutions, streamlining project delivery and compliance. |
| Capacity Expansion | Increase production of high-performance intumescent coatings for growing demand from data centers and high-rise structures. |
| Product Launch | Introduce lightweight ceramic blankets specifically engineered for electric vehicle battery thermal runaway prevention. |
Research Approach
Initial hypotheses were tested against primary input from building contractors, fire safety engineers, material specifiers, and regulatory compliance officers, and refined through iterative feedback. This primary research was complemented by extensive secondary data analysis, drawing from ASTM E119 reports, EN 13501 classifications, national building codes like Australia's BCA, and chemical industry reports. Bottom-up market sizing was triangulated with top-down validation to ensure data accuracy.
Variance decomposition informed the analytical framework across the analysis window, segmenting the market by product type, application, end-user, installation type, and regional regulatory intensity. Compound annual growth rates were derived from historical growth patterns and projected regulatory impacts, particularly from updated GB standards in China. Planned infrastructure project pipelines for data centers and high-rise buildings served as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside unforeseen global economic downturns, rapid shifts in environmental regulations for chemical compositions, or major geopolitical events affecting supply chains would require recalibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Polypropylene Foams Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Global Insulation Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Flexible Insulation Market